
 Spray Painting Machine Market | 2026-2036
Spray Painting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Painting Machine Market Analytics
REACH compliance is consolidating the cost-of-entry calculus for spray painting equipment suppliers across Europe. SAMES KREMLIN leverages its electrostatic expertise to anchor premium positioning in automotive finishing lines. Graco Inc. competes through extensive distribution control in North American industrial channels. Wagner Group GmbH specializes in compact airmix systems for European furniture manufacturers.
A spray painting machine is a precision fluid delivery system that atomizes paint, lacquer, or coating material through pressurized air, hydraulic force, or electrostatic charge, typically operating at pressures from 20 to 5,000 psi depending on the technology. Its primary purpose is to apply uniform, controlled layers of protective or decorative finishes across complex geometries in manufacturing environments. Electrostatic systems command the highest margin pools due to transfer efficiency requirements in automotive and aerospace applications. HVLP technology leads adoption among furniture and electronics manufacturers seeking compliance with tightening VOC regulations. Automated spray booth configurations represent the fastest-growing technology segment as industrial end users replace manual stations to reduce labor variability and material waste.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate maximum achievable control technology for surface coating operations, directly shaping equipment specifications in US manufacturing facilities. ECHA administers REACH restrictions on chromium and lead compounds in coatings, forcing European suppliers to validate compatible spray system materials and purge protocols. ISO 12944 provides corrosion protection standards that industrial buyers reference when specifying automated painting infrastructure for heavy equipment. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's industrial decarbonization timelines redirect capital toward energy-efficient spray booth and recovery systems.
Market Dynamics
Automotive OEMs are consolidating coating operations around electrostatic transfer efficiency mandates, forcing equipment suppliers to redesign atomization architectures around volatile organic compound recovery systems rather than standalone spray gun performance.
Growth Catalysts
- REACH Phase-Out Deadlines:ECHA restrictions on chromium-based primers are compelling automotive manufacturers in Germany and France to retrofit lines with HVLP-compatible recovery systems before compliance deadlines.
- China Dual Carbon Targets:Provincial energy efficiency mandates in Jiangsu and Guangdong are accelerating replacement of conventional compressed-air booths with heated air recirculation units that capture overspray for solvent recovery.
- Robotic Integration Density:Automotive tier-one suppliers are embedding six-axis painting robots with real-time film thickness sensors to eliminate manual touch-up labor in Stuttgart and Wolfsburg production clusters.
Market Restraints
- Specialized Pump Concentration:Precision ceramic pump manufacturing for high-pressure airmix systems concentrates among German and Swiss component suppliers, creating single-source vulnerability for North American equipment assemblers.
- Fluoropolymer Input Volatility:PTFE-lined hose and seal requirements for solvent-resistant electrostatic systems expose OEMs to fluorochemical price swings under EU F-Gas Regulation quota mechanisms.
- Transfer Efficiency Ceilings:Electrostatic systems face physical limits in Faraday cage penetration for complex automotive underbody geometries, constraining further efficiency gains without auxiliary air-assist nozzles.
Strategic Opportunities
- Indian Commercial Vehicle Expansion:Heavy truck and bus manufacturers near Pune and Chennai lack automated coating infrastructure, presenting first-mover openings for booth-integrated electrostatic suppliers willing to localize service networks.
- Battery Enclosure Coatings:Electric vehicle battery pack manufacturers require dielectric insulation finishes with precise film build control, creating specification demand for robotic bell applicators with closed-loop voltage feedback.
- EU Green Deal Capital Flows:Industrial decarbonization facility grants in Italy and Spain are subsidizing heat-recovery ventilation retrofits that bundle spray booth replacement with energy monitoring infrastructure.
Industry Challenges
- Multi-Standard Certification Burden:Suppliers must simultaneously validate equipment against ISO 12944 corrosion classes, ATEX explosion protection directives, and country-specific electrical codes, extending product launch timelines by eight to fourteen months.
- Legacy PLC Integration Friction:Automated spray lines in mature automotive plants operate on proprietary Siemens or Rockwell control architectures from the 1990s, forcing retrofit suppliers to develop costly protocol translation gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Painting Machine Market |
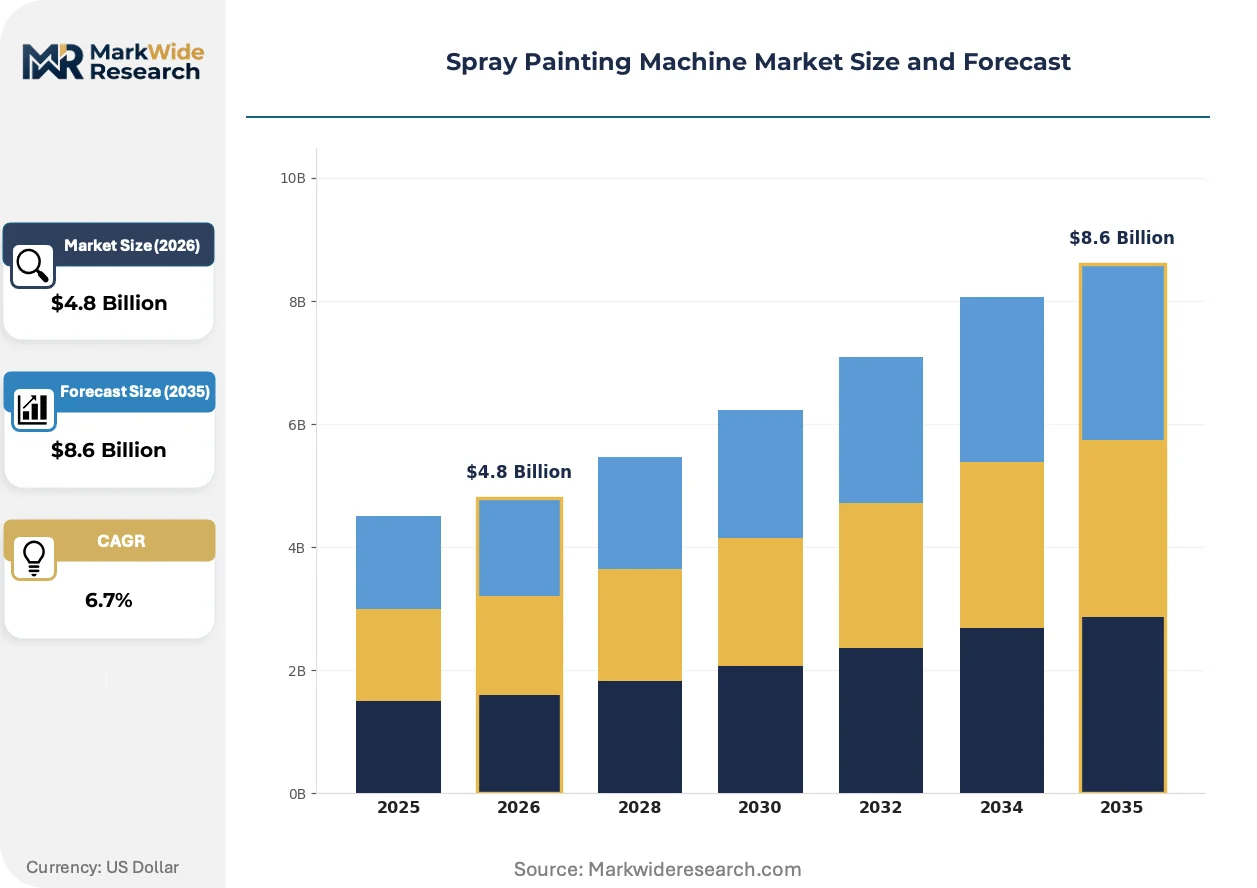
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airmix, Airless, Conventional, Electrostatic Application: Automotive, Furniture, Aerospace, Electronics End User: Manufacturers, Contractors, DIY Enthusiasts, Industrial Technology: HVLP, Spray Booth, Automated, Manual |
| Companies Covered | SAMES KREMLIN, ANEST IWATA Corporation, Wagner Group GmbH, EXEL Industries, SATA GmbH & Co. KG, Nordson Corporation, Kremlin Rexson S.A.S., Binks, Graco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Painting Machine Market Evolving Landscape
Coating application technology is converging around closed-loop material recovery and real-time process telemetry, compressing the distinction between spray equipment and environmental control systems.
Electrostatic rotary bell atomizers with integrated shaping air control are absorbing precision finishing volume previously served by conventional air-spray guns. Aerospace airframe manufacturers in Toulouse and Hamburg are specifying these systems for primer and clearcoat operations where transfer efficiency above eighty-five percent is mandatory. The technology is absorbing margin pool concentration toward high-voltage power supply and precision bearing suppliers rather than conventional fluid handling component vendors.
EPA National Emission Standards for Hazardous Air Pollutants are tightening maximum achievable control technology requirements for surface coating operations in automotive and wood furniture sectors. US manufacturing facilities must now demonstrate continuous parametric monitoring of spray booth capture velocity and carbon bed breakthrough rather than periodic stack testing. Metal fabrication shops in Ohio and Michigan are responding by consolidating dispersed manual spray operations into centralized automated booths with regenerative thermal oxidizers.
Indian automotive component manufacturers are unbundling after-sales service contracts from initial equipment purchases, forcing European and Japanese suppliers to establish captive spare parts depots in Mumbai and Delhi-NCR. Tier-two seating and interior trim suppliers now procure atomizers and pumps through domestic distributors rather than direct OEM relationships, compressing channel margins and accelerating localization requirements for technical documentation and training. This pattern is most visible among Maruti Suzuki and Hyundai supplier parks in Manesar and Sriperumbudur.
Spray Painting Machine Market Segmentation
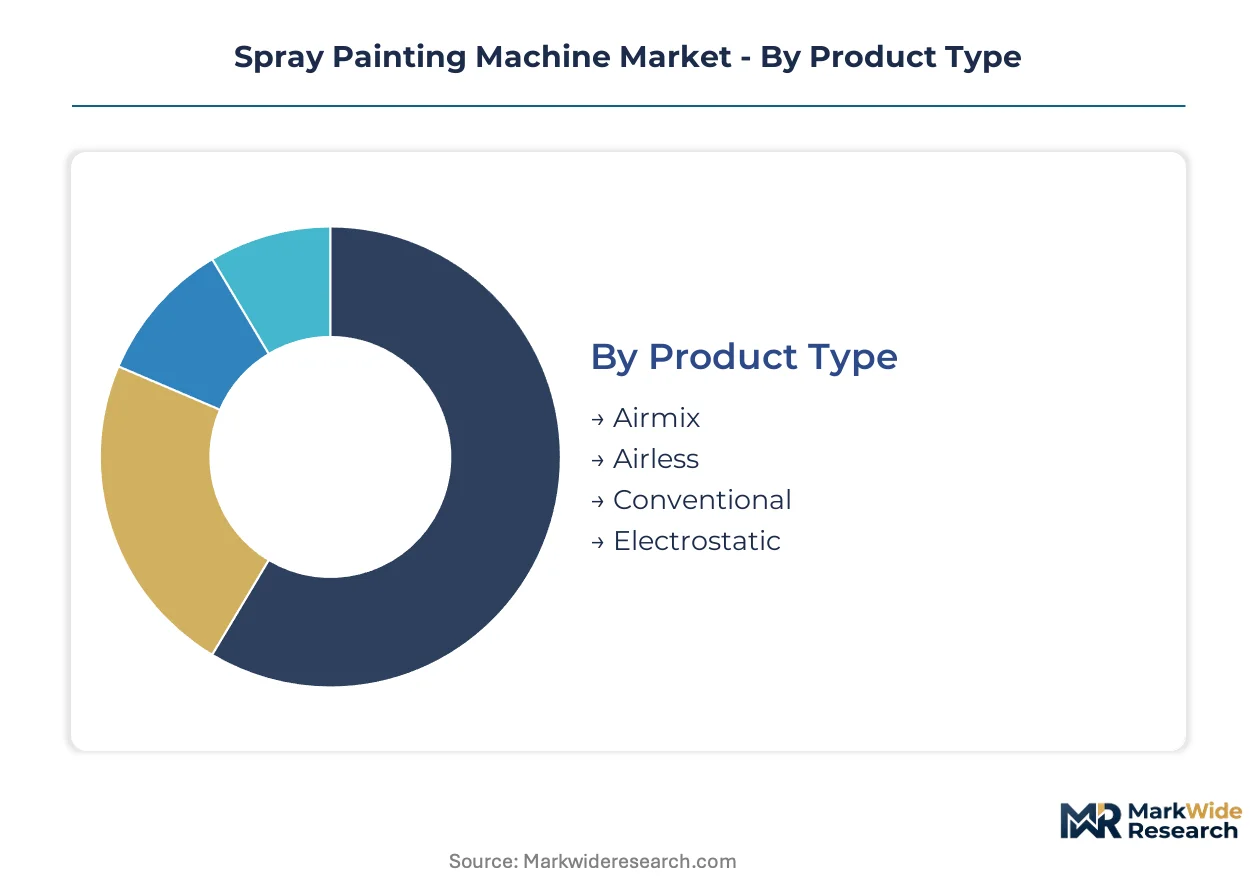
Spray painting equipment segments diverge sharply between precision automotive finishing and high-volume industrial coating. Transfer efficiency mandates and VOC recovery requirements reshape which technologies capture margin versus volume.
Product Type:
Electrostatic systems command premium positioning through transfer efficiency performance, while conventional equipment retains volume share in cost-sensitive applications.
- Electrostatic:High-voltage charging systems atomize paint at 60-120 kV, achieving 85-95% transfer efficiency through charged particle attraction to grounded substrates. German automotive OEMs in Stuttgart and Wolfsburg mandate electrostatic rotary bells for primer and clearcoat operations to meet EU VOC limits.
- Airless:Hydraulic pressure systems operating at 1,500-5,000 psi deliver high-build coatings without compressed air atomization. North American industrial metal fabricators specify airless pumps for protective coatings on structural steel where speed dominates finish quality.
- Airmix:Hybrid technology combining low-pressure air atomization with hydraulic fluid delivery. European furniture manufacturers favor airmix for lacquer application balancing efficiency with hand-finished aesthetics.
- Conventional:Compressed air spray guns at 20-60 psi remain standard for touch-up, custom finishing, and developing markets. Contractors in India's commercial vehicle aftermarket rely on conventional equipment for field repair and refurbishment.
Mature deployment sits with Conventional systems. Newer deployment is concentrated in Electrostatic configurations.
Application:
Automotive finishing drives specification intensity, while furniture and electronics applications prioritize compliance economics over performance extremes.
- Automotive:OEM coating lines require robotic electrostatic systems with real-time film thickness monitoring and solvent recovery integration. Paint shops in Germany, France, and China face binding VOC reduction timelines that mandate automated booth replacement.
- Aerospace:Airframe manufacturers specify precision bell applicators for primer and topcoat operations where mil-spec thickness tolerances are mandatory. Toulouse and Hamburg production clusters enforce 85% minimum transfer efficiency through electrostatic mandate.
- Furniture:Wood coating operations in Italy and Poland adopt HVLP and airmix systems to meet REACH solvent restrictions. Small-batch manufacturers prioritize equipment flexibility over line speed.
- Electronics:Consumer device housings require thin-film coating with precise edge coverage. Asian contract manufacturers specify compact spray booths with rapid color change capability for high-mix production.
Volume concentration centers on Automotive. Margin expansion is climbing the fastest in Aerospace applications.
End User:
Industrial manufacturers consolidate around automated infrastructure, while contractors and DIY segments fragment across price tiers.
- Industrial:Tier-one automotive suppliers and heavy equipment manufacturers operate integrated coating lines with robotic application and environmental controls. These buyers specify equipment through multi-year framework agreements bundling hardware, installation, and service.
- Manufacturers:Mid-size metal fabrication and consumer goods producers purchase standalone spray booths and manual guns. Procurement emphasizes capital efficiency and local service availability over technology leadership.
- Contractors:Mobile painting services for construction, marine, and infrastructure maintenance favor portable airless and conventional equipment. Rental channels and distributor financing shape purchase decisions.
- DIY Enthusiasts:Consumer-grade HVLP turbines and compressed air spray guns serve home improvement and hobbyist markets. E-commerce and big-box retail dominate this price-sensitive segment.
Technology investment concentrates with Industrial end users. Equipment refresh cycles are shortest among Manufacturers responding to compliance deadlines.
Technology:
HVLP and automated systems displace legacy compressed-air equipment as regulatory pressure intensifies across manufacturing geographies.
- Automated:Six-axis painting robots with integrated electrostatic applicators and vision-guided path planning eliminate manual touch-up labor. Automotive production clusters in Germany and China drive specification of closed-loop process control systems.
- HVLP:High-volume low-pressure technology operates at 10 psi or below at the air cap, reducing overspray and solvent emissions. US wood furniture manufacturers adopt HVLP to satisfy EPA National Emission Standards for Hazardous Air Pollutants.
- Spray Booth:Enclosed application environments with heated air recirculation, overspray filtration, and solvent recovery. China's provincial energy mandates in Jiangsu and Guangdong accelerate booth replacement with heat-recovery ventilation.
- Manual:Hand-held spray guns across conventional, HVLP, and airless configurations. Remains prevalent in custom finishing, aftermarket repair, and developing industrial infrastructure.
Installed base dominance sits with Manual technology. Steepest expansion trajectory belongs to Automated systems with robotic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Guangdong provincial energy efficiency mandates accelerate spray booth replacement with heat-recovery ventilation systems. Germany's automotive production clusters in Stuttgart and Wolfsburg drive precision electrostatic finishing requirements. India's commercial vehicle expansion near Pune and Chennai creates first-mover openings for automated coating infrastructure.
United States
Metal fabrication shops in Ohio and Michigan consolidate dispersed manual spray operations into centralized automated booths with regenerative thermal oxidizers. EPA National Emission Standards for Hazardous Air Pollutants mandate continuous parametric monitoring of spray booth capture velocity and carbon bed breakthrough. Wood furniture manufacturers in the Southeast adopt HVLP systems to satisfy compliance timelines.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate electrostatic rotary bells for primer and clearcoat operations to meet EU VOC limits. ECHA REACH restrictions on chromium-based primers compel manufacturers to retrofit lines with HVLP-compatible recovery systems. The country's automotive supplier parks drive specification intensity for robotic application systems.
China
Provincial dual carbon targets in Jiangsu and Guangdong accelerate replacement of conventional compressed-air booths with heated air recirculation units. MEE enforcement of industrial emission standards pushes coating operations toward solvent recovery integration. Yangtze River Delta manufacturing clusters specify closed-loop process control systems for automotive finishing.
India
Heavy truck and bus manufacturers near Pune and Chennai lack automated coating infrastructure, presenting openings for booth-integrated electrostatic suppliers. BIS certification requirements for industrial equipment extend product launch timelines for foreign entrants. Maruti Suzuki and Hyundai supplier parks in Manesar and Sriperumbudur drive localization demands for technical documentation and training.
France
Aerospace airframe manufacturers in Toulouse enforce minimum transfer efficiency mandates through electrostatic specification for primer and topcoat operations. EU F-Gas Regulation quota mechanisms expose coating operations to fluorochemical price volatility for PTFE-lined components. The country's furniture coating sector in regional manufacturing zones adopts airmix systems for REACH solvent compliance.
Spray Painting Machine Market Competitive Landscape
German and Swiss producers anchor the precision component tier; North American specialists hold distribution control in industrial channels. The vendor base organizes around three strategic archetypes: electrostatic technology leaders, high-pressure fluid handling specialists, and compact airmix system providers. Competitive positioning hardens through M&A consolidation of ceramic pump manufacturing capacity and strategic partnerships for robotic integration protocols.
Within the electrostatic technology tier, SAMES KREMLIN and Kremlin Rexson S.A.S. exemplify European precision positioning for automotive finishing lines. Graco Inc. anchors North American distribution density in industrial metal fabrication channels. Wagner Group GmbH occupies the compact airmix specialization for European furniture manufacturers. ANEST IWATA Corporation represents Japanese engineering presence in precision atomization components. These four entities collectively illustrate the geographic and technological segmentation governing competitive dynamics.
| Leading Market Players |
|---|
| SAMES KREMLIN |
| ANEST IWATA Corporation |
| Wagner Group GmbH |
| EXEL Industries |
| SATA GmbH & Co. KG |
| Nordson Corporation |
| Kremlin Rexson S.A.S. |
| Binks |
| Graco Inc. |
| Others |
Value Network & Pricing Analysis
PTFE resin price indices cascade through electrostatic system manufacturing, compressing margins for European OEMs dependent on fluoropolymer-lined components while amplifying pricing power for vertically integrated suppliers with captive polymer compounding operations.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent separate spot buyers from contract customers in precision ceramic pump procurement. Pricing stratifies across premium, standard, and economy tiers based on ATEX certification grade and bundled after-sales service intensity. Cost compression in manual spray gun segments is intensifying because Indian distributors are unbundling service contracts from hardware sales. DIY enthusiasts and small contractors exhibit highest price sensitivity, while automotive OEMs prioritize transfer efficiency performance over unit cost.
Supply Chain Analysis
Freight cost volatility from German and Swiss precision component suppliers to North American assembly plants has compressed landed cost predictability for high-pressure airmix systems. Manufacturing draws from ceramic pump fabrication in Germany, precision bearing production in Switzerland, and steel fabrication in China. Single-source vulnerability concentrates in ceramic plunger manufacturing for solvent-resistant pumps. Distribution runs through captive service networks for industrial end users and distributor financing channels for contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as equipment suppliers pursue backward integration into ceramic pump manufacturing to escape German and Swiss component pricing power.
For Market Incumbents: Acquire ceramic pump manufacturing capacity in Germany or Switzerland to secure supply continuity against fluoropolymer input volatility. Consolidate aftermarket service networks in India's automotive supplier parks before domestic distributors capture spare parts revenue streams. ECHA REACH phase-out deadlines threaten equipment refresh cycles, making certification investment the priority defensive lever.
For New Entrants and Emerging Players: Domestic distributors in India's commercial vehicle belt represent the most accessible channel partners for foreign equipment suppliers lacking captive service infrastructure. Target heavy truck manufacturers near Pune and Chennai with booth-integrated electrostatic systems bundled with localized technical training. White-space exists in battery enclosure coating specifications for electric vehicle producers requiring dielectric insulation finishes.
For Investors and Strategic Acquirers: The window for entry favors electrostatic technology specialists with automotive OEM validation and robotic integration protocols. Long-term viability rests on capturing margin pools in automated spray booth configurations rather than manual equipment commoditization. Watch for provincial energy mandate enforcement in China's Jiangsu and Guangdong as the inflection signal for heat-recovery ventilation replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Pump Manufacturing | Captive supply of precision components reduces exposure to German and Swiss single-source pricing power. |
| Robotic Integration Protocol Partnership | Six-axis painting robot compatibility opens automotive OEM specification pathways in Stuttgart and Wolfsburg clusters. |
| Localized Service Network Establishment | Spare parts depots in Mumbai and Delhi-NCR satisfy Maruti Suzuki supplier park localization demands. |
| Heat-Recovery Ventilation Retrofit Bundling | EU Green Deal facility grants in Italy and Spain subsidize spray booth replacement with energy monitoring infrastructure. |
| HVLP-Compatible Recovery System Development | ECHA chromium-based primer restrictions compel automotive manufacturers in Germany and France to retrofit coating lines. |
Research Methodology
Trade databases, automotive production registries, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews across plant engineers at Tier 1 automotive suppliers, procurement leads at industrial coating operations, aftermarket service heads at distributor networks, and technical R&D directors at equipment manufacturers. Bottom-up and top-down triangulation validated segment sizing against customs data and OEM capital expenditure disclosures.
Bottom-up modeling aggregated equipment unit shipments by technology type and application, while top-down analysis cross-checked aggregate market value against industrial automation investment flows. Segmentation dimensions included product type, application sector, end-user category, and technology configuration across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles and regulatory compliance deadline clustering, with specific inputs from EPA NESHAP enforcement timelines and EU F-Gas Regulation quota mechanisms.
Caveats apply where provincial energy mandate enforcement in China or REACH restriction acceleration in Europe could materially shift the outlook for booth replacement demand. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cutting Tool Inserts Market
Tools
Automatic Lathe Machines Market
Tools
Machine Bench Vices Market
Tools
Auger Drill Bits Market
Tools
US Power Tools Market
Tools
Digital Levels Market
Tools
Drywall Tool Market
Tools
Global Sandblasting Media Market
Tools
Concrete Saw Market
Tools
Yard Scraper Market
Tools
Lathe Machines Market
Tools
Surface Levelling Equipment Market
Tools
Sanding Machine Market
Tools
Industrial Ladder Market
Tools
Drill Presses Market
Tools
Woodworking Router Bits Market