
 Global Cutting Discs Market | 2026-2036
Global Cutting Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cutting Discs Market Analysis
Industrial distribution through specialized abrasives distributors and direct OEM supply contracts is tilting toward consolidated procurement platforms. Saint-Gobain Abrasives leverages its vertically integrated ceramic grain production to secure long-term supply agreements with European metalworking chains. Tyrolit Group anchors its position through dense service-center networks across Central Europe and selective Asian markets. Bosch Power Tools competes by bundling cutting discs with its cordless grinder ecosystem, locking in replacement demand through battery-platform compatibility.
Cutting discs are thin, reinforced circular tools manufactured from bonded abrasive grains or diamond segments, typically ranging from 0.8 mm to 3.2 mm in thickness, designed for rotary severing of metals, masonry, and composite materials. Resin-bond aluminum oxide wheels dominate general metal fabrication due to their cost-efficiency in dry cutting operations, while diamond cutting discs command premium positioning in stone and concrete applications where extended blade life offsets higher unit pricing. Metal fabrication and construction applications absorb the majority of volume, though automotive trimming and electrical conduit installation represent faster-growing niches where precision thin-wheel designs reduce material waste and secondary finishing.
OSHA enforces permissible exposure limits on respirable crystalline silica generated during abrasive cutting, compelling manufacturers to reformulate bonded discs with engineered vacuum-brazed or sintered diamond alternatives. REACH restricts specific phenolic resin precursors used in conventional bonding matrices, pushing European producers toward hybrid ceramic-polymer binders that maintain thermal stability at high peripheral speeds. ECHA's ongoing substance evaluations will likely extend restriction lists to additional curing agents, so stakeholders must monitor regulatory pre-registrations and align R&D roadmaps with anticipated compliance deadlines.
Market Dynamics
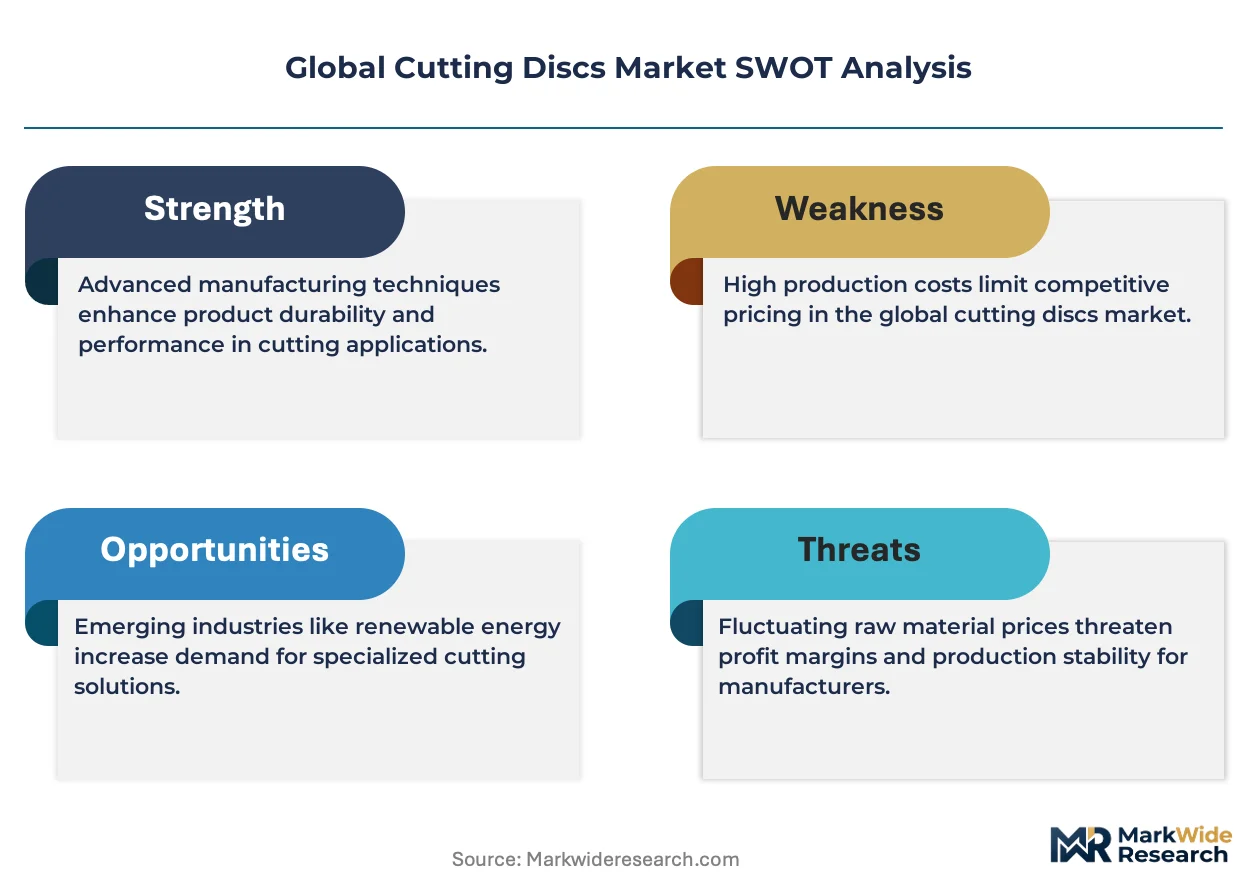
Thin-wheel abrasive discs are displacing conventional thick-cut wheels in precision metalworking, as fabricators prioritize kerf reduction and secondary-finishing elimination over raw cutting speed.
Growth Catalysts
- OSHA silica exposure limits:US metal fabrication shops face mandatory respirable crystalline silica controls, accelerating vacuum-brazed diamond disc adoption in dry-cutting environments.
- Automotive lightweighting:OEMs in China's Yangtze River Delta specify ultra-thin resin-bond wheels for aluminum and high-strength steel trimming, cutting material waste per vehicle.
- Shipbuilding clusters:Guangzhou and Shanghai yards drive bulk procurement of large-diameter diamond cutting wheels for plate severing and structural prep.
Market Restraints
- Phenolic resin precursor costs:REACH-restricted curing agents force European manufacturers toward hybrid ceramic-polymer binders with 15-25% raw material cost premiums.
- Abrasive grain supply concentration:Fused alumina and silicon carbide production concentrates in Henan province and Guizhou prefecture, exposing buyers to single-source disruption risk.
- Diamond segment technical ceiling:Sintered metal-bond discs face peripheral speed limitations above 80 m/s, capping throughput in high-volume automated cutting lines.
Strategic Opportunities
- India's PLI scheme for manufacturing:Metal fabrication incentives in Gujarat and Tamil Nadu create first-mover advantage for bonded abrasive producers establishing local compounding facilities.
- Electrical conduit installation:Thin-wheel precision cutting penetrates building trades where traditional hacksaw methods still dominate, particularly in Southeast Asian construction.
- EU Green Deal procurement mandates:Public infrastructure projects increasingly specify low-emission abrasive formulations, rewarding producers with verified carbon footprint data.
Industry Challenges
- Ceramic grain formulation expertise:Sol-gel and seeded-gel alumina production requires specialized pyrometallurgical talent scarce outside Saint-Gobain's proprietary training pipelines.
- REACH pre-registration alignment:ECHA's substance evaluation timeline compresses R&D-to-compliance windows, forcing smaller producers to outsource regulatory affairs or exit European distribution.
- Legacy equipment retrofit costs:Automated cutting cells with fixed spindle speeds cannot exploit next-generation thin-wheel performance without capital-intensive controller and safety-guard upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cutting Discs Market |
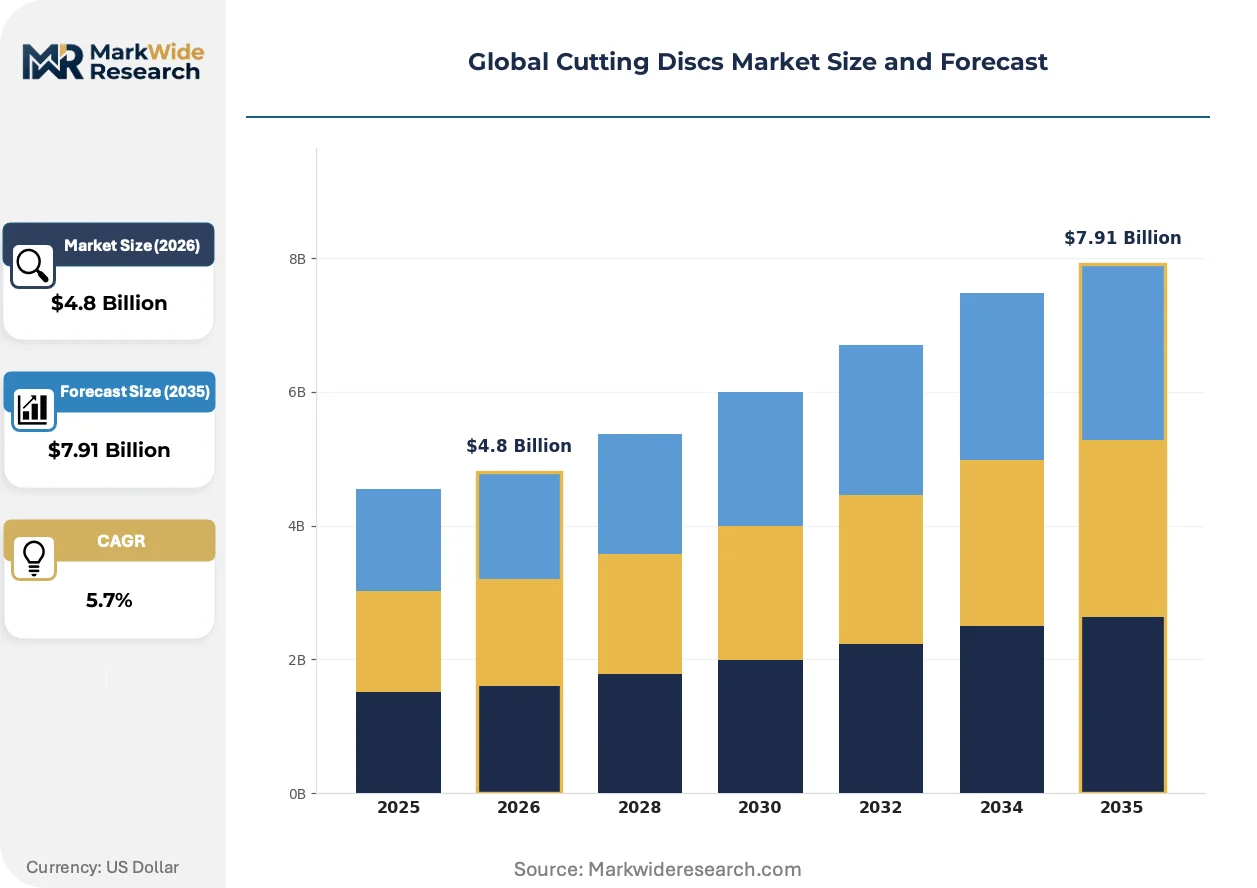
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Cutting, Stone Cutting, Diamond Cutting, Abrasive Cutting Material: Aluminum Oxide, Silicon Carbide, Diamond, Resin Bond Application: Construction, Metal Fabrication, Automotive, Electrical End User: Contractors, Manufacturers, DIY Enthusiasts, Service Providers |
| Companies Covered | 3M Company, Saint-Gobain Abrasives, Tyrolit Group, Pferd Inc., Bosch Power Tools, Klingspor AG, DEWALT, Weiler Abrasives, Rhodius Schleifwerkzeuge GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cutting Discs Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to redefine abrasive bonding systems, while procurement centralization reshapes how cutting discs reach end-users.
Engineered ceramic grains with controlled microstructure are rendering obsolete conventional fused alumina in high-performance metal cutting. German automotive stamping plants now specify sol-gel alumina thin wheels exclusively for stainless steel and exotic alloy work. The technology is rendering obsolete price-based supplier selection in premium metal fabrication segments.
REACH chemical restrictions on phenolic resin precursors are forcing bonded abrasive reformulation across European production. Manufacturers hybridize ceramic-polymer matrices to maintain thermal stability at 100+ m/s peripheral speeds. German and Austrian metalworking distributors now stock dual-certified product lines pending ECHA's anticipated extension of restriction lists to additional curing agents.
Consolidated procurement platforms are displacing traditional abrasives distributor relationships in large metal fabrication chains. Direct OEM supply contracts with embedded inventory management now dominate volume purchasing for automotive and shipbuilding accounts. This concentration is most visible in China's Pearl River Delta, where Guangzhou-based procurement consortia negotiate annual framework agreements covering bonded and superabrasive cutting tools.
Global Cutting Discs Market Segmentation
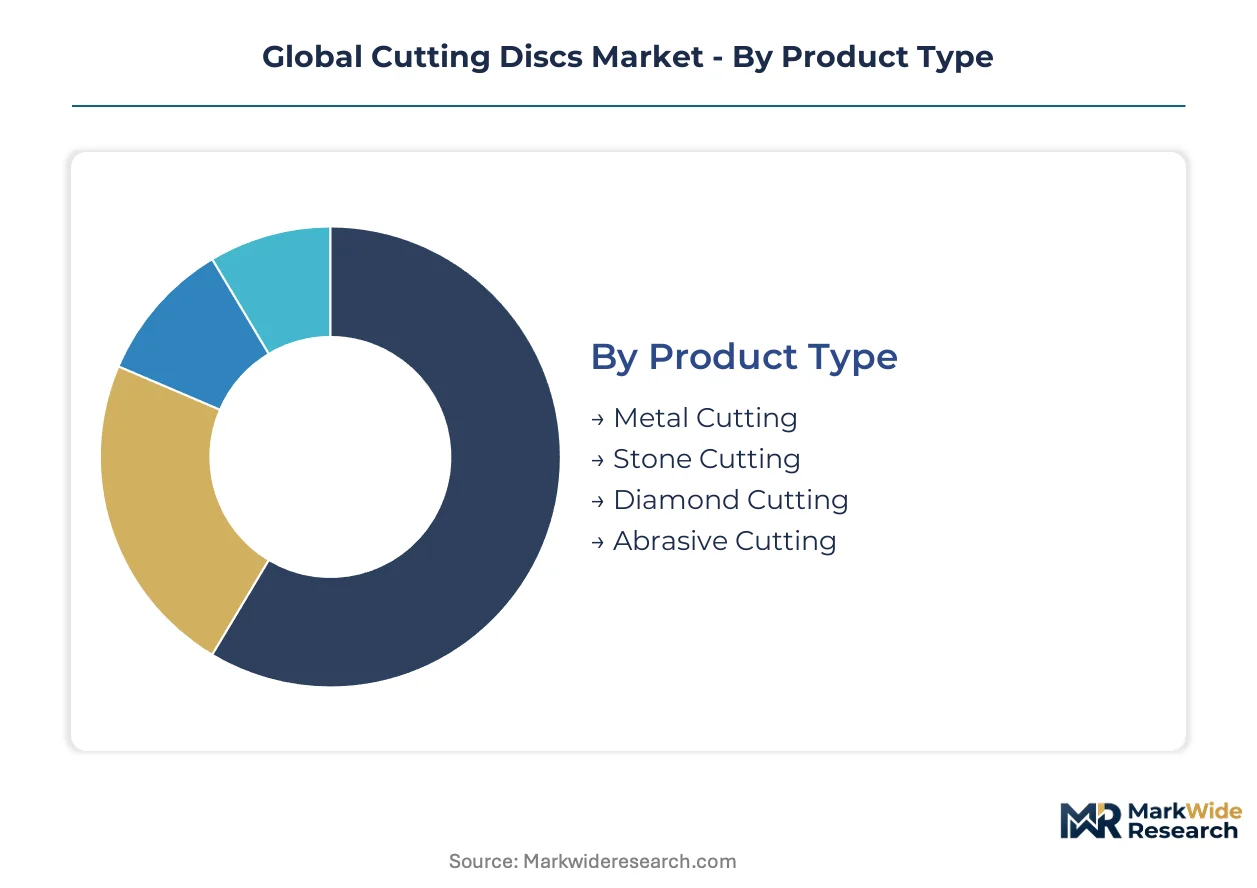
Cutting disc procurement patterns diverge sharply across technical specifications and end-use contexts. Cycle time, inventory turnover, and replacement frequency vary by an order of magnitude between commodity metalworking consumables and precision diamond tools for automated production lines.
Product Type:
Metal cutting discs turn over fastest in high-volume fabrication environments, while diamond cutting wheels command extended replacement cycles measured in months rather than shifts.
- Metal Cutting:Thin-wheel resin-bond designs dominate steel severing in German and US fabrication shops. Demand concentrates around OSHA-compliant silica-reduction formulations as shops retrofit dry-cutting stations.
- Stone Cutting:Sintered diamond segments with continuous rims command premium positioning in concrete and masonry applications. Guangzhou and Shanghai shipyards drive bulk procurement of large-diameter wheels for structural plate prep.
- Diamond Cutting:Vacuum-brazed and laser-welded variants serve precision applications where extended blade life offsets higher unit cost.
- Abrasive Cutting:General-purpose aluminum oxide wheels serve intermittent-use segments and price-sensitive procurement channels.
Metal cutting dominates installed base. Diamond cutting is where expansion concentrates.
Material:
Raw material cost tiers stratify sharply, from commodity fused alumina to engineered ceramic grains with proprietary sol-gel microstructures.
- Aluminum Oxide:Fused and brown alumina grades supply cost-efficient dry cutting in general metal fabrication. Henan province concentration exposes buyers to single-source disruption risk.
- Silicon Carbide:Harder, more brittle grains suit non-ferrous metals and stone cutting where friability accelerates self-sharpening.
- Diamond:Synthetic monocrystalline and polycrystalline segments command superabrasive pricing tiers in precision automated lines.
- Resin Bond:Phenolic and hybrid ceramic-polymer matrices face REACH-driven reformulation costs across European production.
Aluminum oxide dominates volume throughput. Diamond is climbing the fastest on value expansion.
Application:
Construction sites burn through consumables at rates fabrication floors cannot match, while automotive trimming demands precision tolerances that reject commodity specifications.
- Construction:Masonry and concrete cutting absorb high-volume abrasive disc flows through contractor supply chains. OSHA silica rules accelerate vacuum-brazed diamond adoption in US infrastructure work.
- Metal Fabrication:Precision thin-wheel specifications now displace conventional thick-cut designs in German automotive stamping plants.
- Automotive:Yangtze River Delta OEMs specify ultra-thin resin-bond wheels for aluminum and high-strength steel trimming to cut per-vehicle material waste.
- Electrical:Conduit installation represents underpenetrated replacement opportunity where hacksaw methods still dominate Southeast Asian building trades.
Construction commands the largest replacement volume. Automotive is gaining share fastest on lightweighting intensity.
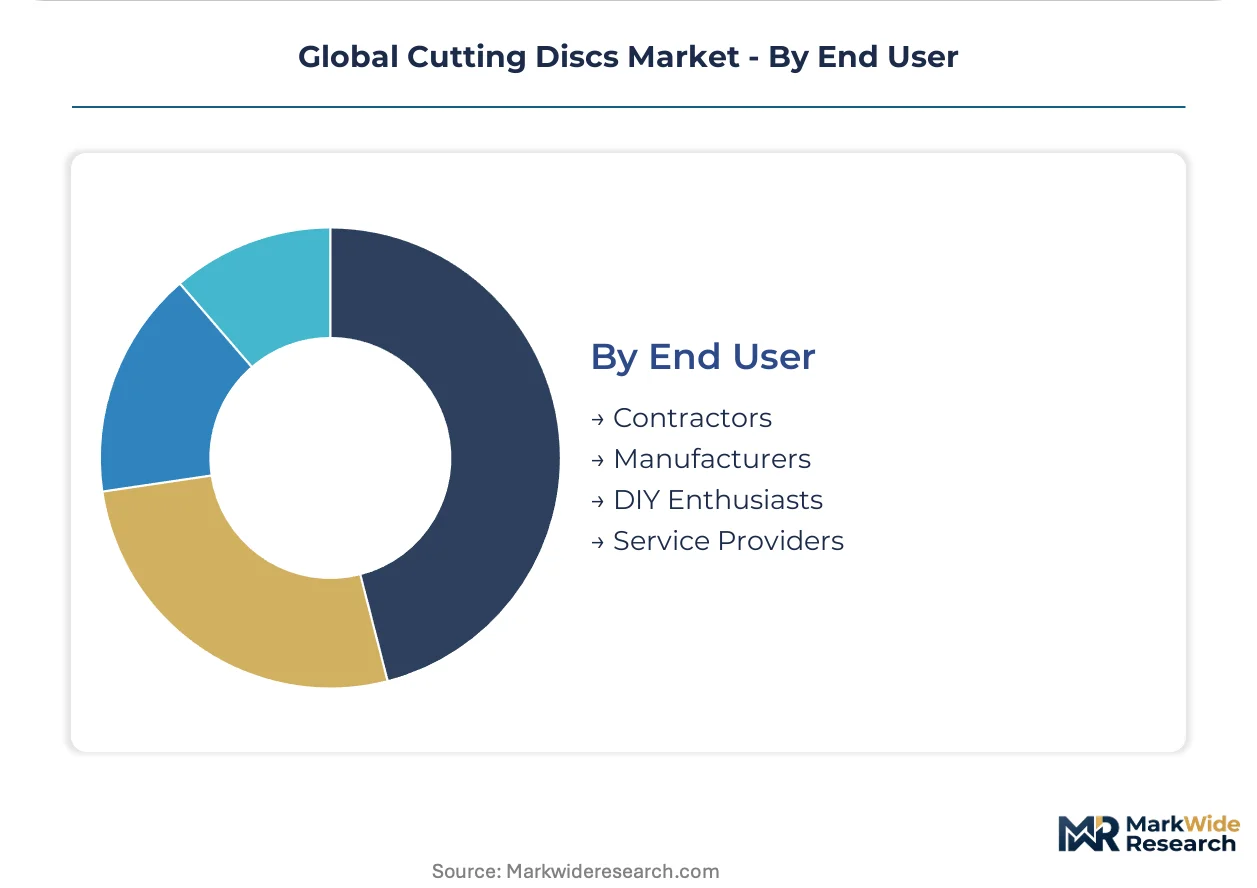
End User:
Procurement sophistication varies from consolidated OEM framework agreements to fragmented spot purchasing through retail hardware channels.
- Contractors:Price-sensitive bulk procurement through distributor relationships, with growing specification of silica-compliant formulations on US public projects.
- Manufacturers:Direct supply contracts with embedded inventory management dominate automotive and shipbuilding accounts in China's Pearl River Delta.
- DIY Enthusiasts:Cordless grinder ecosystem bundling locks in replacement demand through battery-platform compatibility.
- Service Providers:Mobile maintenance and repair operations prioritize portability and universal arbor compatibility over performance optimization.
Manufacturers anchor premium segment value. Contractors represent the steepest volume trajectory on infrastructure spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command 15-25% price premiums for REACH-compliant thin-wheel formulations, while Chinese producers in Henan province undercut on raw alumina costs by leveraging captive fused grain capacity.
United States
OSHA silica exposure limits accelerate vacuum-brazed diamond disc adoption in dry-cutting metal fabrication shops across the Midwest and Southeast. Infrastructure spending through the Inflation Reduction Act channels procurement toward silica-compliant abrasives on federal construction projects. Houston and Pittsburgh metalworking clusters drive bulk replacement demand for thin-wheel resin-bond designs in precision steel severing.
Germany
Automotive stamping plants in Baden-Württemberg specify sol-gel alumina thin wheels exclusively for stainless steel and exotic alloy trimming operations. REACH restrictions on phenolic resin precursors force manufacturers toward hybrid ceramic-polymer binders with certified thermal stability. Stuttgart and Wolfsburg industrial corridors anchor premium-grade procurement through direct OEM supply contracts.
China
Shipbuilding yards in Guangzhou and Shanghai drive bulk purchasing of large-diameter diamond cutting wheels for structural plate preparation. MIIT industrial upgrading guidelines favor domestic superabrasive producers with verified carbon footprint data for state-owned enterprise tenders. Yangtze River Delta automotive OEMs specify ultra-thin resin-bond wheels for aluminum and high-strength steel trimming to reduce per-vehicle material waste.
India
PLI scheme incentives for metal fabrication in Gujarat and Tamil Nadu create first-mover positioning for bonded abrasive producers establishing local compounding facilities. BIS certification requirements for industrial abrasives tighten quality thresholds on imported resin-bond formulations. Mumbai-Pune and Chennai-Bengaluru manufacturing belts concentrate demand from automotive component suppliers and electrical conduit installers.
Japan
METI carbon neutrality roadmaps push abrasive producers toward low-emission bonding matrices for public infrastructure procurement. JIS standards for industrial cutting tools enforce dimensional tolerances that favor precision thin-wheel designs over commodity thick-cut alternatives. Nagoya and Osaka industrial zones maintain premium positioning through embedded inventory management contracts with automated cutting line operators.
Global Cutting Discs Market Vendor Landscape
Vertically integrated multinationals and specialized regional fabricators split the market into distinct capability tiers. Saint-Gobain Abrasives and Tyrolit Group anchor premium positioning through captive ceramic grain production and dense service-center networks. Three archetypes dominate: integrated superabrasive producers with upstream mineral control, cordless tool ecosystem bundlers locking in replacement demand, and regional specialists serving price-sensitive contractor channels. Competitive moves concentrate on backward integration into engineered grain production and geographic expansion through distributor acquisition.
Among integrated abrasive producers, Saint-Gobain Abrasives and Tyrolit Group exemplify the upstream-control archetype through proprietary sol-gel alumina capabilities. Bosch Power Tools occupies a distinct position as an ecosystem bundler leveraging cordless grinder platforms to capture replacement disc demand. Klingspor AG and Rhodius Schleifwerkzeuge GmbH represent the mid-tier specialist model with concentrated regional footprints.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain Abrasives |
| Tyrolit Group |
| Pferd Inc. |
| Bosch Power Tools |
| Klingspor AG |
| DEWALT |
| Weiler Abrasives |
| Rhodius Schleifwerkzeuge GmbH |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese fused alumina smelting is compressing raw material benchmarks while REACH-driven reformulation costs in Europe widen the premium spread for compliant thin-wheel formulations. This divergence pressures margin structures across procurement tiers.
Pricing Analysis
Configured-to-order pricing for sol-gel alumina thin wheels commands 40-60% premiums over standard fused alumina commodity discs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal stability ratings. Cost compression in economy-tier resin-bond wheels is intensifying because Henan province producers are flooding spot markets with excess fused grain capacity. Contractor channels show highest price sensitivity, while German automotive OEMs demonstrate lowest sensitivity due to embedded inventory management contracts.
Supply Chain Analysis
Extended payment terms from Guangzhou shipbuilding consortia are forcing mid-tier distributors to adopt supply-chain finance facilities, squeezing working capital for smaller bonded abrasive fabricators. Raw material sourcing draws from Henan province for fused alumina, Guizhou prefecture for silicon carbide, and synthetic diamond production hubs in India and China. Single-source vulnerability concentrates in ceramic grain pyrometallurgy, where proprietary sol-gel expertise remains captive to Saint-Gobain's training pipelines. Distribution runs through consolidated procurement platforms in China's Pearl River Delta and specialized abrasives distributors across Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against waterjet and laser cutting technologies that threaten precision metalworking segments. Incumbents must differentiate on kerf quality and secondary-finishing elimination to maintain abrasive relevance.
For Market Incumbents: Insulate premium positioning through captive sol-gel alumina production and REACH-compliant hybrid binder certification. Secure long-term supply agreements with Yangtze River Delta automotive OEMs before waterjet adoption accelerates in aluminum trimming applications. Deepen backward integration into engineered grain production to offset phenolic resin precursor cost volatility.
For New Entrants and Emerging Players: Southeast Asian electrical conduit installation offers underpenetrated white-space where hacksaw methods still dominate building trades. Target India's PLI scheme incentives in Gujarat and Tamil Nadu for local compounding facilities ahead of BIS certification tightening. Pursue cordless grinder ecosystem bundling with emerging power tool brands to lock in replacement demand through battery-platform compatibility.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated abrasive producers with OEM embedded inventory management contracts. Long-term viability over a 5-10 year window favors targets with proven ceramic grain formulation expertise and dual REACH-OSHA certification pipelines. Monitor ECHA substance evaluation timelines as inflection indicators for regulatory-driven consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grain Production | Captive sol-gel alumina supply secures premium thin-wheel margins against Henan commodity volatility. |
| REACH-Compliant Binder Reformulation | Hybrid ceramic-polymer matrices maintain thermal stability above 100 m/s for European automotive OEMs. |
| Consolidated Procurement Platform Partnership | Direct supply contracts with Guangzhou shipbuilding consortia displace traditional distributor relationships. |
| Cordless Ecosystem Bundling | Battery-platform compatibility locks replacement demand through grinder-disc pairing in DIY channels. |
| India PLI Scheme Localization | Local compounding facilities in Gujarat and Tamil Nadu preempt BIS certification barriers on imports. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at German automotive stamping facilities, procurement leads at Chinese shipbuilding yards, distribution channel partners across Central Europe, and technical R&D directors at bonded abrasive producers; and secondary validation through customs trade data, SEC filings from listed abrasives manufacturers, ECHA substance evaluation pre-registrations, and OSHA silica exposure compliance databases. Bottom-up demand modeling from end-use consumption patterns was triangulated against top-down supply capacity assessments.
Forecast inputs considered product type segmentation across metal cutting, stone cutting, diamond cutting, and abrasive cutting categories; material grade tiers from commodity fused alumina to engineered sol-gel ceramic grains; application intensity across construction, metal fabrication, automotive trimming, and electrical installation; and end-user procurement sophistication from consolidated OEM frameworks to fragmented contractor spot purchasing. CAGRs were derived through regression analysis against industrial production indices and infrastructure spending trajectories, incorporating REACH regulatory timeline assumptions and MIIT industrial upgrading guidelines as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned enterprises or accelerated waterjet substitution in precision metalworking would shift outcomes. Macroeconomic deviation in industrial output, regulatory extension of REACH restriction lists, or breakthrough advances in laser cutting economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Automated Plasma Beveller Market
Tools
Drain Cleaning Equipment Market
Tools
Edge Banders Market
Tools
Woodworking CNC Tools Market
Tools
Pneumatic Tools Market
Tools
Stationary Wood Planer Market
Tools
Laser Engraving Machine Market
Tools
Surface Planer Market
Tools
Allen Key Market
Tools
Global Metal Forming Machine Tools Market
Tools
Floor Pads Market
Tools
Indexable Tool Inserts Market
Tools
Edge Bending Machine Market
Tools
Foam Cutting Machine Market
Tools
Telescopic Tool Boxes Market
Tools
Global Flange Fasteners Market