
 Thaumatin Market | 2026-2036
Thaumatin Market Size, Share, and Industry Trends Forecast 2026-2036
Thaumatin Market Analysis
Clean-label extraction technology is fragmenting the competitive landscape for high-intensity sweeteners, forcing suppliers to rethink purification and scale economics. Ingredion Incorporated leverages its global ingredient platform to sustain thaumatin distribution across multiple continents. PureCircle Limited anchors its position through specialized botanical extraction capabilities. Ajinomoto Co., Inc. differentiates via integrated fermentation and natural product expertise.
Thaumatin is a protein sweetener extracted from the katemfe fruit (Thaumatococcus daniellii), consisting of five closely related proteins with thaumatin I and II dominating commercial production; it delivers roughly 2,000 times the sweetness intensity of sucrose at threshold concentrations while contributing zero calories and no glycemic impact. Powder formulations dominate current manufacturing throughput due to superior stability and extended shelf life, though liquid concentrates are capturing faster growth in ready-to-drink beverage applications. The bakery segment remains comparatively mature with slower volume expansion, while confectionery represents a concentrated margin pool where premium positioning commands stronger pricing power.
The FDA governs thaumatin's use as a flavor modifier under GRAS designation, while the EMA and EFSA jointly oversee novel food approvals and safety assessments within Europe, creating divergent compliance pathways that shape market access timelines. FSSAI in India maintains separate clearance requirements for protein-based sweeteners, adding regulatory complexity for multinational suppliers. Stakeholders must monitor evolving novel food frameworks and extraction sustainability standards to anticipate which geographies will open or restrict procurement channels.
Market Dynamics
The F-Gas Regulation and evolving EU novel food standards are compressing extraction technology timelines, forcing suppliers to validate low-temperature purification methods before capacity expansion approvals.
Growth Catalysts
- Clean-label beverage reformulation:Formulators in Germany and France are replacing synthetic sweeteners with thaumatin in carbonated and functional drinks, driven by retailer sustainability scorecards.
- FSSAI clearance pathway:India's regulatory framework for protein-based sweeteners is opening procurement channels for multinational ingredient suppliers targeting processed food manufacturers.
- Bioprocess innovation:Precision fermentation methods for thaumatin analogs are reducing botanical extraction dependency while maintaining GRAS-equivalent safety profiles.
Market Restraints
- Katemfe supply concentration:Wild harvesting in Ghana and Ivory Coast creates volume volatility and quality inconsistency for thaumatin I and II isolation.
- Stevia price competition:Reb A and steviol glycoside blends from large-scale fermentation are undercutting thaumatin in mid-tier confectionery applications.
- EMA novel food timelines:Extended safety assessment durations for new extraction variants delay market entry by 18-24 months versus GRAS self-affirmation in the US.
Strategic Opportunities
- Japanese functional foods:METI's Foods with Function Claims system rewards natural sweeteners with documented metabolic benefits, creating premium positioning for thaumatin in aging-population products.
- Pharmaceutical masking:Pediatric and geriatric drug formulations are adopting thaumatin for bitter API taste suppression where sugar alcohols fail.
- Cold-chain liquid concentrates:Aseptic filling technology is enabling ready-to-drink beverage manufacturers to switch from powder reconstitution to direct thaumatin liquid dosing.
Industry Challenges
- Protein stability expertise:Formulation chemists with thaumatin pH and thermal degradation knowledge remain scarce relative to carbohydrate sweetener specialists.
- Dual certification burden:Suppliers seeking EU and US market access must simultaneously satisfy EFSA novel food requirements and FDA GRAS substantiation, doubling documentation costs.
- Batch-to-batch sweetness variance:Natural protein heterogeneity complicates automated dosing systems in high-speed bottling lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thaumatin Market |
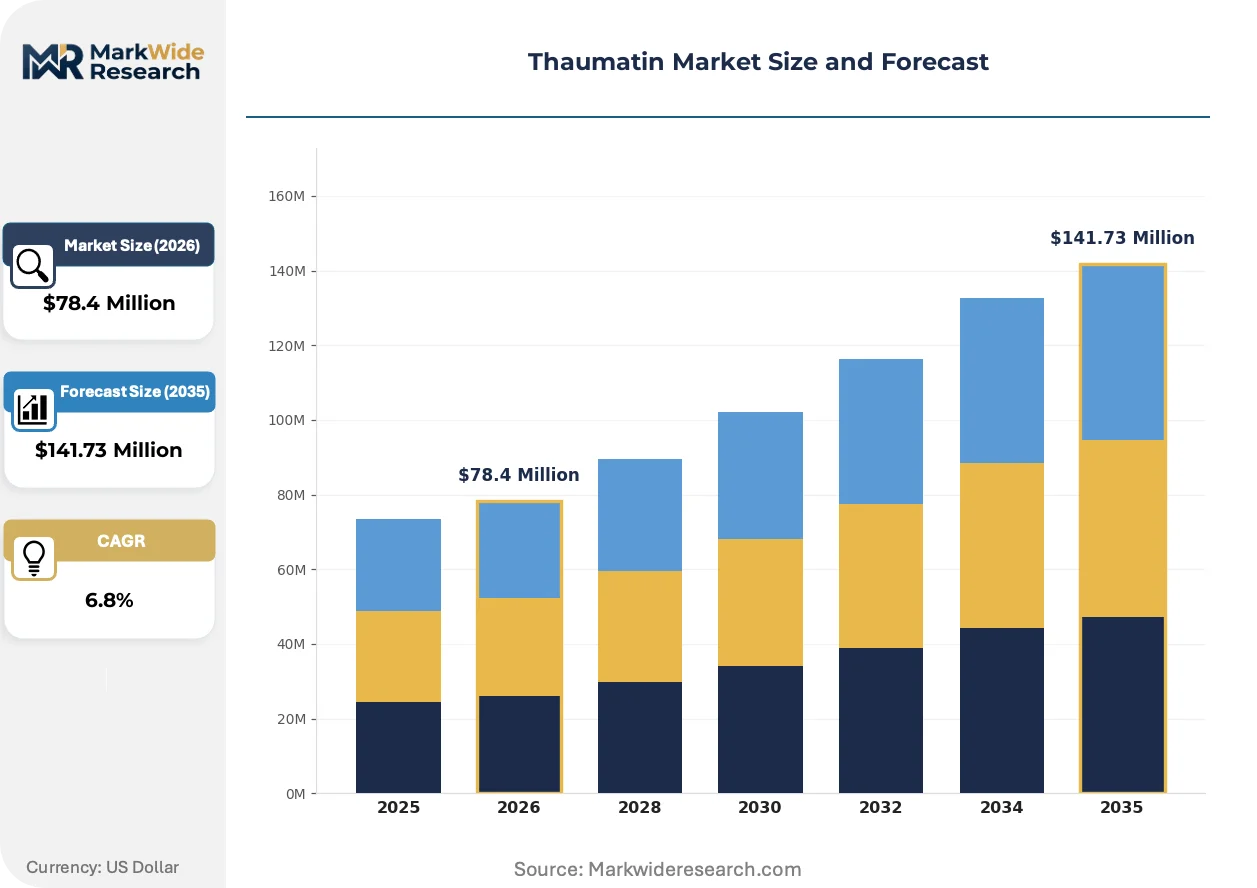
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granular, Concentrate Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Companies, Ingredient Suppliers, Retailers Distribution Channel: Online, Offline, Wholesale, Direct Sales |
| Companies Covered | Ingredion Incorporated, PureCircle Limited, Ajinomoto Co., Inc., Symrise AG, Firmenich S.A., Tate & Lyle PLC, Beneo GmbH, Naturex S.A., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thaumatin Market Emerging Trajectories
Extraction technology convergence with bioprocessing is collapsing traditional supply economics, while regulatory divergence between major markets is fragmenting approval strategies. Formulation science advances are unlocking applications beyond sweetness modulation.
Membrane filtration and chromatographic purification systems are replacing solvent-based extraction in thaumatin production facilities. Beverage manufacturers in Germany and the Netherlands are qualifying these outputs for organic-certified product lines. The shift is rendering obsolete conventional hexane extraction infrastructure and associated carbon-intensive supply chains.
REACH registration requirements for novel extraction solvents are tightening substance authorization timelines across EU member states. Thaumatin processors must now submit full toxicological dossiers for auxiliary chemicals used in purification. Small-scale Ghanaian suppliers without regulatory affairs capabilities are losing access to European procurement channels.
Direct supplier relationships are displacing traditional ingredient distributor networks in thaumatin procurement. Large confectionery manufacturers in Switzerland and Belgium are establishing captive sourcing agreements with West African extraction facilities. This pattern is most pronounced in premium chocolate and medicated lozenge segments where traceability documentation commands price premiums.
Thaumatin Market Segmentation
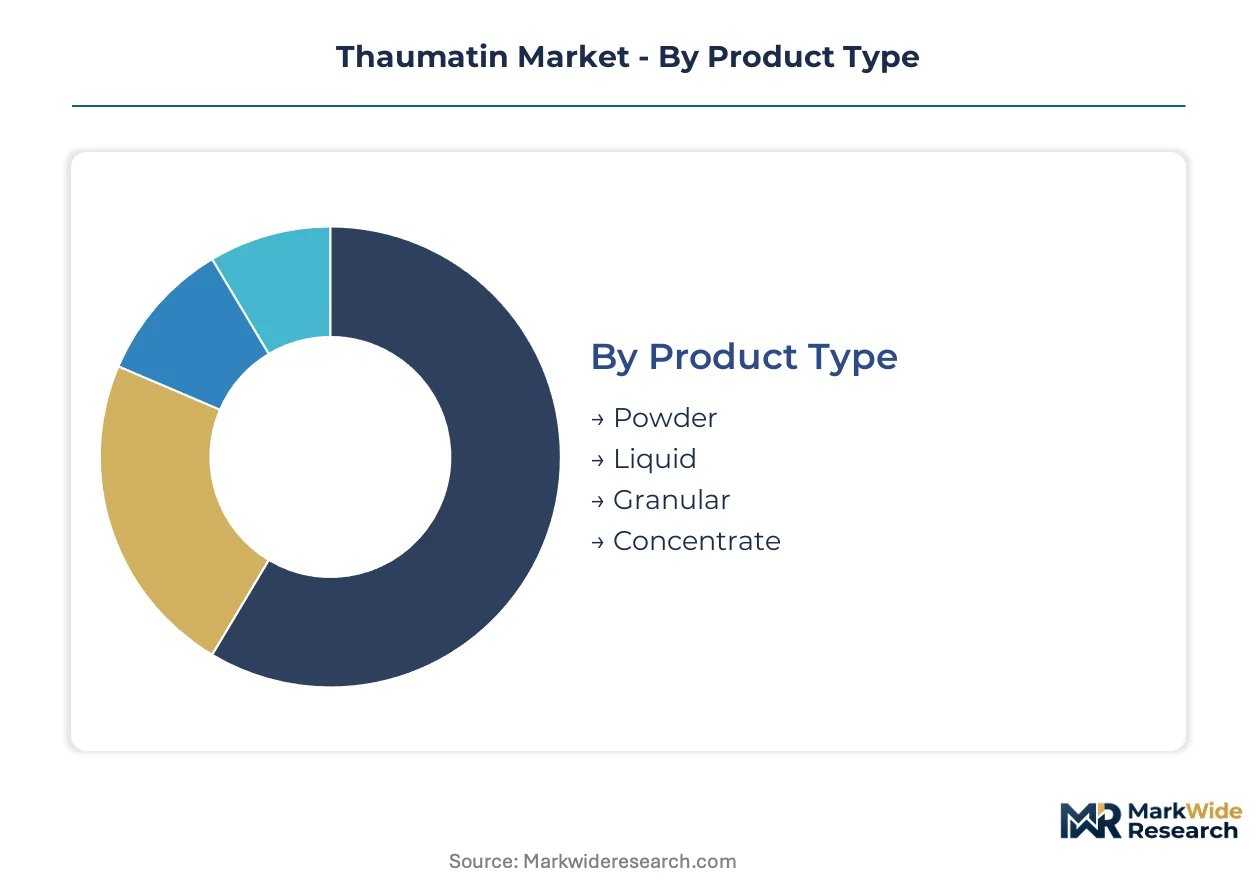
Thaumatin's protein-based chemistry creates divergent shelf-life and handling requirements across physical formats. Application-level segmentation reveals where clean-label premiums justify procurement costs versus commodity substitution pressure.
Product Type:
Powder formulations turn inventory slowest due to extended stability windows, while liquid concentrates require the tightest production-to-consumption cycles.
- Powder:Spray-dried thaumatin I and II proteins with moisture content below 5% deliver 24-month ambient stability. German beverage manufacturers rely on powder for seasonal production campaigns where cold-chain infrastructure is unavailable.
- Liquid:Aqueous solutions at 5-15% protein concentration demand refrigerated logistics and 90-day consumption windows. Ready-to-drink functional beverage brands in the Netherlands are qualifying liquid dosing systems for line-speed efficiency.
- Granular:Agglomerated particles improve flow properties for high-speed tableting operations in Swiss confectionery plants.
- Concentrate:Ultra-filtered slurries at 30%+ solids reduce shipping volumes for captive extraction-to-formulation pipelines.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
Margin structure varies sharply: beverages accept premium positioning while bakery tolerates only modest ingredient cost elevation.
- Beverages:Carbonated soft drinks, functional waters, and protein shakes exploit thaumatin's zero-glycemic impact and clean-label positioning. French retailers are embedding thaumatin in private-label ranges to meet sustainability scorecard thresholds.
- Confectionery:Premium chocolate and medicated lozenges command strongest pricing power where traceability documentation supports origin storytelling.
- Bakery:Bread and pastry applications remain volume-constrained due to thermal degradation of protein sweetness during oven processing.
- Dairy:Fermented products and flavored milk face pH compatibility challenges requiring buffered thaumatin formulations.
Beverages anchor procurement volume. Confectionery captures margin expansion.
End User:
Direct supplier relationships are displacing traditional distributor networks, compressing channel economics for intermediaries.
- Food Manufacturers:Processed food producers in Belgium and Switzerland establish captive sourcing agreements with West African extraction facilities for traceability documentation.
- Beverage Companies:Carbonated and functional drink formulators in Germany and France accelerate clean-label reformulation using retailer sustainability scorecards as procurement mandates.
- Ingredient Suppliers:Mid-scale distributors face margin compression as large buyers bypass traditional procurement channels.
- Retailers:Private-label developers seek direct extraction partnerships for organic-certified product lines.
Food manufacturers control upstream sourcing. Beverage companies are driving specification innovation fastest.
Distribution Channel:
Channel selection tracks buyer scale and technical service requirements, with large formulators favoring direct engagement.
- Direct Sales:Captive agreements between multinational confectioners and Ghanaian extraction facilities eliminate intermediary markups for premium chocolate segments.
- Wholesale:Regional distributors serve mid-tier bakery and dairy processors lacking procurement scale for direct sourcing.
- Online:Digital platforms capture small-batch R&D sampling and specialty ingredient procurement for startup beverage brands.
- Offline:Traditional distributor networks retain relevance in markets where regulatory compliance documentation requires local representation.
Direct sales command the largest transaction values. Online channels are climbing fastest for sampling and pilot-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in thaumatin track divergent regulatory pathways and extraction capacity distribution. Ghana and Ivory Coast dominate raw botanical supply, while Germany, Switzerland, and Japan concentrate downstream formulation demand. The F-Gas Regulation and REACH compliance costs are filtering supplier access to European procurement channels.
Germany
Beverage manufacturers in Bavaria and North Rhine-Westphalia are accelerating clean-label reformulation using retailer sustainability scorecards as procurement mandates. The country's national food regulator enforces strict novel food documentation requirements for protein-based sweeteners. Cologne and Hamburg host major ingredient distributors establishing direct sourcing agreements with West African extraction facilities.
Switzerland
Premium chocolate and medicated lozenge producers in Zurich and Geneva command strongest pricing power where traceability documentation supports origin storytelling. Swissmedic maintains rigorous safety assessment protocols for botanical-derived food ingredients. The Basel industrial cluster concentrates formulation R&D for pediatric and geriatric drug masking applications.
Japan
METI's Foods with Function Claims system rewards natural sweeteners with documented metabolic benefits, creating premium positioning in aging-population products. The Kanto region around Tokyo anchors functional beverage development. Osaka-based confectioners are qualifying thaumatin for clean-label positioning in traditional wagashi modernization.
United States
FDA GRAS self-affirmation enables faster market entry timelines versus European novel food pathways. California beverage startups and Midwest processed food manufacturers drive powder formulation demand. Chicago and New Jersey logistics hubs manage cold-chain distribution for liquid concentrate variants.
India
FSSAI clearance for protein-based sweeteners is opening procurement channels for multinational suppliers targeting processed food manufacturers in Maharashtra and Gujarat. Mumbai and Ahmedabad industrial zones concentrate dairy and bakery formulation activity. Domestic beverage brands are piloting thaumatin in functional drink lines for urban metro consumers.
Thaumatin Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: global ingredient platforms with multi-continent distribution, specialized botanical extraction houses with captive West African sourcing, and integrated fermentation specialists with bioprocess capabilities. Competitive intensity centers on purification technology validation and direct supplier relationships displacing traditional distributor networks. M&A activity targets extraction facility control, while capacity expansion focuses on low-temperature processing infrastructure.
Within the global platform tier, Ingredion Incorporated and Tate & Lyle PLC represent scale-driven distribution architectures spanning multiple continents. Specialized extraction capabilities anchor PureCircle Limited and Naturex S.A. as botanical-focused operators. Ajinomoto Co., Inc. occupies a distinct position integrating fermentation expertise with natural product portfolios. Symrise AG and Firmenich S.A. exemplify flavor-and-fragrance houses extending into sweetness modulation. Beneo GmbH and Archer Daniels Midland Company represent European and North American ingredient suppliers respectively, each navigating divergent regulatory compliance burdens across FDA and EFSA jurisdictions.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| PureCircle Limited |
| Ajinomoto Co., Inc. |
| Symrise AG |
| Firmenich S.A. |
| Tate & Lyle PLC |
| Beneo GmbH |
| Naturex S.A. |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Ghanaian extraction facilities is compressing procurement timelines for European beverage manufacturers and amplifying price volatility for thaumatin I and II isolates. This utilization squeeze simultaneously rewards suppliers with validated low-temperature purification capacity and penalizes buyers locked into spot-market sourcing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across organic-certified, conventional botanical, and precision-fermented tiers. Price differentiation hinges on EFSA novel food dossier completeness and F-Gas Regulation compliance documentation. Cost compression in mid-tier confectionery applications is intensifying because Reb A steviol glycosides from large-scale fermentation undercut thaumatin on unit economics. Small-batch beverage startups exhibit highest price sensitivity, while Swiss premium chocolate manufacturers absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Katemfe fruit wild harvesting in Ghana and Ivory Coast feeds into thaumatin I and II isolation, with protein stability buffers and chromatographic resins as critical processing inputs. Single-source vulnerability concentrates in West African wild collection zones exposed to climate variability and regulatory enforcement gaps. Distribution runs through direct captive agreements between multinational confectioners and extraction facilities, displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thaumatin sits at an inflection where precision fermentation analogs are collapsing traditional botanical extraction economics, while divergent FDA-EFSA regulatory pathways are fragmenting market access strategies.
For Market Incumbents: Pre-empt fermentation-based substitute encroachment by securing captive katemfe sourcing agreements in Ghana and Ivory Coast before capacity constraints harden. Accelerate EFSA novel food dossier investments for low-temperature extraction variants to compress approval timelines versus GRAS self-affirmation competitors. Vertical integration into aseptic liquid concentrate filling infrastructure captures ready-to-drink beverage specification shifts. For New Entrants and Emerging Players: Pursue pharmaceutical taste-masking applications in pediatric and geriatric formulations, where thaumatin's protein-based chemistry outperforms sugar alcohols and regulatory barriers filter out commodity sweetener competitors. Target India's FSSAI-cleared protein-based sweetener channel, where multinational supplier penetration remains shallow and domestic beverage brands seek clean-label positioning for urban metro consumers. Lead with bioprocess innovation narratives to differentiate from incumbent botanical extraction architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation thaumatin analog production, favoring scaled bioprocess specialists over capital-light botanical extraction houses. Five-to-ten year viability favors acquisition targets with dual FDA-EFSA regulatory affairs capabilities and validated low-temperature purification infrastructure. Monitor EMA novel food approval velocity as the critical signal distinguishing market access winners from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Extraction | Secures katemfe supply concentration against climate volatility and ESG compliance tightening. |
| EFSA Novel Food Dossier Investment | Compresses European market entry timelines versus GRAS-affirmed US competitors. |
| Precision Fermentation Scale-Up | Reduces botanical dependency while maintaining protein sweetener functionality for beverage applications. |
| Aseptic Liquid Concentrate Infrastructure | Captures ready-to-drink formulation shifts in German and Dutch beverage manufacturing. |
| Pharmaceutical Taste-Masking Partnership | Opens pediatric and geriatric drug formulation channels beyond commodity food positioning. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with extraction facility operators, beverage formulation chemists, regulatory affairs specialists at EFSA and FDA, and procurement leads at German confectionery manufacturers; alongside secondary synthesis of EMA novel food submission databases, FSSAI clearance registries, F-Gas Regulation compliance filings, and botanical trade flow records. Bottom-up volume modeling triangulated against top-down market sizing from ingredient distributor transaction patterns.
Forecast inputs incorporated product type segmentation across powder, liquid, granular, and concentrate formats; application-level demand from beverages, confectionery, bakery, and dairy; and end-user procurement behavior spanning direct sales, wholesale, and digital channels. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of clean-label reformulation penetration rates, with precision fermentation cost curves and REACH registration timelines as industry-specific modifiers across the projection horizon.
Sensitivities concentrate around EMA novel food approval duration extensions, katemfe harvest yield variability, and steviol glycoside price erosion in mid-tier applications. Forecasts reflect documented assumptions on regulatory pathway convergence and bioprocess scale economics. Cross-checking against FAO botanical trade statistics and EFSA novel food register update frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market