
 Crumb Softener Market | 2026-2036
Crumb Softener Market Size, Share, and Industry Trends Forecast 2026-2036
Crumb Softener Market Analytics
North American production capacity is narrowing as regional milling complexes expand dedicated enzyme and emulsifier blending lines. Kerry Group leverages its integrated bakery ingredient platform to sustain formulation partnerships across industrial bread plants. Corbion competes through microbial fermentation expertise that anchors its clean-label positioning in European and North American markets. DuPont differentiates via enzyme technology leadership in crumb structure modification for high-fiber bread applications.
Crumb softener denotes a food additive formulation—typically comprising emulsifiers, enzymes, and hydrocolloids at 0.5-2.0% flour weight—that modifies starch retrogradation kinetics to extend bread shelf life and improve sliceability. Its primary commercial purpose centers on enabling packaged bread producers to maintain consumer-acceptable texture across distribution chains exceeding seven days. Liquid softener formulations dominate industrial bakery procurement due to metering precision and uniform dough incorporation, while powder variants occupy home baking and small-scale artisan segments where storage stability and dosing flexibility matter more. Concentrate formats represent the fastest-growing structural category as food manufacturers seek reduced freight costs and customized dilution protocols.
The FDA oversees crumb softener safety through GRAS notification and food additive petition pathways, while the EPA regulates processing facility effluent from enzyme manufacturing operations. The USDA's National Organic Program shapes demand through approved substance listings that constrain synthetic emulsifier use in certified organic bread lines. Stakeholders must monitor evolving enzyme labeling disclosure requirements and regional clean-label certification thresholds that increasingly determine bakery procurement criteria.
Market Dynamics
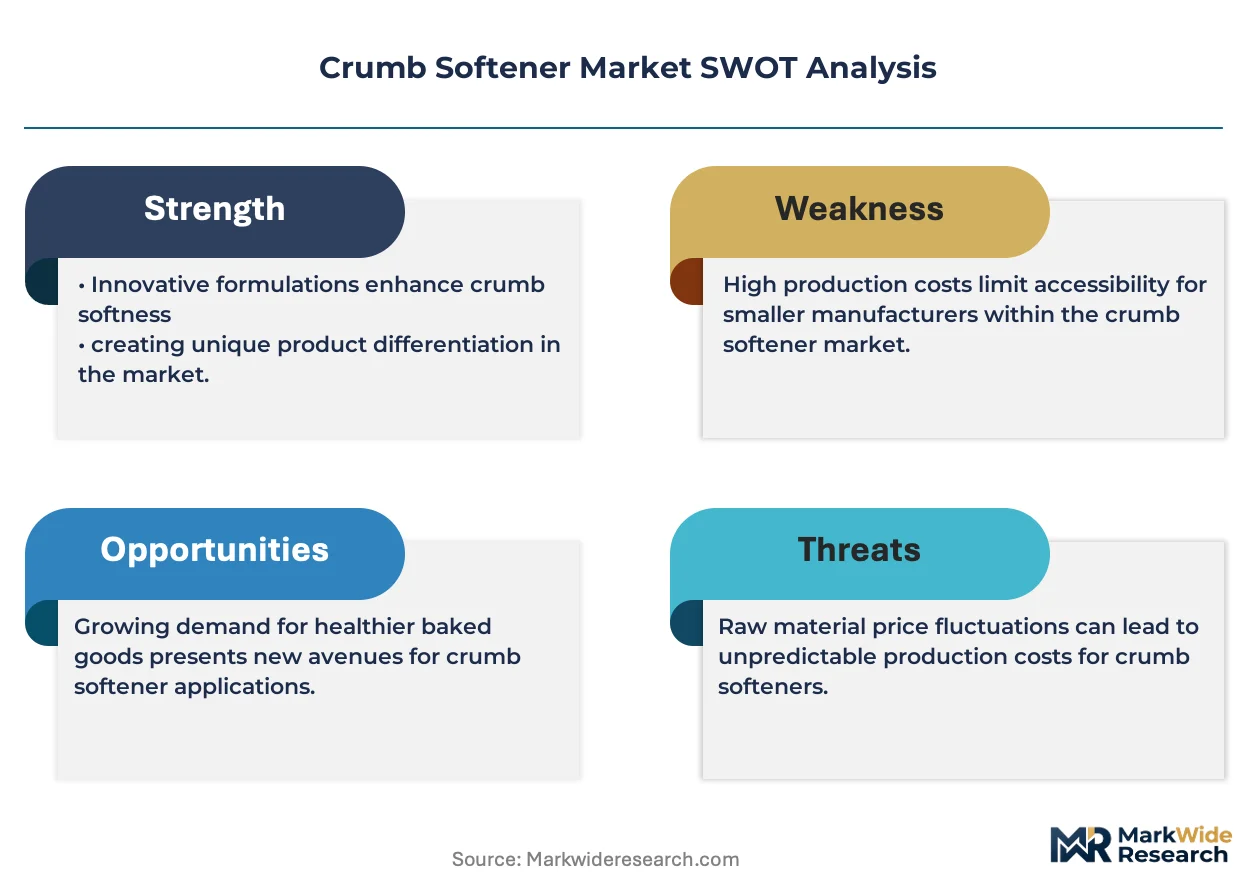
Clean-label reformulation mandates are compressing synthetic emulsifier volumes while enzyme-based alternatives capture formulation slots in premium bread lines. The USDA's National Organic Program substance approvals now determine supplier qualification thresholds for certified organic operations.
Growth Catalysts
- Enzyme engineering advances:Protein engineering platforms now deliver amylases with precise temperature-activity profiles, enabling bakers to reduce additive dosages while maintaining shelf-life targets. Artisan and industrial segments both adopt these refined biocatalysts.
- Extended distribution requirements:E-commerce grocery channels and centralized baking models require bread to maintain sensory quality across 10-14 day fulfillment cycles, driving softener incorporation rates in commercial formulations.
- FDA GRAS pathway efficiency:The self-affirmation notification system accelerates novel ingredient commercialization timelines, allowing fermentation-derived emulsifiers to reach market faster than petition-based alternatives.
Market Restraints
- Palm oil derivative supply concentration:Distilled monoglycerides—core emulsifier inputs—depend on Southeast Asian palm oil processing clusters vulnerable to climate volatility and export policy shifts.
- Clean-label certification fragmentation:Competing definitions across Non-GMO Project, USDA Organic, and retailer-specific standards force redundant formulation testing and label qualification costs.
- Enzyme activity stability limits:Liquid enzyme concentrates degrade during frozen dough storage, constraining their deployment in par-baked and frozen bakery applications where powder emulsifiers dominate.
Strategic Opportunities
- Fermentation-derived emulsifier expansion:Microbially produced glycolipids and phospholipids qualify for clean-label positioning while matching functional performance of synthetic alternatives, opening premium price tiers.
- Concentrate format customization:High-solids softener bases allow regional bakeries to dilute on-site, reducing freight costs and enabling localized formulation adjustments for wheat protein variability.
- Upcycled ingredient integration:Side-stream proteins from oilseed processing and brewing operations provide novel hydrocolloid sources that align with circular economy certifications sought by European retailers.
Industry Challenges
- Enzymologist talent scarcity:Formulation science now requires combined expertise in cereal chemistry and protein engineering, a skill intersection concentrated at few academic programs and ingredient suppliers.
- Legacy equipment compatibility:Automated dosing systems at mid-scale bakeries lack precision for low-inclusion enzyme concentrates, forcing capital reinvestment or outsourcing to toll manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crumb Softener Market |
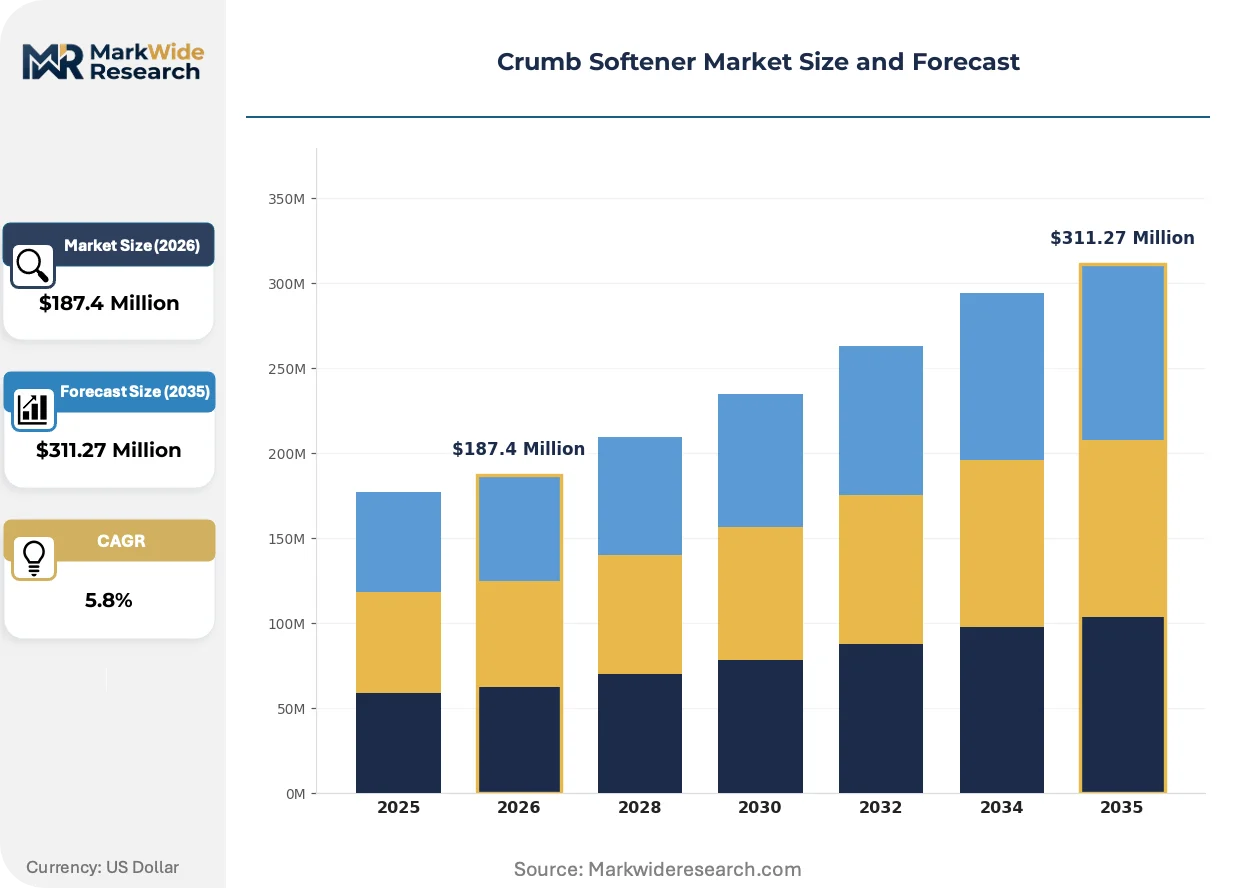
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Softener, Powder Softener, Granular Softener, Concentrate Application: Breads, Cakes, Pastries, Snacks End User: Bakeries, Food Manufacturers, Retail Stores, Home Users Form: Liquid, Powdered, Sprays, Blocks |
| Companies Covered | DuPont, Kerry Group, Archer Daniels Midland, Cargill, Corbion, Ingredion, Lallemand, Puratos, AB Mauri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crumb Softener Market Evolving Landscape
Bioprocess innovation and regulatory disclosure requirements are restructuring how texture-modifying ingredients reach commercial bread formulations. Suppliers now compete on fermentation scale and label transparency rather than commodity chemistry alone.
Transglutaminase-crosslinked protein networks are rendering obsolete traditional SSL/CSL emulsifier systems in high-hydration artisan breads. European clean-label bakeries have accelerated adoption since 2022, with enzyme suppliers now guaranteeing 14-day softness without synthetic additives. The shift compresses margins for legacy emulsifier manufacturers while rewarding integrated enzyme platforms.
EFSA's 2023 enzyme labeling guidance requires disclosure of production organism strain information on ingredient statements, forcing reformulation reviews across European Union member states. Industrial bakeries sourcing across multiple jurisdictions now demand dual-compliant formulations that satisfy both EFSA and FDA disclosure thresholds. The regulation disproportionately affects small enzyme houses lacking regulatory affairs scale.
Direct supplier relationships are displacing distributor-mediated ingredient procurement among top-20 North American bread manufacturers. Category managers now negotiate enzyme and emulsifier blends directly with Kerry Group, Corbion, and DuPont, extracting volume commitments in exchange for formulation exclusivity. This consolidation concentrates in commercial bakery headquarters located in Chicago, Toronto, and Mexico City metropolitan clusters.
Crumb Softener Market Segmentation
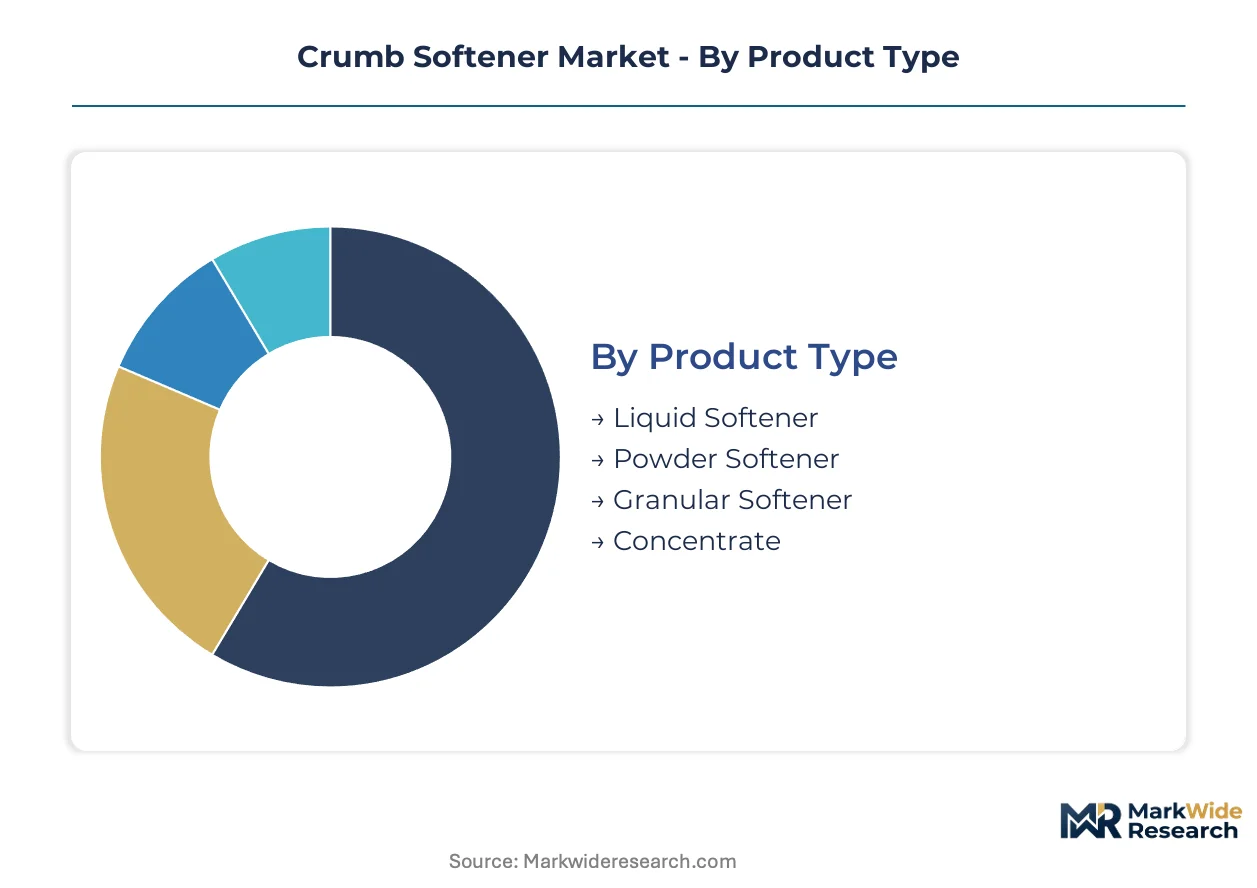
Crumb softener procurement patterns diverge sharply across formulation formats and end-use scale. Industrial bakeries prioritize metering precision and supply security, while artisan operators trade efficiency for dosing flexibility.
Product Type:
Cost tier determines procurement volumes and freight economics across industrial versus artisan segments.
- Liquid Softener:Pumpable emulsifier-enzyme suspensions at 20-40% solids enable automated dough metering. Industrial bread plants in the United States specify liquid formats for continuous mixing lines where inclusion precision below 0.1% flour weight prevents texture defects.
- Concentrate:High-solids bases at 60-80% active content dilute on-site with water or oil carriers. Regional bakeries in Mexico and Canada adopt concentrates to reduce inbound freight costs and customize viscosity for local wheat protein profiles.
- Powder Softener:Spray-dried emulsifier blends with silica carriers suit home baking and small-scale operations lacking liquid handling infrastructure.
- Granular Softener:Agglomerated particles reduce dusting and improve flowability for manual scaling environments.
Liquid softener holds installed capacity. Concentrate is rotating up the share rankings.
Application:
Volume throughput and shelf-life specifications vary dramatically across baked goods categories.
- Breads:Sliced pan breads and artisan loaves consume the majority of crumb softener volume. Extended distribution requirements for 10-14 day shelf-life targets drive enzyme-emulsifier co-formulation in commercial operations serving e-commerce grocery channels.
- Cakes:High-ratio layer cakes depend on emulsifier systems for crumb fineness and moisture retention. Premium cake manufacturers in the United States specify clean-label alternatives as retailer certification requirements tighten.
- Pastries:Laminated dough applications require distinct texture modification approaches where fat-flour interaction dominates over starch retrogradation control.
- Snacks:Shelf-stable cracker and cookie segments employ crumb softeners selectively for specific texture targets in filled or sandwich formats.
Breads command the volume base. Cakes are climbing the fastest as clean-label reformulation accelerates.
End User:
Customer type dictates formulation complexity, procurement scale, and technical service requirements.
- Food Manufacturers:Branded packaged bread producers operate dedicated R&D partnerships with ingredient suppliers. These customers negotiate multi-year supply agreements incorporating formulation exclusivity clauses and joint enzyme development programs.
- Bakeries:Commercial and artisan bakeries span a wide capability spectrum from automated plants to manual operations. Mid-scale facilities in Chicago and Toronto metropolitan clusters increasingly outsource blending to toll manufacturers lacking precision dosing equipment.
- Retail Stores:In-store bakery programs source through distributor channels with limited technical support, constraining adoption of enzyme-dependent systems requiring pH and temperature optimization.
- Home Users:Consumer-packaged softener sachets and spray formats occupy niche positions in premium baking supply retail.
Food manufacturers anchor supplier R&D investment. Bakeries are rotating up the share rankings as regional procurement consolidation proceeds.
Form:
Physical presentation shapes storage stability, incorporation method, and end-use compatibility.
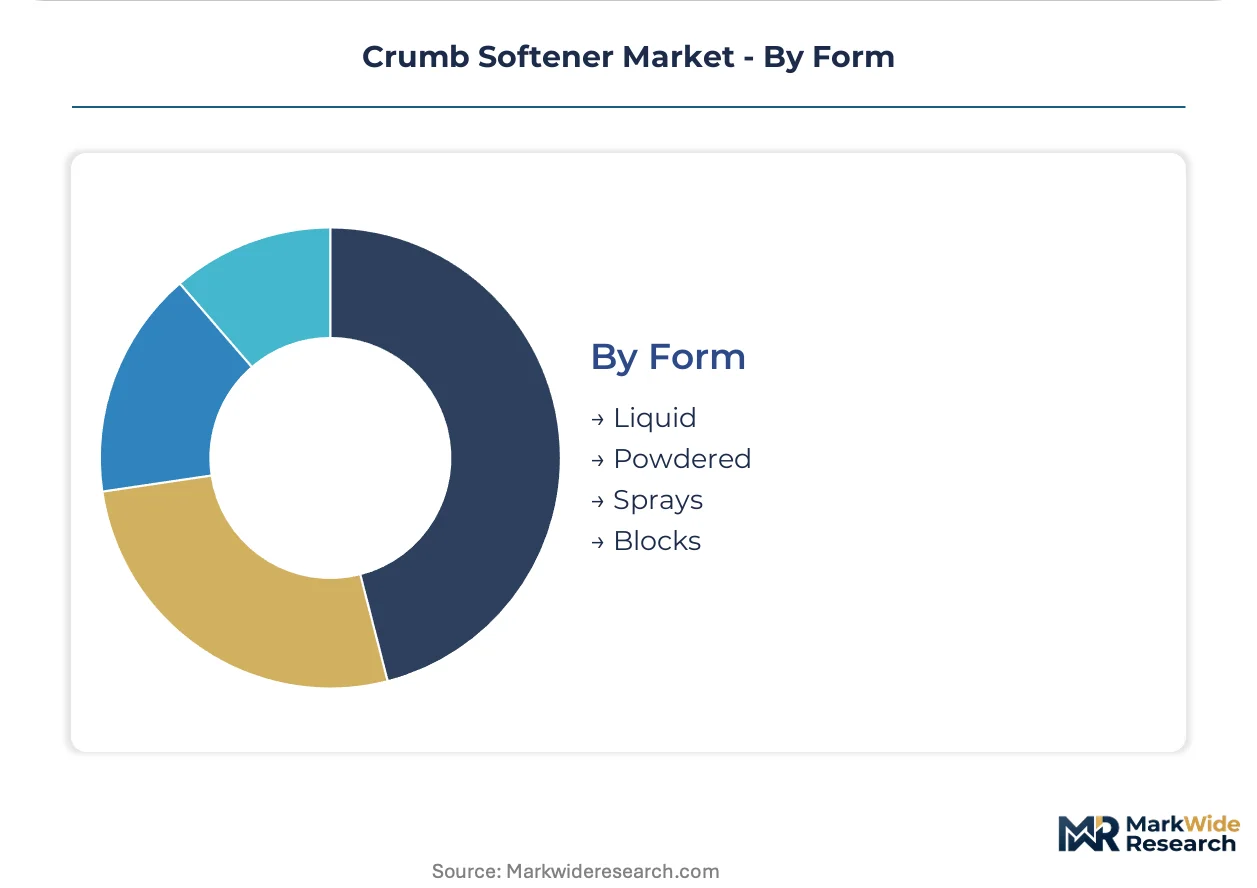
- Liquid:Pumpable formats dominate industrial procurement for uniform distribution in high-speed mixing environments.
- Powdered:Dry blends offer extended ambient storage and suit operations lacking chilled liquid handling infrastructure.
- Sprays:Aerosol or trigger-spray formats target surface application in specific artisan bread finishing protocols.
- Blocks:Solid fat-based carriers enable slow-release emulsifier delivery in specific frozen dough applications where liquid migration causes defects.
Liquid holds installed capacity. Powdered is rotating up the share rankings as frozen dough applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme manufacturing clusters in the United States and Western Europe anchor supply capacity for crumb softener formulations. Regional demand patterns diverge sharply between industrial bread plants requiring extended shelf-life solutions and artisan bakeries pursuing clean-label alternatives.
United States
Commercial bakeries in Chicago and Toronto metropolitan clusters drive concentrate format adoption for localized formulation control. The FDA's GRAS self-affirmation pathway accelerates novel enzyme commercialization timelines. Industrial bread plants serving e-commerce grocery channels specify 10-14 day shelf-life targets that elevate softener inclusion rates.
Germany
Artisan bread operations in Bavaria and North Rhine-Westphalia prioritize fermentation-derived emulsifiers for clean-label positioning. EFSA's 2023 enzyme labeling guidance forces reformulation reviews across member states. Microbial fermentation expertise concentrates in Baden-Württemberg, where suppliers anchor European clean-label supply chains.
France
Premium baguette producers in Île-de-France adopt transglutaminase-crosslinked systems to replace synthetic SSL/CSL emulsifiers. The EU Green Deal circular economy certifications drive upcycled ingredient integration from oilseed processing side-streams. Regional milling complexes in Hauts-de-France expand dedicated enzyme blending capacity.
Canada
Regional bakeries in Ontario and Quebec adopt concentrate formats to reduce inbound freight costs from US suppliers. Health Canada regulates novel enzyme submissions through pre-market notification requirements. Toronto-area mid-scale facilities increasingly outsource precision dosing to toll manufacturers lacking capital for equipment upgrades.
Mexico
Bakery operations in Mexico City and Nuevo León customize softener viscosity for local wheat protein variability. The country's national food safety regulator enforces additive labeling standards aligned with USMCA trade compliance. Concentrate dilution protocols spread through the Bajío Region as regional procurement consolidation proceeds.
Crumb Softener Market Competitive Landscape
Integrated ingredient platforms and specialized fermentation houses split the market between formulation breadth and biocatalytic depth. The vendor base organizes around three strategic archetypes: diversified nutrition conglomerates with bakery ingredient portfolios, microbial technology specialists leveraging fermentation scale, and regional enzyme houses serving niche clean-label segments. Dominant competitive moves include direct supplier relationships displacing distributor channels, and capacity expansion in high-solids concentrate manufacturing.
Within the integrated platform tier, Kerry Group and DuPont exemplify archetypes combining formulation partnerships with industrial bread plants. Corbion occupies a position representing microbial fermentation expertise that anchors clean-label positioning. These three entities sit within the supplier base that category managers at top-20 North American bread manufacturers negotiate directly, extracting volume commitments in exchange for formulation exclusivity across Chicago, Toronto, and Mexico City metropolitan clusters.
| Leading Market Players |
|---|
| DuPont |
| Kerry Group |
| Archer Daniels Midland |
| Cargill |
| Corbion |
| Ingredion |
| Lallemand |
| Puratos |
| AB Mauri |
| Others |
Value Network & Pricing Analysis
Trans-Pacific freight corridors from Southeast Asian palm oil processing clusters to North American industrial bread plants transmit cost volatility directly into emulsifier pricing tiers, concentrating margin pressure on suppliers lacking fermentation-derived alternatives while rewarding integrated enzyme platforms with pricing power across clean-label segments.
Pricing Analysis
USDA's National Organic Program substance approvals dictate the pricing tier structure across the crumb softener market. Three-tier pricing stratifies across certified organic, clean-label compliant, and conventional synthetic formulations, with organic certification commanding substantial premiums due to constrained approved substance lists. Price differentiation rests on fermentation scale and GRAS self-affirmation status, with synthetic emulsifier manufacturers facing intensifying cost compression from palm oil derivative supply volatility. Mid-scale regional bakeries in Chicago and Toronto metropolitan clusters exhibit highest price sensitivity, while top-20 North American bread manufacturers leverage volume commitments for formulation exclusivity discounts.
Supply Chain Analysis
Tariff exposure between Southeast Asian palm oil processing hubs and North American industrial bakeries dominates supply chain risk assessment for distilled monoglyceride-dependent emulsifier systems. Manufacturing capacity concentrates in Malaysia, Indonesia, and Thailand, with enzyme production anchored in United States and Western European fermentation facilities. Raw material dependencies center on palm oil fractions, microbial fermentation feedstocks, and specialized hydrocolloid sources from oilseed processing side-streams. Single-source vulnerability in Southeast Asian oleochemical clusters threatens supply continuity, while distribution runs through direct supplier relationships displacing traditional distributor channels among major bread manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crumb softener market exhibits cyclical recovery characteristics as extended distribution requirements from e-commerce grocery channels drive reformulation cycles, with enzyme engineering advances compressing synthetic emulsifier replacement timelines across commercial bakery operations.
For Market Incumbents: Insulate formulation partnerships through captive supply of fermentation-derived emulsifiers, backward integration into microbial production capacity in Baden-Württemberg and comparable enzyme manufacturing clusters. Expand high-solids concentrate manufacturing to defend against toll manufacturer encroachment in mid-scale bakery segments. Prioritize dual-compliant formulation development satisfying both EFSA enzyme labeling guidance and FDA GRAS disclosure thresholds.
For New Entrants and Emerging Players: Artisan bread operations in Bavaria and North Rhine-Westphalia seeking transglutaminase-crosslinked systems represent the most penetrable entry point for clean-label positioning. Regional bakeries in Mexico's Bajío Region adopting concentrate dilution protocols offer second-tier expansion opportunity. Pursue direct technical service relationships bypassing distributor channels, leveraging enzymologist expertise scarcity to secure formulation partnerships.
For Investors and Strategic Acquirers: Specialized microbial fermentation houses with established clean-label certification pathways present acquisition targets with defensive moats against commodity emulsifier competition. Long-term viability hinges on bioprocess innovation scale and regulatory affairs capabilities spanning multiple jurisdictions. Monitor EFSA enforcement patterns and USDA Organic Program substance list revisions as early signals of competitive repositioning requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation-Derived Emulsifier Scale-Up | Microbial glycolipid production qualifies for clean-label positioning while matching synthetic functional performance. |
| High-Solids Concentrate Manufacturing Expansion | Regional bakeries in Mexico and Canada reduce freight costs through on-site dilution protocols. |
| Dual-Compliant Formulation Development | Industrial bakeries sourcing across EU and US jurisdictions demand unified EFSA-FDA disclosure standards. |
| Direct Supplier Relationship Consolidation | Category managers at top-20 North American bread manufacturers negotiate volume-commitment exclusivity clauses. |
| Upcycled Ingredient Integration | Oilseed processing side-stream proteins align with EU Green Deal circular economy certification requirements. |
Research Methodology
The analysis maps liquid softener, concentrate, powder, and granular formulation categories, each validated through bakery procurement managers, enzyme supplier technical directors, and toll manufacturer operations heads. Primary fieldwork combined structured interviews with industrial bread plant R&D directors, artisan bakery owners, and regulatory affairs specialists at ingredient suppliers. Secondary validation drew from FDA GRAS notification databases, EFSA enzyme labeling guidance documents, USDA National Organic Program substance listings, and customs records tracking emulsifier import flows. Bottom-up volume estimates from individual bakery operations triangulated against top-down supplier capacity assessments.
Forecast assumptions held fixed the current regulatory disclosure threshold trajectory while varying enzyme adoption rates across artisan versus industrial segments. The analytical framework modeled product format, application category, end-user scale, and physical form dimensions across the projection horizon. CAGRs derived from segment-level growth drivers including clean-label reformulation mandates, extended distribution shelf-life requirements, and concentrate format penetration. Industry-specific inputs incorporated wheat protein variability patterns affecting regional formulation customization and frozen dough storage stability constraints on liquid enzyme deployment.
Practitioners should monitor EFSA enforcement discretion on production organism strain disclosure and USDA Organic Program substance list expansion for early signals of competitive repositioning requirements. Forecasts reflect assumptions about regulatory pathway efficiency and enzyme engineering advancement rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market