
 India Food Flavor and Enhancer Market | 2026-2036
India Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Flavor and Enhancer Market Foresight
FSSAI's clean-label mandates for natural versus synthetic distinction is restructuring procurement priorities across India's packaged food sector. Givaudan SA leverages its captive botanical extraction infrastructure to secure raw material traceability for natural flavor lines. Kerry Group plc anchors its position through integrated taste modulation R&D facilities in Karnataka. Synthite Industries dominates the oleoresin-derived natural segment with backward integration into Kerala spice sourcing.
Food flavor and enhancer encompasses volatile and non-volatile compounds—esters, aldehydes, pyrazines, nucleotides, and glutamates—formulated to deliver, intensify, or modify sensory perception at parts-per-million thresholds, primarily serving industrial food systems seeking batch consistency and cost-optimized taste delivery. Natural flavor commands premium positioning as FSSAI scrutiny tightens on synthetic additive declarations, while flavor enhancer volumes expand fastest through instant noodle and savory snack applications. Powder form occupies the largest share of institutional procurement due to extended shelf stability and freight efficiency, though liquid concentrates gain traction in beverage processing.
FSSAI, BIS, and the Food Safety and Standards Regulations collectively govern ingredient disclosure, maximum usage levels, and manufacturing hygiene protocols, with FSSAI's 2022 additive clarification orders directly triggering reformulation cycles among national snack brands. The Bureau of Indian Standards maintains compositional benchmarks for flavor labeling integrity, while state food safety commissioners enforce plant-level compliance through risk-based inspection schedules. Stakeholders must monitor evolving FSSAI natural claim definitions and invest in analytical authentication capabilities before enforcement windows tighten.
Market Dynamics
FSSAI's tightened natural-versus-synthetic labeling mandates are forcing reformulation investments across India's packaged food sector, restructuring procurement priorities from commodity sourcing toward authenticated botanical supply chains.
Growth Catalysts
- Urban Convenience Demand:Processed snack manufacturers now represent the fastest-expanding buyer segment as Maharashtra and Gujarat households shift toward convenience formats requiring standardized flavor delivery.
- PLI Scheme Incentives:India's production-linked incentive scheme for food processing is attracting technical center investments from multinational flavor houses seeking localized R&D infrastructure.
- Spice Corridor Concentration:Kerala's oleoresin extraction cluster provides captive raw material access for natural flavor lines, compressing lead times versus imported alternatives.
Market Restraints
- Input Cost Volatility:Vanilla and citrus oil prices swing unpredictably due to climate disruption in Kerala and Karnataka growing belts, squeezing margin predictability for natural-positioned portfolios.
- Regulatory Friction:FSSAI's 2022 additive clarification orders triggered immediate reformulation cycles, forcing inventory write-downs among national snack brands with legacy synthetic formulations.
- Technical Limitation:Heat-stable natural alternatives to pyrazine-based roasted notes remain commercially immature, constraining clean-label migration in savory snack applications.
Strategic Opportunities
- Underpenetrated North East:Assam and Manipur food processing corridors lack localized flavor technical support, creating first-mover advantage for regional distribution partnerships.
- Beverage Concentrate Channel:Liquid flavor concentrates are gaining traction in Maharashtra juice processing as powder-to-liquid conversion costs erode competitiveness in high-volume applications.
- BIS Certification Tailwind:Bureau of Indian Standards flavor labeling integrity benchmarks create differentiation premium for early analytical authentication adopters ahead of enforcement tightening.
Industry Challenges
- Analytical Skill Gap:Gas chromatography-mass spectrometry authentication expertise for natural claim verification remains scarce among mid-tier flavor houses, delaying FSSAI compliance timelines.
- Legacy System Integration:ERP traceability modules for batch-level botanical provenance require capital deployment that fragments across fragmented spice supplier bases in Karnataka and Tamil Nadu.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Flavor and Enhancer Market |
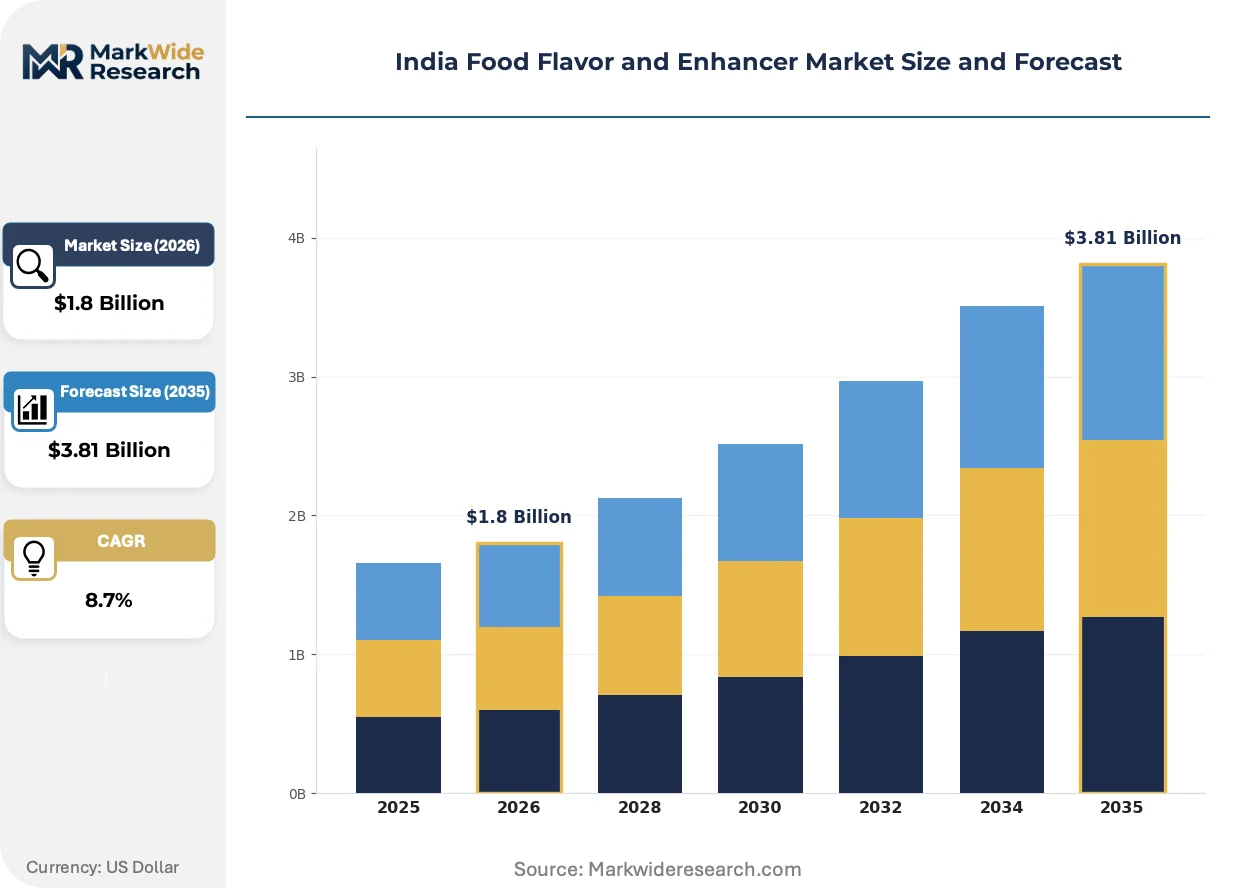
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavor, Synthetic Flavor, Flavor Enhancer, Seasoning Blend Application: Bakery, Beverages, Snacks, Dairy Form: Liquid, Powder, Paste, Granules End User: Food Manufacturers, Restaurants, Retailers, Home Cooks |
| Companies Covered | Symrise AG, Ajinomoto Co. Inc., Givaudan SA, Keva Flavours, Synthite Industries, International Flavors & Fragrances, Kerry Group plc, Sensient Technologies, DSM-Firmenich, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Flavor and Enhancer Market Shifts & Advancements
Clean-label authentication technologies and regional processing infrastructure investments are compressing the gap between natural positioning claims and verified supply chain reality across India's flavor sector.
Encapsulation technology for volatile ester stabilization is expanding into Maharashtra's savory snack processing corridors. National brands adopting spray-dried flavor matrices report extended shelf stability without synthetic antioxidant dependencies. This technology is expanding into Gujarat's extruded snack manufacturing, enabling cleaner ingredient declarations while maintaining batch consistency.
FSSAI's evolving natural claim definitions are forcing analytical capability investments across the value chain. State food safety commissioners now enforce plant-level compliance through risk-based inspection schedules targeting synthetic additive declarations. National snack brands with legacy formulations face compressed reformulation windows as enforcement protocols tighten in Maharashtra and Karnataka processing hubs.
Direct procurement relationships between flavor houses and Kerala spice cooperatives are displacing traditional aggregator intermediaries. Instant noodle manufacturers now source oleoresin-derived extracts through authenticated channels, compressing price volatility exposure. This pattern concentrates most visibly in Gujarat's concentrated food processing corridors where technical center proximity enables real-time formulation collaboration.
India Food Flavor and Enhancer Market Segmentation
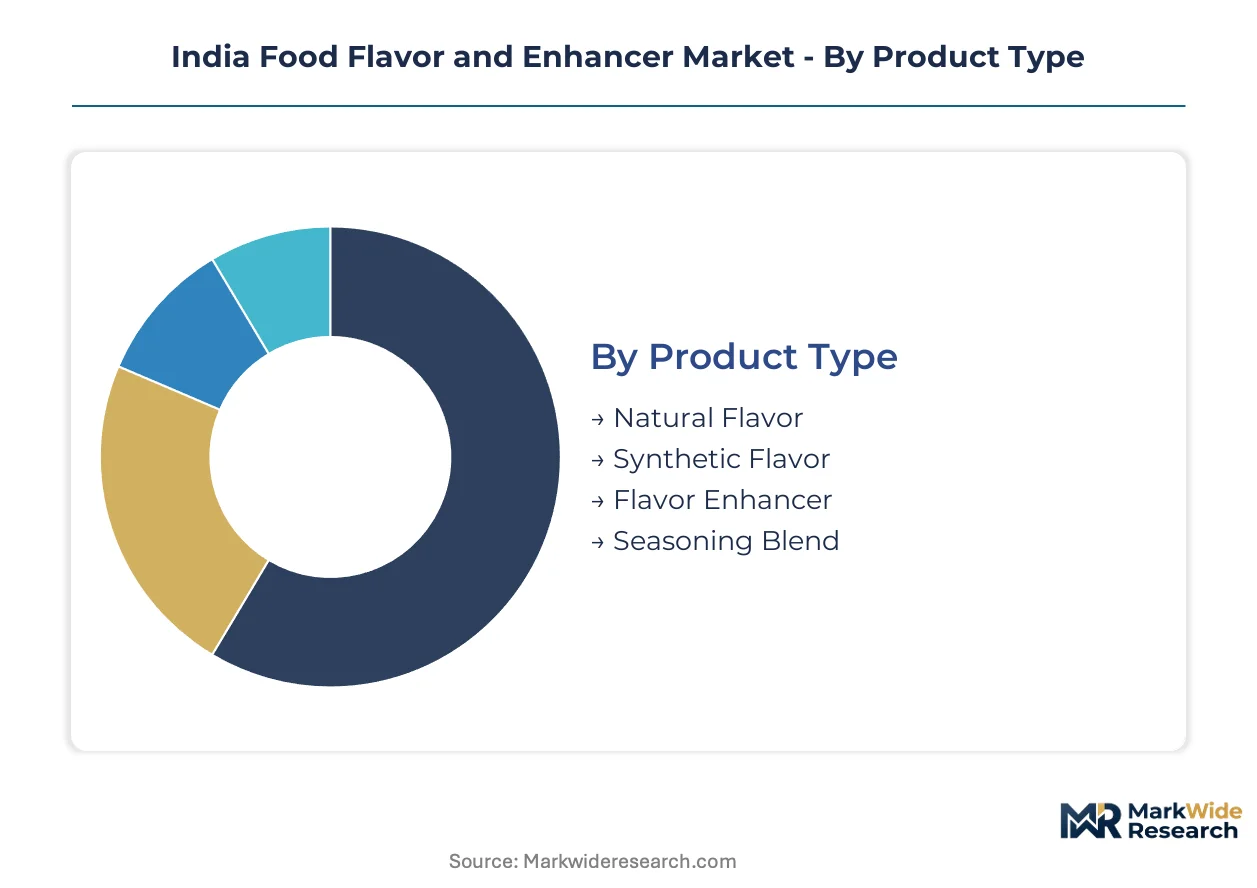
Segmentation in India's food flavor market reveals distinct procurement patterns between industrial-scale food manufacturers and fragmented foodservice operators. FSSAI compliance requirements create divergent specification standards across end-user categories, while form factor choices directly link to processing infrastructure investments in Maharashtra and Gujarat corridors.
Product Type:
Natural flavor lines require standalone botanical authentication systems, whereas synthetic alternatives and enhancers embed directly into compound seasoning systems without separate provenance documentation.
- Natural Flavor:Botanical extracts and oleoresins derived from Kerala spice corridors demand gas chromatography-mass spectrometry verification for FSSAI clean-label compliance. Maharashtra snack manufacturers now mandate batch-level traceability documentation, compressing supplier qualification timelines.
- Flavor Enhancer:Nucleotide and glutamate compounds intensify umami perception at sub-percentage inclusion rates. Instant noodle processors in Gujarat represent the steepest expansion trajectory for monosodium glutamate and disodium inosinate blends.
- Synthetic Flavor:Pyrazine-based roasted notes and ester fruit profiles deliver cost-optimized taste replication. Reformulation investments are accelerating as FSSAI tightens disclosure mandates for artificial additive declarations.
- Seasoning Blend:Pre-compounded flavor-salt-carrier matrices target small-format snack producers lacking in-house blending capabilities.
Volume placements concentrate in Flavor Enhancer; the faster expansion belongs to Natural Flavor.
Application:
Cost tier differentiation separates premium-positioned dairy flavor systems from commodity snack seasonings.
- Snacks:Extruded and fried savory applications require heat-stable flavor matrices resistant to Maillard degradation. Gujarat's concentrated processing corridors generate concentrated demand for encapsulated seasoning systems.
- Beverages:Acid-stable liquid concentrates and emulsion flavor systems serve juice and carbonated drink processors. Maharashtra bottling plants are converting from powder reconstruction to direct liquid dosing infrastructure.
- Bakery:Lipid-soluble vanilla and butter flavor compounds withstand high-temperature baking profiles.
- Dairy:Fermentation-compatible fruit and confectionery notes integrate into yogurt and ice cream bases.
Margin concentration sits with Beverages; share expansion is steepest in Snacks.
Form:
Supply chain configuration separates freight-efficient powder formats from liquid concentrates requiring specialized handling infrastructure.
- Powder:Spray-dried and plated flavor matrices on maltodextrin or salt carriers dominate institutional procurement for shelf stability. Karnataka food manufacturers prioritize powder formats for extended storage in ambient warehouse conditions.
- Liquid:Aqueous and oil-based concentrates enable precise dosing in high-volume beverage processing. Maharashtra juice processors are displacing powder reconstruction with direct liquid concentrate pipelines.
- Paste:High-viscosity emulsions target artisanal bakery and confectionery applications requiring manual incorporation.
- Granules:Agglomerated free-flowing particles reduce dust exposure in savory snack seasoning operations.
Procurement volume clusters in Powder; conversion momentum favors Liquid.
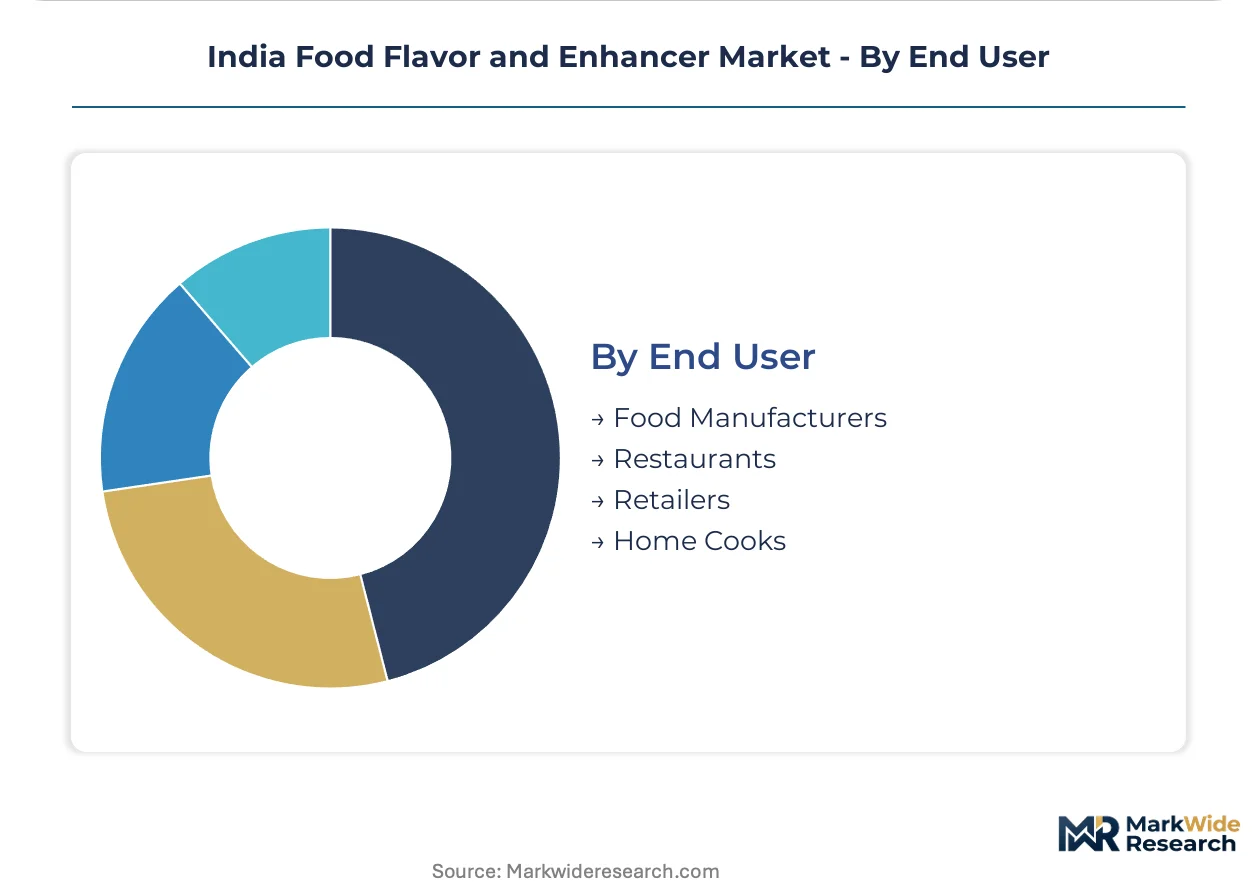
End User:
Customer type determines specification complexity, with food manufacturers demanding certificate-of-analysis documentation absent from retail and foodservice channels.
- Food Manufacturers:Industrial-scale processors in Gujarat and Maharashtra require FSSAI-compliant additive declarations and batch consistency guarantees. Technical center proximity enables real-time formulation collaboration for clean-label migration.
- Restaurants:Chain foodservice operators in urban Maharashtra seek standardized seasoning sachets for menu consistency across outlet networks.
- Retailers:Private-label packaged food programs demand turnkey flavor systems from co-manufacturing partners.
- Home Cooks:Consumer-format seasoning blends and liquid drops target convenience-oriented urban households.
Revenue concentration rests with Food Manufacturers; penetration expansion is fastest among Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Mumbai-Pune food processing corridor concentrates India's highest flavor technical center density, with multinational houses anchoring R&D facilities alongside domestic extraction operations.
Maharashtra
Urban households in Mumbai and Pune drive processed snack demand requiring standardized flavor delivery systems. FSSAI's 2022 additive clarification orders forced immediate reformulation investments among legacy snack brands headquartered in the state. The Mumbai-Pune corridor hosts concentrated technical center infrastructure where flavor houses collaborate with extruded snack manufacturers on clean-label migration.
Gujarat
Instant noodle processors and savory snack extruders generate steep demand expansion for monosodium glutamate and nucleotide enhancer blends. India's PLI scheme for food processing attracts capacity investments from compound seasoning manufacturers. The Ahmedabad-Vadodara belt concentrates extruded snack production where encapsulated flavor matrices enable synthetic-free ingredient declarations.
Karnataka
Beverage bottling plants in Bengaluru convert from powder reconstruction to direct liquid concentrate dosing infrastructure. BIS compositional benchmarks for flavor labeling integrity drive analytical authentication investments among regional juice processors. The state's warehousing infrastructure favors powder format procurement for ambient storage efficiency in extended distribution networks.
Kerala
Oleoresin extraction clusters provide captive raw material access for natural flavor lines derived from cardamom, black pepper, and ginger. Direct procurement relationships between flavor houses and spice cooperatives displace traditional aggregator intermediaries. Kochi and Alappuzha processing zones concentrate backward-integrated supply chains compressing price volatility exposure versus imported botanical alternatives.
Tamil Nadu
Dairy and confectionery applications in Chennai and Coimbatore drive fermentation-compatible fruit flavor demand for yogurt and ice cream bases. State food safety commissioners enforce risk-based inspection schedules targeting synthetic additive declarations in processing facilities. The state's fragmented spice supplier base complicates ERP traceability module deployment for batch-level botanical provenance documentation.
India Food Flavor and Enhancer Market Competitive Landscape
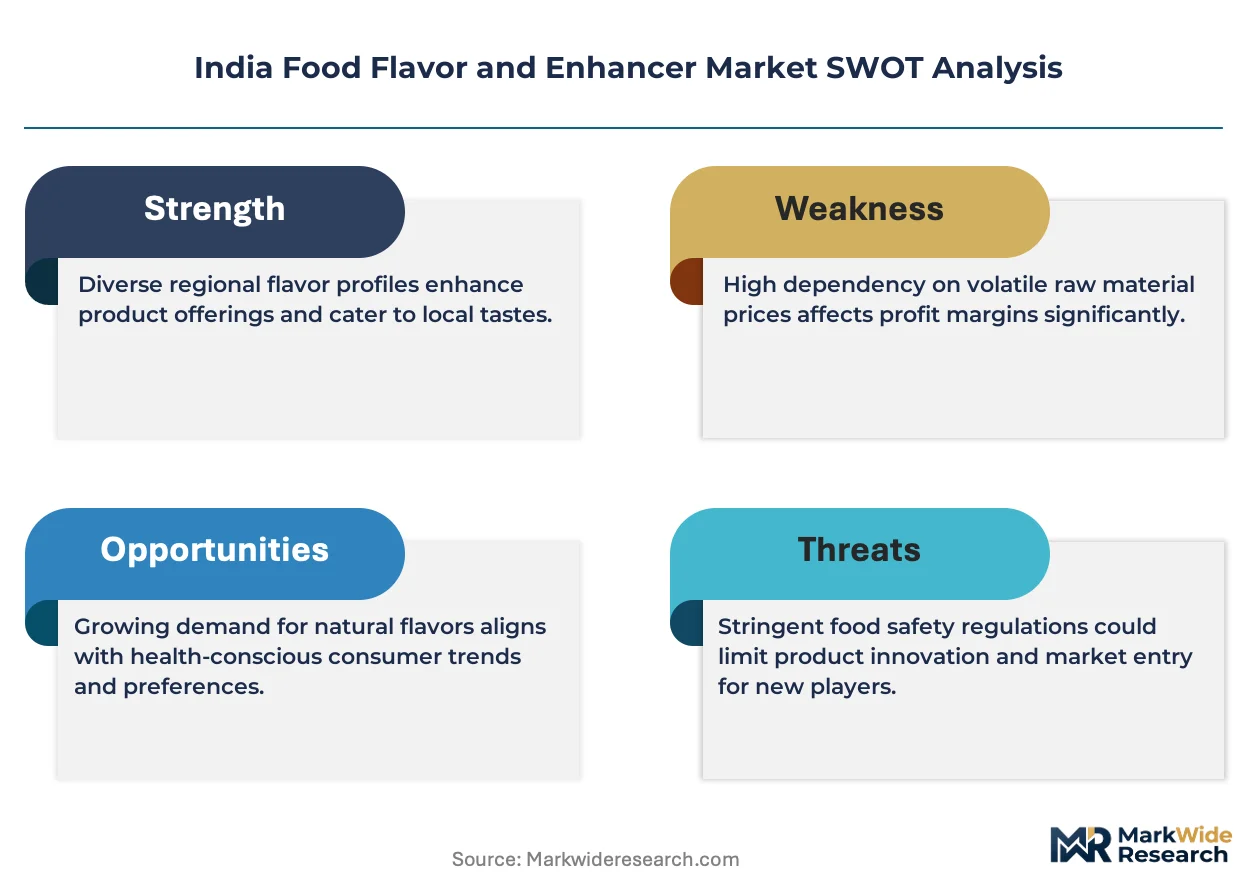
Premium-margin players sit above commodity-margin players across authentication capability and captive raw material access. The vendor base stratifies into three tiers: multinational flavor houses with integrated botanical extraction infrastructure, domestic specialists with regional spice corridor backward integration, and commodity compounders serving price-sensitive snack seasoning markets. Two dominant competitive moves are reshaping positioning: technical center proximity investments in Maharashtra and Gujarat processing hubs, and analytical authentication capability buildout ahead of FSSAI enforcement tightening.
Within the integrated multinational tier, Givaudan SA, Kerry Group plc, and Symrise AG exemplify archetypes spanning captive botanical extraction, taste modulation R&D infrastructure, and global formulation libraries. Domestic specialists including Synthite Industries and Keva Flavours occupy positions anchored in Kerala oleoresin sourcing and regional distribution partnerships respectively. Ajinomoto Co. Inc. represents the enhancer-focused segment where nucleotide and glutamate compound volumes concentrate in instant noodle and savory snack applications.
| Leading Market Players |
|---|
| Symrise AG |
| Ajinomoto Co. Inc. |
| Givaudan SA |
| Keva Flavours |
| Synthite Industries |
| International Flavors & Fragrances |
| Kerry Group plc |
| Sensient Technologies |
| DSM-Firmenich |
| Others |
Supply & Pricing Matrix
Vanilla and citrus oil price indices in Kerala and Karnataka growing belts cascade through India's flavor value chain into three-tier pricing structures across premium natural, standard synthetic, and economy enhancer tiers. FSSAI's clean-label mandates compress margin predictability for natural-positioned portfolios while amplifying price premiums for authenticated botanical supply chains.
Pricing Analysis
Yield-per-batch consistency anchors value-based pricing for natural flavor lines serving Maharashtra snack manufacturers demanding FSSAI-compliant traceability documentation. Three-tier pricing structure across premium natural, standard synthetic, and economy enhancer levels separates authenticated oleoresin extracts from commodity nucleotide compounds. Cost compression in synthetic tiers is intensifying because reformulation investments drain R&D budgets. Small-format snack producers exhibit highest price sensitivity; multinational beverage processors absorb premium natural positioning costs.
Supply Chain Analysis
Skilled extraction technicians in Kerala's Alappuzha processing zones and Karnataka's Bengaluru corridor constrain capacity expansion for natural flavor lines. Supply concentrates in India for oleoresin extraction, with secondary sourcing from Indonesia and Vietnam for vanilla and citrus oil alternatives. Raw material dependencies center on cardamom, black pepper, ginger, and specialty citrus cultivars. Single-source vulnerability runs through Kerala's spice cooperative networks. Distribution runs through Maharashtra and Gujarat technical centers for formulation collaboration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's food flavor market operates as a supply-constrained system where analytical authentication capability scarcity props pricing premiums for verified natural lines.
For Market Incumbents: Hedge margin erosion by securing captive oleoresin extraction capacity in Kerala before FSSAI enforcement windows tighten. Anchor positioning through gas chromatography-mass spectrometry infrastructure investments that mid-tier competitors cannot replicate. Defend against emerging domestic specialists by locking multi-year procurement contracts with Maharashtra snack manufacturers.
For New Entrants and Emerging Players: FSSAI's 2022 additive clarification orders in India opens a window for analytical service providers targeting mid-tier flavor houses lacking in-house authentication capabilities. Penetrate Assam and Manipur food processing corridors where localized technical support remains absent. Pursue regional distribution partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic specialists with Kerala backward integration in India's spice corridors. Long-term viability over a multi-year horizon hinges on authenticated supply chain control rather than formulation libraries. Watch FSSAI natural claim definition evolution as the inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kerala Spice Sourcing | Synthite Industries anchors natural flavor positioning through captive oleoresin extraction infrastructure. |
| Analytical Authentication Capability Buildout | Gas chromatography-mass spectrometry investments compress FSSAI compliance timelines for Maharashtra processors. |
| Technical Center Proximity Investment | Givaudan SA and Kerry Group plc localize R&D collaboration with Gujarat extruded snack manufacturers. |
| Clean-Label Migration Partnership | Encapsulation technology adoption enables synthetic-free declarations in savory snack applications. |
| Regional Distribution Network Expansion | First-mover positioning in Assam and Manipur corridors captures underpenetrated food processing demand. |
Research Methodology
Independent corroboration across FSSAI regulatory filings, BIS compositional benchmarks, and Kerala spice cooperative procurement records underwrites the qualitative findings. Primary interviews with flavor house R&D directors, FSSAI compliance officers, Maharashtra snack manufacturer procurement leads, and Karnataka beverage processor plant managers combined with secondary validation from trade customs data, FSSAI additive clarification orders, and state food safety commissioner inspection schedules. Bottom-up volume modeling and top-down value reconciliation triangulate market sizing.
Rate-of-change decomposition across product type, application, form, and end user dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by price-tier evolution. Industry-specific forecast inputs include FSSAI enforcement intensity assumptions and Kerala spice yield volatility patterns.
The model assumes a particular technology adoption path; alternative pathways for heat-stable natural pyrazine alternatives would alter the outlook. Forecasts reflect assumptions about FSSAI natural claim definition stability and Kerala climate patterns. Material deviation in FSSAI enforcement timelines or spice corridor weather events warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Flour Improvers Market