
 Instant Whipping Agents Market | 2026-2036
Instant Whipping Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Whipping Agents Market Analysis
China is fragmenting as domestic producers expand spray-drying capacity for whipping agent intermediates. Wacker Chemie AG leverages its silicone-based aerating technology to dominate specialty dessert applications in Europe. BASF anchors its position through backward integration into emulsifier feedstocks, while Kerry Group competes via customized stabilizer blends for industrial bakeries.
Instant whipping agents comprise functional food additives—typically hydrocolloid, protein, or surfactant-based powders or liquids—that entrap air into aqueous or lipid phases to create stable foams with overrun values between 80% and 150%. These agents enable consistent texture, volume, and shelf stability in aerated food systems without mechanical whipping equipment. Emulsifiers command the deepest margin pools due to dual-functionality in fat-water interface stabilization, while aerating agents in powdered form represent the fastest-growing configuration as dry-mix dessert brands expand. Dessert applications lead volume consumption, though dairy products show the strongest structural momentum from plant-based whipped topping substitution.
The FDA's GRAS notification pathway shapes ingredient approval timelines for US food manufacturers, while the EU Green Deal and REACH compliance obligations drive reformulation toward bio-based emulsifiers. China's SAMR enforces stricter GB standards on food additive labeling, raising compliance costs for imported formulations. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation variants or unified global recipes offer superior cost efficiency.
Market Dynamics
The EU Green Deal's tightening disclosure mandates are forcing reformulation investments across European dessert manufacturing, while spray-drying capacity expansion in Asia is redrawing feedstock procurement geography.
Growth Catalysts
- Clean-label mandates:The EU Green Deal and EFSA disclosure requirements are accelerating demand for bio-based emulsifiers in German and French premium dessert clusters.
- Plant-based dairy substitution:Industrial bakeries are expanding aerating agent volumes to replicate mouthfeel in vegan whipped toppings without hydrogenated fats.
- Dry-mix dessert proliferation:Powdered whipping agent configurations are capturing share as at-home baking brands eliminate mechanical equipment requirements for consumers.
Market Restraints
- Palm oil price volatility:Emulsifier feedstock costs fluctuate with Malaysian and Indonesian export policy shifts, compressing margin pools for surfactant-based formulations.
- REACH compliance burden:ECHA substance evaluation timelines extend 18-24 months for novel bio-based emulsifiers, delaying European market entry.
- Mechanical aeration legacy:Artisan bakeries in Southern Europe retain capital investment in traditional whipping equipment, slowing powder adoption.
Strategic Opportunities
- SAMR compliance arbitrage:China's stricter GB labeling standards favor domestic spray-dried intermediate producers with established regulatory pathways.
- Silicone aerating convergence:Hybrid hydrocolloid-silicone formulations are opening specialty dessert applications requiring thermal stability above 80°C.
- Direct-to-manufacturer channels:Bakery chains are consolidating supplier relationships, bypassing traditional ingredient distributors for customized stabilizer blends.
Industry Challenges
- Formulation chemist scarcity:Industrial bakeries struggle to recruit specialists capable of optimizing overrun values across varying fat-phase compositions.
- Dual-certification timelines:Simultaneous FDA GRAS and EFSA novel food approvals require parallel toxicology studies, doubling regulatory spend.
- Legacy dry-mix integration:Retrofitting spray-dried whipping agents into existing dessert powder production lines demands line-specific particle size calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Whipping Agents Market |
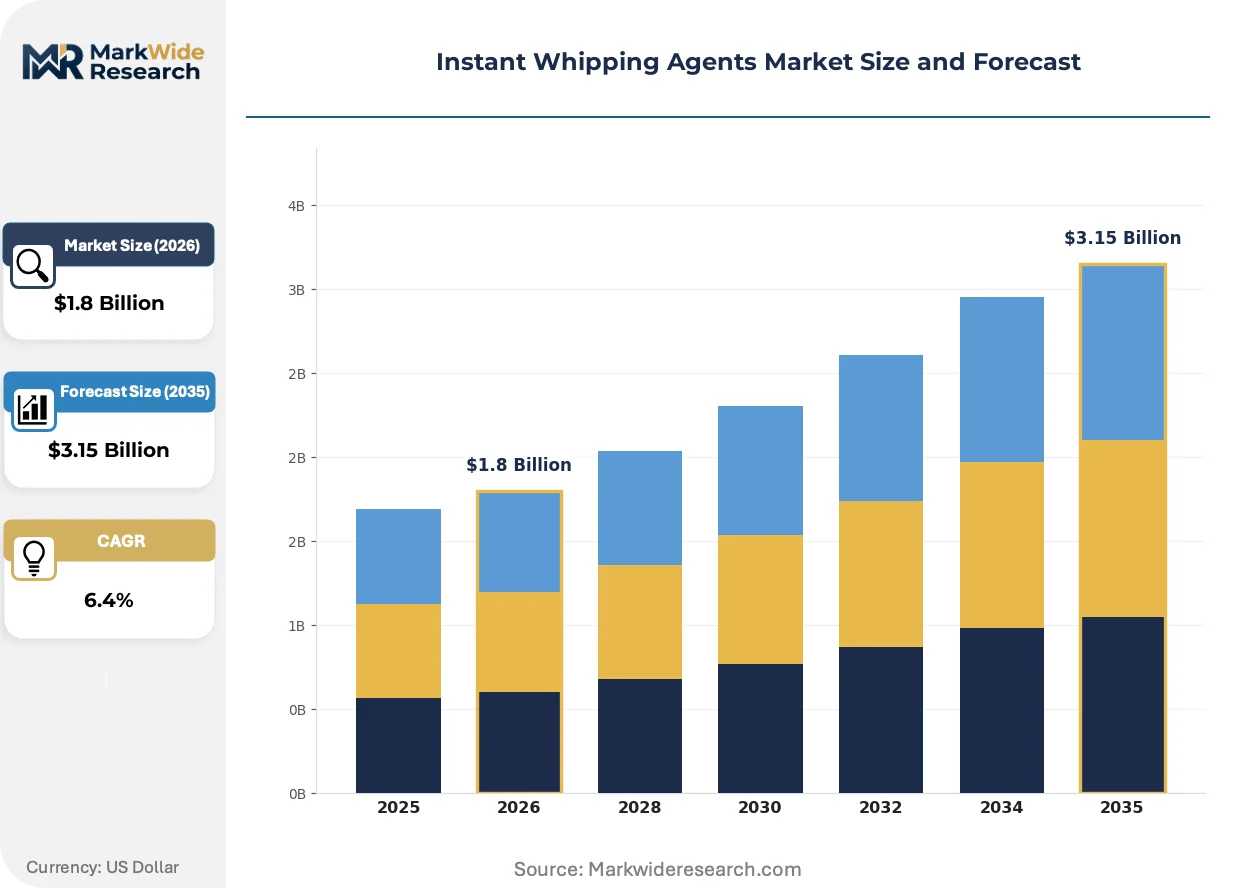
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerating Agents, Stabilizers, Emulsifiers, Foaming Agents Application: Desserts, Bakery Products, Dairy Products, Sauces End User: Food Manufacturers, Restaurants, Bakeries, Home Cooks Form: Powdered, Liquid, Granular, Paste |
| Companies Covered | Wacker Chemie AG, Meggle Foods, BASF, Ingredion Inc, Kerry Group, Cargill, Tate & Lyle, Arla Foods, Avril Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Whipping Agents Market Emerging Trajectories
Spray-drying technology advances and regulatory disclosure tightening are converging to reshape ingredient sourcing strategies, while buyer consolidation is rewriting distribution economics.
Enzymatically modified lecithin is collapsing the cost-performance gap between synthetic and natural emulsifiers in high-overrun dessert applications. Industrial bakeries in the Netherlands and Belgium are adopting these bio-catalyzed alternatives at scale. The technology is collapsing premium pricing for conventional hydrocolloid-stabilized foams by 30-40% in standardized cake mixes.
REACH authorization requirements for persistent organic pollutants are tightening impurity thresholds in glycerol-based emulsifiers. ECHA's 2024 updated guidance documents now mandate sub-ppm detection limits for certain process contaminants. European dessert manufacturers are responding by qualifying alternate feedstock suppliers and accelerating internal analytical capability investments.
Bakery chain procurement teams are consolidating annual whipping agent contracts from twelve-plus suppliers to three-to-four strategic partners. This concentration is displacing spot-market purchasing and distributor-mediated relationships. The shift is most visible in Germany, where Rewe and Aldi Süd have implemented direct sourcing programs for private-label dessert ingredients.
Instant Whipping Agents Market Segmentation
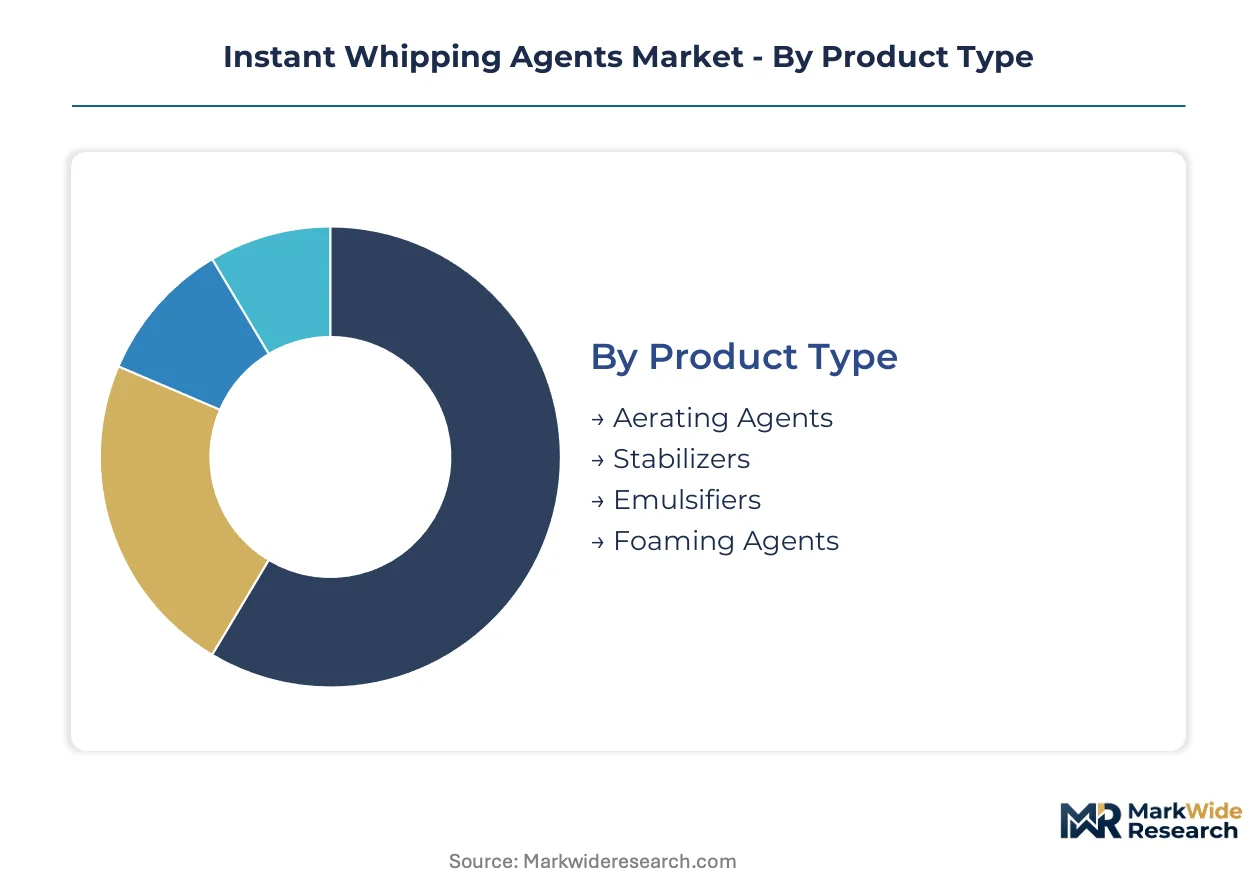
Instant whipping agents serve divergent performance requirements across dessert manufacturing, industrial baking, and foodservice channels. Each segment demands distinct overrun characteristics, thermal stability profiles, and dispersion kinetics that shape procurement decisions.
Product Type:
Mature emulsifier formulations anchor volume consumption while aerating agents emerge as the technology frontier for high-overrun applications.
- Emulsifiers:Glycerol-based and lecithin-derived surfactants stabilize fat-water interfaces in premium dessert foams. German and French industrial bakeries concentrate procurement here for dual-functionality in mouthfeel and shelf stability.
- Aerating Agents:Silicone-based and protein-hydrocolloid hybrid powders entrap air at overrun values exceeding 120% without mechanical whipping. Dry-mix dessert brands in Belgium and the Netherlands are expanding volumes fastest for at-home convenience positioning.
- Stabilizers:Xanthan and carrageenan systems prevent syneresis in plant-based whipped toppings.
- Foaming Agents:Specialized surfactant blends for high-temperature dessert applications requiring thermal stability above 80°C.
Emulsifiers handle the majority of throughput; aerating agents are climbing the fastest on share.
Application:
Volume concentrates in established dessert manufacturing while dairy substitution drives structural momentum in adjacent categories.
- Desserts:Mousse, meringue, and instant cream applications dominate procurement volumes across European premium manufacturing clusters. EFSA disclosure requirements under the EU Green Deal are accelerating reformulation toward bio-based stabilizer systems in German production facilities.
- Dairy Products:Plant-based whipped topping substitution is expanding aerating agent demand as industrial bakeries replicate hydrogenated fat mouthfeel. Kerry Group and BASF are competing most intensely for contract supply here.
- Bakery Products:Cake mixes and cream fillings require consistent overrun across batch-scale production.
- Sauces:Aerated emulsion systems for specialty condiments represent niche but high-margin demand.
Desserts command the deepest revenue pools; dairy products show the steepest expansion trajectory.
End User:
Procurement patterns diverge between consolidated food manufacturing and fragmented foodservice channels.
- Food Manufacturers:Industrial-scale dessert and bakery producers in Germany, France, and Belgium consolidate annual contracts with three-to-four strategic suppliers. Direct sourcing programs at Rewe and Aldi Süd are displacing traditional distributor relationships.
- Bakeries:Artisan operations in Southern Europe retain mechanical whipping equipment, slowing powder adoption despite convenience advantages.
- Restaurants:Foodservice operators prioritize liquid and paste formats for speed of execution.
- Home Cooks:Dry-mix brands are eliminating equipment requirements for consumers, expanding powdered format accessibility.
Food manufacturers generate the dominant procurement volumes; home cooks are gaining share fastest as at-home baking brands proliferate.
Form:
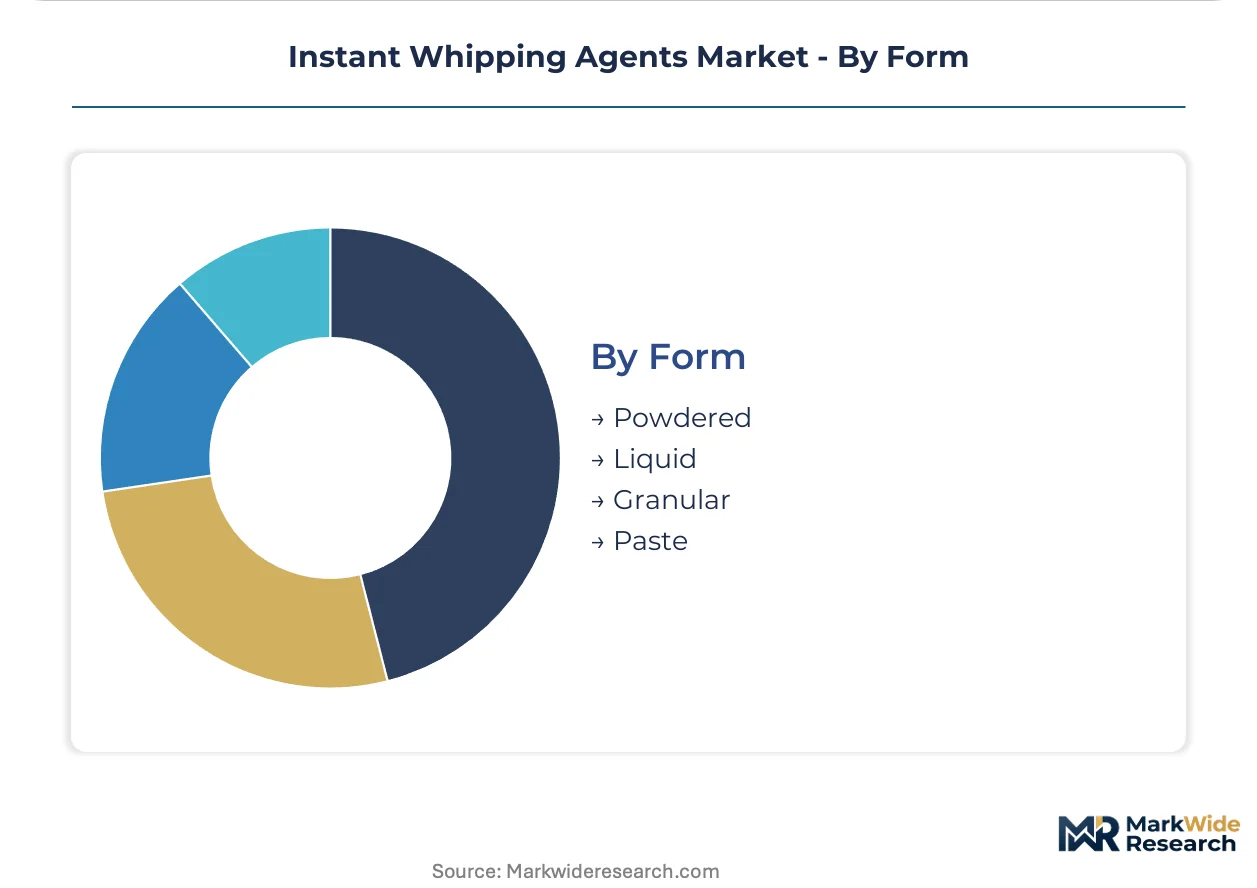
Physical configuration determines distribution economics and line integration requirements across manufacturing scales.
- Powdered:Spray-dried intermediates dominate industrial procurement for extended shelf life and precise dosing. China's domestic producers are expanding capacity fastest, redrawing feedstock procurement geography for European formulators.
- Liquid:Ready-to-use emulsions serve foodservice and small-batch bakery operations requiring minimal processing steps.
- Granular:Intermediate dispersion kinetics for specialty dessert applications.
- Paste:High-concentration formats for premium artisan bakery segments.
Powdered forms absorb the majority of manufacturing throughput; liquid formats are expanding most quickly in foodservice channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spray-dried intermediate production concentrates in China while formulation and application development cluster in Germany and France. Procurement geography is fragmenting as domestic Asian capacity expands and European manufacturers qualify alternate feedstock suppliers under tightening disclosure mandates.
Germany
Premium dessert manufacturing clusters in Bavaria and North Rhine-Westphalia drive concentrated demand for dual-function emulsifiers. The EU Green Deal's EFSA disclosure requirements are accelerating reformulation timelines for industrial bakeries supplying Rewe and Aldi Süd private-label programs. Cologne-based procurement teams have consolidated supplier relationships from twelve-plus vendors to three-to-four strategic partners.
China
Domestic producers are expanding spray-drying capacity for whipping agent intermediates, redrawing feedstock procurement geography for European formulators. SAMR enforces stricter GB standards on food additive labeling, raising compliance costs for imported formulations. Yangtze River Delta manufacturing hubs are capturing share from traditional European intermediate suppliers.
France
Industrial dessert producers in Île-de-France and Auvergne-Rhône-Alpes operate at scale, concentrating procurement volumes for high-overrun applications. REACH compliance obligations for novel bio-based emulsifiers extend ECHA substance evaluation timelines 18-24 months. Lyon-based manufacturing facilities are qualifying enzymatically modified lecithin alternatives to collapse cost-performance gaps.
United States
Industrial bakeries and dry-mix dessert brands drive aerating agent demand for plant-based whipped topping substitution. The FDA's GRAS notification pathway shapes ingredient approval timelines for domestic manufacturers. Midwest production facilities in Illinois and Ohio are retrofitting spray-dried whipping agents into existing powder production lines.
Belgium
Netherlands-adjacent industrial baking clusters in Flanders adopt enzymatically modified lecithin at scale for standardized cake mix applications. ECHA's 2024 updated guidance documents mandate sub-ppm detection limits for certain process contaminants in glycerol-based emulsifiers. Antwerp-area manufacturers are accelerating internal analytical capability investments to meet impurity thresholds.
Instant Whipping Agents Market Vendor Landscape
Specialty chemical conglomerates and diversified ingredient suppliers split the market between technology-led and scale-led competitive vectors. The vendor base organizes around three strategic archetypes: silicone-aerating technology specialists, backward-integrated emulsifier producers, and customized stabilizer blend formulators. Consolidation is accelerating through direct-to-manufacturer channel bypass and spray-drying capacity expansion in Asia.
Among European chemical conglomerates, Wacker Chemie AG and BASF occupy positions at opposite ends of the technology spectrum. Wacker exemplifies the specialty silicone-aerating archetype with concentrated European dessert applications. BASF anchors the backward-integrated emulsifier segment through captive feedstock control. Kerry Group sits within the customized stabilizer blend tier, competing for industrial bakery contracts. Meggle Foods and Ingredion represent regional European and North American ingredient supplier archetypes respectively.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Meggle Foods |
| BASF |
| Ingredion Inc |
| Kerry Group |
| Cargill |
| Tate & Lyle |
| Arla Foods |
| Avril Group |
| Others |
Supply Flow & Price Mechanics
Palm oil price volatility in Malaysian and Indonesian export markets determines both margin compression in surfactant-based formulations and the geographic diversification of emulsifier feedstock sourcing across European formulators. This commodity exposure creates pricing tier spreads between backward-integrated producers and spot-market dependent competitors while accelerating supply chain restructuring toward enzymatically modified lecithin alternatives.
Pricing Analysis
REACH authorization requirements dictate the pricing tier structure across European dessert manufacturing, separating ECHA-compliant bio-based emulsifiers from legacy glycerol-based formulations on certification grade and impurity threshold compliance. Volume scale and vertical integration status differentiate contract pricing for industrial bakeries in Germany and France, with spot-market purchasers facing margin compression from palm oil feedstock volatility. Pricing pressure stems from enzymatically modified lecithin collapsing premium spreads by 30-40% in standardized applications. Small-batch artisan bakeries in Southern Europe exhibit highest price sensitivity due to mechanical aeration legacy equipment, while consolidated food manufacturers leverage direct sourcing programs for cost stability.
Supply Chain Analysis
Export-control restrictions on silicone-based aerating technology limit technology transfer to Chinese domestic producers, concentrating high-performance specialty formulation capacity in Germany while spray-dried intermediate production expands in the Yangtze River Delta. Feedstock dependencies center on Malaysian and Indonesian palm oil derivatives, lecithin from South American soy processing, and hydrocolloid gums from Southeast Asian seaweed harvesting. Single-source vulnerability runs through concentrated spray-drying equipment suppliers for powder configuration capacity. Distribution runs through direct-to-manufacturer channels consolidating at Rewe and Aldi Süd procurement teams, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in clean-label reformulation niches created by EU Green Deal disclosure mandates tightening across German and French premium dessert clusters. This regulatory-driven demand shift generates specialized procurement requirements that favor agile formulators over commodity-scale suppliers.
For Market Incumbents: Pre-empt enzymatically modified lecithin substitution threats by accelerating backward integration into captive feedstock production and securing ECHA pre-registration for novel bio-based emulsifiers before evaluation timelines extend further. BASF's existing captive supply infrastructure provides a template for margin defense against 30-40% cost-performance compression in standardized cake mix applications. Certification investment in dual FDA GRAS and EFSA novel food pathways creates switching costs for consolidated bakery chain contracts.
For New Entrants and Emerging Players: SAMR compliance arbitrage in China's domestic spray-dried intermediate market represents the most penetrable entry point, with established GB labeling pathways displacing imported formulation costs for European dessert manufacturers seeking alternate feedstock suppliers. Hybrid hydrocolloid-silicone thermal stability formulations above 80°C offer specialty dessert application niches underserved by Wacker Chemie AG's concentrated European position. Go-to-market execution through direct technical service partnerships with midsize industrial bakeries bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: EU Green Deal implementation milestones through EFSA disclosure requirement phases reshape the acquisition landscape toward bio-based emulsifier specialists with qualified regulatory pathways and spray-drying capacity in Asian manufacturing hubs. Five-to-ten year viability favors targets combining enzymatic modification capabilities with established bakery chain direct sourcing relationships. The signal to watch is ECHA substance evaluation timeline acceleration for novel bio-based entrants, which would compress first-mover advantage windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emulsifier Feedstocks | BASF's captive supply model anchors margin pools against palm oil volatility. |
| Spray-Drying Capacity Expansion | China's Yangtze River Delta hubs redraw procurement geography for European formulators. |
| Dual Certification Investment | Parallel FDA GRAS and EFSA pathways extend switching costs for bakery chain contracts. |
| Direct-to-Manufacturer Channel Development | Rewe and Aldi Süd procurement consolidation displaces traditional distributor economics. |
| Enzymatic Modification Technology Adoption | Netherlands and Belgium industrial bakeries collapse synthetic-natural emulsifier cost gaps. |
Methodological Framework
Operator-level perspectives from dessert manufacturing procurement directors, spray-drying plant managers, emulsifier R&D technical leads, and bakery chain category buyers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through ECHA guidance documents, FDA GRAS notification filings, SAMR GB standard updates, and trade data on Malaysian and Indonesian palm oil export flows. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across product configurations.
Scenario-bracketing framed demand projections across the analysis window through sensitivity testing of regulatory implementation timelines and feedstock price volatility bands. Segmentation dimensions modeled include product type, application category, end-user channel, and physical form configuration, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from weighted average growth contributions across these segments, incorporating spray-drying capacity expansion rates and clean-label reformulation penetration curves as industry-specific inputs.
Practitioners should monitor ECHA substance evaluation acceleration, SAMR enforcement intensity on imported formulations, and enzymatically modified lecithin cost-performance convergence for early signals requiring forecast revision. Material shifts in EU Green Deal implementation pace or Malaysian export policy disruption would require updated calibration of pricing tier spreads and supply chain geography assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Italy Anti-Caking Market