
 Kaempferol Market | 2026-2036
Kaempferol Market Size, Share, and Industry Trends Forecast 2026-2036
Kaempferol Market Analysis
Modular bundling of kaempferol with quercetin and resveratrol into stacked antioxidant formulations is restructuring buyer choice across nutraceutical channels. Aktin Chemicals Inc. leverages its botanical extraction infrastructure to supply standardized flavonoid complexes. Indena S.p.A. specializes in phytosome delivery systems that improve kaempferol bioavailability. Foodchem International Corporation anchors bulk powder distribution into Asian functional food processors.
Kaempferol is a flavonol aglycone with the molecular formula C15H10O6, typically extracted from Sophora japonica buds, tea leaves, or broccoli through solvent extraction followed by chromatographic purification; manufacturers target purity grades from 50% to 98% for pharmaceutical and nutraceutical applications. Powder formulations dominate current volume due to lower unit costs and broader formulation flexibility, while capsule configurations capture expanding direct-to-consumer nutraceutical demand. Antioxidant applications lead the application matrix, though anti-inflammatory and cardiovascular health segments attract accelerated R&D investment from functional ingredient developers.
REACH registration requirements govern kaempferol import and formulation within Europe, while FDA 21 CFR Part 111 cGMP rules shape U.S. dietary supplement manufacturing standards. EFSA novel food opinions and FDA New Dietary Ingredient notifications create divergent compliance pathways that influence regional market access strategies. Stakeholders must monitor evolving botanical drug guidance from FDA and pending EU harmonization of flavonoid health claims to align product positioning with enforceable regulatory thresholds.
Market Dynamics
Modular bundling of kaempferol with complementary flavonoids into standardized supplement stacks is restructuring procurement patterns across nutraceutical channels, forcing extractors to reconfigure purification lines for multi-compound output.
Growth Catalysts
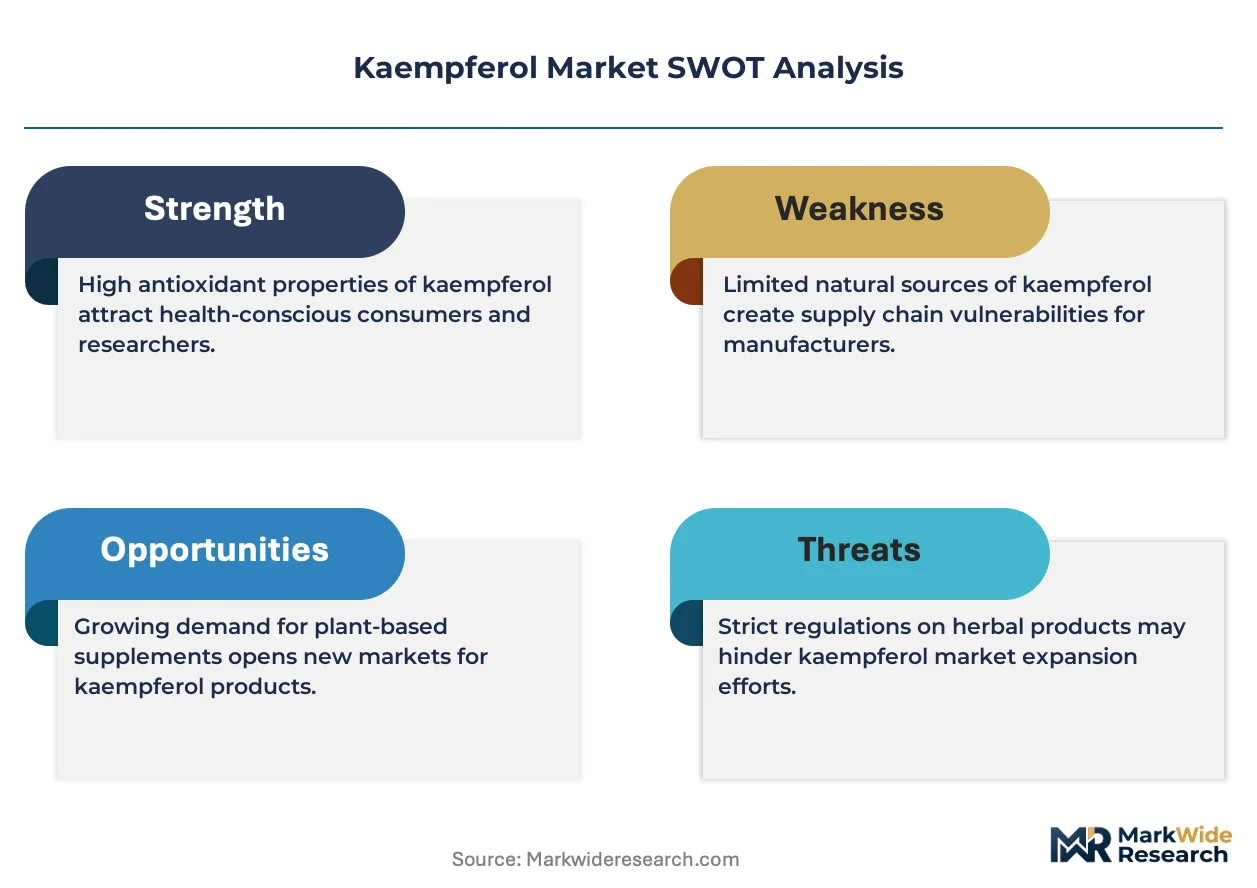
- EFSA Novel Food Guidance:Clearer approval pathways for botanical extracts accelerate product launches across European functional food categories, reducing regulatory uncertainty for formulators.
- Phytosome Delivery Systems:Lipid-based encapsulation technologies improve kaempferol bioavailability by 8-10x versus standard powder, expanding therapeutic dosing applications.
- Germany:REACH-registered supply chains from botanical extract processors anchor pharmaceutical-grade production capacity serving cosmeceutical and drug developers.
Market Restraints
- Sophora Japonica Supply Concentration:Over 60% of raw bud sourcing concentrates in Chinese agricultural zones, exposing processors to climate volatility and export licensing friction.
- Chromatographic Purification Costs:High-purity grades (95%+) require preparative HPLC systems with solvent recovery infrastructure, elevating capex thresholds for new entrants.
- Quercetin Substitution:Lower-cost flavonol alternatives with similar antioxidant profiles capture price-sensitive nutraceutical formulations, compressing kaempferol volume in economy-tier stacks.
Strategic Opportunities
- Anti-Inflammatory Therapeutics:Preclinical pipelines targeting NF-κB pathway modulation open prescription drug applications beyond current nutraceutical positioning.
- Direct-to-Consumer Capsules:Subscription wellness platforms bypass traditional wholesale distribution, capturing margin previously allocated to intermediaries.
- Japan:PMDA botanical drug guidelines create a regulatory pathway for standardized flavonoid complexes in functional medicine clinics.
Industry Challenges
- Analytical Chemist Scarcity:Flavonoid quantification via HPLC-MS requires specialized metabolomics expertise that outpaces current vocational training output.
- cGMP Certification Timelines:FDA 21 CFR Part 111 facility audits average 14-18 months for botanical extractors, delaying market entry for new production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kaempferol Market |
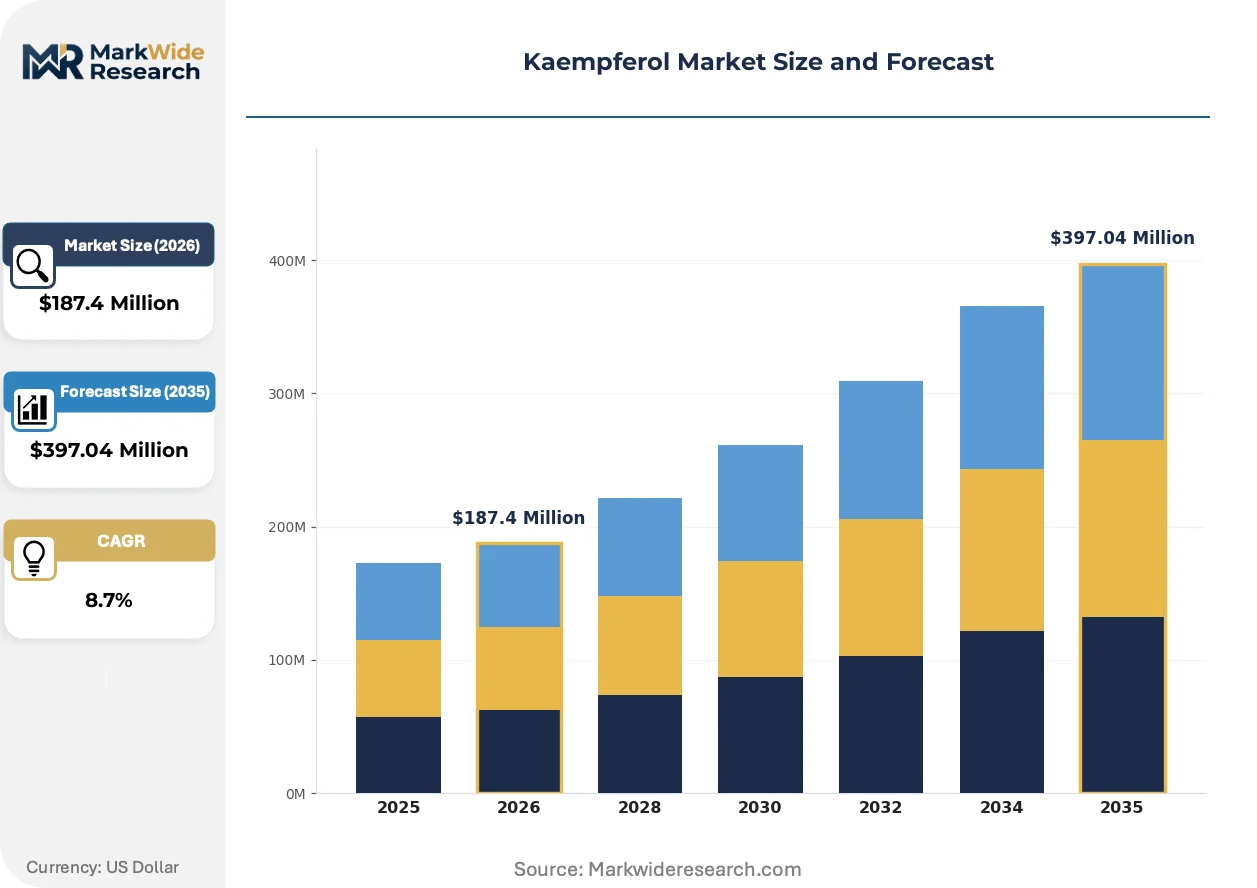
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tablet End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Food & Beverages Application: Antioxidant, Anti-inflammatory, Cardiovascular Health, Cancer Treatment Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Aktin Chemicals Inc., FUJIFILM Wako Chemicals U.S.A Corporation, Shaanxi NHK Technology, Risun Bio-Tech, TCI Chemicals (India) Pvt. Ltd., Spectrum Chemical Mfg. Corp., INDOFINE Chemical Company, Inc., Indena S.p.A., Foodchem International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kaempferol Market Emerging Trajectories
Delivery technology convergence and regulatory clarity are compressing development cycles for bioavailable kaempferol formulations, while procurement centralization among contract manufacturers reconfigures traditional supply relationships.
Liposomal encapsulation systems are absorbing investment from mid-scale nutraceutical compounders seeking differentiation in saturated antioxidant markets. Functional beverage developers in South Korea and California adopt these formats for ready-to-drink wellness lines. The technology is absorbing margin pressure from commodity powder pricing by commanding 3-4x unit premiums in premium channels.
REACH registration harmonization across EU member states is consolidating supplier qualification requirements for botanical extracts. German and Dutch importers now demand full substance dossiers from Asian extractors, filtering out non-compliant traders. Pharmaceutical-grade applications face the steepest compliance escalation, with cosmeceutical formulators absorbing documentation costs through longer-term supply contracts.
Buyer concentration among contract manufacturers is displacing fragmented purchasing from small supplement brands. Tier-one formulators in the United States and Germany now specify flavonoid complexes rather than single-compound inputs, consolidating order volumes with integrated extractors. This shift concentrates negotiation leverage among processors with captive purification and phytosome capabilities.
Kaempferol Market Segmentation
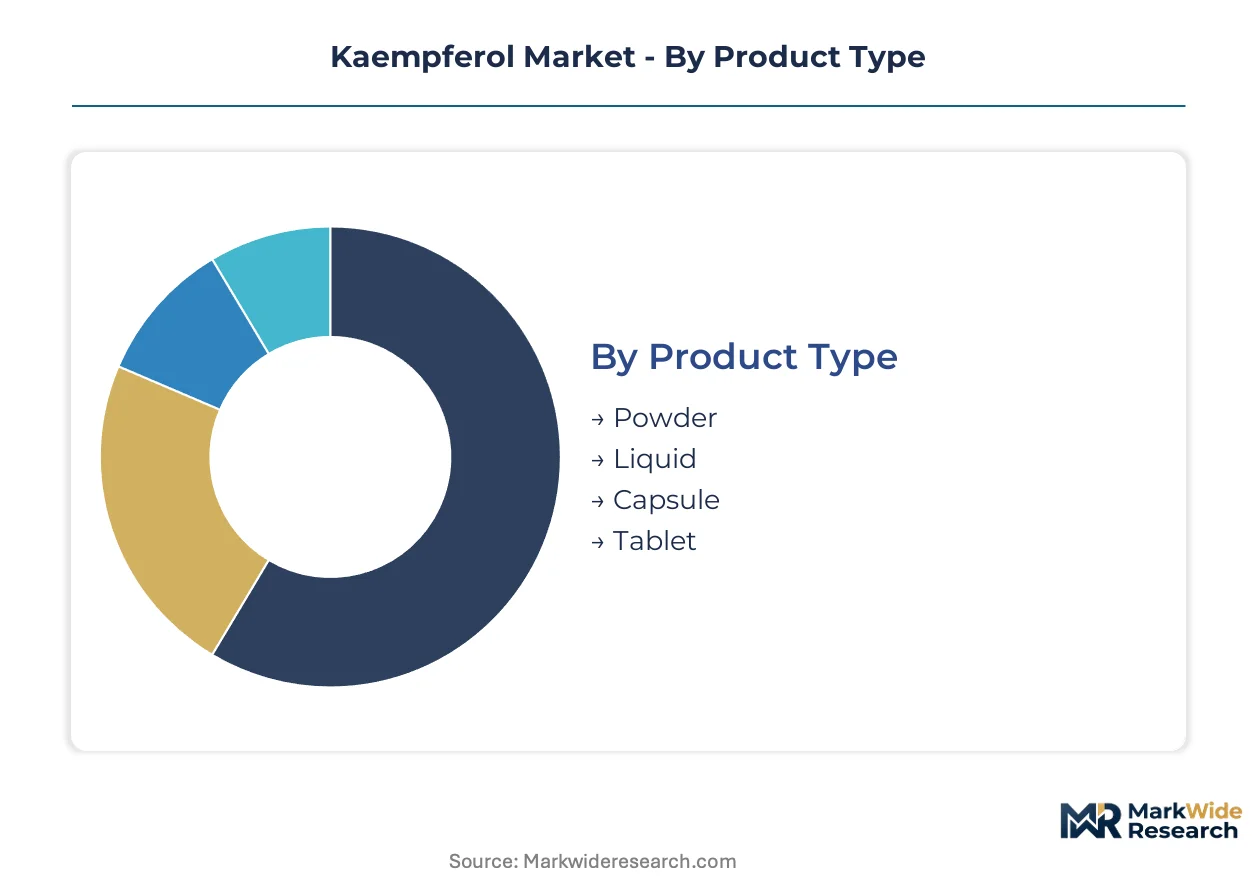
Kaempferol market segmentation reflects divergent regulatory burdens across pharmaceutical, nutraceutical, and food applications. Formulators select product formats and distribution channels based on bioavailability requirements, cGMP certification status, and target jurisdiction approval pathways.
Product Type:
Certification requirements vary sharply by format: powder grades for bulk nutraceutical compounding demand FDA 21 CFR Part 111 cGMP documentation, while finished capsules for direct-to-consumer channels require NDI notifications and stability testing protocols.
- Powder:Bulk formulations dominate pharmaceutical and nutraceutical B2B procurement due to formulation flexibility and lower per-unit costs. REACH-registered German extractors supply standardized 50-98% purity grades to contract manufacturers under long-term supply agreements.
- Capsule:Pre-dosed configurations capture expanding direct-to-consumer demand through subscription wellness platforms. Phytosome delivery systems from Indena S.p.A. and liposomal encapsulation technologies command 3-4x premiums over standard powder in premium channels.
- Liquid:Functional beverage applications in South Korea and California drive demand for ready-to-drink formats with enhanced solubility profiles.
- Tablet:Compressed forms serve pharmacy-distributed antioxidant supplements requiring precise dosing and extended shelf stability.
Leading the category by volume: Powder. Growing fastest: Capsule.
End User:
Cost stratification separates pharmaceutical-grade specifications from economy-tier nutraceutical sourcing, with purity thresholds and analytical documentation driving 5-10x price differentials between segments.
- Pharmaceuticals:Prescription drug developers target kaempferol for NF-κB pathway modulation in anti-inflammatory therapeutics. Preclinical pipelines demand 98%+ purity with full impurity profiling and ICH Q3D elemental impurity compliance.
- Nutraceuticals:Dietary supplement formulators bundle kaempferol with quercetin and resveratrol into modular antioxidant stacks. EFSA novel food guidance and FDA dietary supplement labeling rules shape regional product launch strategies.
- Cosmetics:Cosmeceutical applications leverage kaempferol's photoprotective properties in topical formulations. German botanical extract processors serve this segment under REACH-registered supply chains with cosmetic safety assessments.
- Food & Beverages:Functional food developers in Asia incorporate kaempferol into fortified beverages and health-positioned snacks. FSSAI approvals govern Indian market access, while SAMR registration requirements apply in China.
Pharmaceuticals command the steepest purity premiums. Nutraceuticals expand most quickly across direct-to-consumer channels.
Application:
Volume concentration aligns with established clinical evidence bases, while R&D investment flows toward therapeutic indications with stronger mechanistic validation.
- Antioxidant:The most mature application segment leverages kaempferol's free radical scavenging capacity in cellular protection formulations. Standardized extracts from Sophora japonica dominate supply, though climate volatility in Chinese growing regions creates procurement risk.
- Anti-inflammatory:Preclinical research targeting NF-κB and COX-2 pathway inhibition attracts pharmaceutical investment. Lipid-based delivery systems improve bioavailability 8-10x versus standard powder, enabling therapeutic dosing.
- Cardiovascular Health:Endothelial function and lipid metabolism applications drive formulation development for aging populations in Japan and Germany.
- Cancer Treatment:Adjunctive oncology applications remain investigational, with clinical trials examining kaempferol's pro-apoptotic effects in combination protocols.
Antioxidant leads by volume. Anti-inflammatory gains share fastest through pharmaceutical pipeline advancement.
Distribution Channel:
Margin capture varies by channel control: vertically integrated brands retain 40-50% more margin through direct online distribution versus wholesale pharmacy networks.
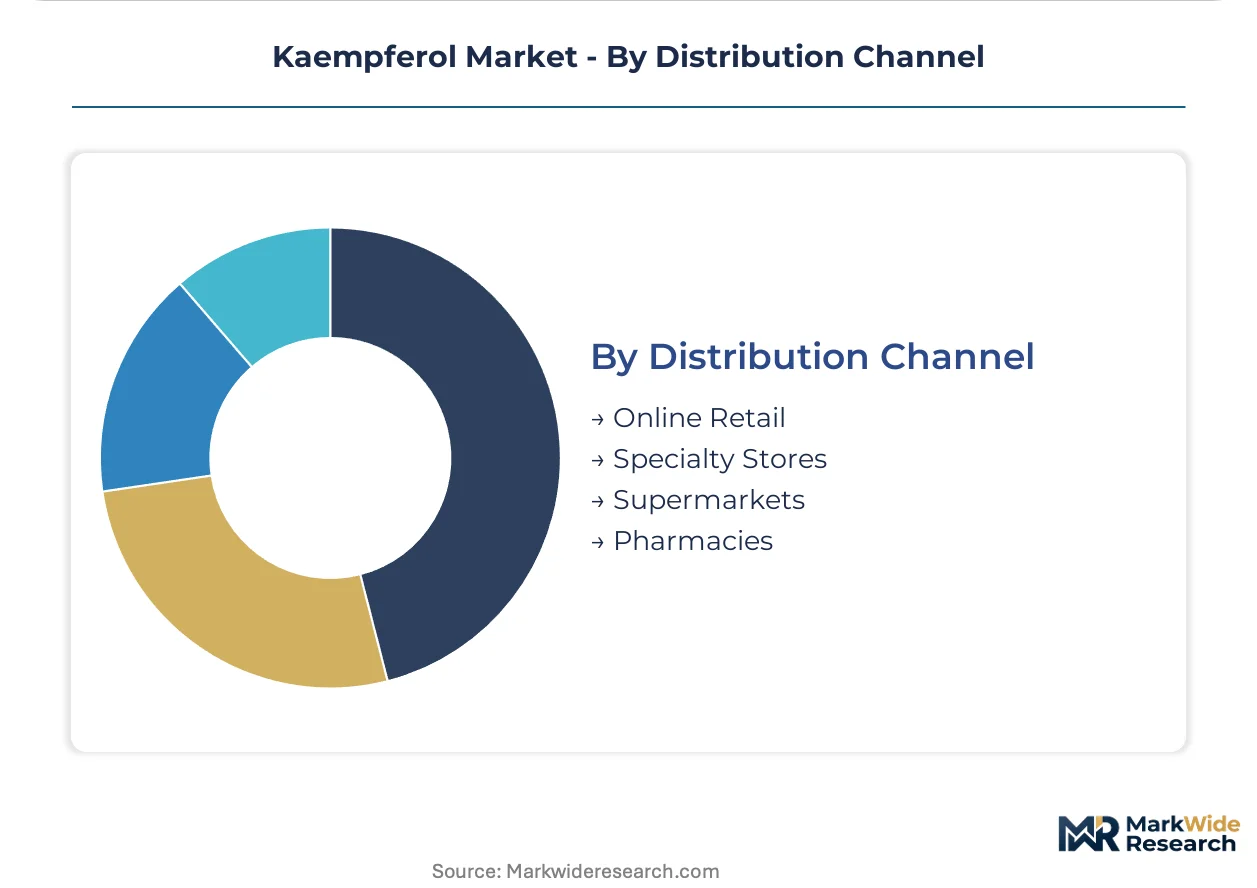
- Online Retail:Subscription wellness platforms and direct-to-consumer brands bypass traditional distribution markups. Capsule and tablet formats dominate this channel with automated replenishment and personalized dosing protocols.
- Pharmacies:Professional recommendation channels serve pharmaceutical-grade and high-purity nutraceutical products. Pharmacist counseling requirements in Germany and France support premium positioning.
- Specialty Stores:Health food retailers and functional medicine clinics curate flavonoid complexes for educated consumers. Staff training on bioavailability differentiates phytosome formulations from commodity powders.
- Supermarkets:Mass-market functional food and beverage placement requires price-competitive positioning. Quercetin substitution pressure is strongest in this channel.
Online retail leads volume growth. Pharmacies sustain the highest average transaction values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material harvesting concentrates in Chinese agricultural zones, while formulation and pharmaceutical-grade processing clusters in Germany and the United States. This geographic split shapes trade flows, regulatory compliance costs, and final product pricing across consuming markets.
Germany
REACH-registered botanical extract processors in Bavaria and North Rhine-Westphalia serve pharmaceutical and cosmeceutical clients with standardized flavonoid complexes. ECHA substance dossier requirements filter supplier networks, consolidating procurement among compliant traders. The Cologne-Düsseldorf corridor anchors chromatographic purification capacity for 98%+ purity grades.
United States
FDA 21 CFR Part 111 cGMP-certified contract manufacturers in New Jersey and California drive demand for bulk powder inputs. New Dietary Ingredient notification pathways shape product launch timelines for direct-to-consumer capsule formats. Greater Boston hosts preclinical research pipelines examining kaempferol's NF-κB modulation for anti-inflammatory therapeutics.
China
Sophora japonica bud harvesting concentrates in Shandong and Henan provinces, supplying over sixty percent of global raw material. SAMR registration requirements for functional food applications create divergent compliance costs versus export markets. Yangtze River Delta extractors maintain solvent recovery infrastructure for mid-purity grades.
Japan
PMDA botanical drug guidelines enable standardized flavonoid complexes in functional medicine clinics. METI-funded research programs examine bioavailability enhancement for aging-population cardiovascular applications. Osaka-based formulators integrate phytosome delivery systems into subscription wellness platforms.
India
FSSAI approvals govern functional food and nutraceutical market access for imported extracts. CDSCO pharmaceutical regulations create parallel pathways for prescription-grade applications. Gujarat and Maharashtra host contract manufacturing organizations serving export markets with cost-compounded formulations.
Kaempferol Market Vendor Landscape
The competitive structure tilts toward specialized botanical extractors with captive purification infrastructure. Tier-one formulators in Germany and the United States consolidate order volumes with integrated suppliers possessing phytosome capabilities. Three archetypes dominate: REACH-registered European processors, cGMP-certified North American compounders, and scale-driven Asian bulk extractors. Strategic moves center on backward integration into raw material sourcing and technology licensing for lipid-based delivery systems.
Among the named suppliers, Aktin Chemicals Inc. exemplifies the botanical extraction archetype with standardized flavonoid output, while Indena S.p.A. occupies a position within the delivery-technology specialist tier. Foodchem International Corporation represents the bulk distribution archetype serving Asian functional food processors. These three anchors illustrate the geographic and functional segmentation governing procurement relationships.
| Leading Market Players |
|---|
| Aktin Chemicals Inc. |
| FUJIFILM Wako Chemicals U.S.A Corporation |
| Shaanxi NHK Technology |
| Risun Bio-Tech |
| TCI Chemicals (India) Pvt. Ltd. |
| Spectrum Chemical Mfg. Corp. |
| INDOFINE Chemical Company, Inc. |
| Indena S.p.A. |
| Foodchem International Corporation |
| Others |
Supply Flow & Price Mechanics
Purity-grade divergence between pharmaceutical specifications and nutraceutical commodity grades manifests in parallel supply chain configurations: REACH-registered German processors command 5-10x premiums through captive chromatographic infrastructure, while Chinese bulk extractors serve price-sensitive Asian functional food markets via solvent-based mid-purity output.
Pricing Analysis
Cost-down pressure on standard powder grades accelerates because quercetin substitution captures economy-tier nutraceutical formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and bioavailability technology. Pricing pressure stems from commodity flavonol competition in mass-market channels. Direct-to-consumer capsule buyers show lowest price sensitivity; supermarket functional food purchasers exhibit highest.
Supply Chain Analysis
Specialized analytical chemist scarcity in German and North American manufacturing geographies constrains chromatographic purification capacity expansion. Raw material harvesting draws from Shandong and Henan provinces in China; pharmaceutical-grade processing clusters in Bavaria and North Rhine-Westphalia. Single-source vulnerability concentrates in Sophora japonica bud supply. Distribution runs through REACH-registered importers and cGMP-certified contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preparative HPLC capacity scarcity props pricing for 98%+ purity grades, constraining pharmaceutical pipeline expansion and preserving margin capture for incumbent processors with solvent recovery infrastructure.
For Market Incumbents: Lock in long-term offtake agreements with Sophora japonica cooperatives in Shandong to hedge climate volatility exposure. Expand phytosome production capacity in Germany before analytical chemist scarcity worsens, securing therapeutic-dosing market positioning against quercetin substitution threats. For New Entrants and Emerging Players: Capture liposomal encapsulation white space in South Korean and Californian functional beverage channels where premium pricing tolerates technology learning curves. Target cosmeceutical formulators in Japan seeking PMDA-compliant botanical drug pathways with localized stability testing capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with integrated extractors possessing captive purification and phytosome capabilities given EFSA novel food guidance acceleration. Monitor CDSCO pharmaceutical regulation harmonization in India as inflection indicator for prescription-grade market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Sophora japonica cooperative agreements in Shandong reduce climate volatility exposure for German processors. |
| Phytosome Delivery System Licensing | Indena S.p.A. technology partnerships enable 8-10x bioavailability premiums in therapeutic dosing applications. |
| REACH Registration Harmonization | Full substance dossiers filter Asian supplier networks, consolidating procurement among compliant Dutch and German importers. |
| Direct-to-Consumer Capsule Launch | Subscription wellness platforms bypass wholesale markups, capturing 40-50% margin retention for vertically integrated brands. |
| cGMP Certification Investment | FDA 21 CFR Part 111 facility audits averaging 14-18 months create defensive moats against fast-follower entrants. |
Methodological Framework
Document review covered FDA 21 CFR Part 111 guidance documents, EFSA novel food opinions, and REACH substance dossiers, complemented by interviews with botanical extraction plant managers, pharmaceutical procurement leads at German cosmeceutical firms, and regulatory affairs directors at Asian functional food processors. Secondary validation drew from customs trade data, SEC filings of listed nutraceutical compounders, and ICH Q3D elemental impurity standards. Bottom-up volume modeling triangulated against top-down market sizing across purity grades and application segments.
Segment-level outputs across product type, end user, application, and distribution channel dimensions were constructed through the projection horizon. CAGRs derived from regression analysis of historical price-volume relationships and forward pipeline tracking of preclinical NF-κB research. Industry-specific forecast inputs incorporated phytosome adoption curves and EFSA approval velocity for stacked flavonoid formulations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Sophora japonica harvest volatility and PMDA botanical drug guideline evolution. Forecasts reflect documented assumptions regarding regulatory pathway timelines and delivery technology penetration rates. Material deviation in Chinese export licensing protocols or FDA NDI notification backlogs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Charcoal-Infused Food Market