
 South Africa Water Enhancer Market | 2026-2036
South Africa Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Water Enhancer Market Analytics
Premium natural additive formulations and commodity-grade flavoring agents is rebalancing as price-sensitive shoppers trade down while affluent buyers demand clean-label credentials. PepsiCo Inc. leverages its bottling partnerships to anchor shelf presence in major supermarkets, while The Coca-Cola Company competes through Coca-Cola Beverages South Africa's localized distribution muscle. Nestle S.A. differentiates via nutritional booster expertise honed across its wellness portfolio.
Water enhancers comprise concentrated liquid or powder additives that dissolve in plain water to deliver flavor, electrolytes, vitamins, or functional compounds, typically containing less than five calories per serving and achieving stability through pH buffering and preservative systems. Their primary commercial purpose is converting commodity bottled or tap water into value-added beverages without carbonation infrastructure. Flavoring agents command the largest revenue pool given repeat purchase frequency, though nutritional boosters capture superior margins as consumers prioritize immunity and protein fortification. Sports nutrition use cases expand fastest among fitness enthusiasts, while everyday consumption segments mature with slower velocity but steadier household penetration.
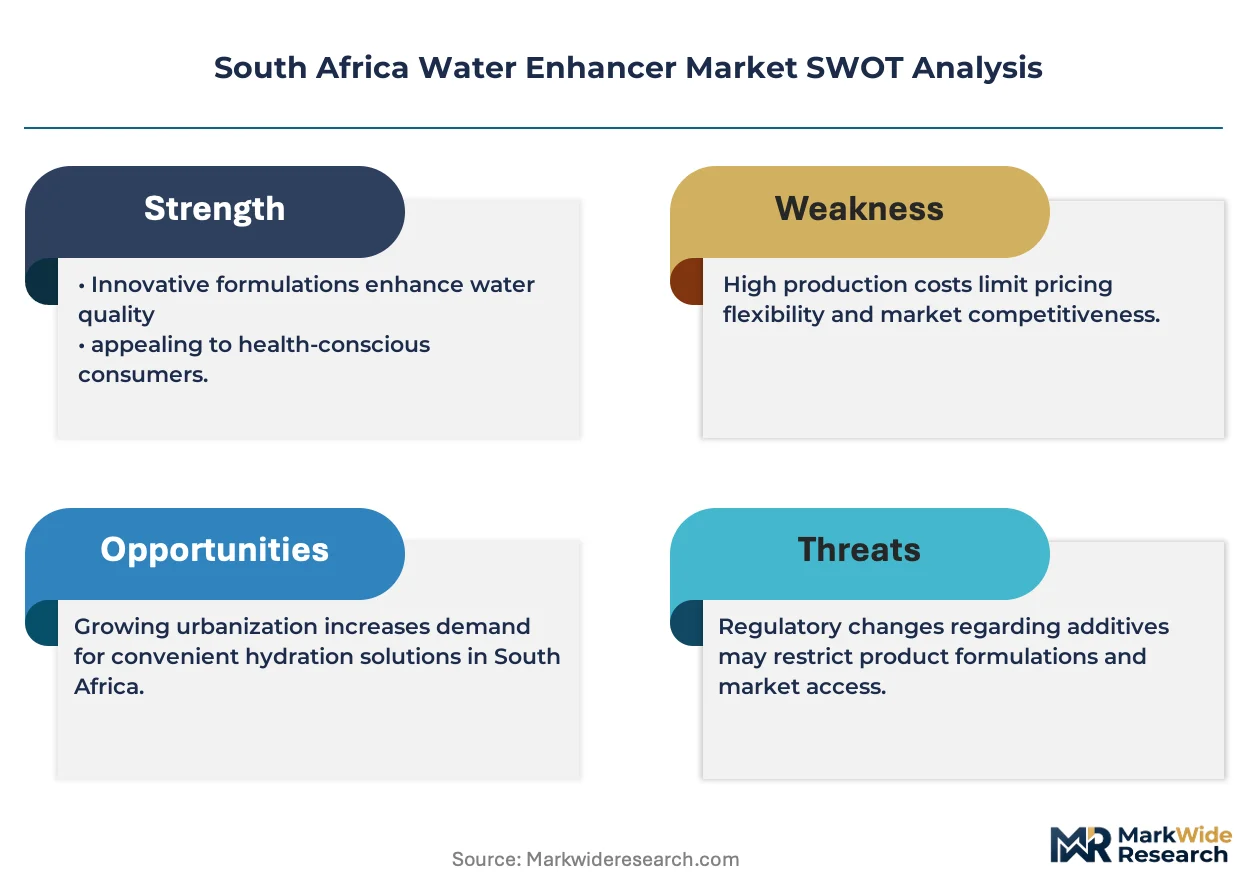
South Africa's Department of Health enforces food additive standards through the Foodstuffs, Cosmetics and Disinfectants Act, while the country's sugar tax under the Health Promotion Levy pressures manufacturers toward reduced-calorie formulations. BIS-aligned import testing for preservative residues shapes market access for international suppliers. Stakeholders must monitor pending amendments to labeling regulations and decide whether to front-run stricter natural claim definitions or absorb reformulation costs reactively.
Market Dynamics
South Africa's Health Promotion Levy on sugary beverages is compressing formulation margins while simultaneously opening white space for zero-calorie natural sweetener systems. Manufacturers face immediate pressure to reformulate without sacrificing sensory performance.
Growth Catalysts
- Health Promotion Levy:South Africa's sugar tax penalizes high-calorie formulations above 4g per 100ml, forcing manufacturers toward stevia and monk fruit extract alternatives that align with clean-label demand.
- Fitness Enthusiast Penetration:Gym culture expansion in Johannesburg and Pretoria corridors drives electrolyte-enhanced water additive uptake among protein-conscious consumers seeking hydration optimization.
- Foodstuffs, Cosmetics and Disinfectants Act:BIS-aligned import testing for preservative residues creates compliance barriers that favor domestic manufacturers with established laboratory relationships.
Market Restraints
- Stevia Supply Concentration:Global stevia leaf processing concentrates in Chinese extraction facilities, exposing South African formulators to yuan-denominated input volatility and shipping lane disruptions.
- Natural Claim Definition Lag:Pending amendments to South Africa's labeling regulations create formulation uncertainty, with natural claim thresholds undefined for enzymatically modified steviol glycosides.
- Tap Water Substitution:Municipal water quality improvements in Cape Town and Durban reduce bottled water dependency, compressing the addressable base for water enhancer conversion.
Strategic Opportunities
- Western Cape Expansion:Cape Town's wellness tourism infrastructure and boutique fitness studio density remain underpenetrated relative to Gauteng, offering first-mover shelf space in premium organic retailers.
- Immune Fortification Positioning:Zinc and vitamin C booster formulations can capture margin premiums as post-pandemic health vigilance persists among suburban household purchasers.
- Direct-to-Subscription Channels:E-commerce fulfillment partnerships with Takealot and Woolworths online platforms bypass traditional supermarket slotting fees for emerging challenger brands.
Industry Challenges
- Flavor Chemist Scarcity:South Africa's tertiary food science programs produce insufficient natural product formulation specialists, forcing manufacturers to recruit from European expatriate pools at premium compensation.
- pH Stability Certification:Shelf-life validation for buffered preservative systems requires 18-24 month accelerated aging protocols, delaying new product launches and tying up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Water Enhancer Market |
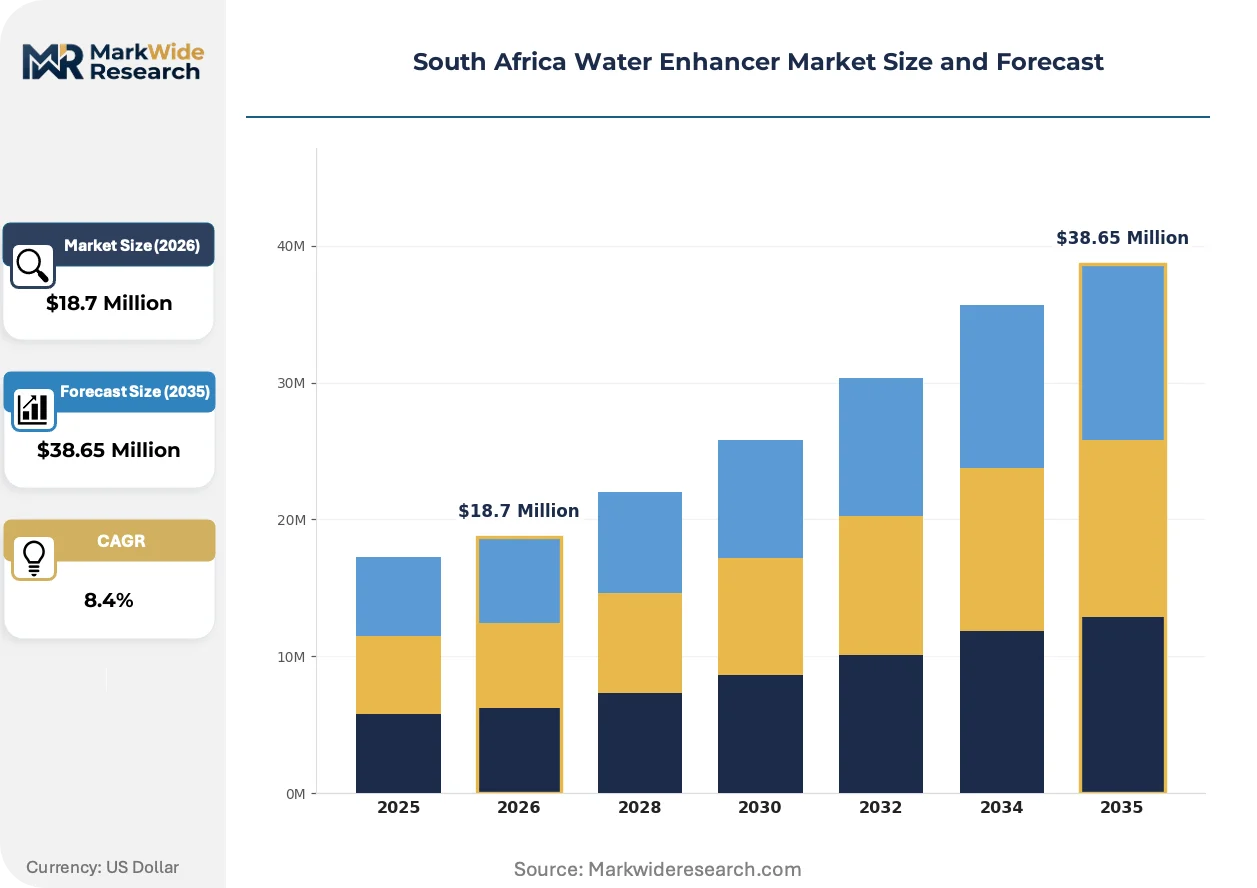
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Electrolyte Enhancers, Nutritional Boosters, Natural Additives Use Case: Sports Nutrition, Hydration Support, Everyday Consumption, Functional Beverages End User: Fitness Enthusiasts, Health-Conscious Consumers, Outdoor Adventurers, General Population Distribution Channel: Online Retailers, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Kraft Heinz Company, Welch Foods Inc., PepsiCo Inc., Continental Mills Inc., True Citrus Co., Keurig Dr Pepper, The Coca-Cola Company, Nestle S.A., Coca-Cola Beverages South Africa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Water Enhancer Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing parallel transformation as natural extract stability meets digital channel fragmentation. These shifts are compressing traditional go-to-market timelines while elevating technical sophistication requirements.
Microencapsulation technology for heat-sensitive botanical extracts is expanding into sports nutrition applications, protecting polyphenol integrity through pasteurization exposure. Cape Town-based contract manufacturers are adopting spray-drying systems at accelerated pace. This capability is expanding into value-added service offerings that differentiate toll processors from commodity flavor houses.
South Africa's Department of Health is tightening natural claim substantiation through pending amendments to the Foodstuffs Act's labeling chapter. Manufacturers must now document extraction methods and solvent residues for herbal additive positioning. Mid-tier brands lacking in-house regulatory affairs capacity are outsourcing compliance documentation to Johannesburg-based consulting firms.
Gym-based vending and fitness center direct distribution are displacing supermarket-centric purchase patterns among high-frequency users. Boutique studio partnerships in Sandton and Umhlanga Rocks provide sampling access to affluent early adopters. This channel rotation is most visible in Pretoria's northern suburbs, where private health club density exceeds national averages by significant margins.
South Africa Water Enhancer Market Segmentation
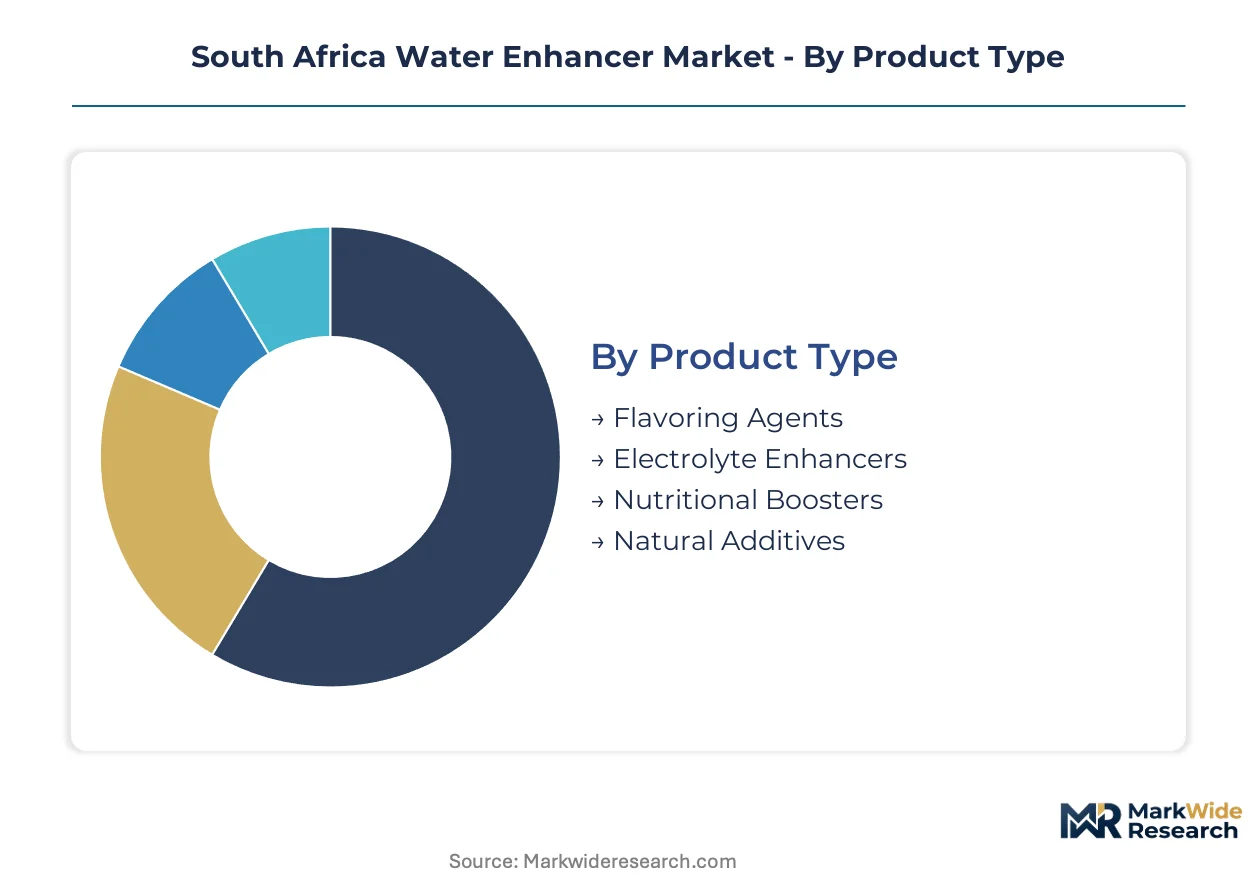
Water enhancer purchasing decisions in South Africa diverge sharply across consumption contexts, with formulation chemistry, channel accessibility, and user lifestyle creating distinct demand pockets. Understanding these segment boundaries enables manufacturers to align R&D investment with margin architecture and distribution partnerships.
Product Type:
Purchase intent splits between sensory gratification and functional efficacy, driving divergent formulation investments across calorie thresholds and extract sourcing.
- Flavoring Agents:Concentrated liquid or powder systems delivering taste transformation through artificial or natural flavor compounds, typically sub-five-calorie formulations. Demand concentrates in Gauteng supermarkets among price-sensitive households seeking bottled water alternatives, with repeat purchase frequency sustaining volume leadership despite thinner margins.
- Electrolyte Enhancers:Sodium, potassium, and magnesium-dosed formulations targeting hydration optimization during exertion. Johannesburg and Pretoria gym corridors drive uptake among protein-conscious consumers, with fitness culture expansion accelerating penetration faster than other product categories.
- Nutritional Boosters:Vitamin, mineral, and protein-fortified additives commanding premium positioning through immunity and wellness claims.
- Natural Additives:Stevia and monk fruit-sweetened systems aligning with Health Promotion Levy compliance and clean-label demand.
Flavoring agents lead on scale; electrolyte enhancers lead on momentum.
Use Case:
Consumption occasion defines serving size, frequency, and channel strategy, with sports-adjacent applications commanding higher per-gram pricing than routine hydration.
- Sports Nutrition:Pre-, intra-, and post-workout formulations optimized for electrolyte replenishment and muscle recovery. Boutique fitness studios in Sandton and Umhlanga Rocks anchor demand among affluent early adopters, with gym-based vending displacing supermarket purchase patterns for high-frequency users.
- Everyday Consumption:Routine flavor enhancement of tap or bottled water for household hydration improvement. Mature penetration in suburban Johannesburg constrains velocity, though steadier purchase cadence supports baseline manufacturing capacity utilization.
- Hydration Support:Medical or wellness-positioned electrolyte therapy for illness recovery or heat exposure mitigation.
- Functional Beverages:Nootropic, adaptogen, or energy-positioned systems targeting cognitive or metabolic outcomes.
Sports nutrition climbs fastest; everyday consumption holds the installed base.
End User:
Self-identification with health and fitness culture determines willingness to pay for premium extract systems versus commodity flavoring.
- Fitness Enthusiasts:Gym members and competitive athletes prioritizing hydration optimization and macro tracking. Pretoria's northern suburbs exhibit private health club density exceeding national benchmarks, concentrating demand for electrolyte-dosed and protein-fortified formulations.
- Health-Conscious Consumers:Suburban households prioritizing natural ingredient transparency and reduced sugar intake. Post-pandemic vigilance around immunity fortification sustains interest in zinc and vitamin C booster positioning.
- Outdoor Adventurers:Hikers, cyclists, and trail runners requiring portable hydration enhancement for extended exertion.
- General Population:Occasional users seeking basic flavor variety without functional claims or premium pricing.
Fitness enthusiasts command margin premiums; health-conscious consumers represent the broadest addressable pool.
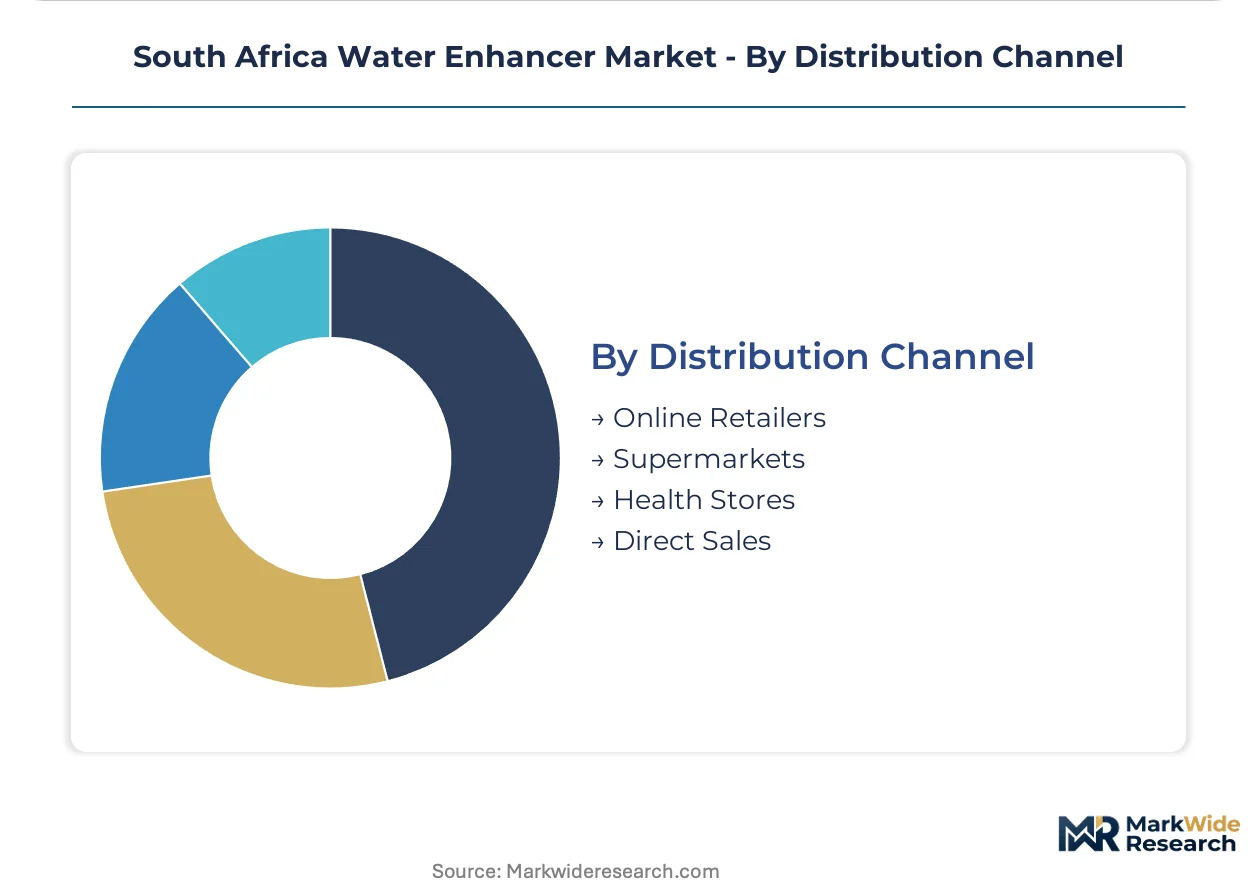
Distribution Channel:
Channel selection determines slotting fee exposure, sampling access, and subscription revenue potential across urban and peri-urban geographies.
- Supermarkets:Mass-market shelf presence through Checkers, Pick n Pay, and Spar networks. PepsiCo and Coca-Cola leverage bottling partnerships to anchor placement, though slotting fees compress challenger brand economics.
- Online Retailers:E-commerce fulfillment through Takealot and Woolworths platforms enabling direct-to-consumer subscription models. Bypassing traditional retail overhead supports emerging brand entry with reduced working capital requirements.
- Health Stores:Premium organic and specialty retailers in Cape Town's wellness tourism corridor.
- Direct Sales:Gym vending partnerships and fitness center exclusive distribution capturing high-frequency users at point of exertion.
Supermarkets dominate volume throughput; online retailers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemists and food science graduates cluster in Gauteng province, anchoring South Africa's water enhancer formulation capacity. This talent concentration shapes where manufacturers locate R&D facilities and accelerated aging laboratories.
Gauteng Province
Johannesburg and Pretoria retail corridors concentrate demand among fitness enthusiasts seeking electrolyte optimization. The Foodstuffs, Cosmetics and Disinfectants Act governs additive standards here, enforced through BIS-aligned laboratory testing. Sandton's boutique fitness studio density exceeds national benchmarks, driving gym-based vending partnerships for high-frequency users.
Western Cape
Cape Town's wellness tourism infrastructure attracts premium organic retailer expansion for natural additive positioning. Provincial environmental health services administer municipal water quality monitoring that indirectly affects bottled water substitution rates. The city's spray-drying contract manufacturing capacity is expanding into microencapsulation services for heat-sensitive botanical extracts.
KwaZulu-Natal
Durban's humid subtropical climate sustains year-round outdoor activity demand for portable hydration enhancement. The national Health Promotion Levy applies uniformly, pressuring local distributors toward stevia-sweetened inventory. Umhlanga Rocks private health clubs anchor affluent early adopter sampling programs for electrolyte enhancers.
Eastern Cape
Port Elizabeth manufacturing zones host toll processors serving national flavor house demand. Skills migration from Gauteng food science programs supplies formulation technicians to secondary production facilities. The province's supermarket distribution networks connect to Spar and Pick n Pay regional warehouses.
South Africa Water Enhancer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Africa's water enhancer market. Multinational beverage conglomerates anchor shelf presence through bottling partnerships and slotting fee absorption, while domestic toll processors and contract manufacturers supply formulation flexibility to challenger brands. Three archetypes dominate: integrated beverage multinationals with captive distribution, specialized flavor houses with natural extract expertise, and direct-to-consumer digital natives bypassing retail overhead. Competitive intensity centers on M&A-driven portfolio diversification and strategic partnerships with fitness center networks.
Among multinational beverage conglomerates, PepsiCo Inc. and The Coca-Cola Company exemplify integrated distribution archetypes, leveraging Coca-Cola Beverages South Africa's localized logistics muscle. Nestle S.A. occupies a position representing nutritional booster specialization, drawing on wellness portfolio expertise. Kraft Heinz Company and Keurig Dr Pepper sit within the diversified packaged goods tier, while Welch Foods Inc. and True Citrus Co. represent natural positioning specialists. Continental Mills Inc. anchors the contract manufacturing and private label supply vector.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Welch Foods Inc. |
| PepsiCo Inc. |
| Continental Mills Inc. |
| True Citrus Co. |
| Keurig Dr Pepper |
| The Coca-Cola Company |
| Nestle S.A. |
| Coca-Cola Beverages South Africa |
| Others |
Value Network & Pricing Analysis
Microencapsulation technology adoption for heat-sensitive botanical extracts is compressing production timelines while concentrating formulation capability among Cape Town contract manufacturers equipped with spray-drying systems. This equipment transition simultaneously elevates capital barriers for new entrants and shifts bargaining power toward toll processors capable of delivering stabilized natural additive systems.
Pricing Analysis
Unbundled flavor-only formulations compete on per-serving cost against bundled electrolyte-nutrition systems commanding premium positioning. Three-tier pricing structure across premium natural-extract, standard artificial-flavor, and economy private-label levels reflects ingredient sourcing transparency and certification grade. Price differentiation hinges on clean-label credentials and Health Promotion Levy compliance status, with stevia-sweetened variants capturing margin premiums. Cost compression in the standard tier is intensifying as Chinese stevia extract volatility feeds through to South African formulators, while fitness enthusiasts show lowest price sensitivity among end-user archetypes.
Supply Chain Analysis
BIS-aligned laboratory certification for preservative residue testing gates market access for international suppliers, favoring domestic manufacturers with established Johannesburg testing relationships. Stevia leaf processing concentrates in Chinese extraction facilities, while spray-drying equipment and flavor chemist talent clusters in South Africa's Western Cape and Gauteng provinces. Raw material dependencies span steviol glycosides, pH buffering agents, and microencapsulation polymers. Single-source vulnerability runs through yuan-denominated stevia supply exposed to shipping lane disruptions. Distribution runs through supermarket slotting fee networks anchored by bottling partnerships, with direct-to-subscription channels emerging as alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's water enhancer market functions as a regulatory compounder where Health Promotion Levy amendments continuously reshape formulation economics and create compliance-driven replacement demand.
For Market Incumbents: Deploy shelf space leverage through bottling partnerships to absorb slotting fee pressure from challenger brands. Anchor defensive positioning by accelerating stevia supply diversification beyond Chinese extraction facilities, and front-run pending Foodstuffs Act labeling amendments with pre-submitted natural claim documentation to capture first-mover regulatory clearance. For New Entrants and Emerging Players: Microencapsulation capability gaps among mid-tier domestic manufacturers create entry pathways for specialized natural extract formulators. White space concentrates in Cape Town wellness tourism corridors and direct-to-subscription channels bypassing Checkers and Pick n Pay slotting structures. Target gym-based vending partnerships in Pretoria's northern suburbs where private health club density exceeds national benchmarks. For Investors and Strategic Acquirers: Valuations sit cheapest among toll processors with underutilized spray-drying capacity and latent microencapsulation service potential. Long-term viability centers on regulatory affairs capacity and contracted relationships with Johannesburg-based compliance consulting firms. The signal to watch is accelerated BIS-aligned import testing enforcement shifting procurement preference toward domestic laboratory-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Sweetener Reformulation | Health Promotion Levy compliance unlocks shelf placement in sugar-tax-sensitive retail channels. |
| Microencapsulation Service Expansion | Cape Town contract manufacturers differentiate from commodity flavor houses through heat-stable botanical processing. |
| Direct-to-Subscription Channel Launch | Takealot and Woolworths online partnerships bypass supermarket slotting fees for emerging brands. |
| Gym-Based Vending Partnerships | Sandton and Umhlanga Rocks boutique fitness studios capture high-frequency electrolyte enhancer users. |
| Regulatory Affairs Capacity Buildout | Johannesburg consulting relationships accelerate Foodstuffs Act amendment compliance documentation. |
Research Methodology
Direct dialogue with flavor chemists, contract manufacturing executives, supermarket category buyers, and Department of Health regulatory affairs officers grounded qualitative insights in operational reality. Secondary validation drew from Foodstuffs, Cosmetics and Disinfectants Act filings, Health Promotion Levy implementation records, BIS-aligned laboratory testing protocols, and Nielsen retail audit data covering Checkers, Pick n Pay, and Spar networks. Bottom-up volume modeling across product type, use case, and distribution channel segments triangulated against top-down macroeconomic consumption indicators.
Bottom-up demand estimation by segment combined with top-down macroeconomic anchoring shaped the analytical framework across the analysis window. Segmentation dimensions modeled include flavoring agents versus functional enhancers, sports nutrition versus everyday consumption use cases, and supermarket versus direct-to-subscription channel splits. CAGRs were derived from fitted trend extrapolation calibrated to historical volume trajectories and regulatory milestone impacts, with specific inputs including gym membership growth rates in Johannesburg-Pretoria corridors and stevia extract import volume fluctuations.
The model holds under stable Health Promotion Levy enforcement and predictable BIS testing protocols; deviation in sugar tax rate adjustments or natural claim definition amendments would shift volume trajectories materially. Forecasts reflect documented assumptions regarding fitness culture penetration and municipal water quality trends. A model refresh is warranted upon material change in Foodstuffs Act labeling chapter implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Browning Enhancers Market