
 France Water Enhancer Market | 2026-2036
France Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
France Water Enhancer Market Foresight
Fitness-oriented hydration is decoupling from traditional bottled sports drinks as French consumers seek portable, low-calorie flavoring solutions. Nestle SA leverages its beverage science infrastructure to sustain shelf presence across hypermarket chains. PepsiCo Inc anchors the convenience channel with stick-pack formats designed for gym and workplace consumption. The Kraft Heinz Company differentiates through flavor intensity positioning that competes with premium imported alternatives.
Water enhancers comprise concentrated flavoring systems—typically containing natural and artificial flavor compounds, acidulants, sweeteners, and functional additives like electrolytes or vitamins—designed for dilution into still or sparkling water. Liquid formulations lead volume due to faster dissolution and dosing precision, while powder segments capture margin through lower shipping weights and extended stability profiles. Stick packs dominate packaging innovation as single-serve portability aligns with on-the-go consumption patterns among urban professionals and athletic demographics.
ANSM governs additive safety assessments and novel ingredient approvals for ingestible products sold in France, while EFSA provides harmonized risk evaluations that streamline cross-border formulation compliance. France's implementation of EU nutrition and health claims regulation constrains functional positioning, pushing brands toward cleaner label architectures. Stakeholders must monitor evolving caffeine and sweetener thresholds under periodic EFSA re-evaluations to anticipate reformulation mandates before enforcement phases tighten.
Market Dynamics
Fitness-oriented hydration protocols are decoupling from traditional sports beverages as French consumers demand portable, low-calorie flavoring systems. ANSM's tightening additive disclosure mandates compress reformulation timelines while Île-de-France's urban wellness infrastructure concentrates demand clusters.
Growth Catalysts
- Sports Hydration Protocols:Athletic demographics adopt concentrated flavoring systems for personalized electrolyte dosing. Fitness centers across Île-de-France integrate these formats into recovery programs.
- EFSA Harmonization:Streamlined cross-border additive approvals reduce compliance friction for French manufacturers exporting to neighboring EU markets. This accelerates product line extensions.
- Urban Wellness Infrastructure:Parisian workplace wellness programs distribute single-serve formats. Dense professional populations sustain convenience-channel velocity.
Market Restraints
- Stevia Supply Concentration:Natural sweetener sourcing depends on limited cultivation zones. Price volatility in stevia leaf markets squeezes margin structures for clean-label formulations.
- ANSM Disclosure Mandates:Expanded additive labeling requirements force packaging redesigns. Smaller producers face disproportionate compliance cost burdens relative to volume scale.
- Sparkling Water Substitution:Premium carbonated mineral water retains strong brand equity in French households. This limits penetration among traditional beverage consumers.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Expansion:Tourism-dependent coastal municipalities present underdeveloped distribution networks. Seasonal athletic events create concentrated demand windows.
- Functional Convergence:Electrolyte-vitamin hybrid formulations capture margin premiums. Combination products address multiple wellness positioning claims simultaneously.
- Direct-to-Channel Innovation:Gym vending partnerships bypass traditional retail slotting fees. This unlocks trial access among high-frequency athletic users.
Industry Challenges
- Flavor Chemist Scarcity:Natural flavor compound expertise commands premium compensation. Formulation teams struggle to recruit talent capable of clean-label taste replication.
- Stability Testing Timelines:Extended shelf-life validation for liquid concentrates delays launch cycles. Accelerated aging protocols require capital-intensive laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Water Enhancer Market |
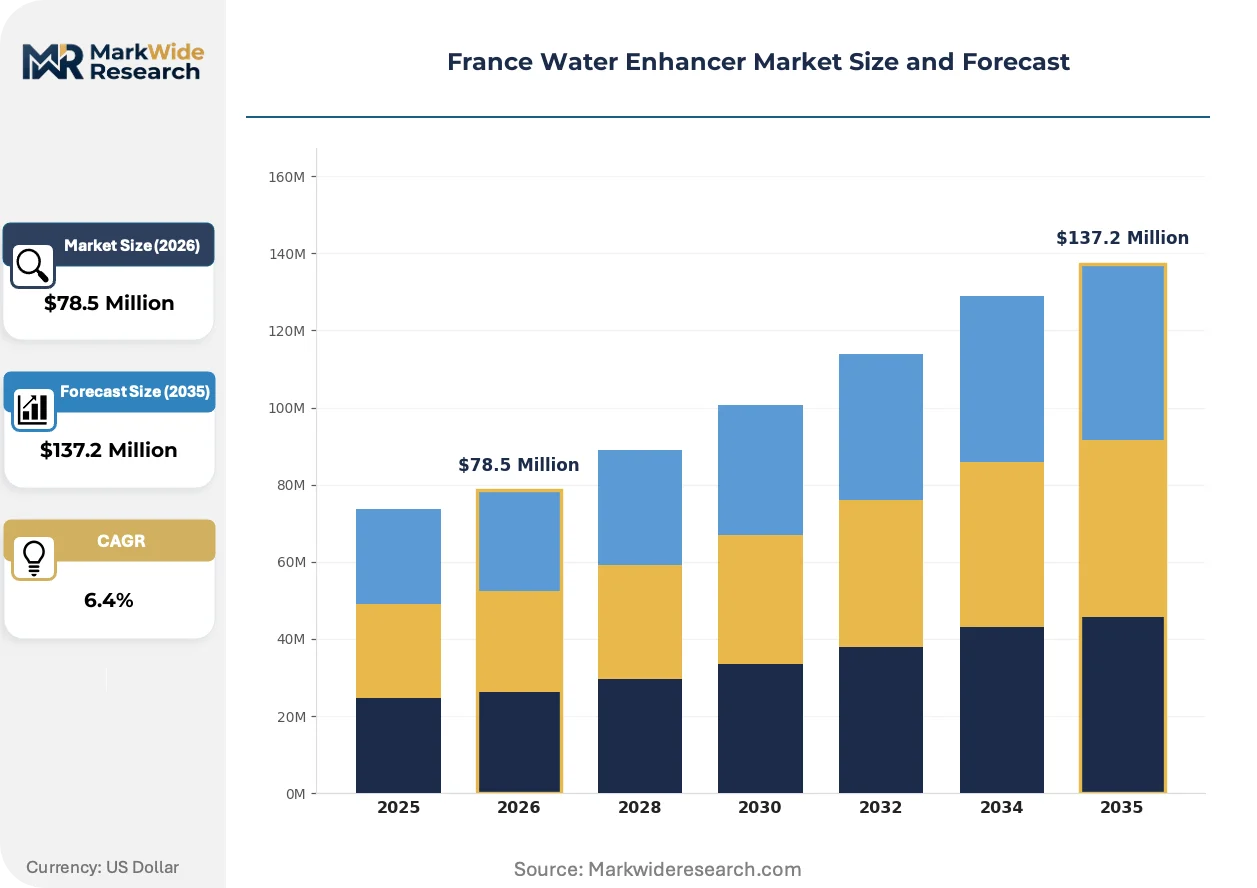
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $137.2 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablet, Drops Flavor: Citrus, Berry, Tropical, Herbal, Mint Packaging Type: Stick Packs, Bottles, Sachets, Tubes Consumer Demographic: Adults, Teens, Athletes, Elderly |
| Companies Covered | BPI Sports LLC, Dyla LLC, Wisdom Natural Brands, Heartland Food Products Group, Arizona Beverages USA, The Kraft Heinz Company, Hain Celestial, Nestle SA, PepsiCo Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Water Enhancer Market Shifts & Advancements
Clean-label architecture is compressing acceptable ingredient panels as French consumers scrutinize additive provenance. Formulation teams race to maintain taste intensity while eliminating artificial compounds.
Microencapsulation technology for volatile flavor compounds is integrating into liquid concentrate production. Premium positioning segments adopt these systems to extend shelf stability without synthetic preservatives. This is integrating natural taste profiles with industrial distribution requirements, compressing the tradeoff between clean labels and product longevity.
France's implementation of EU nutrition and health claims regulation constrains functional positioning vocabulary. Brands pivot toward implied wellness associations through packaging aesthetics rather than explicit physiological claims. Athletic and professional segments respond most visibly, seeking products that signal health consciousness without regulatory risk.
Gym-based consumption occasions are fragmenting traditional retail dependence. Urban professionals purchase single-serve formats at fitness facilities rather than supermarkets. This pattern concentrates most visibly in Paris intra-muros and La Défense business districts, where workplace wellness budgets subsidize on-site product availability.
France Water Enhancer Market Segmentation
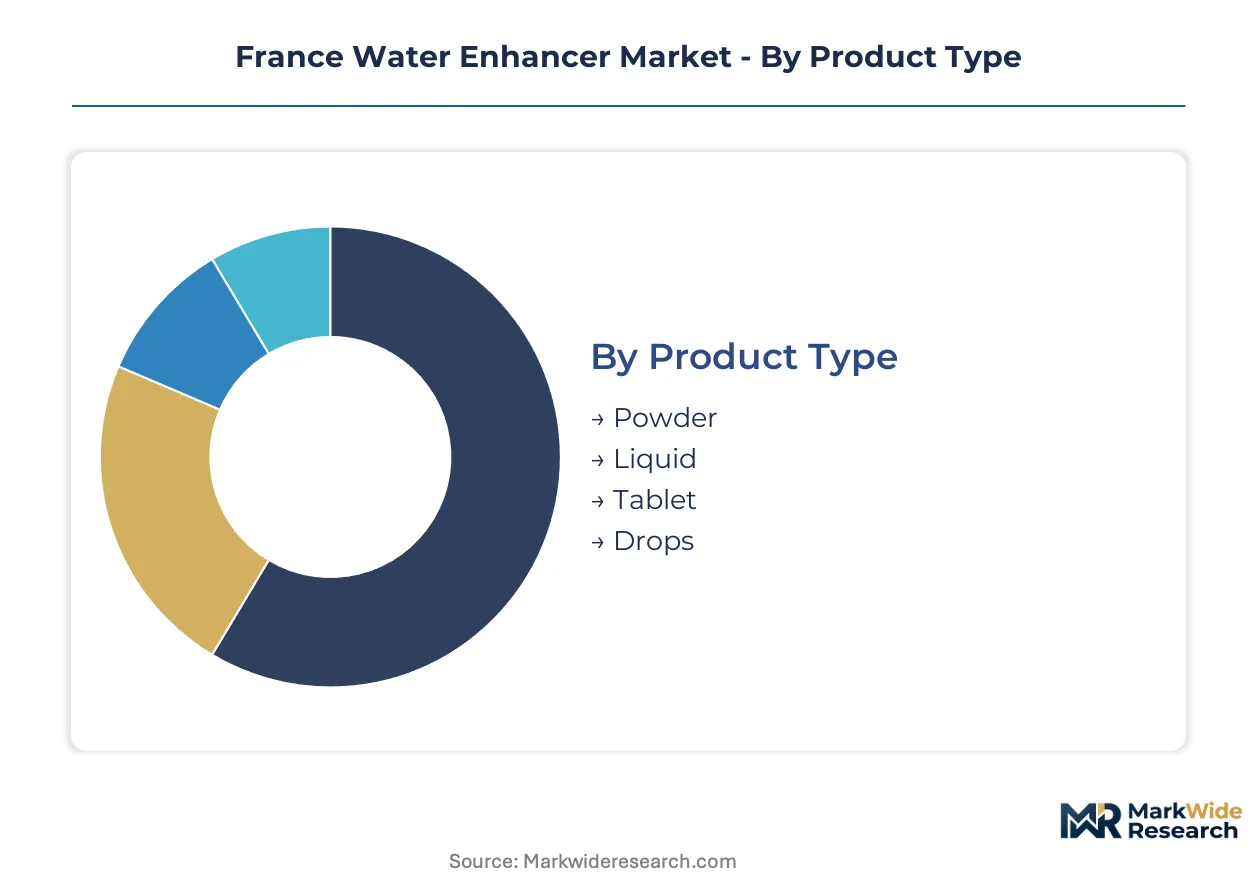
Segmentation in France's water enhancer market reveals distinct capital requirements and margin profiles across formulation technologies. Manufacturers allocate R&D budgets differently depending on which product architectures, flavor systems, and distribution formats they prioritize.
Product Type:
Liquid concentrates demand the heaviest upfront investment in precision dosing equipment and stability testing infrastructure, while powder formats require specialized encapsulation lines.
- Liquid:These concentrates dissolve instantly and permit precise milliliter dosing. Fitness centers across Île-de-France favor liquid formats for their compatibility with shaker bottles and rapid preparation. ANSM's additive disclosure mandates compress reformulation timelines for liquid portfolios.
- Powder:Microencapsulated flavor compounds extend shelf stability without synthetic preservatives. Provence-Alpes-Côte d'Azur tourism corridors see concentrated demand during seasonal athletic events. Lower shipping weights improve margin structures for export-oriented producers.
- Tablet:Compression molding equipment requires moderate capital outlay. These formats appeal to elderly consumers seeking portion-controlled hydration solutions.
- Drops:Pipette packaging lines involve specialized filling machinery. Urban professionals in Paris intra-muros favor drops for desk-side customization.
Liquid absorbs the bulk of installed capacity; powder is expanding most quickly.
Flavor:
Flavor development costs scale with natural ingredient sourcing complexity and clean-label reformulation cycles.
- Citrus:Limonene extraction and stabilization command premium flavor chemistry expertise. These profiles dominate workplace wellness programs in La Défense business districts.
- Berry:Anthocyanin-based color systems require advanced encapsulation to prevent degradation. Athletic demographics in Île-de-France recovery programs show strongest preference.
- Tropical:Volatile ester compounds demand sophisticated supply chain management for raw material freshness. Coastal tourism municipalities present underdeveloped distribution networks.
- Herbal:Botanical extract standardization faces EFSA novel food scrutiny. Elderly consumers respond to implied wellness associations through packaging aesthetics.
- Mint:Menthol crystallization processes suit stick-pack manufacturing lines. Gym vending partnerships favor mint for post-workout refreshment occasions.
Citrus holds the largest volume position; berry is climbing the fastest among athletic segments.
Packaging Type:
Packaging capital allocation tilts toward single-serve portability versus bulk household formats.
- Stick Packs:Vertical form-fill-seal lines require significant automation investment. These formats dominate Parisian workplace wellness budgets and gym-based consumption occasions.
- Bottles:Blow-molding and labeling infrastructure supports multi-serve household penetration. Traditional retail channels in dense urban wellness infrastructure sustain velocity.
- Sachets:Flat pouch equipment offers lower entry barriers for regional producers. Tourism-dependent coastal municipalities utilize sachets for seasonal demand windows.
- Tubes:Collapsible aluminum or plastic extrusion lines serve premium positioning segments. Direct-to-channel innovation bypasses traditional retail slotting fees.
Stick packs capture the majority of new equipment installations; tubes are gaining share fastest in premium channels.
Consumer Demographic:
Marketing spend concentrates on high-frequency users with established hydration routines.
- Athletes:Personalized electrolyte dosing protocols drive concentrated flavoring system adoption. Fitness centers integrate these formats into recovery programs across Île-de-France.
- Adults:Urban professionals seek portable, low-calorie alternatives to bottled sports drinks. Workplace wellness programs subsidize on-site product availability.
- Teens:Flavor intensity positioning competes with premium imported alternatives. Social consumption patterns influence trial and brand switching.
- Elderly:Medication interaction concerns elevate ANSM safety assessment relevance. Clean-label architectures address additive provenance scrutiny.
Athletes command the highest per-capita consumption; adults are expanding most quickly as workplace distribution deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's dense urban wellness infrastructure anchors national demand concentration, with Paris intra-muros and La Défense business districts driving workplace distribution innovation. The region's tax-advantaged zones for food-tech ventures accelerate startup formation in functional beverage formulation.
Île-de-France
Fitness centers across Paris and its inner suburbs integrate concentrated flavoring systems into recovery programs. ANSM's additive disclosure mandates compress reformulation timelines for manufacturers headquartered in this region. La Défense workplace wellness budgets subsidize on-site product availability for urban professionals.
Auvergne-Rhône-Alpes
Lyon's food science research clusters attract formulation talent for clean-label taste replication. EFSA harmonized risk evaluations streamline cross-border compliance for Rhône-Alpes exporters targeting Italian and Swiss markets. Grenoble's athletic demographics sustain demand for personalized electrolyte dosing protocols.
Provence-Alpes-Côte d'Azur
Tourism-dependent coastal municipalities present underdeveloped distribution networks for water enhancer brands. Seasonal athletic events in Nice and Cannes create concentrated demand windows during spring and summer months. Microencapsulated powder formats capture margin through lower shipping weights to these peripheral markets.
Hauts-de-France
Lille's logistics hub position enables efficient distribution to Belgian and Dutch cross-border consumers. The region's beverage manufacturing heritage supports contract packaging infrastructure for emerging brands. Calais-area warehousing facilities reduce lead times for stick-pack exports to UK retail channels.
Nouvelle-Aquitaine
Bordeaux's wine industry expertise transfers into natural flavor extraction capabilities for botanical water enhancers. The region's elderly demographic concentration elevates clean-label scrutiny and medication interaction concerns. Biarritz coastal wellness tourism generates seasonal demand for portable hydration formats.
France Water Enhancer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational beverage conglomerates anchoring hypermarket distribution while regional formulators capture gym-channel velocity. The vendor base organizes around three archetypes: diversified food-and-beverage conglomerates with existing hydration portfolios, pure-play flavor technology specialists, and private-label contract manufacturers serving retail chains. Consolidation pressure intensifies as ANSM compliance costs disproportionately burden smaller scale producers. Dominant competitive moves include portfolio diversification into functional hybrid formulations and direct-to-channel partnerships bypassing traditional retail slotting structures.
Among diversified food-and-beverage conglomerates, Nestle SA and PepsiCo Inc exemplify the scale-driven archetype with established beverage science infrastructure and convenience-channel penetration. The Kraft Heinz Company occupies a distinct position emphasizing flavor intensity differentiation. These three anchors demonstrate how multinational operational footprints compress per-unit compliance costs across reformulation cycles mandated by tightening additive disclosure requirements.
| Leading Market Players |
|---|
| BPI Sports LLC |
| Dyla LLC |
| Wisdom Natural Brands |
| Heartland Food Products Group |
| Arizona Beverages USA |
| The Kraft Heinz Company |
| Hain Celestial |
| Nestle SA |
| PepsiCo Inc |
| Others |
Supply & Pricing Matrix
Flavor chemist scarcity in the Auvergne-Rhône-Alpes research corridor widens labor-cost differentials between premium clean-label formulations and economy-tier artificial-compound alternatives. ANSM disclosure mandates compress margin structures disproportionately for smaller producers unable to amortize compliance across volume scales.
Pricing Analysis
Lead-time premiums attach to rapid-turnaround reformulation services as ANSM disclosure deadlines compress development cycles. Three-tier pricing structure across premium natural-extract, standard hybrid-formulation, and economy artificial-compound levels stratifies the market. Cost compression in the economy tier intensifies because stevia supply concentration squeezes input costs for clean-label alternatives. Adult urban professionals in workplace wellness programs exhibit lowest price sensitivity; elderly consumers seeking medication-compatible formulations demonstrate highest sensitivity.
Supply Chain Analysis
Direct-to-gym channels handle high-frequency athletic demand while hypermarket distribution serves household replenishment occasions. Raw material sourcing draws from China for bulk sweetener compounds, India for botanical extracts, and France for regional citrus terpenes. Microencapsulation equipment and precision dosing machinery constitute critical capital dependencies. Single-source vulnerability concentrates in stevia leaf cultivation zones. Distribution runs through Île-de-France logistics hubs for national coverage and Hauts-de-France warehousing for cross-border EU and UK access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as ANSM compliance costs disproportionately burden sub-scale producers, forcing asset-light regional formulators toward exit or acquisition.
For Market Incumbents: Deploy direct-to-channel control by establishing exclusive gym vending partnerships that bypass traditional retail slotting fees. Acquire clean-label formulation capabilities in Auvergne-Rhône-Alpes to secure scarce flavor chemistry talent before competitor bidding wars escalate. ANSM disclosure mandates threaten smaller competitors with disproportionate packaging redesign costs. For New Entrants and Emerging Players: Coastal tourism municipalities in Provence-Alpes-Côte d'Azur present underdeveloped distribution networks with concentrated seasonal demand windows. Elderly consumers in Nouvelle-Aquitaine remain underserved by medication-interaction-focused clean-label architectures. Pursue sachet-format beach and hotel partnerships as a low-capital entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier formulators possessing ANSM pre-approved additive portfolios given accelerating compliance-driven consolidation. Five-to-ten year viability favors targets with established gym-channel relationships and microencapsulation production assets. Monitor EFSA sweetener threshold re-evaluations as inflection indicators for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Gym Vending Partnership | Bypasses Carrefour and E.Leclerc slotting fees while capturing high-frequency athletic users in Île-de-France. |
| Clean-Label Reformulation | ANSM disclosure mandates accelerate competitive differentiation for natural-extract portfolios versus artificial-compound alternatives. |
| Microencapsulation Investment | Extends shelf stability without synthetic preservatives, enabling premium positioning in stick-pack and tube formats. |
| Provence-Alpes-Côte d'Azur Expansion | Seasonal athletic events in Nice and Cannes create concentrated demand windows for powder-format tourism distribution. |
| Functional Convergence Development | Electrolyte-vitamin hybrid formulations capture margin premiums while navigating EU nutrition and health claims regulation constraints. |
Research Methodology
Multi-period observation of ANSM disclosure mandate implementation timelines, EFSA additive re-evaluation schedules, and gym-channel penetration rates anchored the trend analysis, supplemented by interviews with beverage R&D directors, flavor chemists, hypermarket category buyers, fitness center procurement managers, and regulatory affairs specialists at ANSM and EFSA. Secondary validation drew from EU nutrition and health claims regulation filings, French customs trade data, Nielsen retail audit records, and SEC 10-K disclosures of multinational beverage conglomerates. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, flavor system, packaging format, and consumer demographic dimensions structured the analytical framework. CAGRs were derived from fitted growth curves applied to segment-level baseline values across the projection horizon. Industry-specific forecast inputs included ANSM enforcement phase schedules, EFSA novel food approval pipelines, and workplace wellness program adoption trajectories in Paris intra-muros and La Défense.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA sweetener threshold revisions, stevia supply disruptions, and sparkling water substitution trends. Practitioners should monitor ANSM disclosure mandate enforcement tightening, gym vending partnership announcements by incumbents, and EFSA caffeine re-evaluation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Dough Conditioners Market