
 Encapsulated Citric Acid Market | 2026-2036
Encapsulated Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Citric Acid Market Foresight
The EU Green Deal is pivoting food ingredient sourcing toward lower-carbon encapsulation technologies. Balchem Corporation leverages its integrated choline and encapsulation platform to sustain supply security for North American meat processors. Jungbunzlauer Suisse AG anchors European citric acid fermentation capacity, while Gadot Biochemical Industries Ltd. competes on Dead Sea mineral-derived process advantages.
Encapsulated citric acid consists of a citric acid core surrounded by lipid, polymer, or modified starch coatings that control release between 50°C and 120°C, enabling precise acidulation in thermally processed foods without premature moisture activation. The natural product type dominates current volume as clean-label reformulation displaces synthetic acidulants across European and North American retail channels. Microcapsules represent the fastest-growing form segment, commanding premium positioning in pharmaceutical and precision seasoning applications where particle size below 200 microns determines dissolution uniformity.
FDA food additive regulations under 21 CFR 184.1033 govern citric acid GRAS status, while EFSA evaluates novel encapsulation materials under updated food contact substance guidelines, and China's SAMR enforces GB standards for acidulant purity in imported food ingredients. These frameworks collectively elevate compliance costs for non-integrated suppliers while creating technical barriers that favor manufacturers with in-house regulatory affairs capabilities. Stakeholders must monitor evolving polymer coating approvals and carbon intensity disclosure requirements to preserve market access across major formulation hubs.
Market Dynamics
The EU F-Gas Regulation and REACH compliance requirements are forcing reformulation of encapsulation chemistries, while clean-label meat processors in Germany and the United States simultaneously pull for natural acidulant alternatives to synthetic preservatives.
Growth Catalysts
- Clean-label reformulation:European and North American retail channels are displacing synthetic acidulants with natural encapsulated citric acid in processed meat and snack seasoning formulations.
- REACH polymer approvals:EFSA's updated food contact substance guidelines for novel encapsulation materials are creating technical barriers that favor suppliers with in-house regulatory affairs capabilities.
- Precision seasoning demand:Pharmaceutical and high-end food applications requiring particle sizes below 200 microns are accelerating microcapsule adoption for dissolution uniformity.
Market Restraints
- Fermentation input volatility:Molasses and corn-derived feedstock costs for citric acid fermentation fluctuate with agricultural commodity cycles, compressing margins for non-integrated producers.
- European supply concentration:Jungbunzlauer Suisse AG anchors the majority of EU citric acid fermentation capacity, creating single-source dependency risk for regional formulators.
- Coating material limitations:Lipid and modified starch coatings degrade above 120°C, restricting applications in ultra-high-temperature processed foods.
Strategic Opportunities
- Chinese precision food sector:SAMR's evolving GB standards for acidulant purity are elevating compliance costs for imports, creating opening for domestic encapsulation specialists serving local processed food multinationals.
- Carbon disclosure tailwinds:The EU Green Deal's carbon intensity reporting requirements favor suppliers with lower-carbon encapsulation technologies and transparent supply chain data.
- Dual-release coating convergence:Combining pH-responsive polymers with thermal-triggered matrices enables sequential acidulation in complex multi-stage thermal processes.
Industry Challenges
- Regulatory affairs talent scarcity:Specialists capable of navigating simultaneous FDA GRAS petitions, EFSA novel food consultations, and SAMR import registrations command premium compensation.
- Encapsulation equipment capex:Fluidized bed and spray-drying systems for sub-200-micron microcapsule production require seven-figure capital commitments with extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Citric Acid Market |
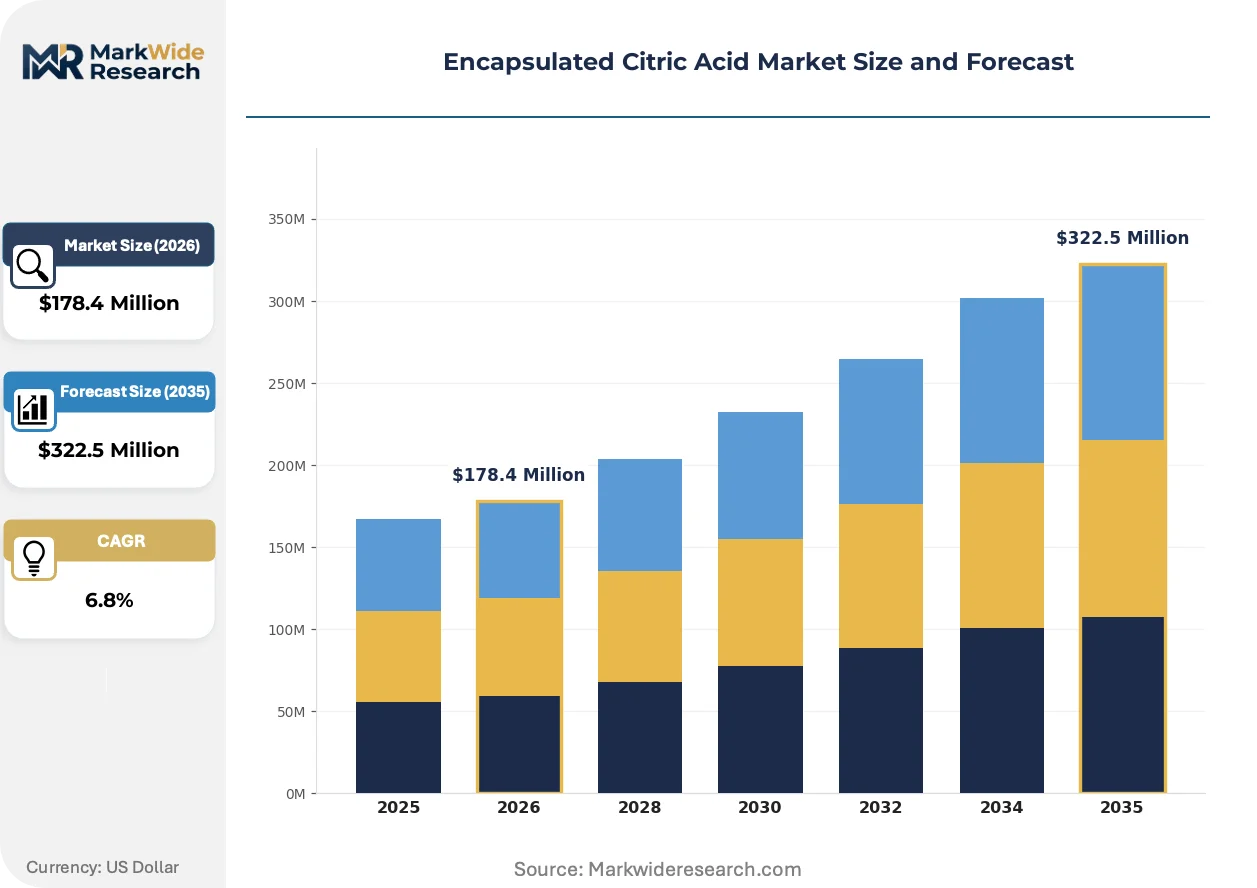
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $322.5 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
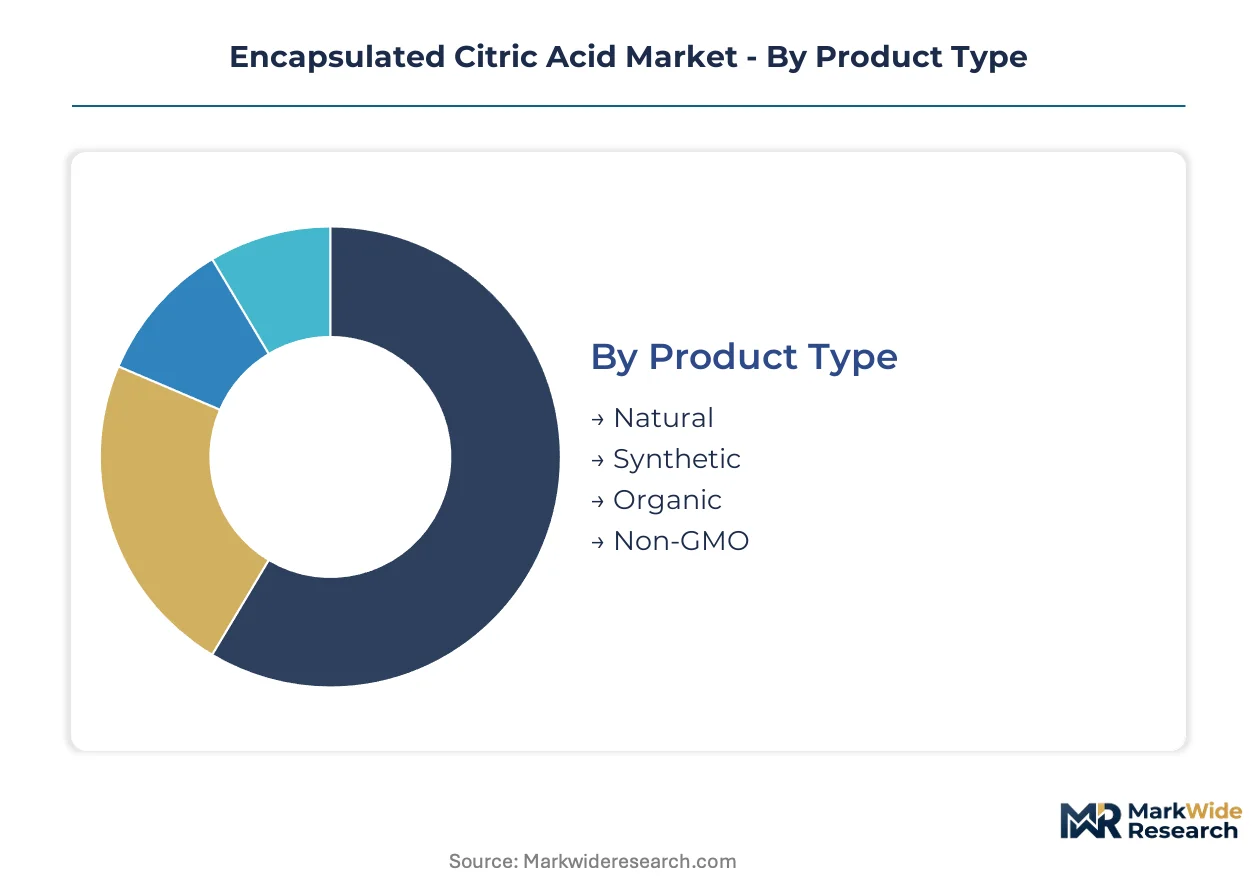
| Segmentation | Product Type: Natural, Synthetic, Organic, Non-GMO Application: Food Preservation, Pharmaceuticals, Cosmetic Products, Industrial Cleaning Form: Powder, Granules, Pellets, Microcapsules End User: Food & Beverage, Healthcare, Personal Care, Household Products |
| Companies Covered | Balchem Corporation, Watson Inc., Lamirsa Group VEDEQSA, Gadot Biochemical Industries Ltd., Jungbunzlauer Suisse AG, Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Weifang Ensign Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Citric Acid Market Shifts & Advancements
Encapsulation chemistry is pivoting toward bio-based coating materials as thermal stability requirements tighten and carbon accounting penetrates ingredient sourcing decisions across formulation hubs.
Modified starch coatings with tailored gelatinization temperatures are overtaking traditional lipid-based encapsulation in meat processing applications. North American sausage and cured meat manufacturers are adopting these systems at accelerating pace to achieve precise acidulation at 72°C without premature release during mixing. This transition is compressing demand for hydrogenated vegetable oil coatings while creating specification divergence between premium and commodity encapsulation tiers.
EFSA's updated guidance on food contact substances for polymer encapsulation materials is mandating expanded migration testing and toxicological data packages. The industrial consequence is extended approval timelines stretching 18-24 months for novel coating chemistries. European pharmaceutical and precision seasoning segments are most affected, with formulators stockpiling approved materials and delaying supplier switches until regulatory certainty clarifies.
Buyer concentration among multinational processed food corporations is consolidating procurement decisions toward fewer, larger encapsulation contracts with integrated technical service requirements. Regional seasoning houses and mid-tier meat processors are losing direct supplier relationships as purchasing authority centralizes at headquarters level. This pattern is most visible in Germany and the United States, where formulation hubs now specify encapsulation performance parameters that only integrated choline and acidulant platforms can satisfy.
Encapsulated Citric Acid Market Segmentation
Encapsulated citric acid segmentation reflects divergent compliance burdens across regulatory jurisdictions. FDA GRAS petitions, EFSA novel food consultations, and SAMR import registrations each impose distinct documentation requirements that reshape supplier economics by segment.
Product Type:
FDA 21 CFR 184.1033 governs citric acid GRAS status, while EFSA evaluates novel encapsulation materials under updated food contact substance guidelines, and China's SAMR enforces GB standards for acidulant purity. These frameworks elevate compliance costs disproportionately across product categories.
- Natural:Fermentation-derived citric acid with lipid or modified starch coatings meets clean-label specifications for European and North American retail channels. Meat processors in Germany and the United States specify natural variants to displace synthetic acidulants in sausage and cured meat formulations. FDA and EFSA alignment on fermentation-source documentation streamlines multi-jurisdiction filings for this segment.
- Synthetic:Petrochemical-derived citric acid with polymer coatings serves industrial cleaning and lower-tier food applications where cost minimization dominates specification. REACH compliance for petrochemical feedstocks adds regulatory complexity absent in natural variants. Formulators in China increasingly bypass synthetic grades for export-bound food ingredients.
- Organic:Certified organic fermentation with organic-compliant coatings commands premium positioning in European organic retail channels. EU organic regulation (EU) 2018/848 mandates full supply chain certification.
- Non-GMO:Identity-preserved corn or molasses feedstock with GMO-free coating materials addresses North American retailer non-GMO verification requirements. Non-GMO Project verification adds third-party audit costs.
Leading the category by volume: Natural. Growing fastest: Organic.
Application:
Application segmentation tracks thermal stability requirements and release temperature precision, with coating chemistry calibrated to process conditions rather than end-use labeling alone.
- Food Preservation:Encapsulated citric acid enables controlled acidulation at 72°C in meat processing and snack seasoning without premature moisture activation. Modified starch coatings with tailored gelatinization temperatures are displacing hydrogenated vegetable oil systems in North American sausage manufacturing. EFSA migration testing requirements for polymer coatings extend approval timelines for novel encapsulation chemistries in this segment.
- Pharmaceuticals:Microcapsules below 200 microns deliver dissolution uniformity for active pharmaceutical ingredients and excipient applications. Sub-200-micron particle size specifications demand fluidized bed or spray-drying production systems with seven-figure capital commitments. FDA drug master file requirements for excipient-grade encapsulation materials exceed food-additive documentation burdens.
- Cosmetic Products:pH-responsive coatings enable sequential release in multi-step personal care formulations. EU Cosmetics Regulation (EC) 1223/2009 governs encapsulation material safety assessments.
- Industrial Cleaning:Lower-cost synthetic-grade encapsulation serves detergent and sanitizer applications where thermal release precision matters less than bulk acidulant dosing. SAMR GB standards for industrial chemical purity apply to import registrations.
Dominant by revenue: Food Preservation. Steepest expansion trajectory: Pharmaceuticals.
Form:
Form factor determines equipment compatibility and dissolution kinetics, with microcapsule production requiring specialized capital investment that fragments supplier capabilities.
- Powder:Standard milled encapsulation with particle sizes above 500 microns serves commodity seasoning and industrial applications. Lower production costs and minimal equipment specialization sustain broad supplier participation. Powder specifications dominate Chinese domestic consumption for processed food manufacturing.
- Granules:Intermediate particle size distribution improves flowability in high-speed seasoning lines and reduces dust generation during meat processing operations. German meat processors specify granule forms for automated dosing equipment.
- Pellets:Compressed agglomerates with controlled porosity enable extended release profiles in slow-cured meat applications. Pellet production requires pelletizing equipment with moderate capital investment.
- Microcapsules:Sub-200-micron particles produced via fluidized bed coating or spray-drying achieve dissolution uniformity critical for pharmaceutical and precision seasoning applications. Extended commissioning timelines for production equipment create supply scarcity. Microcapsule adoption accelerates where particle size determines regulatory approval or performance specification compliance.
Highest volume: Powder. Gaining share fastest: Microcapsules.
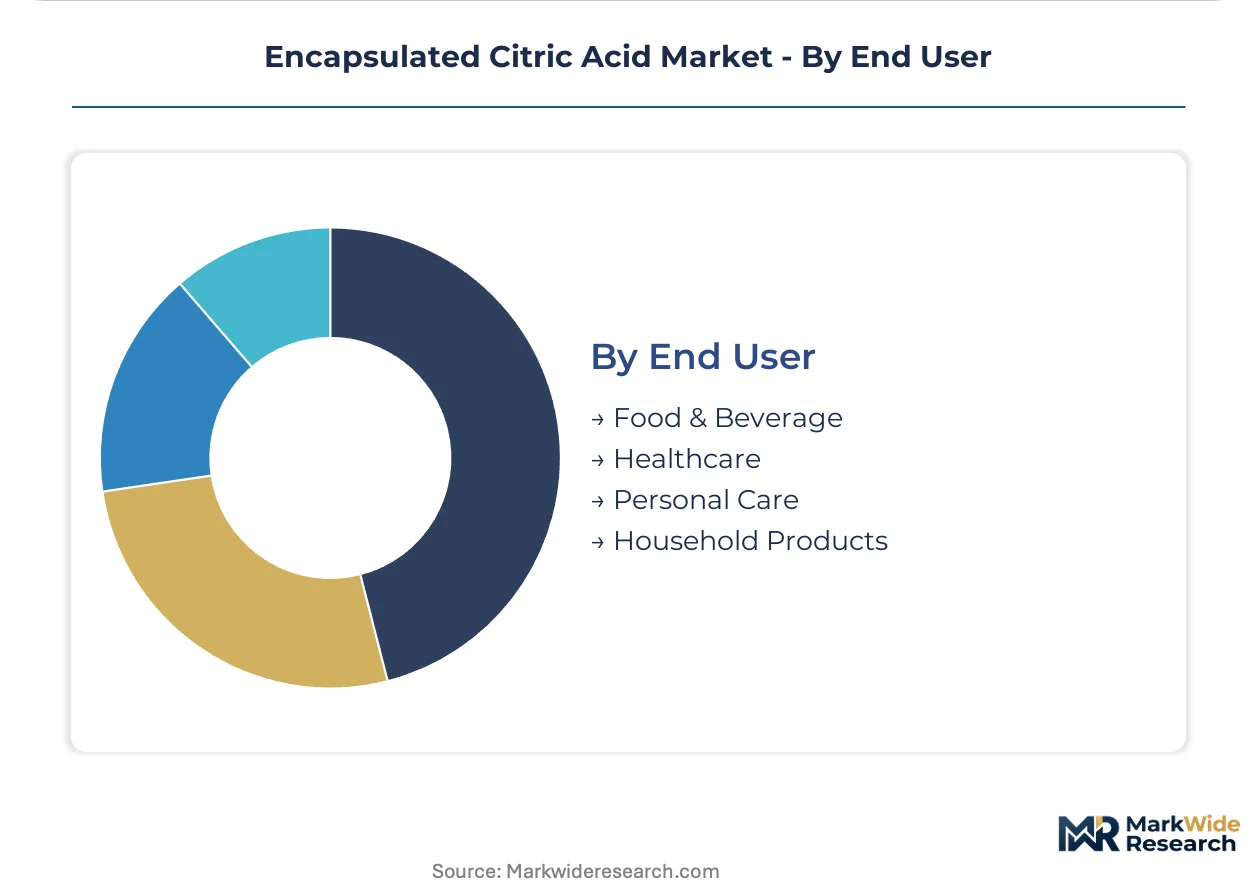
End User:
End user concentration drives procurement centralization, with multinational processed food corporations consolidating purchasing authority toward fewer, larger encapsulation contracts.
- Food & Beverage:Processed meat multinationals and snack seasoning houses in Germany, China, and the United States anchor demand for natural and non-GMO encapsulated citric acid. Clean-label reformulation across European and North American retail channels displaces synthetic acidulants. Buyer concentration is consolidating procurement decisions toward integrated technical service contracts.
- Healthcare:Pharmaceutical manufacturers and nutraceutical formulators specify microcapsule grades for dissolution uniformity and regulatory documentation depth. FDA drug master file and EMA excipient qualification requirements exceed food-grade compliance burdens. Healthcare procurement prioritizes supplier regulatory affairs capabilities over unit cost minimization.
- Personal Care:Cosmetic formulators leverage pH-responsive coatings for sequential acidulation in multi-step skin and hair care products. EU Cosmetics Regulation safety assessments govern encapsulation material selection.
- Household Products:Detergent and sanitizer manufacturers utilize synthetic-grade encapsulation for cost-optimized bulk acidulant dosing. Industrial cleaning applications tolerate wider particle size distribution and higher coating degradation temperatures.
Largest demand source: Food & Beverage. Expanding most quickly: Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in Switzerland and China while formulation demand concentrates in Germany and the United States. This geographic split shapes trade flows and regulatory compliance burdens across supplier networks.
United States
Meat processors in the Midwest and Southeast specify natural encapsulated citric acid for clean-label sausage and cured meat reformulation. FDA 21 CFR 184.1033 governs GRAS documentation for fermentation-derived acidulants. Chicago anchors North American procurement centralization as multinational headquarters consolidate encapsulation contracts toward integrated technical service providers.
Germany
Snack seasoning houses and processed meat manufacturers drive demand for modified starch-coated microcapsules with precise 72°C release profiles. EFSA's updated food contact substance guidelines extend approval timelines for novel polymer coatings to 18-24 months. The Frankfurt-Rhine-Main corridor hosts formulation hubs where buyer concentration is eliminating direct supplier relationships for mid-tier processors.
China
Domestic processed food multinationals are accelerating microcapsule adoption for precision seasoning applications as SAMR enforces evolving GB standards for acidulant purity. The country's national food safety regulator elevates compliance costs for imported encapsulation materials. Yangtze River Delta manufacturing clusters are developing domestic fluidized bed coating capacity to serve local pharmaceutical and food-grade demand.
Switzerland
Jungbunzlauer Suisse AG anchors European citric acid fermentation capacity, creating single-source dependency risk for regional formulators. REACH compliance requirements for encapsulation chemistries add regulatory complexity absent in non-EU supply alternatives. Basel-area technical service operations support pharmaceutical-grade microcapsule specifications for healthcare customers across the continent.
India
Processed food manufacturers in Maharashtra and Gujarat are displacing synthetic acidulants with natural encapsulated citric acid as clean-label retail channels expand. FSSAI regulations govern acidulant purity standards for domestic and export-bound ingredients. Mumbai-Pune industrial corridors concentrate demand for powder and granule forms in commodity seasoning applications.
Encapsulated Citric Acid Market Competitive Landscape
The competitive structure tilts toward integrated fermentation-encapsulation platforms rather than standalone coating specialists. Three to five multinational suppliers control the majority of pharmaceutical-grade microcapsule capacity, while regional fermentation houses serve commodity food-grade demand. Strategic archetypes include integrated choline-acidulant platforms, Dead Sea mineral-derived process specialists, and Asian corn-fermentation scale operators. Capacity expansion in fluidized bed coating systems and backward integration into citric acid fermentation represent the dominant competitive moves.
Among the integrated platform operators, Balchem Corporation and Jungbunzlauer Suisse AG exemplify the fermentation-encapsulation convergence that procurement centralization now demands. Gadot Biochemical Industries Ltd. occupies a distinct position leveraging mineral-derived process chemistry. These three anchors illustrate how geographic concentration of fermentation assets combines with regulatory affairs depth to determine supplier viability across FDA, EFSA, and SAMR jurisdictions.
| Leading Market Players |
|---|
| Balchem Corporation |
| Watson Inc. |
| Lamirsa Group VEDEQSA |
| Gadot Biochemical Industries Ltd. |
| Jungbunzlauer Suisse AG |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Weifang Ensign Industry Co., Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned fermentation houses in Switzerland and China anchor citric acid supply, their concentrated ownership structures enabling disciplined capacity management that resists spot-market volatility while sustaining premium pricing for pharmaceutical-grade microcapsules. This ownership pattern tightens pricing power at the fermentation tier, forcing downstream encapsulation specialists to absorb margin pressure or pursue captive acidulant supply.
Pricing Analysis
Margin tightening in commodity powder grades traces to molasses and corn feedstock volatility, compressing returns for non-integrated producers. Three-tier pricing structure across pharmaceutical-grade microcapsules, food-grade granules, and industrial powder segments separates certification-burdened healthcare supply from commodity seasoning applications. Pricing pressure intensifies in standard food-grade tiers as Chinese domestic capacity expansion floods regional markets. Pharmaceutical buyers exhibit lowest price sensitivity, prioritizing regulatory documentation depth over unit cost.
Supply Chain Analysis
Direct-to-processor channels handle multinational meat processor demand, while distributor networks serve mid-tier seasoning houses and regional pharmaceutical formulators. Fermentation capacity clusters in Switzerland and China, with encapsulation finishing distributed across Germany, the United States, and the Yangtze River Delta. Raw material supply draws from Black Sea corn belts, Brazilian sugarcane regions, and Dead Sea mineral deposits. Single-source dependency on Jungbunzlauer's Swiss fermentation creates regional vulnerability for European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The encapsulated citric acid market is a vertical-integration race. Players are pursuing captive fermentation capacity to escape feedstock volatility and secure pharmaceutical-grade supply certification.
For Market Incumbents: Deepen backward integration into citric acid fermentation to offset molasses cost volatility and deny supply leverage to commodity traders. Anchor encapsulation capacity in the Yangtze River Delta to capture Chinese precision food sector growth while SAMR elevates import compliance costs. Defend microcapsule margins by stockpiling EFSA-approved polymer coatings before extended approval timelines tighten further. For New Entrants and Emerging Players: Begin with pH-responsive dual-release coating development for multi-stage thermal processes, a white space between established lipid and modified starch systems. Target Indian processed meat manufacturers in Maharashtra and Gujarat where clean-label reformulation is displacing synthetic acidulants faster than local encapsulation supply can respond. Lead with regulatory affairs capabilities as the primary go-to-market wedge. For Investors and Strategic Acquirers: Fluidized bed coating equipment order backlogs extending 18-24 months is the leading indicator that microcapsule supply scarcity will persist. Long-term viability favors integrated fermentation-encapsulation platforms over standalone coating specialists. Target acquisition archetypes: Asian corn-fermentation scale operators with underutilized pharmaceutical-grade certification capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive citric acid supply insulates margins from agricultural commodity cycles. |
| Fluidized Bed Coating Capacity Expansion | Sub-200-micron microcapsule production captures pharmaceutical and precision seasoning premiums. |
| EFSA Polymer Coating Pre-Approval Stockpiling | Extended 18-24 month approval timelines create scarcity value for approved materials. |
| Chinese Domestic Encapsulation Buildout | SAMR's evolving GB standards favor local suppliers over import-dependent competitors. |
| Dual-Release Coating R&D Partnership | pH-responsive and thermal-triggered matrix convergence enables sequential acidulation patents. |
Research Methodology
Document review covered FDA GRAS petitions, EFSA food contact substance guidance, and SAMR GB standards, complemented by interviews with fermentation plant managers, encapsulation equipment specialists, regulatory affairs directors at processed food multinationals, and procurement leads at German meat processors. Secondary validation drew from customs trade data, SEC 10-K filings of integrated suppliers, and REACH registration databases. Bottom-up capacity modeling triangulated against top-down demand estimates from end-use industry consumption patterns.
Cross-referencing historical capacity utilization against expert panel input on coating technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application thermal stability requirement, form factor equipment compatibility, and end-user procurement centralization level. CAGRs were derived from weighted scenario analysis incorporating feedstock cost trajectories and regulatory approval timeline assumptions.
Underlying measurement precision varies by segment; pharmaceutical-grade microcapsule volumes carry tighter precision than commodity powder estimates due to concentrated supplier disclosure. Forecasts reflect assumptions on EFSA polymer approval timelines and SAMR enforcement intensity that stress-testing should periodically revisit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Automotive Coolant Additives Market
Additives
Rosin Ester Market
Additives
Alkyl Acetates Market
Additives
Calcium Stearate Market
Additives
Biofuel Additives Market
Additives
Antimicrobial Ingredients Market
Additives
1,4 Butanediol Derivatives Market
Additives
Propyl Gallate Market
Additives
Glyceryl Caprylate Market
Additives
Global Polyurethane Additives Market
Additives
Agrochemicals Additives Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Anti-Foaming Agent Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Carboxymethyl Cellulose Market
Additives
India Feed Additives Market