
 South Sudan Oil and Gas Upstream Market | 2026-2036
South Sudan Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
South Sudan Oil and Gas Upstream Market Analytics
Field development service revenue is fragmenting across multiple contract structures as operators reassess risk allocation models. China National Petroleum Corporation leverages its pipeline infrastructure and refining offtake agreements to sustain dominant production volumes from the Dar and Greater Nile consortia. Sinopec anchors its position through integrated drilling and workover service capabilities, while PETRONAS competes via deepwater exploration expertise in frontier blocks.
South Sudan oil and gas upstream encompasses crude petroleum extraction, reservoir appraisal, and well completion activities targeting API gravities ranging from 26° to 34° in rift basin formations, primarily supplying regional refineries and export terminals. Exploration activity under Operation Type segments commands disproportionate capital allocation given untested Melut Basin extensions, while Production Sharing contracts within Contract Structure categories concentrate margin pools through cost recovery mechanisms and profit oil splits. Onshore field development dominates current output, though tight oil appraisal represents the fastest-growing technical focus area as conventional reserve depletion accelerates.
The Ministry of Petroleum governs licensing rounds and fiscal terms, while the National Petroleum and Gas Commission oversees environmental compliance and field abandonment bonds. Production sharing agreement renegotiations and local content regulations directly shape foreign operator economics and partner selection criteria. Stakeholders must monitor pipeline security dynamics and transit fee disputes with Sudan, as these operational variables determine whether new field developments achieve commercial threshold.
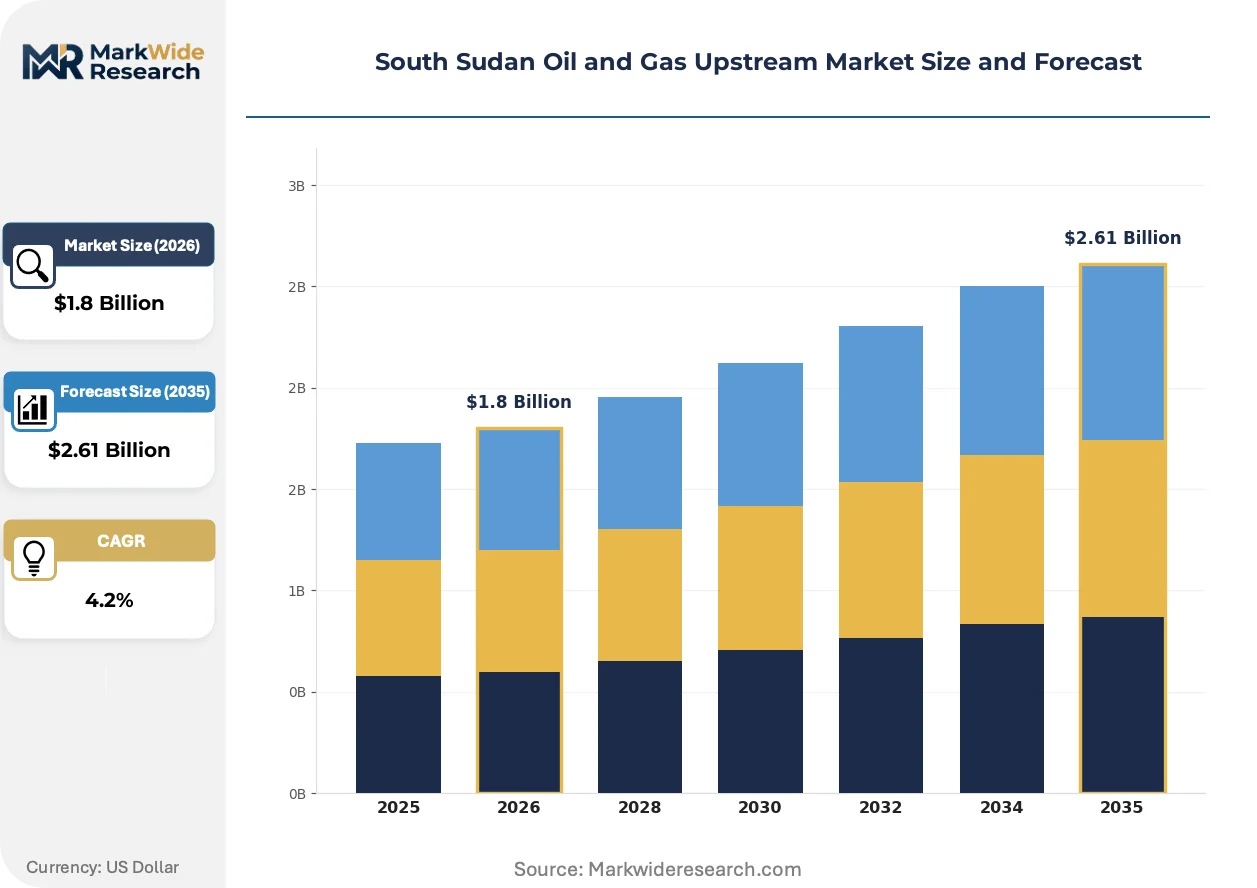
Market Dynamics
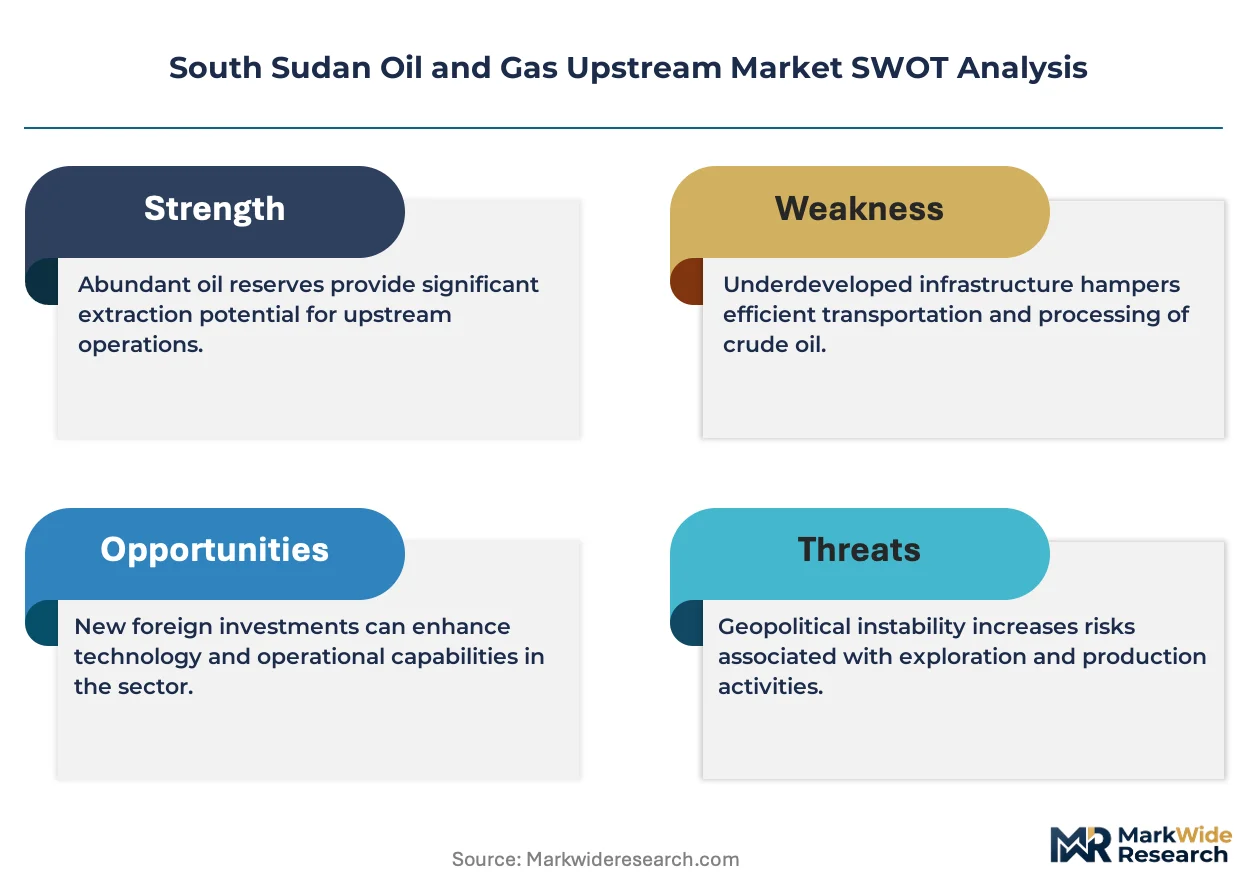
Production sharing agreement renegotiations by South Sudan's Ministry of Petroleum are fragmenting risk allocation models across upstream contracts, forcing operators to recalibrate cost recovery timelines and profit oil splits amid fiscal uncertainty.
Growth Catalysts
- Melut Basin Extensions:Untested rift structures in this northern formation attract disproportionate capital allocation from exploration-focused operators seeking conventional reserve replacement.
- Local Content Regulations:Mandates requiring South Sudanese workforce participation and domestic supplier integration create structural demand for indigenous service capacity building.
- Dar Pipeline Infrastructure:Existing crude evacuation routes through this corridor reduce greenfield development breakeven thresholds for new field tie-ins.
Market Restraints
- Transit Fee Disputes:Ongoing negotiations with Sudan over pipeline access tariffs introduce revenue volatility that compresses project IRR calculations for upstream investors.
- API Gravity Limitations:Crude ranging 26° to 34° in Muglad Basin formations restricts direct substitution into light sweet refining configurations without blending infrastructure.
- Security Expenditure Burden:Field protection costs in conflict-affected zones inflate operating expenses beyond comparable onshore African basins.
Strategic Opportunities
- Tight Oil Appraisal:Unconventional reservoir characterization in rift basin source rocks represents the fastest-growing technical focus area as conventional depletion accelerates.
- Regional Refinery Integration:Supply agreements with East African downstream projects create captive offtake channels reducing export terminal dependency.
- Environmental Compliance Bonds:National Petroleum and Gas Commission field abandonment requirements generate recurring revenue streams for specialized remediation contractors.
Industry Challenges
- Reservoir Engineering Talent:Scarce expertise in rift basin fault compartmentalization forces reliance on expatriate technical staff, inflating payroll costs and creating knowledge transfer gaps.
- Workover Rig Availability:Limited indigenous drilling service capacity constrains production maintenance schedules and artificial lift optimization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Sudan Oil and Gas Upstream Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Operation Type: Exploration, Production, Drilling, Development Contract Structure: Joint Venture, Production Sharing, Service Contract, Licensing Field Type: Offshore, Onshore, Tight Oil, Conventional Investment Type: Foreign Direct Investment, Domestic Investment, Public Financing, Private Equity |
| Companies Covered | Petroliam Nasional Berhad (PETRONAS), Oranto Petroleum, Nile Petroleum Corporation, Dar Petroleum Operating Company, Greater Nile Petroleum Operating Company, China National Petroleum Corporation, Sinopec, Sudd Petroleum Operating Company, ONGC Videsh Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Sudan Oil and Gas Upstream Market Evolving Landscape
Upstream operators in South Sudan are reconfiguring technical workflows around digital reservoir surveillance and modular development architectures, compressing cycle times between discovery and first oil while adapting to capital discipline pressures.
Advanced 4D seismic monitoring is migrating from exploration-focused supermajors to mid-tier operators managing mature Muglad Basin fields. Sinopec and consortium partners deploy time-lapse surveys to track waterflood front movement and optimize infill drilling locations. This capability migration from frontier appraisal to brownfield asset management is enabling smaller operators to defend production decline curves without full-field simulation investments.
South Sudan's Ministry of Petroleum has implemented production sharing contract templates requiring explicit local content percentage commitments and domestic training expenditure floors. These fiscal terms reshape partner selection criteria, favoring operators with established East African workforce development programs. Field development proposals now undergo parallel technical and social impact review, extending approval timelines but reducing post-signature compliance disputes.
Service contract unbundling is fragmenting integrated drilling packages across multiple specialized vendors. Operators disaggregate directional drilling, logging-while-drilling, and completions services to optimize unit economics and mitigate single-supplier concentration risk. This procurement restructuring is most visible in Greater Nile Petroleum Operating Company tenders, where modular scope definitions attract niche technical specialists previously excluded from full-service awards.
South Sudan Oil and Gas Upstream Market Segmentation
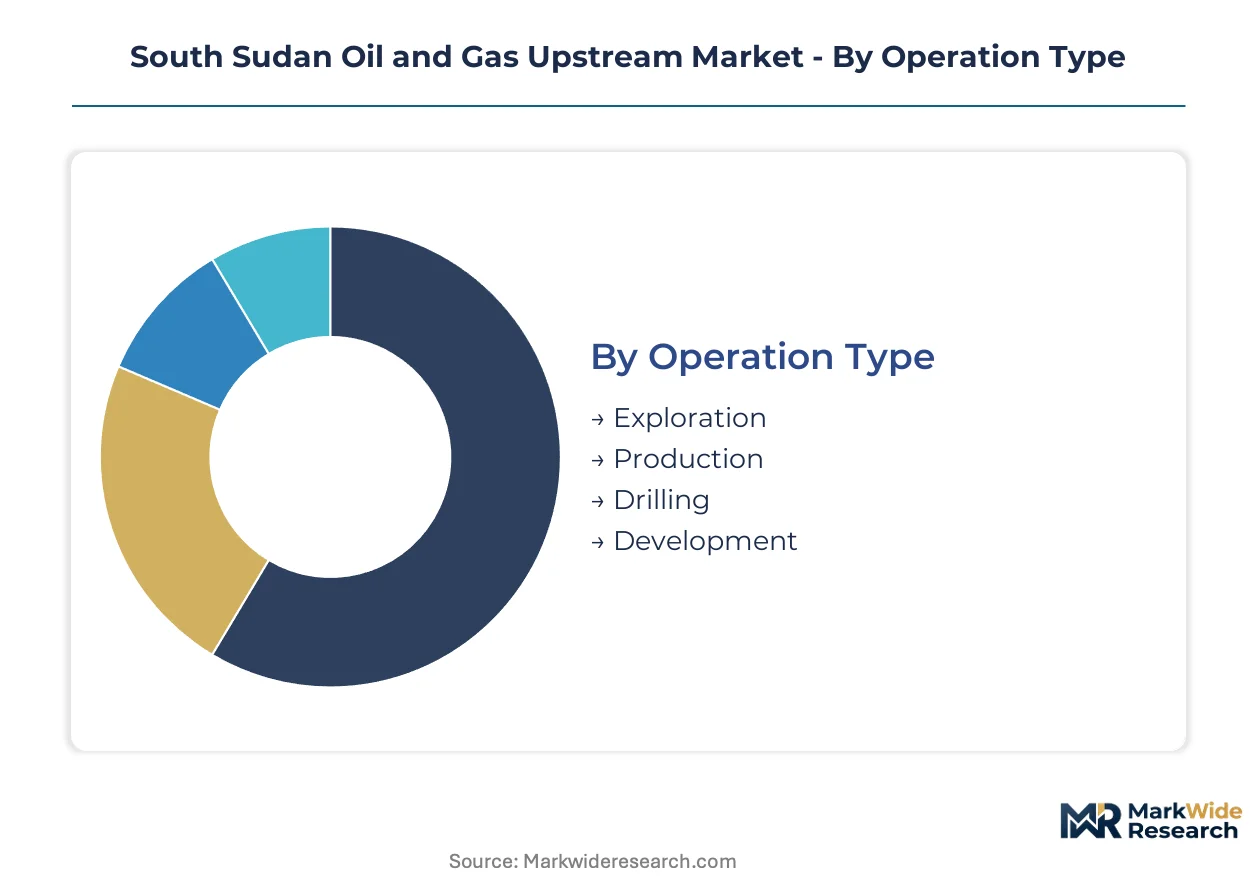
Segmentation in South Sudan's upstream market reveals how risk allocation and capital deployment vary across operational phases and contractual frameworks. Each dimension captures distinct stakeholder incentives, from exploration frontier exposure to mature field cash flow stability.
Operation Type:
Activity phase determines capital intensity and timeline to revenue, with exploration commanding disproportionate upfront allocation against production's steady-state economics.
- Exploration:Seismic acquisition and wildcat drilling in Melut Basin extensions target untested rift structures. Capital concentrates on northern concessions where Ministry of Petroleum licensing rounds have opened frontier blocks to new entrants.
- Production:Sustained crude extraction from Dar and Greater Nile consortium fields generates the revenue base funding field maintenance and artificial lift programs. Output volumes anchor domestic power generation and regional export commitments.
- Drilling:Workover and infill operations address reservoir compartmentalization challenges in Muglad Basin mature assets. Scarce indigenous rig availability forces reliance on expatriate service contractors.
- Development:Greenfield facility construction and pipeline tie-ins convert reserves into producible capacity. Dar corridor infrastructure proximity reduces project breakeven thresholds for new field connections.
Production commands the established base. The steepest expansion runs through Exploration.
Contract Structure:
Fiscal architecture shapes how operators recover costs and split profit oil, directly influencing partner selection and field development sequencing.
- Production Sharing:Ministry of Petroleum templates mandate explicit local content percentages and domestic training floors. Cost recovery timelines and profit oil splits are fragmenting across renegotiated agreements amid fiscal uncertainty.
- Joint Venture:China National Petroleum Corporation leverages integrated pipeline and refining offtake positions within Dar and Greater Nile consortia. Equity stakes align operator interests with long-term production sustainability.
- Service Contract:Unbundled procurement across directional drilling, logging-while-drilling, and completions services attracts niche technical specialists previously excluded from full-service awards.
- Licensing:Ministry of Petroleum rounds reshape investor access terms through reformed fiscal frameworks. Approval timelines extend under parallel technical and social impact review requirements.
Production Sharing commands the established base. The steepest expansion runs through Service Contract.
Field Type:
Reservoir characteristics dictate extraction technology requirements and crude quality profiles, with implications for regional refinery compatibility.
- Onshore:Dominant current output from Muglad and Melut Basin rift formations with API gravities ranging 26° to 34°. Conventional development economics support the operational cash flow funding exploration programs.
- Tight Oil:Unconventional reservoir characterization in rift basin source rocks is gaining technical focus as conventional depletion accelerates. Appraisal drilling targets fractured shale intervals requiring specialized completion designs.
- Conventional:Established sandstone reservoirs with proven waterflood response in mature Greater Nile fields. 4D seismic monitoring tracks flood front movement to optimize infill locations.
- Offshore:Frontier deepwater blocks attract PETRONAS exploration expertise, though development remains pre-commercial pending resolution of pipeline security and transit fee structures with Sudan.
Onshore commands the established base. The steepest expansion runs through Tight Oil.
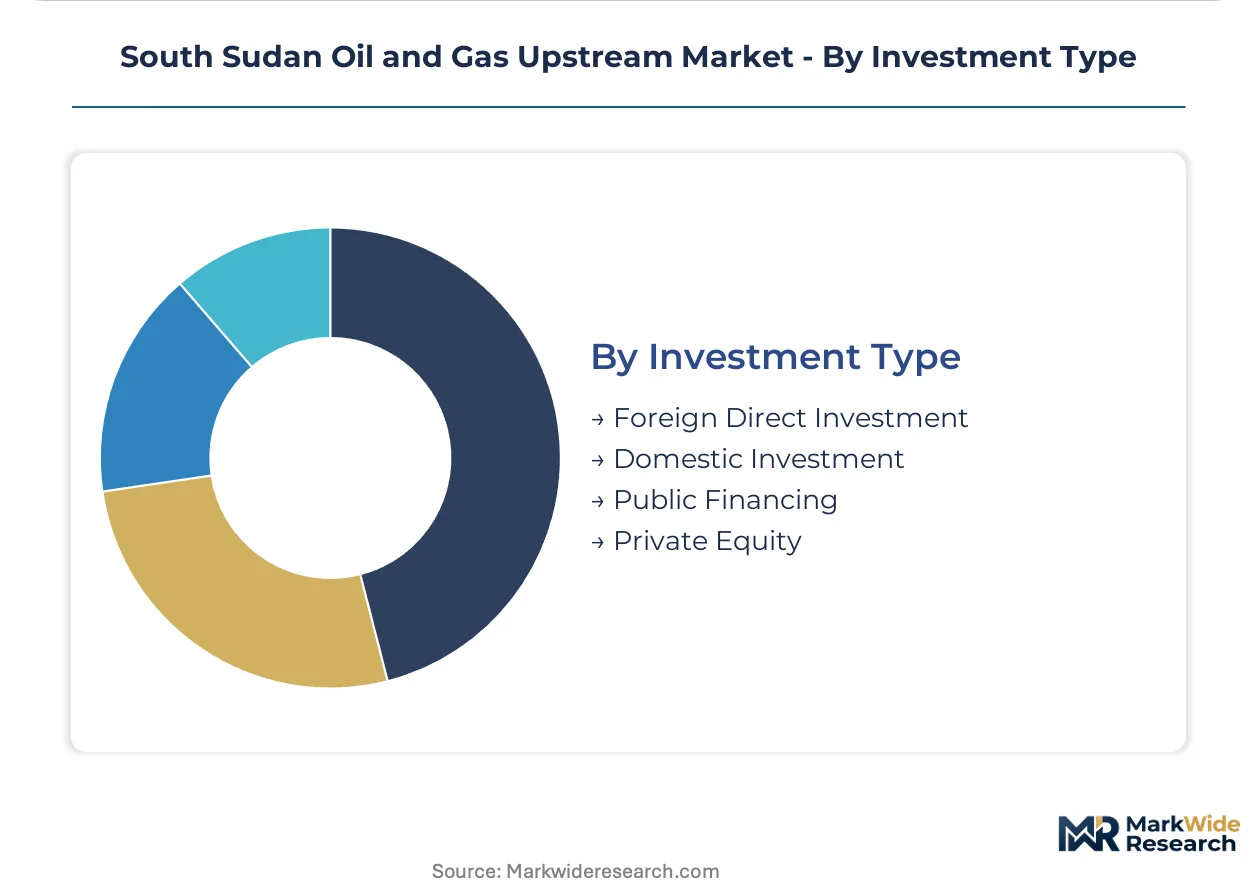
Investment Type:
Capital source determines risk tolerance and holding period expectations, with implications for field development pacing and technology transfer commitments.
- Foreign Direct Investment:Chinese state-owned operators anchor upstream capacity through integrated drilling, pipeline, and refining positions. Long-term offtake agreements secure evacuation routes for crude output.
- Private Equity:Mid-tier specialists pursue modular development architectures and digital reservoir surveillance to compress discovery-to-first-oil timelines. Capital discipline pressures favor unbundled service procurement.
- Domestic Investment:Indigenous participation requirements under local content regulations create structural demand for South Sudanese workforce and supplier capacity building.
- Public Financing:Limited sovereign capital deployment given fiscal constraints and competing budget priorities for infrastructure and security expenditure.
Foreign Direct Investment commands the established base. The steepest expansion runs through Private Equity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream investment elasticity varies sharply across South Sudan's producing basins. Melut Basin operators absorb higher exploration risk premiums, while Muglad Basin incumbents enjoy infrastructure proximity that insulates margins from transit volatility.
Upper Nile State
Dar Petroleum Operating Company manages the Palogue and Adar Yale fields, feeding the Dar export pipeline corridor. The Ministry of Petroleum's 2023 licensing round opened adjacent exploration blocks with revised cost recovery terms. Malakal serves as the logistics hub for northern basin drilling campaigns and workforce mobilization.
Unity State
Sudd Petroleum Operating Company and Greater Nile Petroleum Operating Company maintain production from mature Thar Jath and Unity field complexes. Local content regulations mandate South Sudanese workforce quotas that extend project staffing timelines. Bentiu anchors the regional supply chain for workover rig services and artificial lift equipment.
Jonglei State
Untested Melut Basin extensions attract exploration-focused operators seeking conventional reserve replacement. The National Petroleum and Gas Commission imposes environmental compliance bonds that inflate pre-drilling capital requirements. Bor functions as the southern logistics coordination point for seismic acquisition crews.
Lakes State
Frontier tight oil appraisal targets fractured shale intervals in rift basin source rocks below established conventional reservoirs. Production sharing agreement renegotiations have delayed final investment decisions on pilot drilling programs. Rumbek hosts emerging indigenous service contractor capacity under workforce development mandates.
Central Equatoria State
Juba concentrates administrative functions for Ministry of Petroleum licensing oversight and joint venture governance. The capital hosts technical offices for Chinese state-owned operators coordinating Greater Nile consortium activities. Domestic power generation demand from Juba's grid expansion creates captive offtake channels for marginal field production.
South Sudan Oil and Gas Upstream Market Competitive Landscape
Capability concentration sits with integrated state-owned enterprises holding pipeline and refining positions; scale advantage sits with specialized exploration operators deploying modular development architectures. The upstream structure divides between infrastructure-anchored incumbents and frontier-focused specialists. Three archetypes dominate: integrated national oil companies with captive evacuation routes, independent exploration specialists pursuing high-risk basin extensions, and hybrid consortium vehicles blending public and private capital. Competitive positioning hardens around pipeline access security and production sharing fiscal terms rather than pure technical differentiation.
Among Chinese state-owned operators, China National Petroleum Corporation and Sinopec occupy positions reflecting integrated infrastructure control and drilling service capability respectively. PETRONAS represents the deepwater exploration specialist archetype targeting frontier blocks. Oranto Petroleum exemplifies the independent African-focused explorer model. These three anchors illustrate how geographic origin and corporate structure shape strategic options within South Sudan's contractually fragmented upstream environment.
| Leading Market Players |
|---|
| Petroliam Nasional Berhad (PETRONAS) |
| Oranto Petroleum |
| Nile Petroleum Corporation |
| Dar Petroleum Operating Company |
| Greater Nile Petroleum Operating Company |
| China National Petroleum Corporation |
| Sinopec |
| Sudd Petroleum Operating Company |
| ONGC Videsh Limited |
| Others |
Value Network & Pricing Analysis
Malakal anchors northern basin logistics capacity, with its warehousing and workforce mobilization infrastructure concentrating supply-side leverage that translates into field development service pricing power for upstream operators bidding into Ministry of Petroleum licensing rounds.
Pricing Analysis
Workover rig availability premiums now drive lifetime contract value more than day-rate baselines, as operators fragment integrated drilling packages across directional drilling, logging-while-drilling, and completions specialists to optimize unit economics. Price differentiation hinges on local content compliance certification and security expenditure absorption capacity, with frontier exploration blocks commanding risk-adjusted premiums while mature Muglad Basin production faces margin compression from artificial lift maintenance inflation. Cost compression in exploration tiers is intensifying because National Petroleum and Gas Commission environmental bond requirements inflate pre-drilling capital thresholds. National oil company consortia show least price sensitivity due to integrated pipeline offtake positions, whereas private equity-backed independents exhibit highest sensitivity to service rate volatility.
Supply Chain Analysis
Chinese state-owned drilling contractors and Malaysian deepwater specialists hold dominant service capacity, with equipment and technical personnel drawing from China, Malaysia, and Singapore supply bases. Critical dependencies include specialized workover rigs, 4D seismic acquisition systems, and subsea wellhead components. Single-source vulnerability concentrates in directional drilling telemetry technology where patent-protected suppliers control niche segments. Distribution runs through Juba-based procurement coordination for administrative approvals, with physical logistics channeling through Malakal and Bentiu field supply depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Production sharing agreement fragmentation creates multiple entry niches as fiscal term renegotiations dislodge incumbent operator positions and local content mandates reshape partner selection criteria.
For Market Incumbents: Insulate pipeline infrastructure control through long-term offtake contract extensions with Dar corridor operators, while accelerating digital reservoir surveillance deployment to defend production decline curves against tight oil appraisal competitors. Vertical integration into modular service procurement reduces single-supplier concentration risk from unbundled drilling contracts. For New Entrants and Emerging Players: Melut Basin extension blocks with revised cost recovery terms represent the most penetrable entry point for exploration-focused specialists lacking legacy infrastructure positions. Target environmental compliance and field abandonment bond services as a go-to-market angle, where National Petroleum and Gas Commission mandates generate recurring revenue streams independent of crude price cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized remediation contractors holding environmental compliance bonds and workover rig service providers with multi-year maintenance agreements. Long-term viability across the projection horizon favors operators with demonstrated local content workforce development programs and established East African supplier networks. Monitor pipeline security incident frequency and Sudan transit fee arbitration outcomes as early inflection indicators for upstream investment IRR thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Workforce Development | Ministry of Petroleum contract templates mandate explicit domestic training floors that reshape partner selection. |
| Digital Reservoir Surveillance Deployment | 4D seismic monitoring capability migration enables smaller operators to optimize infill drilling without full-field simulation. |
| Modular Service Procurement Unbundling | Disaggregated directional drilling and completions contracts attract niche technical specialists previously excluded. |
| Environmental Compliance Bond Structuring | National Petroleum and Gas Commission field abandonment requirements generate recurring revenue for specialized contractors. |
| Regional Refinery Integration Agreements | East African downstream supply contracts create captive offtake channels reducing export terminal dependency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Ministry of Petroleum licensing documentation, Sudan transit fee arbitration records, and National Petroleum and Gas Commission environmental compliance filings. Interviews with drilling service procurement managers, reservoir engineering directors, and local content compliance officers at Dar and Greater Nile consortium operators combined with customs trade data, EIA crude export statistics, and IEA East African energy outlooks. Bottom-up field development cost modeling triangulates against top-down basin reserve estimates.
Forecast inputs include operation type capital intensity curves, contract structure fiscal term variations, and field type extraction technology requirements across the analysis window. Segmentation dimensions encompass operation phase, contractual framework, reservoir characteristics, and investment source origin. CAGRs derive from production decline curve analysis, exploration success rate assumptions, and infrastructure capacity expansion schedules. Pipeline security incident probability and Sudan transit fee volatility represent key scenario inputs.
Practitioners should monitor production sharing agreement renegotiation outcomes and local content regulation enforcement intensity for early signals of operator economics shifts. Forecasts reflect assumptions regarding sustained crude evacuation route functionality and exploration licensing round participation rates. Quarterly review of Ministry of Petroleum fiscal term announcements and National Petroleum and Gas Commission bond requirement adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market