
 Freight Audit and Payment Service Market | 2026-2036
Freight Audit and Payment Service Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Audit and Payment Service Market Insights
E-commerce retail is repositioning as the dominant demand vertical for freight audit and payment services, displacing traditional manufacturing procurement offices that historically managed carrier relationships manually. CTSI-Global leverages its integrated transportation management platform to anchor enterprise accounts across North America. Cass Information Systems sustains a competitive position through its bank-backed payment infrastructure that controls working capital cycles for Fortune 500 shippers. nVision Global differentiates via multi-modal audit capabilities spanning ocean, air, and ground freight.
Freight audit and payment services comprise systematic invoice verification, rate validation, accrual management, and carrier disbursement functions executed through specialized software platforms or managed service operations. These services apply algorithmic matching of carrier invoices against contracted rates, bills of lading, and proof-of-delivery documentation to eliminate overpayment and accelerate financial closure. Cloud-based solutions lead the technology segment due to their API connectivity with enterprise ERP systems and real-time dashboard accessibility. AI integration represents the fastest-expanding technology category as machine learning models detect anomalous billing patterns and predict accrual variances. Payment processing commands the largest margin pool within service types because transaction volume scales directly with shipper freight spend and retention cycles extend across multi-year contracts.
The US Department of Transportation enforces electronic logging and carrier compliance standards that generate structured data streams essential for automated audit validation. The European Union's CSRD and evolving supply chain due diligence directives require granular freight cost transparency that audit platforms must document for sustainability reporting. ISO standards for supply chain security and quality management further shape platform architecture and data retention protocols. Stakeholders must monitor regulatory divergence between US hours-of-service data formats and EU multimodal reporting requirements when selecting platform architectures that preserve cross-border interoperability.
Market Dynamics
Machine learning algorithms are compressing invoice processing cycles from weeks to hours, forcing freight audit providers to restructure service delivery models around real-time data pipelines rather than batch reconciliation.
Growth Catalysts
- US Electronic Logging Device Mandate:Hours-of-service tracking generates structured telematics data streams that enable automated freight invoice validation without manual intervention.
- E-commerce retail expansion:Multi-carrier parcel networks require algorithmic audit capabilities to reconcile thousands of daily invoices across competing delivery providers.
- Cloud API architectures:Real-time ERP connectivity allows shippers to embed freight payment workflows directly into treasury management systems.
Market Restraints
- Carrier data standardization gaps:Inconsistent EDI formats across North American trucking fleets force audit platforms to maintain expensive mapping libraries for each major carrier.
- European CSRD compliance costs:Granular carbon accounting requirements for freight spend transparency impose additional data collection burdens on audit service providers.
- Legacy TMS lock-in:Shippers with entrenched on-premise transportation management systems face high switching costs to adopt cloud-native audit platforms.
Strategic Opportunities
- India logistics digitization:GST e-invoicing mandates and FASTag toll integration create openings for automated freight audit platforms in underpenetrated domestic supply chains.
- AI-powered anomaly detection:Convergence of natural language processing with rate contract parsing enables automated identification of billing errors in unstructured carrier invoices.
- Ocean freight contract complexity:Multi-modal shippers seek unified audit platforms spanning container demurrage, detention, and bunker adjustment factor calculations.
Industry Challenges
- Data science talent scarcity:Freight audit providers compete with fintech and logistics technology firms for machine learning engineers capable of building predictive accrual models.
- Cross-border regulatory fragmentation:Divergent data retention requirements between US DOT hours-of-service formats and EU multimodal reporting standards complicate platform architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Audit and Payment Service Market |
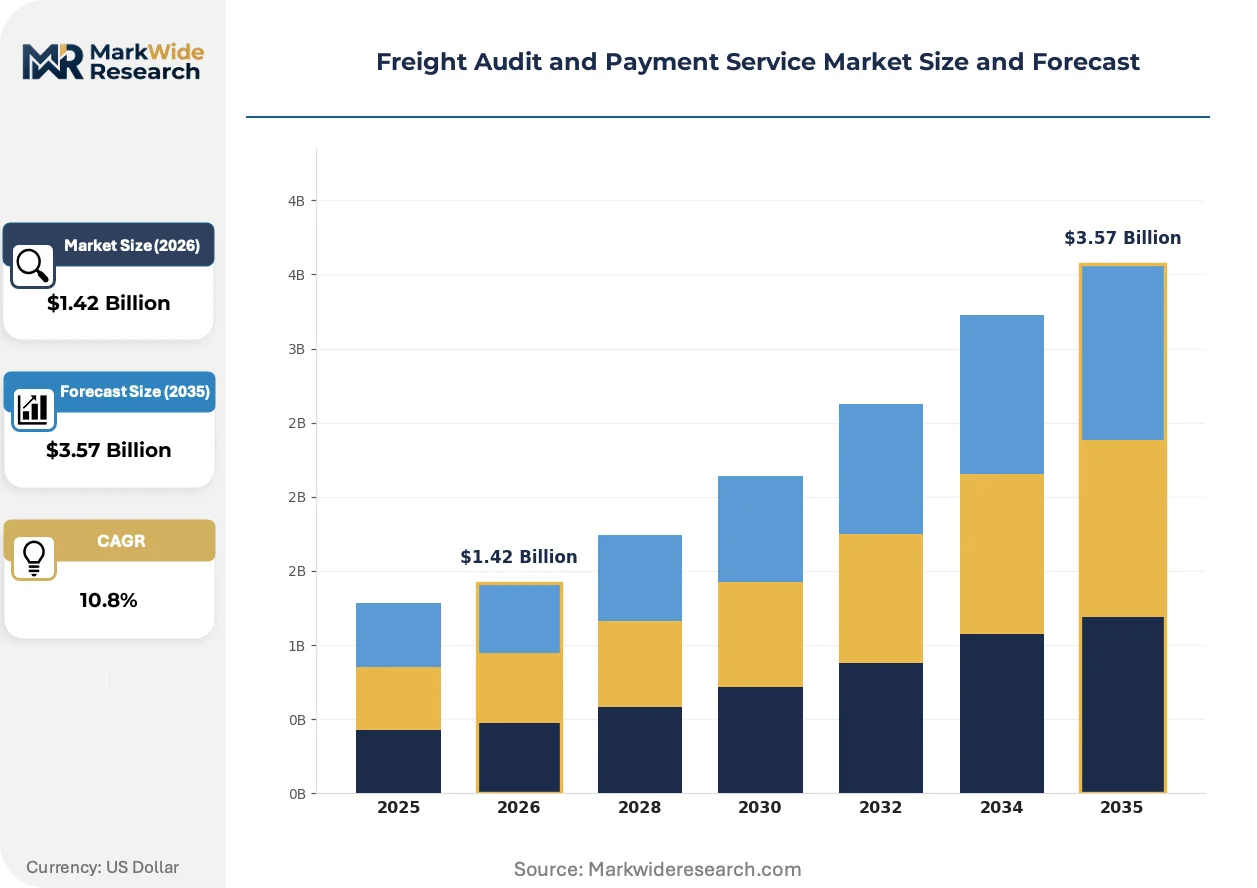
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.57 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Auditing Services, Payment Processing, Reporting Tools, Dispute Management End User: Shippers, 3PL Providers, Freight Forwarders, Retailers Technology: Cloud-Based Solutions, Software Platforms, Analytics Tools, AI Integration Pricing Model: Subscription-Based, Transactional Fees, Tiered Pricing, Custom Plans |
| Companies Covered | CTSI-Global, Transporeon Freight Audit, Cass Information Systems, Trax Technologies, nVision Global, CT Logistics, Blume Global, Data2Logistics, Intelligent Audit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Audit and Payment Service Market Trends and Innovations
Freight audit platforms are pivoting from retrospective invoice verification toward predictive financial planning tools that anticipate cost variances before carrier bills arrive.
Natural language processing engines are automating the extraction of rate terms from unstructured carrier contracts and bills of lading. Third-party logistics providers and large retail shippers are deploying these tools to eliminate manual data entry in invoice matching workflows. The technology is automating exception handling that previously required dedicated audit teams, compressing staffing requirements for high-volume freight payment operations.
The European Union's Corporate Sustainability Reporting Directive mandates granular disclosure of freight-related emissions and cost allocations across supply chain tiers. This regulatory pressure forces audit platforms to capture fuel surcharge methodologies, empty mile ratios, and modal shift data alongside traditional financial metrics. German automotive and chemical shippers face the most immediate compliance deadlines, driving demand for audit services that embed carbon accounting directly into invoice reconciliation.
Shippers are consolidating freight audit relationships from multiple regional providers toward single global platforms capable of harmonizing payment cycles across currencies and tax jurisdictions. Large manufacturing enterprises in the United States and Germany are terminating fragmented country-by-country audit contracts in favor of multi-year managed service agreements with unified data lakes. This concentration trend favors audit providers with bank-backed payment infrastructure and direct carrier settlement capabilities in multiple markets.
Freight Audit and Payment Service Market Segmentation
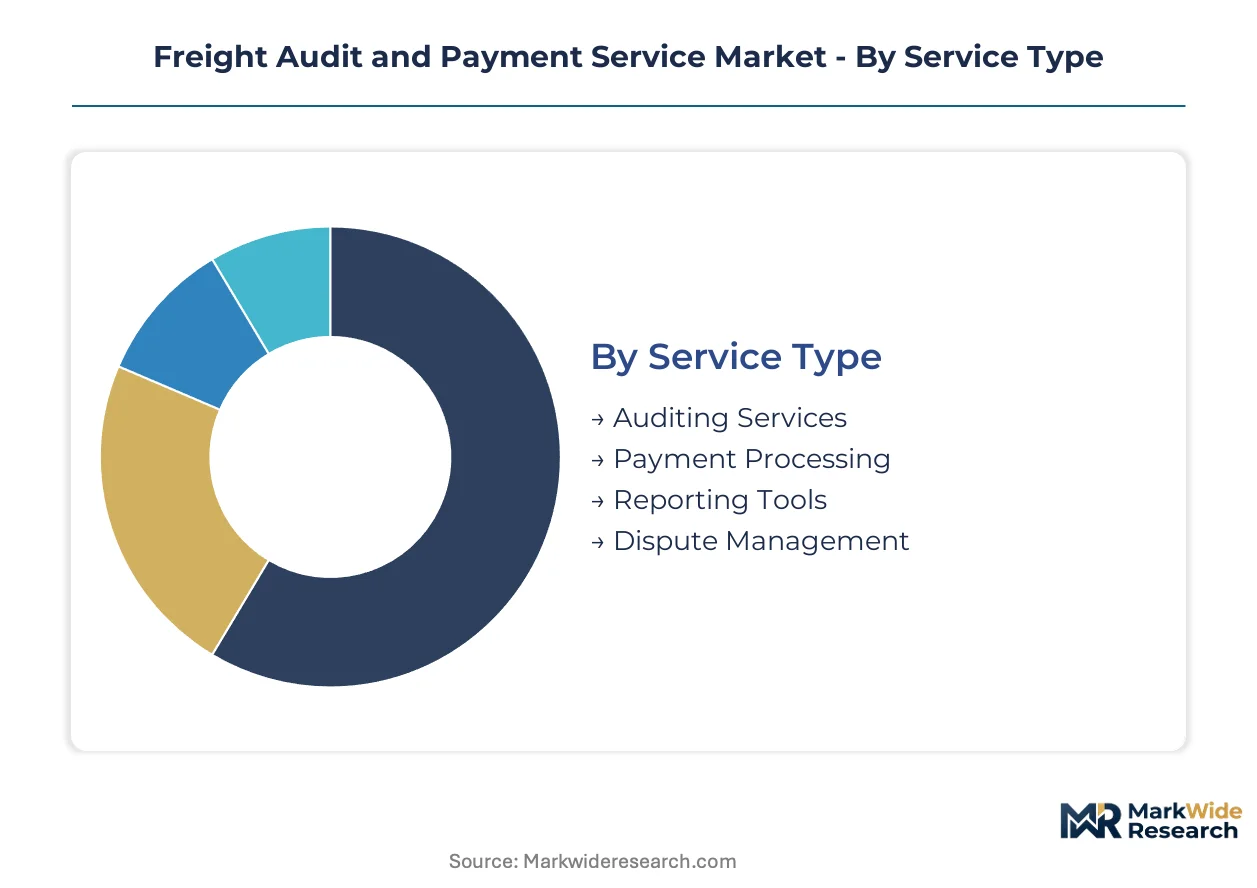
Freight audit and payment services fragment across four structural dimensions that determine platform architecture and revenue capture. Service type defines margin pools, technology selection dictates integration costs, and pricing model shapes customer lifetime value in this invoice-intensive market.
Service Type:
Standalone auditing modules dominate mid-market deployments, while payment processing anchors enterprise contracts through working capital control.
- Auditing Services:Algorithmic invoice verification against contracted rates, bills of lading, and proof-of-delivery documentation eliminates overpayment through systematic matching protocols. Retailers operating multi-carrier parcel networks in Germany and the United States concentrate demand here as daily invoice volumes exceed manual processing capacity.
- Payment Processing:Carrier disbursement functions executed through bank-backed infrastructure control treasury cycles and capture the largest margin pool through transaction volume scaling. Fortune 500 shippers favor providers with direct settlement capabilities across multiple currencies and tax jurisdictions.
- Reporting Tools:Dashboard accessibility for freight spend visibility and accrual management supports procurement governance requirements.
- Dispute Management:Automated exception handling for carrier billing disagreements reduces dedicated audit team staffing needs.
Payment processing leads volumes today; auditing services are gaining share fastest as e-commerce invoice complexity accelerates.
End User:
Shipper size determines feature depth, with enterprise accounts requiring embedded ERP connectivity and mid-market buyers accepting standalone portals.
- Shippers:Manufacturing and distribution enterprises with annual freight spend exceeding thresholds that justify dedicated audit investment. Chemical and automotive producers in Germany face immediate CSRD compliance deadlines that embed carbon accounting into invoice reconciliation workflows.
- 3PL Providers:Third-party logistics operators white-label audit capabilities to extend service portfolios for shipper clients.
- Freight Forwarders:Multi-modal intermediaries seek unified platforms spanning ocean demurrage, detention calculations, and bunker adjustment factors.
- Retailers:E-commerce operators with parcel-heavy networks drive algorithmic audit adoption for thousands of daily invoices across competing delivery providers.
Shippers anchor revenue concentration; retailers are expanding most quickly as digital commerce penetrates domestic supply chains.
Technology:
Deployment architecture separates real-time API connectivity from batch-processing legacy systems, with AI integration commanding premium pricing.
- Cloud-Based Solutions:API-enabled platforms with ERP embedding and real-time dashboard accessibility lead the technology segment through scalable infrastructure. The US Electronic Logging Device mandate generates structured telematics data streams that cloud architectures ingest for automated validation without manual intervention.
- AI Integration:Machine learning models detect anomalous billing patterns and predict accrual variances, representing the steepest expansion trajectory as natural language processing automates rate term extraction from unstructured carrier contracts.
- Software Platforms:On-premise or hybrid deployments serving shippers with entrenched TMS infrastructure and high switching costs.
- Analytics Tools:Predictive financial planning capabilities that anticipate cost variances before carrier bills arrive.
Cloud-based solutions dominate installed base; AI integration is climbing the fastest as data science investment concentrates in audit technology.
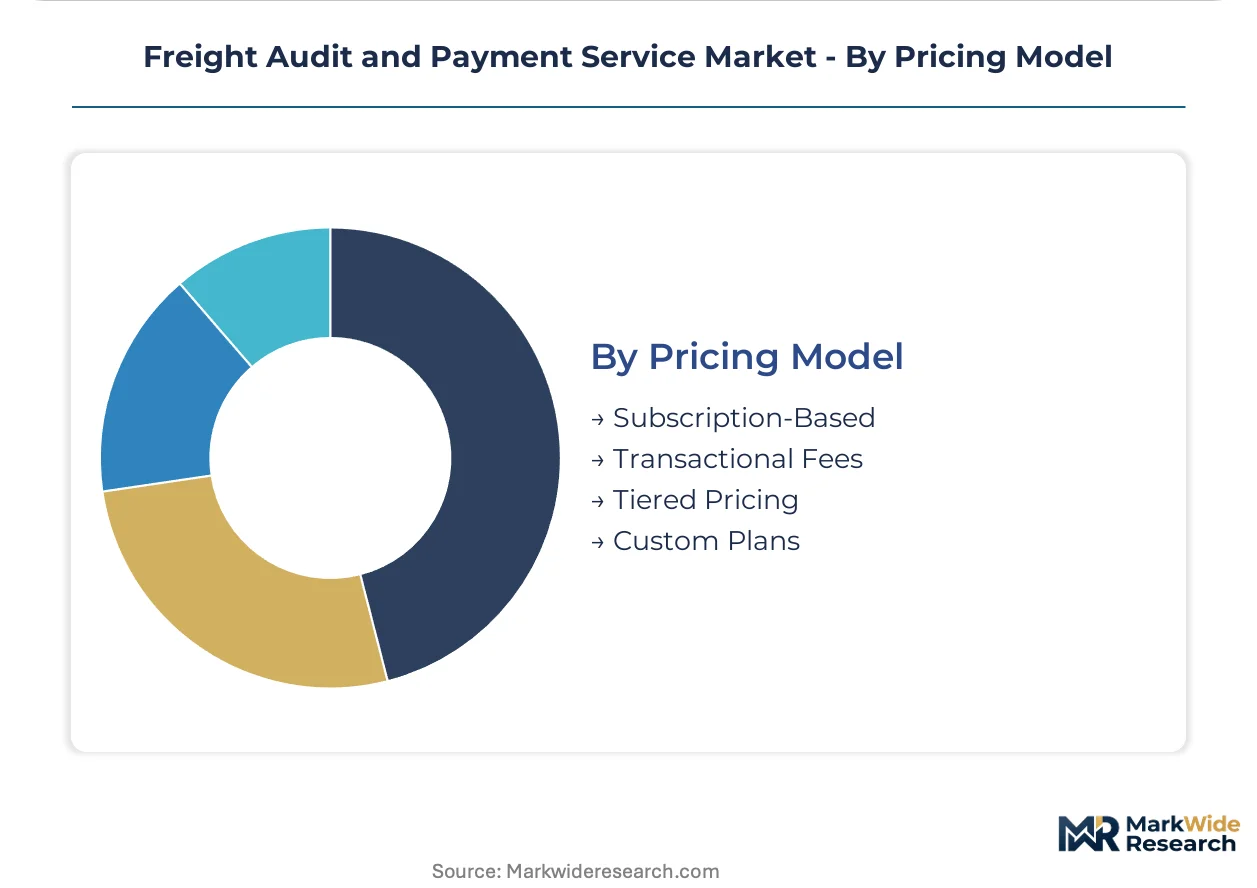
Pricing Model:
Revenue recognition timing separates predictable subscription streams from volume-linked transactional economics.
- Transactional Fees:Per-invoice or percentage-of-spend pricing scales directly with shipper freight volume and extends retention cycles across multi-year contracts. Large manufacturing enterprises in the United States and Germany favor this structure for cost alignment with activity levels.
- Subscription-Based:Fixed periodic fees for platform access and standard audit volumes, preferred by shippers with stable freight profiles seeking budget predictability.
- Tiered Pricing:Three-level differentiation across premium, standard, and economy service tiers based on feature depth and support levels.
- Custom Plans:Negotiated enterprise agreements for complex multi-modal or multi-jurisdictional requirements.
Transactional fees capture the largest revenue pool; subscription models are gaining traction fastest among mid-market shippers prioritizing cost certainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between US hours-of-service data formats and EU multimodal reporting standards creates compliance-cost arbitrage that shapes platform deployment decisions. Shippers route freight audit procurement toward jurisdictions with standardized electronic logging mandates that reduce data transformation overhead.
United States
E-commerce parcel networks in California and Texas drive algorithmic audit adoption for multi-carrier invoice reconciliation. The US Department of Transportation enforces Electronic Logging Device mandates that generate structured telematics streams for automated validation. Chicago and Atlanta logistics clusters concentrate demand from retail shippers managing thousands of daily invoices.
Germany
Automotive and chemical producers face immediate Corporate Sustainability Reporting Directive deadlines embedding carbon accounting into freight payment workflows. The EU CSRD mandates granular freight cost transparency that audit platforms must document for supply chain due diligence. The Rhine-Ruhr industrial corridor anchors enterprise demand from manufacturers harmonizing payment cycles across currencies.
China
Dense logistics networks in the Yangtze River Delta and Pearl River Delta require invoice reconciliation at scale as domestic e-commerce penetrates tier-two cities. The Ministry of Industry and Information Technology drives digitization standards that shape platform data architecture. Shanghai and Shenzhen clusters concentrate multi-modal shippers seeking unified audit capabilities spanning ocean, air, and ground freight.
India
GST e-invoicing mandates and FASTag toll integration create openings for automated audit platforms in underpenetrated domestic supply chains. The Central Board of Indirect Taxes and Customs enforces electronic invoice standards that reduce manual reconciliation requirements. Maharashtra and Gujarat logistics hubs concentrate early adoption among manufacturing exporters building dense distribution networks.
United Kingdom
Post-Brexit customs complexity elevates demand for audit platforms managing cross-border freight cost allocation and VAT reconciliation. The UK Environment Agency enforces emissions reporting standards that intersect with supply chain transparency requirements. The Midlands logistics corridor concentrates demand from retailers consolidating fragmented country-by-country audit contracts.
Freight Audit and Payment Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with bank-backed payment infrastructure providers controlling working capital cycles for Fortune 500 accounts while software-native platforms capture mid-market share through API connectivity. The market structure concentrates around three strategic archetypes: integrated transportation management platforms, bank-affiliated payment processors, and multi-modal audit specialists. M&A activity targets AI-enabled anomaly detection capabilities, while geographic expansion focuses on India and Southeast Asia logistics digitization.
Within the integrated platform tier, CTSI-Global anchors enterprise accounts across North America through its transportation management system. Cass Information Systems occupies a position exemplifying bank-backed payment infrastructure that controls treasury cycles. nVision Global represents the multi-modal specialization archetype spanning ocean, air, and ground freight audit capabilities.
| Leading Market Players |
|---|
| CTSI-Global |
| Transporeon Freight Audit |
| Cass Information Systems |
| Trax Technologies |
| nVision Global |
| CT Logistics |
| Blume Global |
| Data2Logistics |
| Intelligent Audit |
| Others |
Pricing and Supply Chain Analysis
Bank-affiliated payment processors and private-equity-rolled audit specialists dominate ownership structures, concentrating pricing discipline among providers with direct carrier settlement capabilities and compressing margins for standalone software vendors lacking treasury infrastructure.
Pricing Analysis
Direct-to-shipper contracts capture the dominant channel-margin layer, bypassing distributor markups that characterize legacy freight payment intermediaries. Three-tier pricing structure across premium, standard, and economy levels segments by API integration depth and accrual forecasting sophistication. Cost compression in mid-market SaaS tiers is intensifying because cloud-native entrants are undercutting established providers on per-invoice transactional fees. Small parcel e-commerce shippers exhibit the highest price sensitivity, while Fortune 500 manufacturers prioritize working capital control over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with North American EDI format libraries, where inconsistent carrier data standards force audit platforms to maintain expensive proprietary mapping architectures. Technology development concentrates in the United States, Germany, and India, with cloud infrastructure sourcing from hyperscale providers. Raw material dependencies include GPU clusters for AI model training, API gateway licenses, and compliance documentation databases. Tariff exposure runs through cross-border data transfer restrictions affecting EU-US freight cost reconciliation. Distribution runs through direct enterprise sales teams and embedded partnerships with transportation management system vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight audit and payment services constitute a late-cycle quality story as shippers consolidate fragmented regional contracts toward unified global platforms with embedded carbon accounting capabilities demanded by CSRD compliance deadlines.
For Market Incumbents: Deploy bank-backed payment infrastructure as the anchor lever to deepen carrier direct settlement relationships and extend contract retention cycles. Integrate natural language processing engines for automated rate contract parsing to defend against AI-native entrants. Acquire machine learning engineering teams in India to offset data science talent scarcity affecting predictive accrual model development. Address the threat of cloud-native mid-market disruptors by embedding treasury management APIs directly into shipper ERP systems. For New Entrants and Emerging Players: Third-party logistics providers represent the most accessible channel partner type for white-label audit capability deployment. Target India's GST e-invoicing mandate compliance gap as the most penetrable geography, where domestic supply chain digitization lags behind invoice automation adoption. Pursue ocean freight contract complexity as a specialized entry vector, offering unified demurrage and bunker adjustment factor calculations that incumbent platforms handle through fragmented modules. Develop FASTag toll integration expertise to anchor early relationships with Maharashtra and Gujarat manufacturing exporters. For Investors and Strategic Acquirers: Transportation management system vendors are the most active acquirer in this space, seeking to complete platform stacks with payment and audit functionality. The five-to-ten year viability window favors providers with multi-currency settlement licenses and direct carrier API connectivity across three or more countries. Target acquisition archetype: AI-enabled anomaly detection specialists with proven natural language processing rate extraction capabilities. Monitor CSRD enforcement consistency across German automotive and chemical producers as the signal to watch for carbon accounting feature premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Anomaly Detection | Machine learning models trained on ELD telematics data compress invoice exception handling from weeks to hours. |
| Multi-Modal Audit Platform Integration | Unified ocean-air-ground capabilities address container demurrage complexity sought by global manufacturers. |
| Bank-Backed Payment Infrastructure Expansion | Direct carrier settlement licenses in India and Southeast Asia unlock working capital control in underpenetrated markets. |
| Carbon Accounting Module Development | CSRD-compliant freight emissions tracking embeds sustainability reporting directly into invoice reconciliation workflows. |
| Natural Language Processing Rate Extraction | NLP engines automate unstructured carrier contract parsing, eliminating manual data entry in high-volume operations. |
Research Methodology
Multiple input streams — structured interviews with freight audit platform executives, procurement directors at multi-modal shippers, treasury management officers at Fortune 500 manufacturers, and carrier relationship managers at 3PL providers — were reconciled against secondary validation from US DOT ELD mandate filings, EU CSRD implementation guidance, SEC 10-K disclosures from bank-affiliated payment processors, and customs data on freight invoice volumes. Bottom-up segment sizing across service type, technology deployment, and end-user vertical was triangulated with top-down market boundary analysis from logistics technology analyst reports.
Historical growth patterns from cloud SaaS adoption curves and AI integration investment cycles were cross-referenced against panel input from shipper technology procurement committees to construct the analytical framework. Segmentation dimensions modeled include service type, deployment architecture, organization size tier, freight spend volume band, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to technology adoption thresholds and compliance deadline impacts. Forecast inputs incorporated ELD data granularity expansion timelines and GST e-invoicing mandate rollout schedules.
Revisions become necessary when carrier data standardization initiatives achieve material EDI format harmonization, when CSRD enforcement intensity diverges across member states, or when hyperscale cloud providers enter direct freight payment services. Forecasts reflect documented assumptions about API connectivity penetration rates and shipper consolidation behavior toward global platform contracts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Real Time Payments Market
Payments
MENA Digital Payments Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Portugal POS Terminals Market
Payments
France Mobile Payment Market
Payments
Smart Home Payments Market
Payments
Croatia POS Terminals Market
Payments
Global Payment Processor Market
Payments
In-Vehicle Payment Services Market
Payments
Europe Accounts Payable Automation Market
Payments
Ireland POS Terminals Market
Payments
US Buy Now Pay Later Services Market
Payments
Canada Mobile Payments Market
Payments
India Gift Card and Incentive Card Market
Payments
China Prepaid Cards Market
Payments
Uganda Mobile Money Market