
 Spain Payments Market | 2026-2036
Spain Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Payments Market Analytics
Merchant acquiring relationships among Spain's mid-market retailers is consolidating toward fewer full-service platforms. Banco Santander anchors domestic clearing infrastructure through Redsys Servicios de Procesamiento S.L., which operates Spain's dominant card payment network. Adyen N.V. competes for cross-border e-commerce volume with unified acquiring and issuing capabilities. Worldline S.A. specializes in European omnichannel terminals and merchant services across Iberian retail chains.
Spain payments encompass electronic fund transfer systems, card networks, digital wallets, and real-time settlement rails that process consumer and commercial transactions through encrypted authorization protocols and tokenized credential exchange. These systems serve retail commerce, utility billing, payroll distribution, and treasury operations by replacing cash handling with auditable, interoperable digital records. Credit card and mobile wallet methods lead transaction volume as contactless and NFC technology displace mag-stripe terminals at Spanish points of sale. Peer-to-peer and subscription transaction types expand fastest among Gen Z and millennial customer segments, where QR code interfaces reduce friction for split bills and recurring digital services.
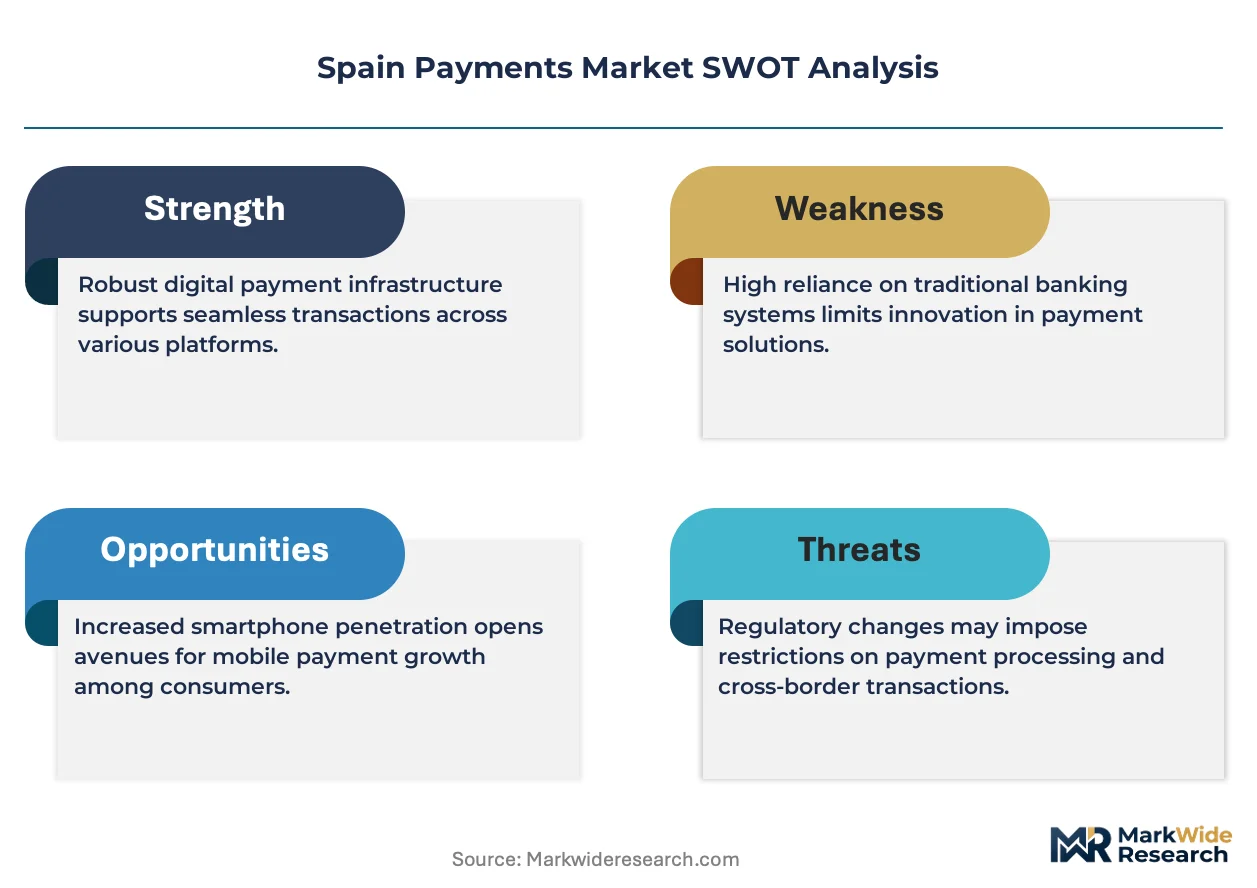
The Bank of Spain supervises payment service providers under European Central Bank oversight, while the Spanish Data Protection Agency enforces GDPR-compliant transaction data handling. DORA implementation tightens operational resilience requirements for critical payment infrastructure, raising compliance costs for domestic fintech entrants. Stakeholders must weigh regulatory capital demands against the margin compression from real-time payment commoditization.
Market Dynamics
Spain's payment infrastructure is consolidating around platform-integrated acquiring solutions as mid-market retailers abandon fragmented point solutions for unified omnichannel stacks. The European Commission's DORA framework accelerates this shift by raising operational resilience thresholds that favor scaled providers with compliance depth.
Growth Catalysts
- Real-time settlement rails:The Bank of Spain's instant payment infrastructure reduces merchant working capital cycles. Retailers in Barcelona and Madrid are migrating treasury operations to these rails.
- Contactless terminal mandates:Spanish point-of-sale regulations now require NFC-enabled devices. Terminal refresh cycles are compressing as mag-stripe hardware reaches end-of-life.
- Embedded finance workflows:SaaS platforms serving Iberian SMEs are integrating payment acceptance into vertical software. This reduces merchant onboarding friction for service-sector businesses.
Market Restraints
- Compliance cost escalation:DORA implementation demands redundant data centers and penetration testing regimes. Domestic fintech entrants face capital requirements that favor established banks.
- Interchange fee compression:EU caps on card-present transaction economics squeeze acquirer margins. Merchant pricing pressure intensifies as real-time alternatives commoditize settlement.
- Legacy core dependency:Regional Spanish banks operate on aging payment switches that resist API modernization. Migration timelines extend as core banking replacements stall.
Strategic Opportunities
- Andalusian and Valencian SME penetration:Merchant acquiring density remains below Madrid and Barcelona levels. Platform providers can capture underserved service economies in secondary cities.
- Request-to-pay infrastructure:The European Payments Council's R2P standard enables invoice-linked settlement. Spanish utilities and B2B marketplaces are piloting these workflows.
- Cross-border e-commerce orchestration:Iberian retailers selling into France and Portugal need multi-currency acquiring. Unified platforms can displace correspondent banking arrangements.
Industry Challenges
- Cloud resilience certification:DORA requires payment infrastructure operators to demonstrate third-party risk management. Achieving auditor sign-off for cloud-native architectures consumes 12-18 month implementation windows.
- Token vault interoperability:Proprietary credential storage systems fragment merchant portability. Spanish retailers demand network-agnostic tokenization that acquirers are slow to deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Payments Market |
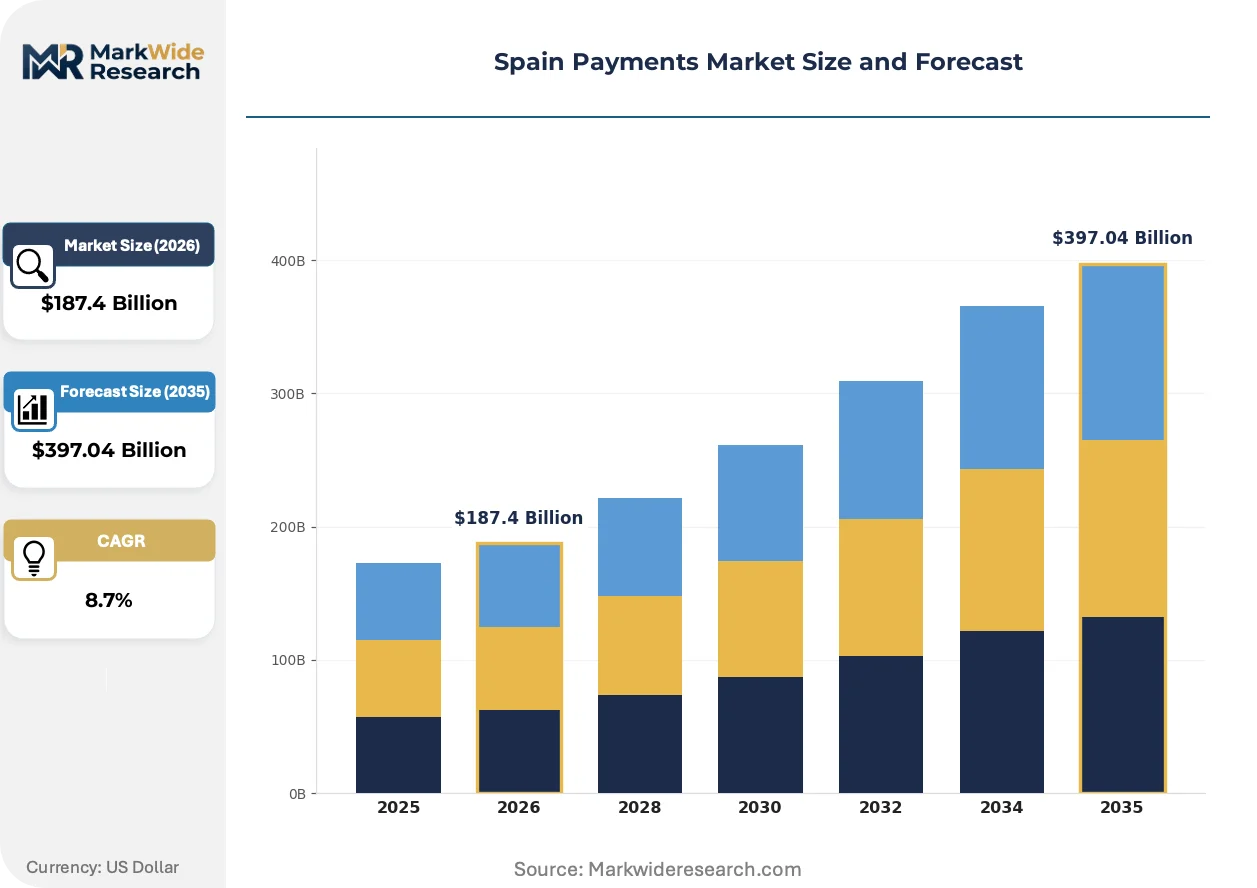
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Transaction Type: Online, In-Store, Subscription, Peer-to-Peer Customer Segment: Millennials, Gen Z, Small Businesses, Corporates Technology: Contactless, Blockchain, QR Code, NFC |
| Companies Covered | Visa Inc., Mastercard Incorporated, PayPal Holdings, Inc., Stripe, Inc., Adyen N.V., Redsys Servicios de Procesamiento S.L., Banco Santander, S.A., Google Pay, Worldline S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Payments Market Evolving Landscape
Payment orchestration layers are reshaping how Spanish merchants route transactions across multiple acquirers and alternative payment methods. This architectural shift favors technology-agnostic platforms over single-network dependencies.
Biometric authentication at Spanish point-of-sale terminals is converging with card-present transaction flows. Large-format retail chains in Madrid are piloting palm-vein and facial recognition for high-value purchases. This convergence is compressing checkout times while raising fraud thresholds that traditional PIN entry cannot match.
The European Commission's Digital Operational Resilience Act imposes mandatory incident reporting and third-party risk management on payment service providers. Spanish infrastructure operators must now map critical dependencies and conduct threat-led penetration testing. Mid-tier fintechs are responding by outsourcing compliance functions to specialized audit firms rather than building in-house capabilities.
Merchant procurement of payment acceptance is fragmenting across specialized providers for online, in-store, and marketplace channels. Spanish retailers are unbundling omnichannel contracts that previously locked them into single acquirer relationships. This unbundling is most visible among fast-fashion and grocery verticals where channel-specific optimization outweighs administrative simplicity.
Spain Payments Market Segmentation
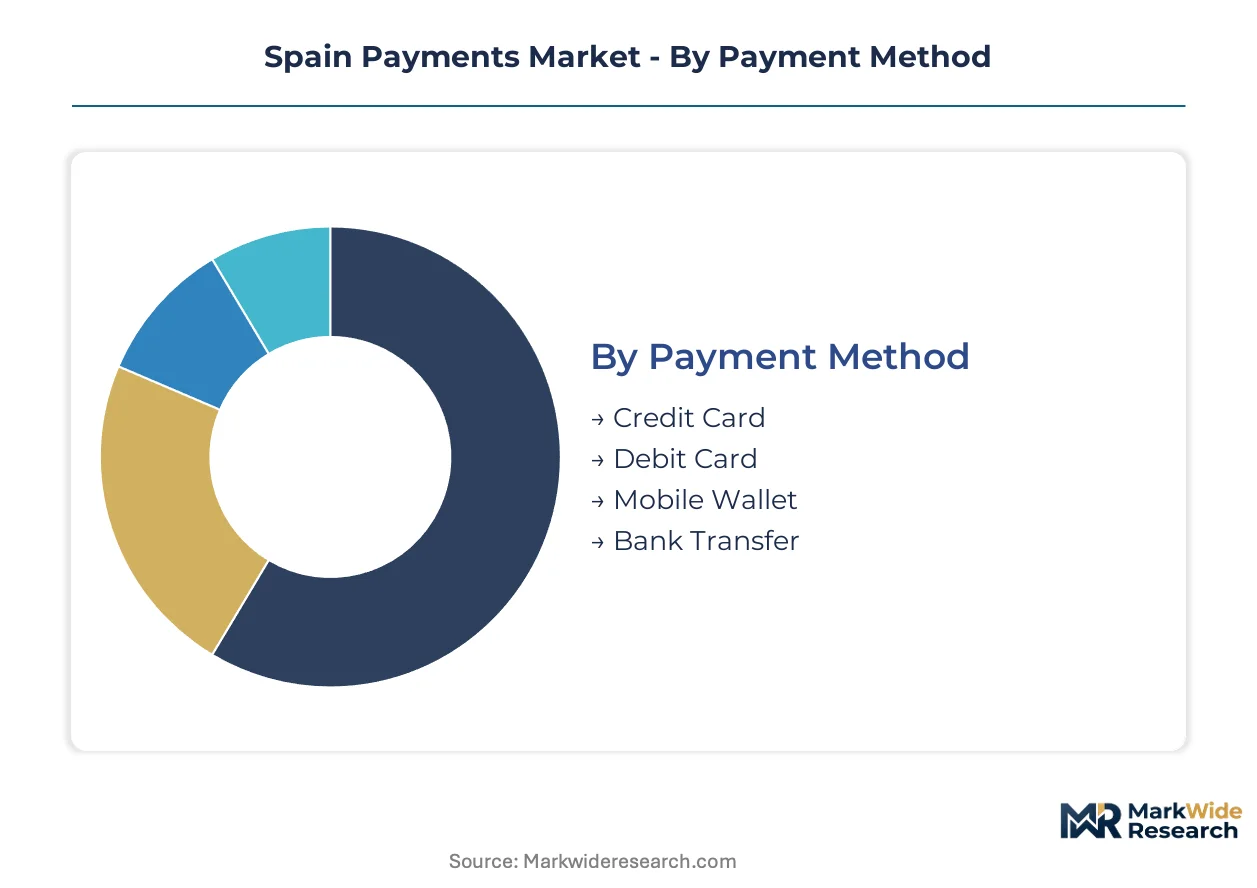
Payment method and transaction type segmentation reveals how Spanish merchants configure acceptance infrastructure around channel-specific requirements. Customer and technology segments expose divergent investment priorities across generational cohorts and hardware refresh cycles.
Payment Method:
Credit and debit card rails operate as standalone acquiring relationships for large merchants, while mobile wallets and bank transfers embed deeper into SaaS platforms serving SMEs.
- Credit Card:Revolving credit instruments process high-ticket retail purchases through four-party network schemes. Madrid department stores and Barcelona luxury retail anchor volume concentration, though interchange caps under EU regulation compress acquirer economics on these transactions.
- Debit Card:Direct account deduction instruments dominate grocery and fuel verticals where transaction velocity outweighs ticket size. Spanish regional banks push debit issuance to capture deposit-funded payment flows that bypass credit risk provisioning.
- Mobile Wallet:Tokenized credential storage on smartphones enables one-tap transit and quick-service restaurant payments. Gen Z adoption in Valencia and Seville drives merchant enablement of Apple Pay and Google Pay acceptance.
- Bank Transfer:Account-to-account settlement through SEPA Instant Credit Transfer rails displaces cards for B2B invoices and utility billing. Spanish utilities pilot request-to-pay messaging to trigger these transfers at invoice presentment.
Credit card leads volumes today; mobile wallet is gaining share fastest.
Transaction Type:
Cost tier segmentation separates high-friction onboarding for online and subscription merchants from low-touch in-store and P2P activation.
- Online:Card-not-present transactions require 3-D Secure authentication and fraud screening layers. Cross-border e-commerce from Iberian retailers into France and Portugal demands multi-currency acquiring that raises processing costs versus domestic settlement.
- In-Store:Card-present transactions through NFC-enabled terminals dominate grocery and fast-fashion verticals. Contactless terminal mandates from Spanish regulators accelerate hardware refresh cycles at smaller merchants.
- Subscription:Recurring billing workflows embed into SaaS platforms serving Spanish software and media companies. Strong Customer Authentication exemptions under PSD2 reduce friction for repeat transactions.
- Peer-to-Peer:Split-payment and remittance flows concentrate among Gen Z users in Madrid and Barcelona. Bizum, the Spanish banking consortium platform, dominates domestic P2P volume through mobile phone number routing.
In-store transactions anchor acquiring revenue today; subscription billing climbs the fastest.
Customer Segment:
Volume concentration among corporates and small businesses shapes merchant acquiring sales motion, while generational segments dictate authentication and interface preferences.
- Millennials:Cohort aged 28-43 drives mobile-first banking adoption and subscription service density. This segment's payment behavior favors biometric authentication over password entry.
- Gen Z:Digital-native cohort exhibits highest P2P and QR code payment velocity. Spanish fintechs target this segment with social payment features and split-bill functionality.
- Small Businesses:Service-sector SMEs in Andalusia and Valencia remain underpenetrated by integrated acquiring platforms. Embedded finance workflows reduce onboarding friction for these merchants.
- Corporates:Large enterprises demand treasury integration and multi-acquirer routing for payment resilience. DORA compliance requirements favor established bank relationships over fintech alternatives.
Corporate relationships generate highest revenue per merchant today; small business acquisition expands most quickly.
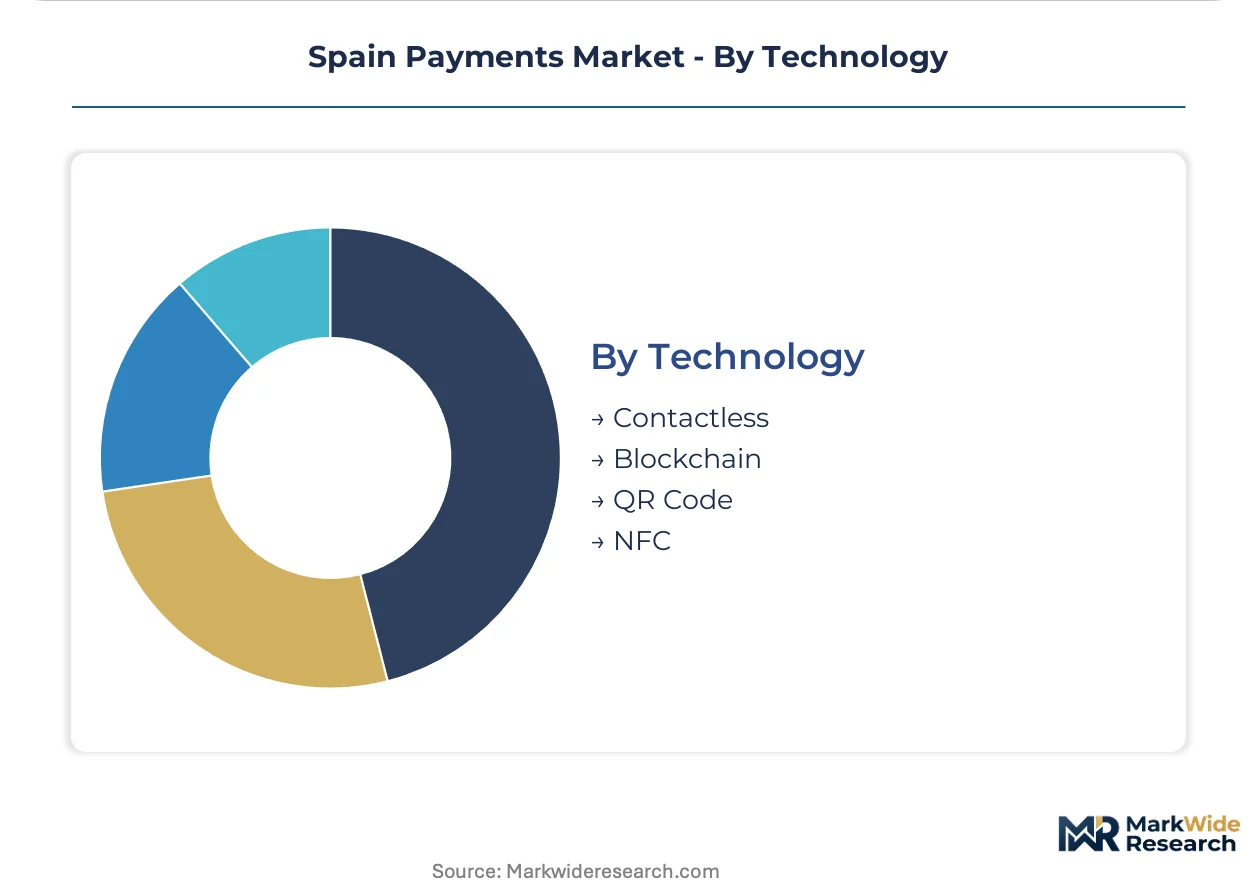
Technology:
Maturity segmentation separates contactless and NFC as proven infrastructure from blockchain and QR code as emerging rails requiring merchant education.
- Contactless:Tap-to-pay card and phone interfaces dominate Spanish point-of-sale volume. Terminal mandates ensure near-universal merchant acceptance in Madrid and Barcelona retail corridors.
- Blockchain:Distributed ledger settlement remains experimental for cross-border remittance and B2B invoice financing. Spanish regulators apply anti-money laundering scrutiny to crypto-asset payment providers.
- QR Code:Static and dynamic code interfaces enable low-cost merchant acceptance without terminal hardware. Street vendors and market traders in Valencia adopt these rails to avoid rental fees.
- NFC:Near-field communication protocols enable sub-second transaction authorization at transit gates and quick-service restaurants. Large-format retailers pilot biometric-NFC convergence for high-value purchases.
Contactless and NFC anchor transaction volume today; QR code deployment shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's payment infrastructure maturity contrasts with Portugal's slower real-time rail adoption, creating divergent competitive dynamics across the Iberian Peninsula. Both markets face identical EU regulatory frameworks but deploy divergent merchant acquiring strategies.
Madrid
Madrid anchors Spain's payment processing concentration through Banco Santander's clearing infrastructure and Redsys network operations. The Bank of Spain's supervisory headquarters enforces PSD2 and DORA compliance thresholds for domestic fintech licensing. Corporate treasury departments in the capital's financial district pilot request-to-pay workflows for B2B invoice settlement.
Catalonia
Barcelona's retail and tourism economy drives dense contactless terminal deployment across hospitality and fast-fashion verticals. Catalan merchants face identical EU interchange caps but negotiate harder on acquirer pricing due to cross-border French commerce. The region's software-as-a-service cluster embeds payment acceptance into vertical platforms serving Mediterranean SME exporters.
Basque Country
Bilbao and San Sebastián host industrial manufacturers adopting SEPA Instant Credit Transfer for supplier payments. Basque regional development agencies subsidize SME digitalization programs that include payment terminal upgrades. The concentration of automotive suppliers creates B2B payment automation demand distinct from consumer-facing retail patterns.
Andalusia
Seville and Málaga exhibit lower merchant acquiring density than northern metros, creating whitespace for platform-integrated solutions. Andalusian tourism operators require multi-currency acquiring for Northern European visitors. Regional banks lag in API modernization, forcing merchants toward fintech intermediaries for embedded finance workflows.
Valencia
Valencia's port logistics and agricultural export sectors drive trade finance payment automation distinct from retail patterns. The city's growing tech workforce accelerates mobile wallet adoption among Gen Z consumers. Street vendors and market traders pioneer QR code acceptance to avoid terminal rental fees.
Spain Payments Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's payment infrastructure. Global card networks and bank-owned processors dominate transaction volume, while fintech challengers capture embedded finance and cross-border e-commerce niches. Two strategic archetypes prevail: vertically integrated banking groups with captive merchant bases, and technology-agnostic platforms unbundling omnichannel acceptance. Consolidation accelerates through acquiring mergers and cloud infrastructure partnerships.
Within the bank-integrated tier, Banco Santander S.A. and Redsys Servicios de Procesamiento S.L. anchor domestic clearing relationships through Spain's dominant card network. Technology-agnostic specialists include Adyen N.V., which occupies a position representing unified acquiring and issuing capabilities for cross-border merchants. These entities exemplify divergent strategic postures—captive infrastructure versus platform openness—in a market where DORA compliance costs increasingly favor scaled providers.
| Leading Market Players |
|---|
| Visa Inc. |
| Mastercard Incorporated |
| PayPal Holdings, Inc. |
| Stripe, Inc. |
| Adyen N.V. |
| Redsys Servicios de Procesamiento S.L. |
| Banco Santander, S.A. |
| Google Pay |
| Worldline S.A. |
| Others |
Value Network & Pricing Analysis
Mid-market retailers in Barcelona and Madrid concentrate payment infrastructure procurement around platform-integrated acquiring solutions, locking in subscription-tiered pricing models that bundle hardware, software, and compliance services into predictable monthly fees. This buyer concentration gives scaled providers pricing power while squeezing point-solution vendors into commodity transactional rates.
Pricing Analysis
Capacity additions in Ireland and the Netherlands are reshaping price floors for cloud-native payment infrastructure across Iberia. Three-tier pricing structure across premium, standard, and economy levels dominates merchant acquiring contracts, with differentiation hinging on DORA compliance certification depth and real-time settlement SLA guarantees. Pricing pressure stems from SEPA Instant Credit Transfer commoditization displacing card-present economics. Small businesses in Andalusia exhibit highest price sensitivity, while corporate treasuries in Madrid prioritize resilience over marginal cost savings.
Supply Chain Analysis
Terminal refurbishment and end-of-life hardware returns flow through reverse-logistics networks anchored in Germany and Poland, where payment device remanufacturing concentrates. Payment terminal production draws from Taiwan, China, and Vietnam, with semiconductor components sourced from South Korea and Japan. Single-source vulnerability in NFC chip supply creates exposure to foundry allocation decisions. Distribution runs through Redsys-operated domestic clearing nodes before last-mile deployment to merchant locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain Payments Market functions as a stable compounder anchored by regulatory-mandated infrastructure refresh cycles that guarantee recurring revenue streams for compliant providers.
For Market Incumbents: Cement dominance in DORA-compliant infrastructure by acquiring cloud-resilience certification ahead of mid-tier fintechs. Prioritize backward integration into token vault operations to reduce third-party dependency. The European Commission's operational resilience deadlines threaten non-compliant challengers with licensing revocation, creating consolidation opportunity for prepared incumbents. For New Entrants and Emerging Players: DORA in Spain opens a window for specialized compliance-as-a-service providers serving domestic fintechs lacking capital for in-house audit functions. Target Andalusian and Valencian SME merchants underserved by integrated platforms, using embedded finance partnerships with vertical SaaS vendors as primary go-to-market channel. For Investors and Strategic Acquirers: Spanish banking conglomerates are the most active acquirer in this space, seeking technology-agnostic platforms to modernize legacy core dependencies. The market supports long-term viability through embedded finance penetration in service-sector verticals. Monitor SEPA Instant Credit Transfer volume share versus card-present transactions as inflection indicator for infrastructure valuation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Resilience Certification | DORA compliance creates licensing moat against undercapitalized fintech entrants. |
| Embedded Finance Integration | Vertical SaaS partnerships capture Andalusian SME merchants outside Madrid-Barcelona corridor. |
| Request-to-Pay Infrastructure | European Payments Council standard enables B2B invoice automation for Basque manufacturers. |
| Cross-Border E-commerce Orchestration | Multi-currency acquiring displaces correspondent banking for Iberian retailers exporting to France. |
| Biometric Authentication Deployment | Palm-vein and facial recognition pilots at Madrid retailers compress checkout times below NFC thresholds. |
Research Methodology
Bottom-up merchant acquiring modeling reconciled against top-down payment volume tracking forms the analytical core of this study. Primary interviews with payment operations executives at Spanish retail chains, treasury directors at industrial manufacturers, compliance officers at domestic fintechs, and platform engineers at embedded finance providers combined with secondary validation from Bank of Spain statistical bulletins, European Central Bank payment statistics, SEPA Instant Credit Transfer volume disclosures, and DORA implementation guidance documents.
Historical trendline analysis across transaction type evolution, payment method migration, and regional penetration patterns established baseline growth trajectories. The forecast framework segments by payment method, transaction type, customer cohort, and technology maturity, with CAGR derivation anchored in regulatory mandate timelines and hardware refresh cycle assumptions. Model inputs include DORA compliance cost estimates, terminal deployment schedules, and real-time rail adoption curves.
Revisions become necessary when regulatory enforcement intensity shifts, core banking modernization stalls extend, or alternative payment method adoption accelerates beyond modeled trajectories. Practitioners should monitor European Commission DORA audit findings and SEPA Instant volume reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Bitcoin Payments Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Mobile Wallet Market
Payments
Bus Card Reader Market
Payments
3D Secure Payment Authentication Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Contactless Payment Market
Payments
Global Payment Gateways Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Retail Point of Sale (POS) Market
Payments
Japan Credit Cards Market
Payments
Proximity Mobile Payment Market
Payments
United Kingdom Real Time Payments Market
Payments
Mobile Money Market
Payments
France Mobile Payment Market
Payments
Southeast Asia POS Terminal Market