
 North America POS Terminal Market | 2026-2036
North America POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
North America POS Terminal Market Analytics
Mexico is narrowing its manufacturing gap through expanded electronics assembly capacity in Tijuana and Guadalajara, drawing component suppliers closer to North American end markets. Square, Inc. leverages integrated software-hardware ecosystems to sustain merchant retention across small-business segments. PAX Technology anchors production scale for terminal hardware distributed throughout the region. NCR Voyix Corporation competes through vertical specialization in restaurant and hospitality deployments.
A POS terminal constitutes an electronic payment processing device combining secure card-reading hardware, encrypted communication modules, and transaction management software operating at PCI DSS Level 1 certification standards, designed to authenticate and route consumer payments to merchant acquiring networks. Terminal hardware retains the largest installed base across retail storefronts, though cloud-based deployment architectures capture the fastest expansion as merchants seek remote management and real-time analytics. Mobile POS solutions differentiate through lower capital requirements and line-busting flexibility in restaurants, while integrated systems concentrate margin pools through recurring software attach rates.
PCI DSS standards enforced by the PCI Security Standards Council govern encryption and data-handling protocols, while the U.S. Federal Reserve and Canada's Department of Finance shape payment system access rules and interchange fee structures affecting terminal economics. The U.S. FCC maintains electromagnetic emissions standards for wireless-enabled devices, and state-level privacy statutes in California and Canada federal privacy law increasingly influence data collection practices embedded in POS software. Stakeholders must weigh cloud migration timelines against the durability of on-premise legacy footprints as regulatory fragmentation deepens across provincial and state jurisdictions.
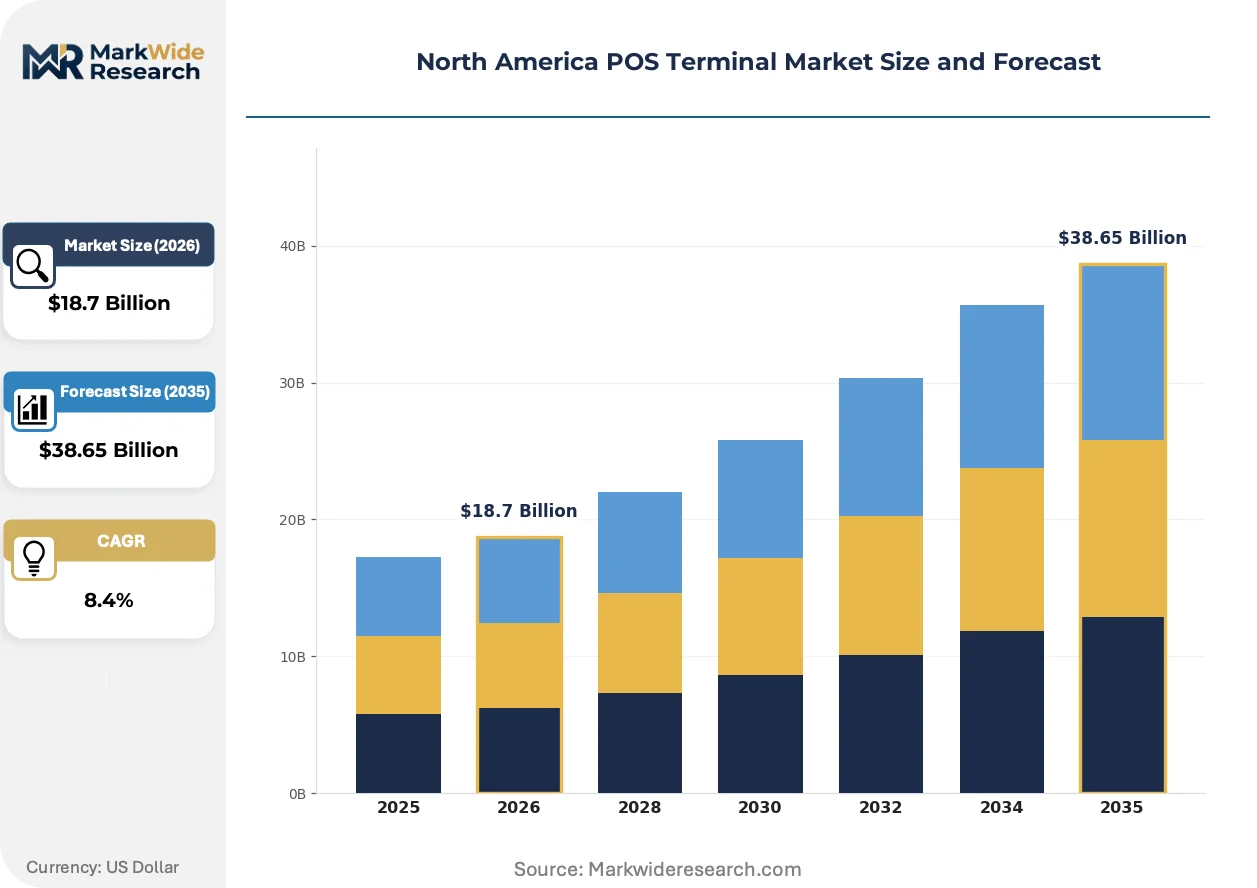
Market Dynamics
Cloud-connected terminal architectures are compressing hardware refresh cycles across quick-service restaurants and retail storefronts, forcing incumbent vendors to restructure software attach-rate economics around recurring revenue streams rather than one-time device sales.
Growth Catalysts
- PCI DSS Level 1 Certification Mandates:Merchants facing liability exposure from EMV chip standards are replacing countertop units at accelerated pace, driving replacement demand across the U.S. Northeast corridor.
- Quick-Service Restaurant Digital Transformation:Line-busting mobile POS deployments in high-volume foodservice environments are expanding terminal density per location beyond traditional single-counter configurations.
- Mexico Electronics Assembly Expansion:Tijuana and Guadalajara production clusters are shortening component lead times for North American terminal manufacturers, reducing supply chain latency against Asian sourcing.
Market Restraints
- Semiconductor Component Concentration:Secure encryption chip fabrication remains concentrated in a limited supplier base, creating input cost volatility and allocation risk for terminal OEMs.
- California Consumer Privacy Act Friction:State-level data collection restrictions complicate customer analytics software integration, forcing architecture redesigns for multi-state merchants.
- Legacy System Interoperability Barriers:Proprietary communication protocols in installed countertop units resist cloud-gateway integration, extending deployment timelines for hybrid environments.
Strategic Opportunities
- Integrated Software-Hardware Ecosystems:Convergence of payment processing with inventory management and loyalty platforms creates recurring revenue pools beyond transaction fees alone.
- Canada Federal Privacy Law Tailwinds:PIPEDA compliance requirements favor vendors with pre-certified data-handling architectures, advantaging prepared entrants against retrofit-dependent competitors.
- Southern California Metro Cluster Penetration:Dense independent restaurant and retail concentration in Los Angeles and San Diego corridors offers scalable deployment economics for mobile-first terminal solutions.
Industry Challenges
- Payment Security Engineering Talent Scarcity:Shortage of firmware developers with PCI DSS audit experience extends product certification timelines and inflates compensation costs.
- Multi-Jurisdiction Compliance Complexity:Fragmentation between U.S. state privacy statutes, Canadian federal requirements, and Mexican data localization rules forces redundant engineering effort for cross-border merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America POS Terminal Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminal Hardware, Software Solutions, Mobile POS, Integrated Systems End User: Retail Stores, Restaurants, Hospitality, E-commerce Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Payment Method: Credit/Debit Cards, NFC, Mobile Wallets, Cryptocurrencies |
| Companies Covered | VeriFone Systems, Inc., Ingenico, First Data Merchant Services LLC, Castles Technology Co., Ltd., BBPOS Limited, Square, Inc., PAX Technology, NCR Voyix Corporation, Toast, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America POS Terminal Market Evolving Landscape
Terminal functionality is migrating from isolated transaction processing toward integrated commerce platforms, compressing the boundary between payment hardware and merchant operating systems. This architectural shift redefines competitive advantage around software ecosystem depth rather than device specifications alone.
Android-based open operating systems are displacing proprietary embedded firmware in countertop and mobile terminal form factors. Mid-market retailers and restaurant chains are adopting these platforms at accelerating pace, attracted by third-party application marketplaces and remote management capabilities. The technology is migrating from niche challenger deployments toward mainstream merchant acceptance, eroding incumbents' software lock-in advantages.
The FCC's electromagnetic emissions standards for wireless-enabled devices are tightening testing protocols for Bluetooth and WiFi-integrated terminals. Hardware manufacturers must now navigate extended certification cycles before market release, compressing product launch windows. Restaurant and hospitality segments deploying cordless payment solutions face the steepest compliance burden, driving consolidation toward vendors with pre-certified module libraries.
Merchant acquiring relationships are unbundling from terminal hardware procurement, reversing decades of bundled distribution economics. Independent software vendors and direct-to-merchant channels are capturing terminal placement decisions previously controlled by bank sales forces. This pattern concentrates most visibly among small-business segments in the United States, where Square and similar platforms have normalized separate hardware and processing vendor selection.
North America POS Terminal Market Segmentation
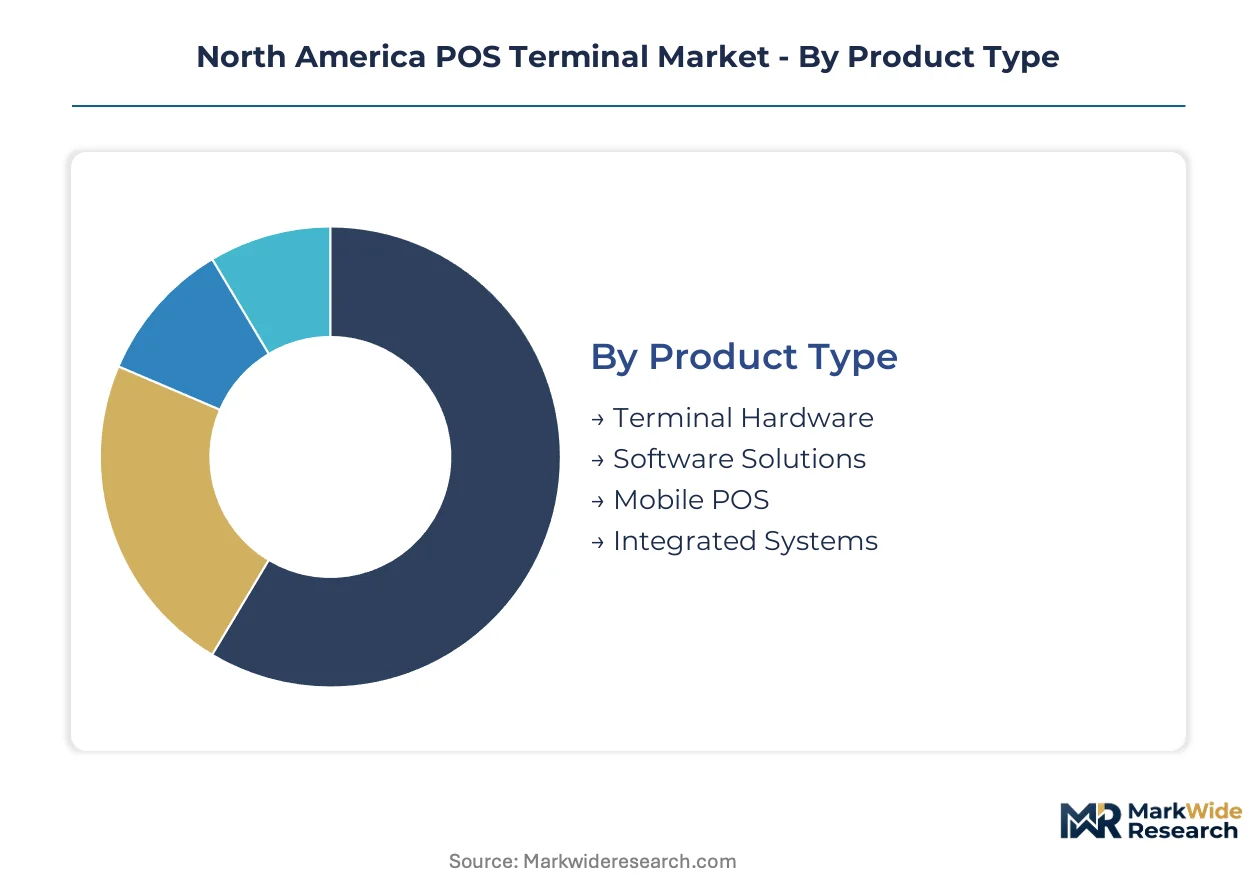
POS terminal segmentation reveals divergent margin structures and refresh cycles across hardware-centric versus software-centric deployments. Understanding these divisions exposes where vendor economics concentrate and which configurations face accelerated replacement demand from compliance mandates.
Product Type:
Mature terminal hardware installations dominate storefront counts, while emerging cloud-native configurations reset competitive dynamics around recurring revenue attachment.
- Terminal Hardware:Secure card-reading devices with PCI DSS Level 1 encryption modules and EMV chip compatibility form the installed base across U.S. Northeast corridor retail chains. PCI DSS compliance deadlines and EMV liability shifts force accelerated replacement cycles at quick-service restaurants and independent merchants.
- Software Solutions:Transaction management platforms with remote configuration capabilities and real-time analytics dashboards capture merchant attention. Southern California metro clusters show concentrated demand from multi-location restaurant operators seeking centralized oversight across dispersed storefronts.
- Mobile POS:Line-busting tablet and smartphone peripherals enable tableside and curbside payment capture.
- Integrated Systems:Converged hardware-software stacks bundle inventory, loyalty, and payment processing.
Terminal hardware handles the majority of throughput; software solutions are expanding most quickly on share as merchants prioritize remote management capabilities.
End User:
Cost tier differentiation separates high-volume transaction environments from lower-frequency specialty retail applications.
- Retail Stores:Department stores, grocery chains, and specialty merchants deploy countertop and self-checkout terminals with high-throughput encryption processors. U.S. Northeast corridor concentration drives replacement demand as legacy units age past PCI DSS certification windows.
- Restaurants:Quick-service and full-service establishments adopt mobile POS for line-busting and tableside flexibility. California Consumer Privacy Act compliance complexity forces architecture redesigns for customer analytics integration.
- Hospitality:Hotels and event venues require portable terminals for check-in and ancillary service capture.
- E-commerce:Online merchants utilize virtual terminals and payment gateway integrations for card-not-present transactions.
Retail stores anchor absolute terminal counts; restaurants are gaining share fastest through mobile POS density expansion per location.
Deployment:
Volume concentration favors cloud architectures, though hybrid configurations persist where legacy system interoperability barriers resist full migration.
- On-Premise:Locally hosted transaction processing with dedicated server infrastructure retains footholds in security-sensitive merchant segments. Legacy proprietary protocol integration challenges extend deployment timelines for hybrid environment transitions.
- Cloud-Based:Remote-hosted architectures with automatic software updates and centralized data aggregation attract mid-market chains. Canada federal PIPEDA compliance requirements favor vendors with pre-certified data-handling architectures.
- Hybrid:Split processing between local and remote environments accommodates staged migration paths.
- SaaS:Subscription-model software delivery with bundled hardware provisioning reduces capital barriers for small-business entry.
Cloud-based deployment captures the steepest expansion trajectory; on-premise retains residual share in compliance-sensitive verticals.
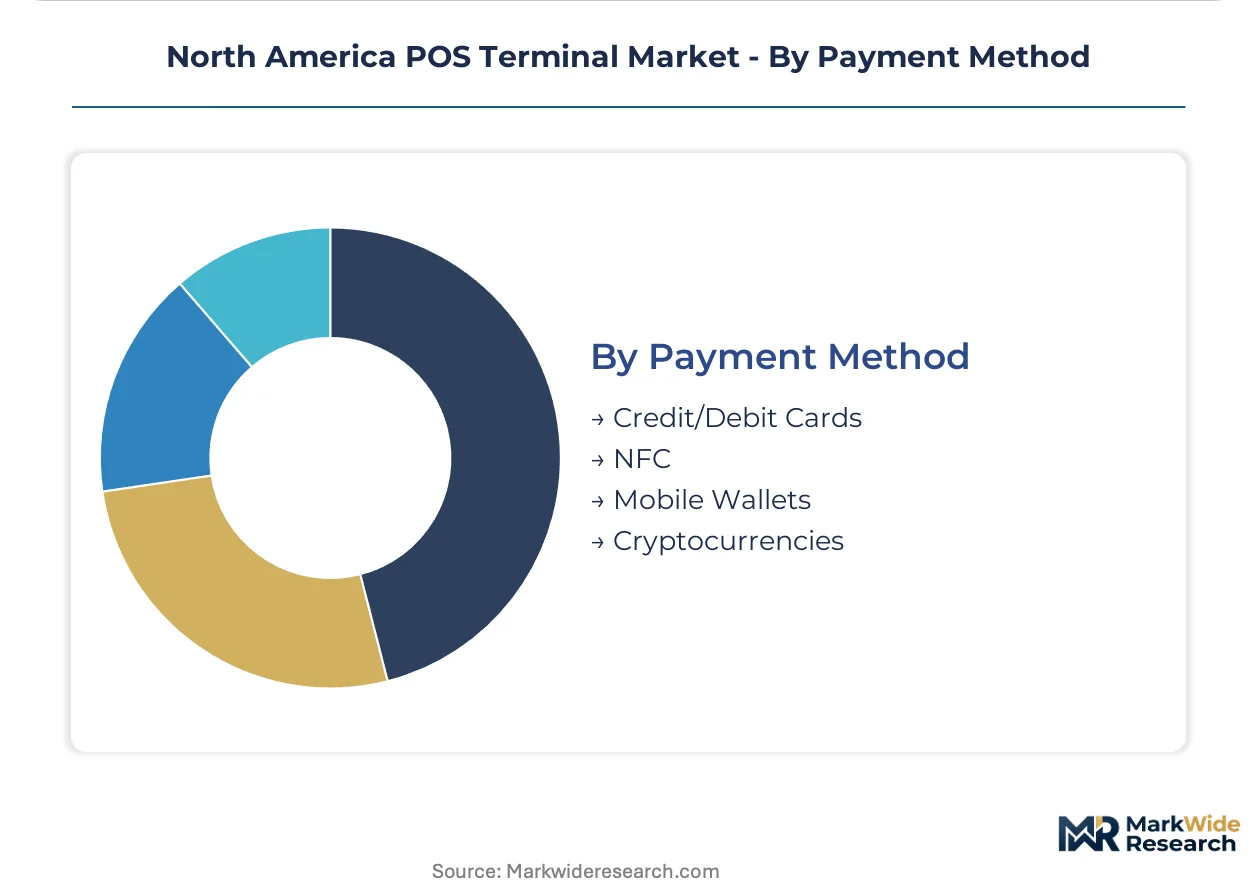
Payment Method:
Application context determines method adoption, with proximity payment growth concentrated in high-frequency, low-ticket environments.
- Credit/Debit Cards:EMV chip and magnetic stripe acceptance remains mandatory baseline functionality across all terminal configurations. U.S. Federal Reserve interchange fee structures influence terminal economics for card-present transactions.
- NFC:Contactless tap-to-pay protocols enable sub-10-second transaction completion at quick-service restaurant drive-thrus. FCC electromagnetic emissions standards tighten testing protocols for wireless-integrated terminal releases.
- Mobile Wallets:Apple Pay, Google Pay, and Samsung Pay integration requires tokenization support and biometric authentication handshakes.
- Cryptocurrencies:Blockchain-based settlement protocols attract niche merchant segments seeking payment diversification.
Credit and debit cards handle the majority of transaction volume; NFC is climbing the fastest on acceptance point penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component assembly for North American terminal demand concentrates in Mexican border cities, while merchant deployment density clusters in U.S. coastal metros and Canadian commercial corridors. Terminal refresh cycles vary sharply across these three markets based on regulatory enforcement timing and merchant segment composition.
United States
Quick-service restaurant chains and independent retailers drive terminal replacement across the Northeast corridor and Southern California metro clusters. FCC electromagnetic emissions standards tighten testing protocols for wireless-enabled devices, extending certification timelines. Los Angeles and San Diego corridors show concentrated mobile-first terminal adoption among independent restaurant operators seeking line-busting flexibility.
Canada
Mid-market retail chains and hospitality operators anchor cloud-based terminal demand, particularly in Ontario and Quebec commercial corridors. Federal PIPEDA privacy law compliance requirements favor vendors with pre-certified data-handling architectures, advantaging prepared entrants. Toronto and Vancouver merchant clusters prioritize centralized oversight capabilities across dispersed storefront locations.
Mexico
Electronics assembly capacity expansion in Tijuana and Guadalajara shortens component lead times for North American terminal manufacturers. Mexican data localization rules add compliance complexity for cross-border merchants operating unified payment systems. Guadalajara production clusters draw component suppliers closer to end markets, reducing supply chain latency against Asian sourcing alternatives.
North America POS Terminal Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encryption modules and secure processors. The vendor base separates into consolidated hardware-scale players and fragmented software-layer challengers. Three archetypes dominate: integrated ecosystem builders, vertical specialists targeting restaurant and hospitality segments, and component-scale fabricators anchoring production volume. Competitive dynamics center on M&A activity consolidating software capabilities and strategic partnerships unbundling merchant acquiring relationships from hardware procurement.
Within the integrated ecosystem tier, Square, Inc. and Toast, Inc. exemplify platform convergence strategies binding payment processing with merchant operating systems. PAX Technology anchors the hardware fabrication archetype with production scale distributed throughout the region. NCR Voyix Corporation occupies a position in vertical specialization, competing through restaurant and hospitality deployment expertise. These three companies represent the dominant competitive vectors: software-hardware bundling, manufacturing scale, and sector-specific solution depth.
| Leading Market Players |
|---|
| VeriFone Systems, Inc. |
| Ingenico |
| First Data Merchant Services LLC |
| Castles Technology Co., Ltd. |
| BBPOS Limited |
| Square, Inc. |
| PAX Technology |
| NCR Voyix Corporation |
| Toast, Inc. |
| Others |
Value Network & Pricing Analysis
Semiconductor encryption chip single-source dependency determines both pricing tier spreads and supply chain shape across North American POS terminal procurement, compressing margins for hardware OEMs while elevating premium attach rates for software-integrated vendors.
Pricing Analysis
PCI DSS Level 1 certification mandates dictate the pricing tier structure across the North America POS Terminal Market, separating premium-certified units from standard-grade hardware. Three-tier pricing structure across premium, standard, and economy levels reflects encryption module provenance, FCC pre-certification status, and software ecosystem depth. Cost compression in the economy tier is intensifying because merchant acquiring unbundling eliminates hardware subsidies previously embedded in processing contracts. Small independent restaurants exhibit highest price sensitivity, while multi-location quick-service chains prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from Tijuana and Guadalajara assembly clusters are reshaping working capital requirements for terminal OEMs serving North American markets. Secure processor fabrication draws from Taiwan and South Korea, while PCB assembly and final integration rest on Mexico and China capacity. Single-source vulnerability in EMV encryption chip supply creates allocation risk during demand surges. Distribution runs through merchant acquiring partnerships, direct-to-merchant channels, and independent software vendor marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
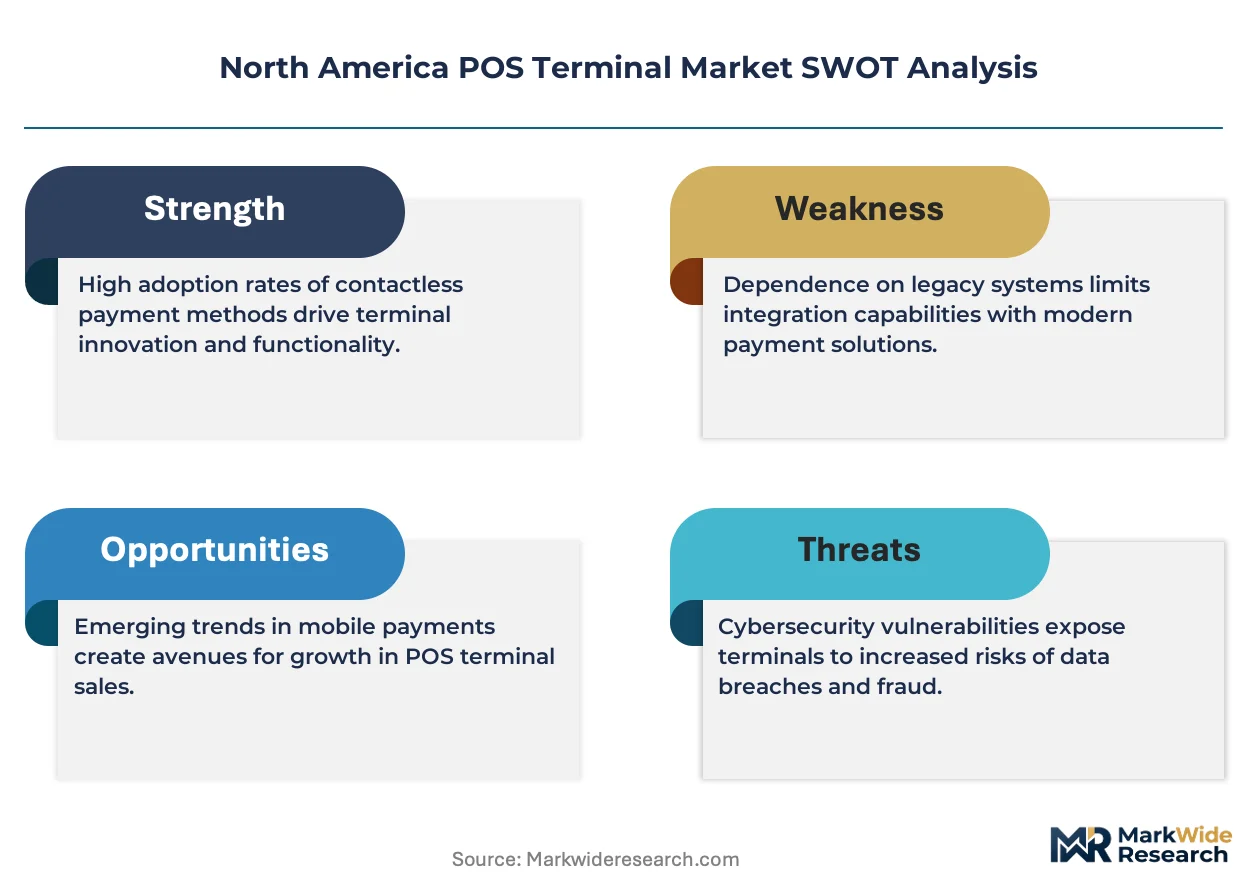
The North America POS Terminal Market functions as a defensive-moat industry where PCI DSS certification entrenchment and merchant switching costs protect incumbent positions against pure-play hardware commoditization.
For Market Incumbents: Build switching-cost moats through software ecosystem depth that embeds inventory, loyalty, and analytics modules into daily merchant workflows. Deepen backward integration into secure processor supply through strategic partnerships with Taiwan and South Korea fabrication capacity. Acquire mobile-first POS specialists before they achieve scale in Southern California and Northeast corridor restaurant clusters. For New Entrants and Emerging Players: Establish a beachhead in mid-market Canadian retail chains where PIPEDA pre-certification requirements disadvantage retrofit-dependent competitors. Target hybrid deployment architectures for merchants stalled between legacy on-premise systems and full cloud migration. Lead with Android-based open platforms that accelerate third-party application development and reduce certification timeline risk. For Investors and Strategic Acquirers: Vertical software specialists with pre-certified data-handling architectures represent the most defensible acquisition profile across the projection horizon. Evaluate targets through their certification velocity and recurring revenue attachment rates rather than hardware shipment volumes. Watch PCI DSS audit backlogs as an inflection indicator for vendor operational stress.| Strategic Initiative | Industry Significance |
|---|---|
| PCI DSS Pre-Certification Investment | Accelerates market access for cloud-native terminal architectures against legacy retrofit competitors. |
| Android Platform Migration | Erodes proprietary firmware lock-in through third-party application marketplace network effects. |
| Mexico Assembly Expansion | Shortens component lead times for North American terminal OEMs against Asian sourcing alternatives. |
| Software-Hardware Bundling | Captures recurring revenue pools beyond transaction fees through inventory and loyalty integration. |
| Merchant Acquiring Unbundling | Shifts terminal placement decisions from bank sales forces to independent software vendor channels. |
Research Methodology
A spread of perspectives from terminal hardware procurement managers, payment security engineering directors, merchant acquiring executives, and quick-service restaurant IT directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FCC certification databases, PCI Security Standards Council compliance registries, and SEC filings from publicly traded terminal OEMs. Bottom-up unit economics triangulated against top-down merchant segment sizing.
Demand-supply balance framing anchored the analytical framework across the analysis window, modeling deployment mode, merchant size tier, vertical segment, integration complexity, and regional regulatory cluster. CAGRs derived from terminal refresh cycle velocity, software attach rate trajectories, and cloud migration penetration curves. Forecast inputs incorporated EMV liability shift enforcement timing and FCC electromagnetic emissions standard evolution.
Sensitivities concentrate around semiconductor allocation disruptions, state-level privacy statute fragmentation, and merchant acquiring relationship restructuring. Forecasts reflect documented assumptions on certification timeline stability and Mexico assembly capacity expansion. Macroeconomic contraction, regulatory enforcement acceleration, or contactless payment protocol disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China Prepaid Cards Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Estonia POS Terminal Market
Payments
France Payments Market
Payments
Digital Debit Market
Payments
Contactless Payment Terminals Market
Payments
Global Digital Wallets Market
Payments
Poland POS Terminal Market
Payments
Blockchain Payments Software Market
Payments
Bus Card Reader Market
Payments
Vietnam Payments Market
Payments
Gift Card and Incentive Card Market
Payments
Retail Point of Sale (POS) Market
Payments
Tanzania Mobile Money Market
Payments
Norway POS Terminals Market
Payments
Germany Gift Card and Incentive Card Market