
 Subscription Billing Management Market | 2026-2036
Subscription Billing Management Market Size, Share, and Industry Trends Forecast 2026-2036
Subscription Billing Management Market Intelligence
A scarcity of revenue-operations talent is collapsing implementation timelines for mid-market enterprises. Zuora Inc. leverages its pre-built integrations with CRM and ERP ecosystems to reduce deployment friction. Chargebee anchors its position through localized tax-engine coverage across 150 jurisdictions. Stripe, Inc. competes by embedding billing primitives directly into its payments infrastructure.
Subscription billing management denotes software systems that automate recurring invoicing, payment collection, revenue recognition, and subscriber lifecycle management across variable pricing constructs. These platforms enforce ASC 606 and IFRS 15 compliance through automated contract modification tracking and performance obligation allocation. Cloud-based deployment now leads the deployment model segment as enterprises abandon on-premise maintenance burdens. Usage-based pricing within the pricing strategy segment is accelerating fastest among IoT and API-first vendors seeking consumption-aligned monetization.
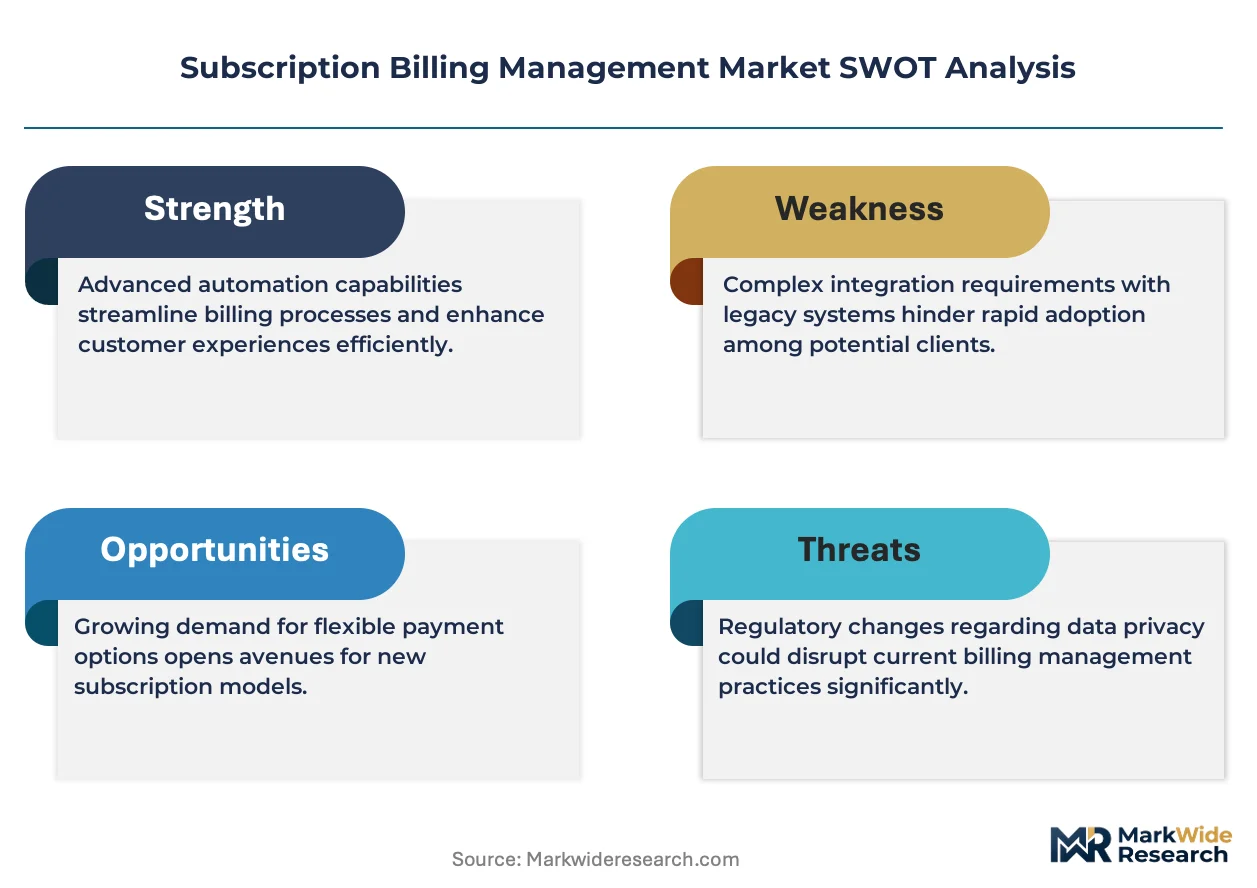
The Federal Trade Commission scrutinizes subscription cancellation friction under the Click-to-Cancel rule, while the EU Digital Services Act imposes transparency obligations on automated billing decisions. PCI-DSS certification remains mandatory for any platform handling cardholder data, creating a compliance moat around established providers. Stakeholders must weigh the trade-off between vertical feature depth and horizontal platform extensibility when selecting long-term billing architecture.
Market Dynamics
The FTC's Click-to-Cancel rule is forcing platforms to redesign subscriber retention workflows, while ASC 606 and IFRS 15 mandates are compressing revenue recognition cycles into automated contract-modification tracking.
Growth Catalysts
- Consumption-Based Monetization:IoT vendors and API-first platforms are migrating from seat-based to metered pricing models, requiring billing engines that ingest telemetry streams and compute prorated charges in real time.
- GDPR and PCI-DSS Compliance Burden:European enterprises facing data-handling audits are abandoning self-managed billing stacks for certified cloud-native platforms with pre-validated security controls.
- Japan and Germany:These mature digital service economies anchor enterprise adoption, where recurring-revenue models now dominate software and industrial equipment financing.
Market Restraints
- Revenue-Operations Talent Scarcity:Mid-market enterprises report collapsed implementation timelines due to shortage of professionals fluent in both billing architecture and ASC 606 allocation logic.
- Input Cost Volatility in Cloud Infrastructure:Billing platforms dependent on hyperscaler compute face margin pressure from fluctuating egress and storage pricing.
- Legacy ERP Integration Friction:SAP and Oracle environments resist real-time API synchronization, forcing costly middleware layers that extend deployment cycles.
Strategic Opportunities
- India's Digital Payments Surge:Unified Payments Interface adoption creates white space for localized billing platforms handling recurring mandates in rupee-denominated subscriptions.
- EU Digital Services Act Transparency Mandates:Automated billing decision audit trails become a competitive differentiator for platforms serving European streaming and SaaS vendors.
- Embedded Finance Convergence:Billing primitives are merging with lending and insurance APIs, enabling platforms to offer subscription financing and usage-based insurance as bundled services.
Industry Challenges
- Revenue Recognition Certification Timelines:SOC 2 Type II and ISO 27001 audits consume 6-12 months, delaying market entry for new entrants.
- Multijurisdictional Tax Engine Complexity:Platforms must maintain real-time compliance across 150+ tax regimes, each with distinct digital services tax thresholds and filing cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subscription Billing Management Market |
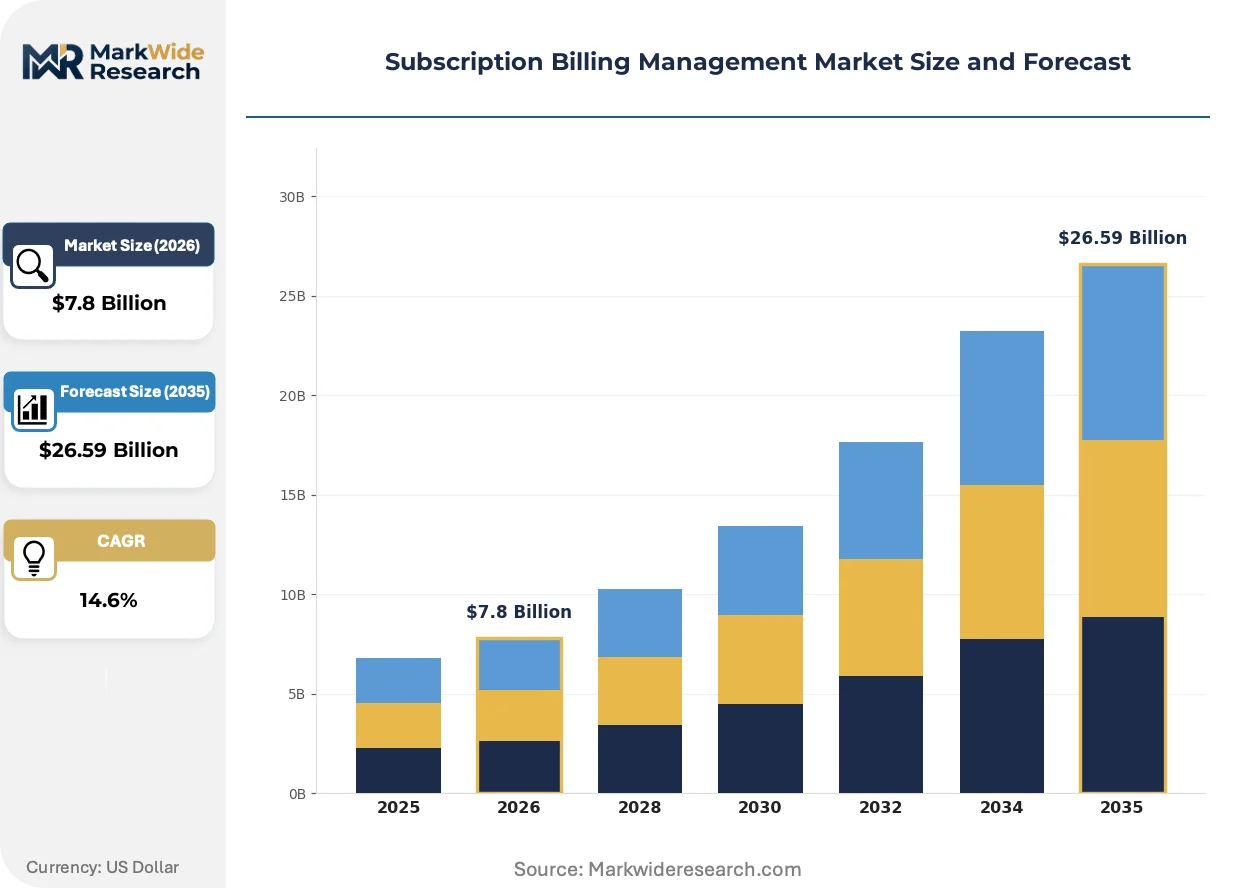
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $26.59 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recurring Billing, Payment Processing, Invoice Management, Revenue Recognition Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Telecommunications, Media, Software, E-Commerce Pricing Strategy: Flat Rate, Tiered Pricing, Usage-Based, Freemium |
| Companies Covered | SAP SE, Oracle Corporation, Zuora Inc., Chargebee, Recurly, Inc., Aria Systems, Inc., Stripe, Inc., BillingPlatform, cleverbridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subscription Billing Management Market Strategic Shifts & Innovations
Event-driven billing architectures are supplanting batch-oriented invoice generation, compressing cash-to-revenue cycles from days to seconds. This shift demands entirely new data infrastructure and is redrawing competitive boundaries between payment processors and standalone billing vendors.
Event-streaming infrastructure is supplanting traditional database polling for usage metering. API-first vendors and connected device manufacturers now ingest telemetry through Apache Kafka and Pulsar pipelines, enabling real-time rating and charging. This architecture eliminates end-of-period invoice surprises and is compressing payment collection cycles from thirty days to immediate settlement.
The EU Digital Services Act imposes algorithmic transparency obligations on automated billing decisions, requiring platforms to maintain auditable logs of price adjustments and renewal logic. SaaS vendors serving European customers must now expose the reasoning behind subscription tier migrations and proration calculations. German and French enterprises are prioritizing vendors with pre-built DSA compliance modules.
Buyer procurement patterns are fragmenting as finance teams demand usage-based contracts with annual spend caps rather than fixed subscriptions. Enterprise SaaS procurement now routes through FinOps functions that benchmark unit economics across competing billing models. This behavior is most visible among Series C and D software vendors in the United States, where venture-backed boards mandate consumption-aligned cash burn rates.
Subscription Billing Management Market Segmentation
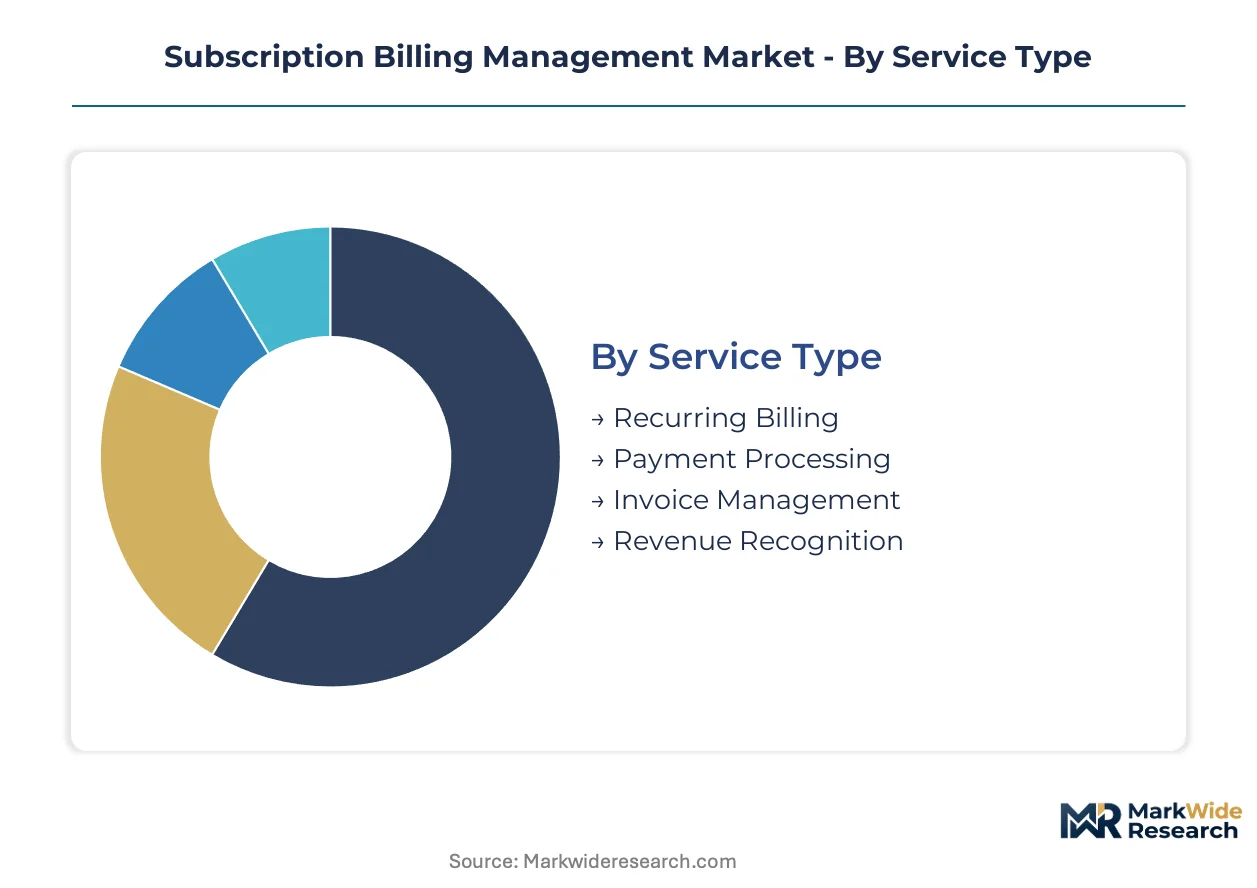
Segmentation in subscription billing management reflects divergent compliance burdens and technical architectures across service delivery modes. Enterprises select segments based on ASC 606 audit readiness, PCI-DSS certification status, and integration complexity with existing ERP investments.
Service Type:
PCI-DSS Level 1 certification separates enterprise-grade offerings from mid-market alternatives, with audit scope varying dramatically across functional modules.
- Recurring Billing:Core automation engines handle subscription lifecycle events including renewals, upgrades, and proration calculations. German SaaS vendors and Japanese industrial equipment manufacturers drive concentration here, compelled by METI guidelines on recurring revenue disclosure and GDPR Article 17 deletion mandates.
- Payment Processing:Card-on-file vaulting and tokenization infrastructure with real-time authorization routing. United States streaming platforms anchor demand following FTC Click-to-Cancel enforcement actions requiring immediate payment cessation capabilities.
- Invoice Management:Multi-currency billing document generation with localized formatting rules.
- Revenue Recognition:ASC 606 and IFRS 15 compliance engines automating performance obligation allocation and contract modification tracking.
Recurring Billing handles the majority of throughput; Payment Processing is climbing the fastest on share.
Deployment Model:
Cost tier differentiation separates self-managed infrastructure from fully outsourced SaaS alternatives, with hybrid architectures occupying a narrowing middle ground.
- Cloud-Based:Hyperscaler-hosted platforms with automatic scaling and geographic redundancy. European enterprises facing GDPR Article 32 security processing requirements are abandoning on-premise stacks for certified cloud-native alternatives with pre-validated ISO 27001 controls.
- SaaS:Multi-tenant architectures with zero infrastructure ownership and continuous feature delivery. United States mid-market software vendors concentrate here, drawn by consumption-based pricing that aligns cash outflows with subscriber growth curves.
- On-Premise:Self-managed installations within enterprise data centers retaining full data sovereignty.
- Hybrid:Split architectures maintaining sensitive data on-premise while leveraging cloud elasticity for compute-intensive rating operations.
Cloud-Based deployments command the dominant revenue position; SaaS alternatives are expanding most quickly among venture-backed software vendors.
End User:
Application maturity varies sharply, with sectors facing the most complex usage metering requirements driving platform innovation.
- Software:API-first vendors and developer-tooling companies with seat-based, usage-based, and outcome-based pricing hybrids. United States Series C and D startups anchor this segment, compelled by FinOps mandates to benchmark unit economics across competing billing models.
- Telecommunications:Legacy carriers with established BSS/OSS infrastructure requiring real-time rating for voice, data, and IoT connectivity bundles.
- Media:Streaming platforms and digital content distributors with freemium conversion funnels and regional content licensing tiers.
- E-Commerce:Subscription box services and replenishment models with variable fulfillment cadences and promotional pricing complexity.
Software end users generate the highest platform revenue per customer; Telecommunications is gaining share fastest as 5G IoT deployments multiply metering endpoints.
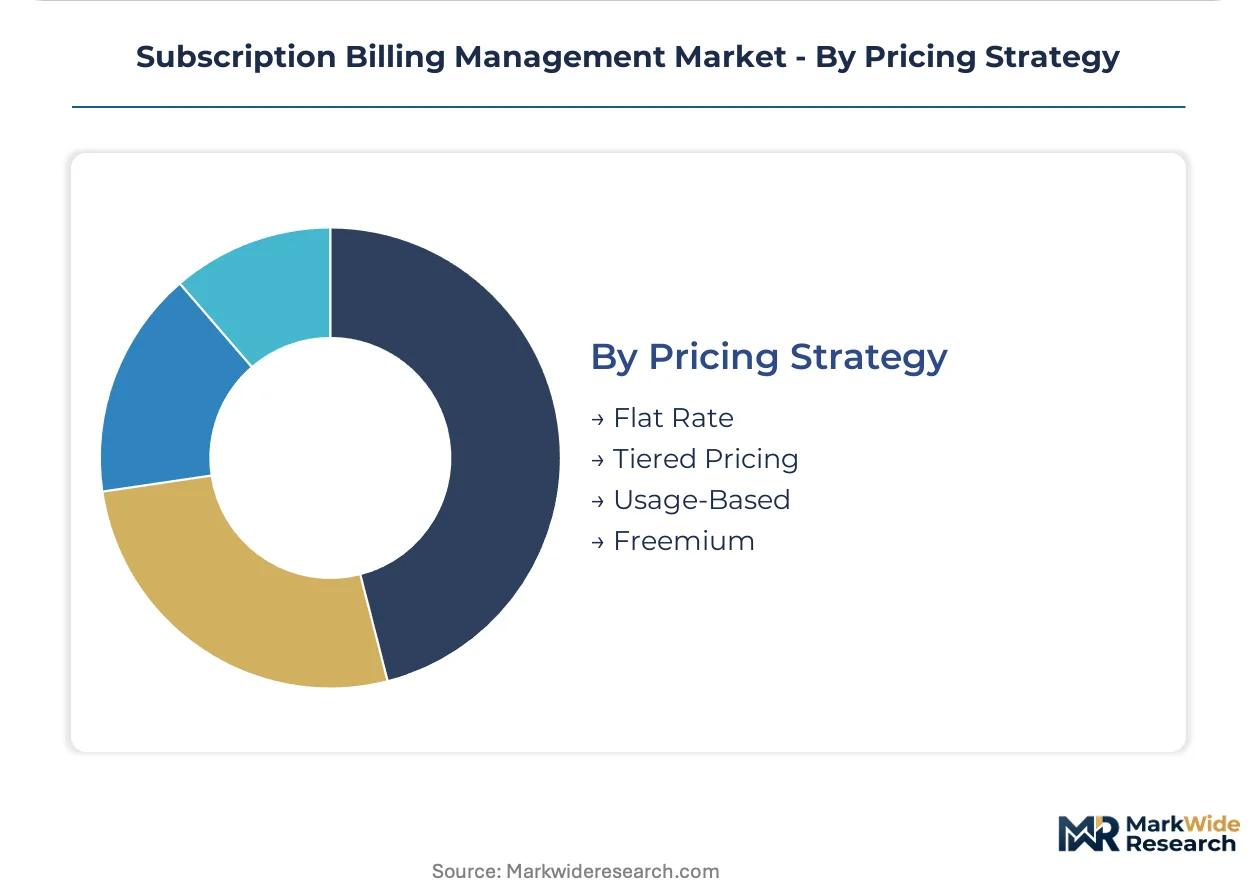
Pricing Strategy:
Customer procurement sophistication is fragmenting traditional fixed-subscription models, with finance teams demanding consumption-aligned contracts.
- Usage-Based:Metered consumption with telemetry ingestion and real-time rating engines. IoT device manufacturers and API-first platforms in Germany and Japan concentrate here, seeking monetization models that capture value from variable utilization patterns.
- Freemium:Tiered conversion funnels with feature-gated upgrades and in-product purchase flows. United States productivity software vendors dominate, optimizing activation-to-paid conversion rates through billing-integrated experimentation platforms.
- Flat Rate:Fixed periodic charges without consumption variability, simplest for revenue forecasting.
- Tiered Pricing:Discrete feature bundles with clear upgrade paths and annual spend commitments.
Usage-Based pricing carries the steepest expansion trajectory; Freemium models retain the largest installed base among growth-stage software vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with United States enterprises prioritizing real-time payment cessation capabilities under FTC enforcement, while German and Japanese markets emphasize automated revenue recognition compliance for industrial equipment financing.
United States
Streaming platforms and Series C/D SaaS vendors anchor demand, driven by FinOps mandates to benchmark unit economics and FTC Click-to-Cancel rules requiring immediate payment cessation. The Federal Trade Commission enforces subscription cancellation friction penalties. Silicon Valley and Seattle clusters concentrate billing-integrated experimentation platforms optimizing activation-to-paid conversion.
Germany
Industrial equipment manufacturers and IoT device vendors dominate adoption, compelled by METI-aligned recurring revenue disclosure requirements and GDPR Article 17 deletion mandates. The EU Digital Services Act imposes algorithmic transparency obligations on automated billing decisions. Berlin and Munich host enterprises prioritizing vendors with pre-built DSA compliance modules for audit trails.
Japan
Industrial equipment financing and mature digital service economies drive enterprise adoption, with METI guidelines mandating recurring revenue disclosure. The Personal Information Protection Commission enforces data handling audit requirements. Tokyo and Osaka clusters concentrate enterprises migrating from perpetual licenses to consumption-aligned monetization models.
India
Unified Payments Interface adoption creates white space for localized billing platforms handling recurring mandates in rupee-denominated subscriptions. The Reserve Bank of India governs payment aggregator licensing and recurring transaction authorization. Bangalore and Mumbai clusters anchor venture-backed SaaS vendors seeking consumption-based pricing alignment with subscriber growth curves.
United Kingdom
API-first vendors and developer-tooling companies concentrate demand, driven by procurement patterns routing through FinOps functions benchmarking competing billing models. The Financial Conduct Authority scrutinizes subscription fairness and auto-renewal transparency. London's fintech corridor hosts enterprises demanding usage-based contracts with annual spend caps rather than fixed subscriptions.
Subscription Billing Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the former commanding pre-validated compliance certifications and the latter competing on vertical feature depth. The upper tier consolidates around cloud-native platforms with PCI-DSS Level 1 certification and ASC 606 automation engines. Three strategic archetypes define positioning: ERP-integrated incumbents extending financial modules, standalone billing pure-plays with multi-jurisdictional tax engines, and payment processors embedding billing primitives into infrastructure stacks. Competitive moves concentrate on strategic partnerships with hyperscaler marketplaces and portfolio diversification into embedded finance convergence.
Within the standalone pure-play tier, Zuora Inc. and Chargebee exemplify archetype specialization, with the former leveraging pre-built CRM and ERP ecosystem integrations and the latter anchoring position through localized tax-engine coverage. Stripe, Inc. occupies a distinct position as a payment infrastructure provider embedding billing primitives directly into its stack, representing the processor-convergence archetype.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Zuora Inc. |
| Chargebee |
| Recurly, Inc. |
| Aria Systems, Inc. |
| Stripe, Inc. |
| BillingPlatform |
| cleverbridge |
| Others |
Cost & Logistics Intelligence
Consumption-based contracts with annual spend caps lock in multi-year platform commitments while preserving buyer flexibility on compute scaling. This structure concentrates pricing power with hyperscaler-backed vendors in the United States and Germany, where PCI-DSS Level 1 certification costs create tiered entry barriers.
Pricing Analysis
Long-term SaaS subscriptions dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels anchored to ASC 606 automation depth and tax-engine jurisdiction count. Price differentiation hinges on PCI-DSS certification grade and real-time usage metering capability. Cost compression in mid-market tiers is intensifying because hyperscaler compute pricing volatility squeezes vendor margins. Series C and D software vendors in the United States exhibit highest price sensitivity, while Japanese industrial equipment manufacturers prioritize compliance depth over unit cost.
Supply Chain Analysis
Inventory cycles for cloud infrastructure components stretch 8-14 weeks, constraining platform scaling velocity during demand surges. Supply concentrates in the United States, Ireland, and Singapore, where hyperscaler regions anchor primary compute capacity. Raw material dependencies span advanced semiconductors for encryption modules, specialized database licensing, and fiber-optic interconnect hardware. Single-source vulnerability in AI inference chip supply chains poses concentration risk. Distribution runs through direct enterprise sales with hyperscaler marketplace co-sell arrangements gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription billing management functions as a critical service-attach layer, with revenue-recognition automation and embedded finance modules expanding faster than core payment processing as enterprises seek consumption-aligned monetization.
For Market Incumbents: Consolidate around ASC 606 automation depth and pre-built ERP connectors to defend against Stripe's infrastructure-embedded billing primitives. Prioritize SOC 2 Type II certification investment to maintain compliance moats. Acquire specialized tax-engine providers in India and Southeast Asia to capture UPI-driven recurring mandate growth. For New Entrants and Emerging Players: Anchor in India's Unified Payments Interface ecosystem, where localized recurring mandate handling remains underpenetrated by global vendors. Target mid-market SaaS vendors in Bangalore and Mumbai seeking consumption-based pricing alignment. Pursue FinOps-integrated go-to-market partnerships with venture capital portfolio services. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platforms with PCI-DSS Level 1 certification and multi-jurisdictional tax coverage, positioned for 5-10 year consolidation as compliance burdens intensify. Monitor FTC Click-to-Cancel enforcement velocity as inflection indicator for retention-technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built Salesforce and NetSuite connectors reduce deployment friction for mid-market enterprises. |
| Geographic Expansion | Localized tax-engine deployment across India's UPI ecosystem captures rupee-denominated subscription growth. |
| Strategic Partnership | Hyperscaler marketplace co-sell agreements accelerate enterprise procurement velocity with pre-validated security controls. |
| Acquisition of Specialist Firm | Real-time usage metering vendors with Apache Kafka pipelines address IoT and API-first vendor requirements. |
| Product Launch | Embedded finance modules bundling subscription lending differentiate platforms in competitive RFP processes. |
Research Approach
A standing panel of revenue operations directors, FinOps practitioners, SaaS CFOs, and billing platform engineers provided ongoing calibration across the research cycle. Primary interviews combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and PCI-DSS certification databases established baseline metrics. Bottom-up deployment counts and top-down enterprise software spend estimates underwent cross-referencing to resolve discrepancies.
Consistency checks against external benchmarks validated projections across the modeling period. Segmentation dimensions spanned deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and adoption curve modeling incorporated ASC 606 compliance mandate timelines and FTC enforcement patterns as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration and stable hyperscaler pricing; material deviation in either would warrant model refresh. Forecasts assume continued regulatory fragmentation across tax jurisdictions and data sovereignty requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia-Pacific Payments Market
Payments
China Forex Cards Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Estonia POS Terminal Market
Payments
Remittance Market
Payments
Germany Mobile Payments Market
Payments
Global Payment Gateways Market
Payments
Taiwan Mobile Payments Market
Payments
Italy Gift Cards Market
Payments
Australia Payments Market
Payments
Malta POS Terminal Market
Payments
Global Accounts Payable Automation Market
Payments
Mobile Point of Sale (POS) Market
Payments
Fingerprint Payment Market
Payments
Buy Now Pay Later (BNPL) Services Market