
 Payment Analytics Software Market | 2026-2036
Payment Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Analytics Software Market Analysis
Data science talent scarcity is unwinding deployment timelines for advanced payment analytics platforms across mid-market banks. Stripe leverages its developer-centric infrastructure to dominate API-first analytics integration for SaaS billing workflows. Adyen sustains a unified commerce data layer that anchors cross-channel transaction intelligence for enterprise merchants. Fiserv competes through embedded analytics within core banking stacks, occupying a defensive position against standalone challengers.
Payment analytics software comprises algorithmic platforms that ingest, normalize, and visualize transaction streams to detect anomalies, forecast cash flows, and optimize acceptance costs through machine-learned routing rules. These systems process structured and unstructured payment data in sub-second windows to surface actionable intelligence for revenue operations and compliance teams. Cloud-based deployment leads segment uptake as financial institutions retire legacy on-premise infrastructure, though hybrid architectures persist where data sovereignty requirements fragment workload placement. Among end users, e-commerce platforms represent the fastest-expanding category as merchant acquirers bundle analytics into checkout experiences to reduce cart abandonment and optimize fee structures.
The US Federal Reserve's FedNow instant payment mandate and the European Banking Authority's PSD3 technical standards are reshaping real-time data architecture requirements for analytics vendors. The UK's Financial Conduct Authority enforces consumer duty rules that compel payment service providers to demonstrate fair value through transparent transaction analytics. India's RBI guidelines on digital lending data standards and China's SAMR fintech oversight protocols add compliance complexity for platforms seeking multi-jurisdiction scale. Stakeholders must decide whether to build proprietary data pipelines or rely on third-party enrichment layers as regulatory fragmentation deepens.
Market Dynamics
Real-time payment infrastructure mandates are forcing analytics vendors to rebuild data pipelines for sub-second processing windows, compressing deployment timelines and elevating cloud-native architecture requirements.
Growth Catalysts
- FedNow instant payment mandate:The US Federal Reserve's real-time settlement protocol compels banks to upgrade transaction monitoring systems, creating immediate demand for low-latency analytics platforms.
- Open banking API proliferation:PSD2-style data-sharing frameworks in the European Union and United Kingdom accelerate platform interoperability, enabling cross-institutional analytics services.
- E-commerce checkout optimization:Merchant acquirers bundle payment intelligence into point-of-sale experiences to reduce cart abandonment, driving analytics adoption among mid-market retailers.
Market Restraints
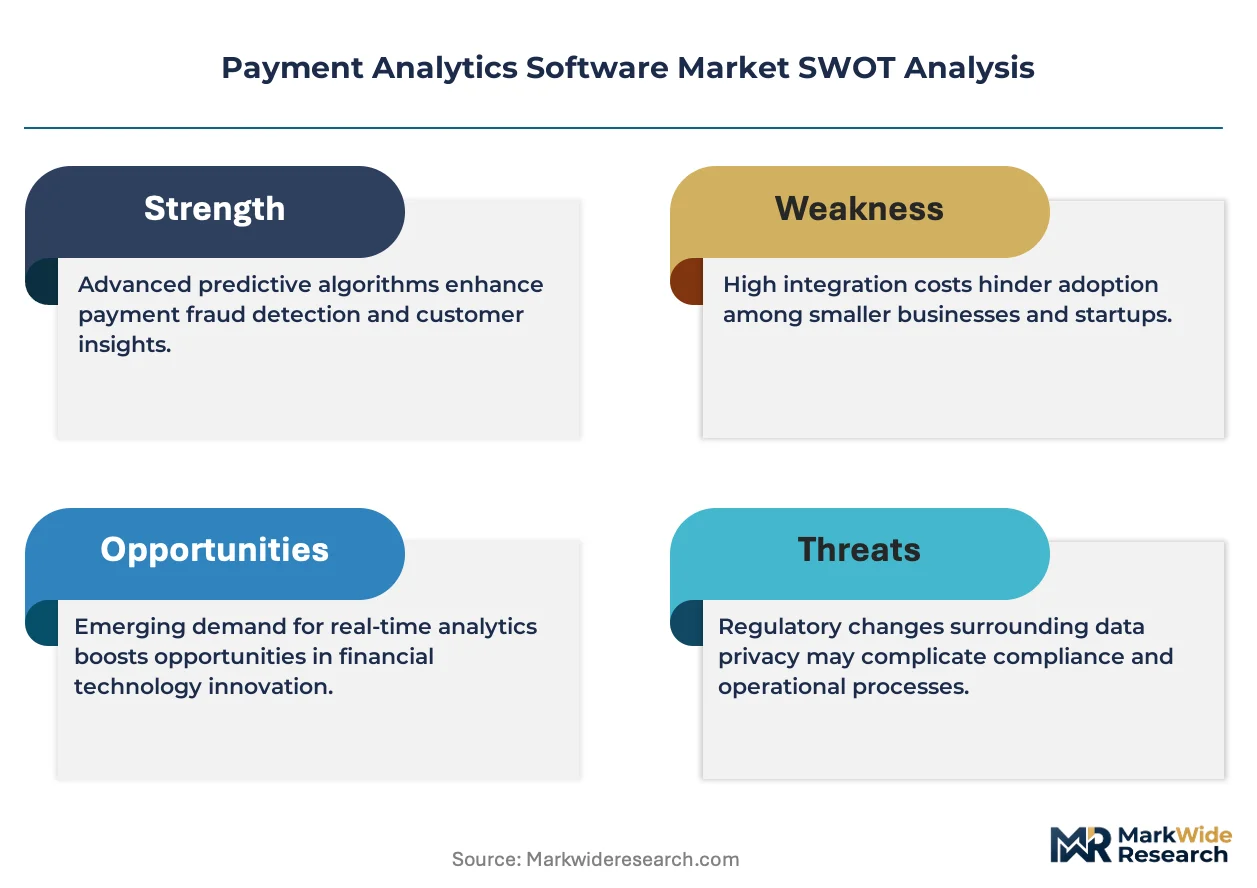
- Data science talent scarcity:Shortages of machine learning engineers and quantitative analysts extend deployment timelines for advanced anomaly detection systems.
- Regulatory fragmentation:Divergent technical standards across the US Federal Reserve, European Banking Authority, and Reserve Bank of India force vendors to maintain jurisdiction-specific compliance modules.
- Legacy infrastructure lock-in:On-premise core banking systems at regional banks resist cloud migration, constraining addressable market for pure-play SaaS analytics providers.
Strategic Opportunities
- India digital lending data standards:RBI guidelines on borrower data collection create compliance-driven demand for transaction analytics among non-bank financial companies.
- Embedded finance convergence:Integration of payment analytics with Buy Now Pay Later workflows and merchant cash advance underwriting opens new revenue streams.
- Hybrid cloud architectures:Data sovereignty requirements in Germany and France favor workload-splitting solutions that combine edge processing with centralized analytics.
Industry Challenges
- Sub-second latency engineering:Building real-time fraud detection pipelines that process structured and unstructured data within payment windows demands specialized infrastructure expertise.
- Multi-jurisdiction certification complexity:Platforms seeking scale across the United States, United Kingdom, and Germany must simultaneously satisfy FedNow, PSD3, and FCA consumer duty requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Analytics Software Market |
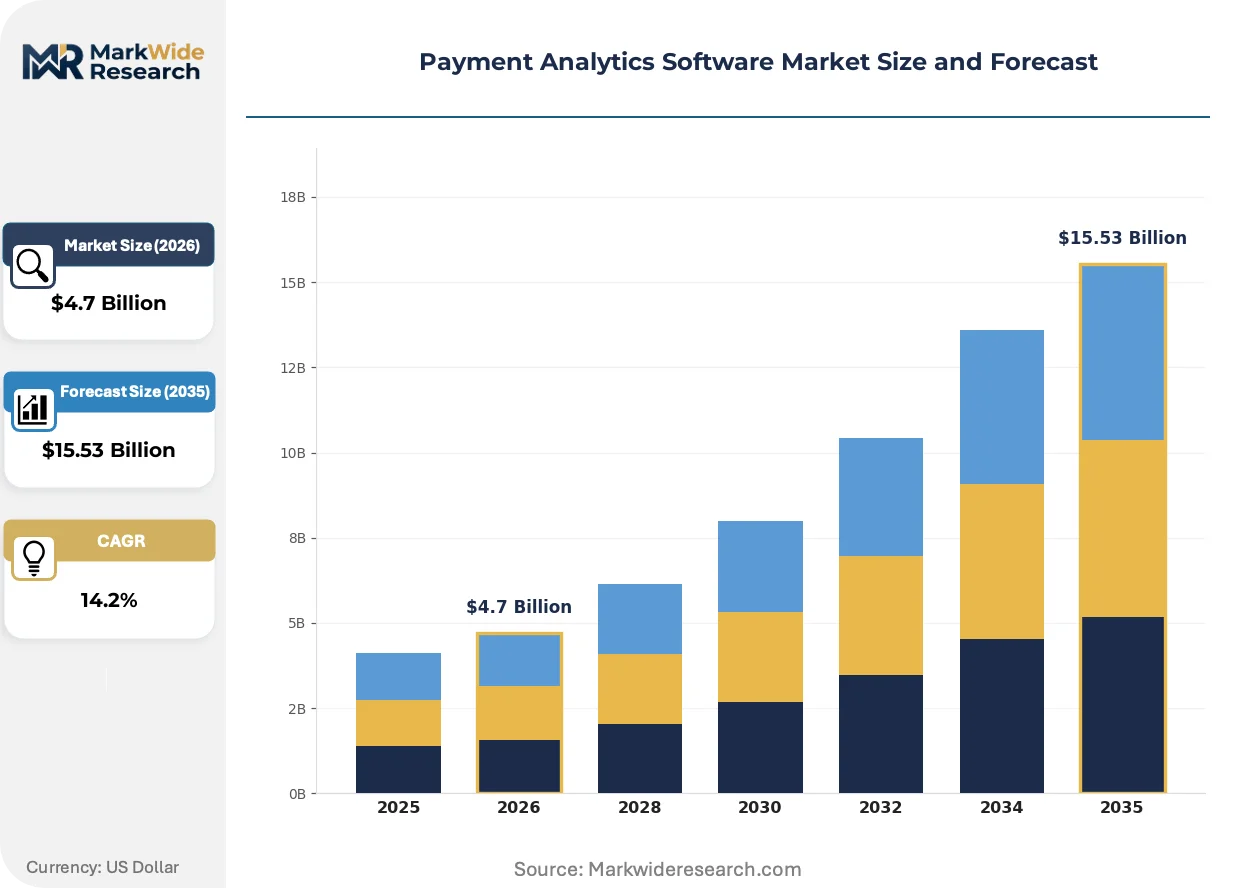
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Fraud Detection, Customer Insights, Revenue Forecasting, Risk Management End User: Retail Businesses, E-commerce Platforms, Financial Institutions, Payment Processors Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | Stripe, Adyen, DualEntry, Fiserv, Block Inc., BlueSnap, Mastercard, Plaid, ProfitWell Metrics by Paddle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Analytics Software Market Emerging Trajectories
Algorithmic transaction routing and machine-learned cost optimization are compressing the value chain between payment acceptance and treasury operations, blurring traditional vendor boundaries.
Graph neural networks for fraud detection is supplanting rules-based transaction monitoring in tier-one banks. These systems map entity relationships across payment networks to identify synthetic identities and mule accounts. Large US card issuers deploy these models within 200-millisecond authorization windows, compressing false-positive rates while expanding real-time decision scope.
PSD3 technical standards from the European Banking Authority mandate enhanced transaction data granularity for payment service providers. These requirements force analytics platforms to reconstruct audit trails across fragmented banking APIs. German and Dutch banks face the steepest compliance costs as they retrofit legacy reporting infrastructure to satisfy real-time disclosure mandates.
Merchant procurement of payment intelligence is consolidating through acquiring banks rather than standalone software vendors. Retailers in the United Kingdom increasingly bundle analytics into interchange fee negotiations, treating transaction data as a cost-optimization lever rather than a separate technology purchase. This channel shift pressures pure-play analytics vendors to embed within processor ecosystems or cede mid-market share.
Payment Analytics Software Market Segmentation
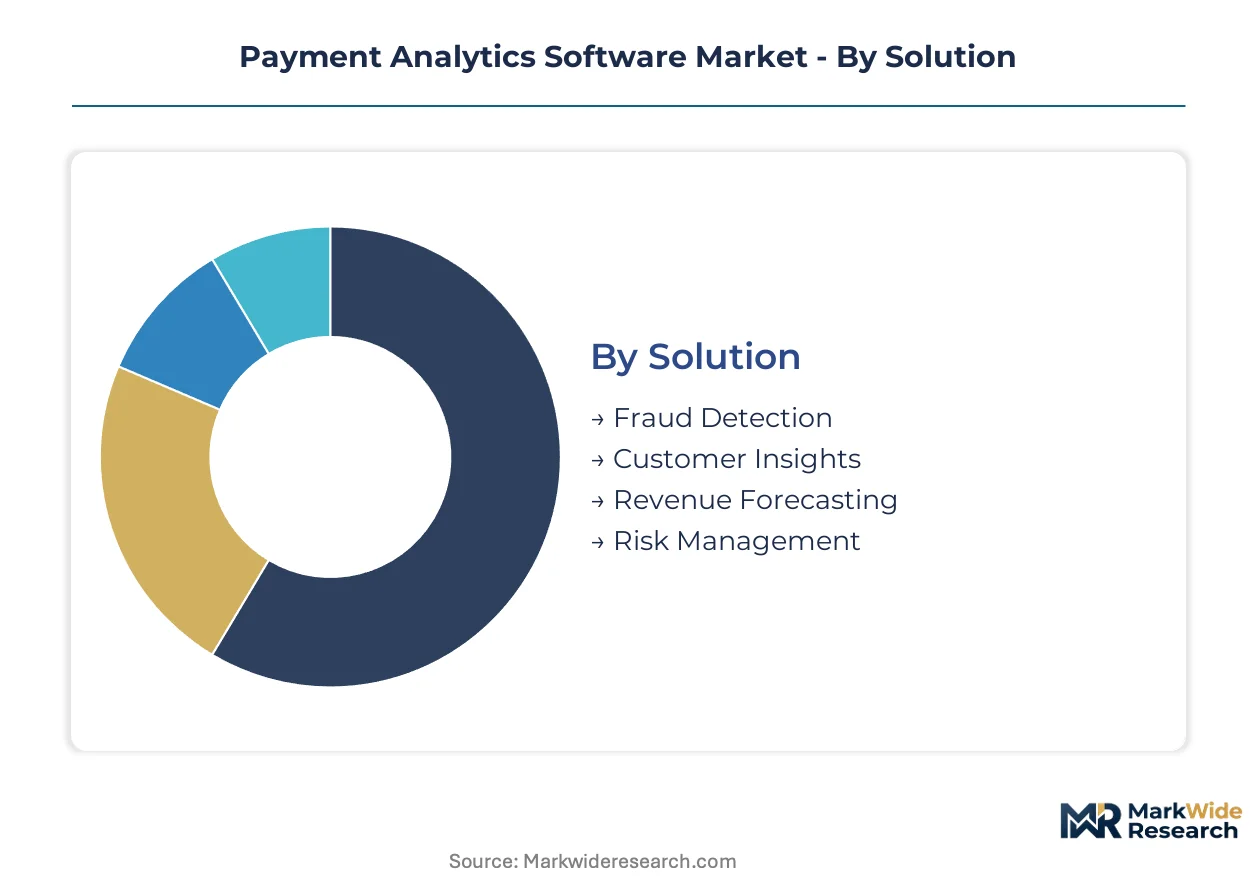
Payment analytics software segments diverge sharply in margin structure, with real-time processing modules commanding premium pricing while legacy reporting tools face commoditization. Understanding these tiered economics helps vendors allocate R&D and sales resources across deployment modes and customer types.
Solution:
Fraud Detection solutions capture the deepest margin pools within this category, driven by sub-second latency requirements and specialized infrastructure expertise.
- Fraud Detection:Algorithmic platforms process authorization streams within 200-millisecond windows to identify synthetic identities and mule accounts through graph neural networks. Demand concentrates among tier-one US card issuers facing FedNow real-time settlement mandates, where false-positive compression justifies premium licensing.
- Customer Insights:These modules normalize transaction histories into behavioral segments for personalized marketing and retention campaigns. E-commerce platforms in the United Kingdom bundle this intelligence into checkout experiences to reduce cart abandonment, treating data as a cost-optimization lever rather than standalone software.
- Revenue Forecasting:Cash flow prediction engines ingest structured payment streams to project liquidity positions for treasury operations.
- Risk Management:Compliance-focused modules reconstruct audit trails across fragmented banking APIs to satisfy PSD3 technical standards.
The dominant share belongs to Fraud Detection, while Customer Insights is closing the gap fastest.
End User:
Volume concentration tilts toward Financial Institutions, though E-commerce Platforms exhibit the steepest expansion trajectory as merchant acquirers embed analytics into payment flows.
- Financial Institutions:Banks and credit unions deploy enterprise-grade platforms for real-time transaction monitoring and regulatory reporting. German and Dutch institutions face the steepest compliance costs as they retrofit legacy infrastructure to satisfy European Banking Authority disclosure mandates.
- E-commerce Platforms:Online retailers procure payment intelligence through acquiring banks rather than standalone vendors, consolidating procurement channels. Mid-market retailers in the United Kingdom increasingly negotiate analytics bundles as part of interchange fee structures.
- Retail Businesses:Brick-and-mortar merchants leverage point-of-sale analytics to optimize acceptance costs and inventory synchronization.
- Payment Processors:Acquirers and gateways embed white-label analytics to differentiate merchant services and reduce churn.
Financial Institutions retain the largest installed base, though E-commerce Platforms are expanding most quickly.
Deployment:
Cost tier differentiation separates cloud-native architectures from legacy on-premise installations, with hybrid configurations capturing mid-market budgets constrained by data sovereignty requirements.
- Cloud-Based:SaaS delivery dominates new deployments as financial institutions retire legacy infrastructure, though data residency rules in Germany and France fragment workload placement. Vendors offering regional cloud instances capture compliance-sensitive budgets that pure centralized platforms cannot access.
- Hybrid:Split architectures combine edge processing for sensitive data with centralized analytics for aggregate intelligence. German banks favor this model to satisfy national data sovereignty requirements while accessing scalable compute for model training.
- On-Premise:Legacy installations persist at regional banks with entrenched core banking systems resistant to migration.
- Mobile:Lightweight deployment for field-based merchant services and microfinance operations.
Cloud-Based deployment holds the leading position, while Hybrid configurations are gaining share fastest among European regulated entities.
Customer Type:
Maturity curves diverge across enterprise tiers, with Large Corporations demanding bespoke integration while Startups prioritize API-first, pay-as-you-scale consumption models.
- Large Corporations:Enterprise procurement emphasizes custom data pipelines, dedicated support tiers, and multi-jurisdiction compliance certification. These buyers negotiate multi-year contracts with professional services attachments that inflate lifetime value metrics for vendors.
- Startups:Early-stage companies favor developer-centric platforms with embedded analytics for SaaS billing workflows, prioritizing speed-to-integration over feature depth. Stripe and similar providers capture this segment through documentation quality and sandbox environments.
- Medium Enterprises:Mid-market banks face extended deployment timelines due to data science talent scarcity for advanced anomaly detection systems.
- Small Enterprises:Micro-merchants and sole proprietors access analytics through processor-bundled offerings with limited customization.
Large Corporations command the highest revenue per account, while Startups are scaling fastest in absolute customer additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where real-time payment mandates justify premium analytics licensing, while vendors competing in India and Brazil face compressed margins on compliance-driven procurement.
United States
The Federal Reserve's FedNow instant settlement protocol compels tier-one card issuers to upgrade transaction monitoring infrastructure within sub-second windows. Financial institutions in New York and Chicago negotiate multi-year contracts embedding professional services for bespoke data pipeline integration. Silicon Valley technology clusters anchor developer-centric platform adoption among SaaS billing workflows.
Germany
Data sovereignty requirements under national banking regulations fragment workload placement between edge processing and centralized analytics. Frankfurt-based financial institutions retrofit legacy reporting systems to satisfy European Banking Authority disclosure mandates. Bavarian technology hubs concentrate hybrid cloud architecture development for compliance-sensitive deployments.
United Kingdom
The Financial Conduct Authority's consumer duty rules compel payment service providers to demonstrate fair value through transparent transaction analytics. London merchant acquirers bundle intelligence into interchange fee negotiations, consolidating procurement channels away from standalone vendors. Manchester and Birmingham mid-market retailers drive checkout optimization demand.
India
Reserve Bank of India guidelines on digital lending data standards create compliance-driven procurement among non-bank financial companies. Mumbai and Bangalore technology clusters anchor localized platform development for borrower data collection requirements. Payment analytics vendors face margin compression as regulatory mandates dominate purchasing criteria over performance optimization.
China
State Administration for Market Regulation fintech oversight protocols add certification complexity for platforms seeking multi-jurisdiction scale. Shanghai and Shenzhen financial technology corridors concentrate domestic analytics platform development for merchant cash advance underwriting. Data localization requirements constrain foreign vendor participation in state-affiliated banking modernization programs.
Payment Analytics Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated infrastructure providers defending embedded positions against API-first challengers. The vendor base separates into three strategic tiers: developer-centric platforms capturing startup procurement, unified commerce data layers anchoring enterprise merchant relationships, and core-embedded analytics occupying defensive positions at regional banks. Dominant competitive moves include strategic partnerships with merchant acquirers and geographic expansion through jurisdiction-specific compliance certification.
Within the infrastructure-embedded tier, Fiserv occupies a defensive position against standalone challengers through analytics integration within core banking stacks. Stripe and Adyen exemplify contrasting archetypes: the former anchors developer-centric API-first adoption for SaaS billing workflows, while the latter sustains unified commerce data layers for cross-channel transaction intelligence. These three companies represent the primary competitive vectors shaping procurement patterns across financial institutions and enterprise merchants.
| Leading Market Players |
|---|
| Stripe |
| Adyen |
| DualEntry |
| Fiserv |
| Block Inc. |
| BlueSnap |
| Mastercard |
| Plaid |
| ProfitWell Metrics by Paddle |
| Others |
Supply Flow & Price Mechanics
Multi-year SaaS contracts with capacity reservation clauses lock in cloud infrastructure access and stabilize unit economics for payment analytics vendors competing across FedNow-mandated deployments. These arrangements bind financial institutions to predictable subscription tiers while insulating providers from spot compute price volatility in Frankfurt and Virginia data centers.
Pricing Analysis
US-Germany price spreads exceed three-to-one for equivalent fraud detection modules, reflecting FedNow latency requirements and Bundesbank data sovereignty compliance costs. Three-tier pricing structure across premium real-time, standard batch, and economy reporting levels stratifies by sub-second processing capability and PSD3 certification grade. Cost compression in the mid-market tier intensifies as processor-bundled offerings absorb standalone analytics budgets. Startups exhibit highest price sensitivity, negotiating usage-based consumption against enterprise procurement teams demanding fixed professional services attachments.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for specialized GPU hardware anchoring graph neural network training clusters. Supply concentrates in Taiwan for advanced semiconductors, the United States for cloud hyperscaler infrastructure, and Ireland for EU data residency-compliant compute pools. Raw material dependencies span NVIDIA accelerator chips, high-bandwidth memory modules, and low-latency networking fabric. Single-source vulnerability around specialized AI silicon creates procurement risk for vendors building sub-200-millisecond authorization pipelines. Distribution runs through direct enterprise sales with embedded implementation services, bypassing traditional software reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment analytics sits in early-cycle expansion as real-time payment infrastructure mandates force wholesale replacement of legacy transaction monitoring stacks across tier-one financial institutions.
For Market Incumbents: Consolidate embedded positions within core banking ecosystems through deeper API integration and exclusive data pipeline partnerships. Defensive moves should prioritize certification pre-emption for PSD3 technical standards and FedNow operational requirements. Threat from API-first challengers demands accelerated professional services capacity in New York and London to match Stripe's developer experience quality. For New Entrants and Emerging Players: Mid-market bank data science talent scarcity creates service-layer gaps where incumbents under-serve deployment and model tuning needs. White-space targets include hybrid cloud architecture implementation for German regional banks and embedded analytics integration for Buy Now Pay Later workflows. The most penetrable segment spans non-bank financial companies in India facing RBI digital lending compliance deadlines. Go-to-market should anchor in processor partnership channels rather than direct standalone sales. For Investors and Strategic Acquirers: Capital is best deployed toward verticalized fraud detection specialists with proven sub-second latency engineering and multi-jurisdiction certification track records. Long-term viability over a decade-plus horizon rests on regulatory compliance moats deepening faster than cloud infrastructure commoditization erodes them. The signal to watch is FedNow transaction volume inflection triggering accelerated tier-two bank procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded analytics within Adyen's unified commerce layer anchors enterprise merchant retention. |
| Geographic Expansion | Jurisdiction-specific compliance certification for RBI guidelines captures India digital lending procurement. |
| Strategic Partnership | Merchant acquirer bundling agreements consolidate UK mid-market analytics channels away from standalone vendors. |
| Acquisition of Specialist Firm | Graph neural network engineering teams compress false-positive rates within FedNow authorization windows. |
| Product Launch | Hybrid cloud architectures satisfy German data sovereignty requirements while accessing scalable centralized compute. |
Methodological Framework
A spread of perspectives from payment technology CTOs, bank procurement officers, regulatory compliance leads, and merchant acquirer platform engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, European Banking Authority technical standard drafts, and Reserve Bank of India circular archives. Bottom-up segment sizing triangulated against top-down addressable market estimates from cloud hyperscaler financial services vertical disclosures.
Segmentation dimensions modeled span deployment architecture, end-user category, solution type, and customer scale tier across the projection horizon. Analytical framework derived CAGRs from penetration curve analysis in comparable real-time infrastructure replacement cycles, adjusted for regulatory mandate acceleration effects. Industry-specific forecast inputs incorporated FedNow rollout timelines and PSD3 implementation cost estimates from German bank retrofit disclosures.
Forecasts assume regulatory continuity in US Federal Reserve, European Banking Authority, and UK Financial Conduct Authority regimes; material policy shifts would require re-modeling adoption curves and compliance cost burdens. Specific risk factors include talent scarcity extending deployment timelines and legacy infrastructure lock-in constraining cloud migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
MENA Digital Payments Market
Payments
Electronic Payment System for Transportation Market
Payments
France Buy Now Pay Later Services Market
Payments
France Payments Market
Payments
South Korea Digital Payments Market
Payments
Singapore Remittance Market
Payments
Digital Debit Market
Payments
Mobile Card Reader Market
Payments
Mobile Payment Transaction Market
Payments
North America Accounts Payable Automation Market
Payments
Electronic Cash Register Market
Payments
India Forex Cards Market
Payments
Italy Gift Cards Market
Payments
Asia Pacific Real Time Payment Market
Payments
Recurring Payments Market
Payments
B2C Payment Market