
 India Metal Packaging Market | 2026-2036
India Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Metal Packaging Market Foresight
Asset-light leasing models for can-forming equipment is rewriting competitive entry dynamics in Indian metal packaging. Kaira Can Company Limited leverages captive tinplate sourcing to sustain margin stability across volatile steel cycles. Hindustan Tin Works Ltd anchors its position through deep specialization in decorative lithography for aerosol and food cans. Ball Corporation competes via technology leadership in lightweight aluminum bottle designs for premium beverage clients.
India metal packaging encompasses rigid containers fabricated from aluminum, steel, or tinplate through processes including deep drawing, three-piece welding, and two-piece drawing and ironing, typically specified to thicknesses between 0.15 mm and 0.40 mm depending on internal pressure and shelf-life requirements. These structures provide oxygen barrier protection, mechanical stackability, and thermal process compatibility for sterilized and retorted contents across food, beverage, pharmaceutical, and chemical supply chains. Cans dominate volume throughput due to established beverage industry offtake and recycling infrastructure, while containers capture widening pharmaceutical and cosmetics demand where tamper-evidence and light-blocking properties command specification premiums. Aluminum leads material selection for weight-sensitive beverage applications, whereas tinplate sustains share in processed food segments where sulfur staining resistance and cost positioning remain decisive.
BIS food-contact standards, FSSAI packaging safety notifications, and CEA energy-efficiency mandates for metal forming operations collectively shape compliance costs and capital planning across Indian metal packaging facilities. The PLI scheme for specialty steel and aluminum downstream processing redirects investment toward domestic tinplate and can-stock capacity, reducing import dependence for critical substrates. Stakeholders must monitor evolving EPR frameworks for metal packaging waste and assess backward integration into coil coating or printing operations before substrate cost volatility hardens into structural margin compression.
Market Dynamics
The PLI scheme for specialty steel and aluminum downstream processing is redirecting capital toward domestic tinplate and can-stock capacity, compressing import dependence for critical substrates while reshaping supplier economics across Maharashtra and Gujarat beverage corridors.
Growth Catalysts
- Beverage bottling corridor expansion:Carbonated drinks and craft beer producers in Maharashtra and Gujarat are scaling aluminum can procurement, creating sustained substrate demand pull.
- FSSAI packaging safety notifications:Mandatory compliance for food-contact surfaces is forcing substrate traceability upgrades that favor organized domestic suppliers with certified coil coating capabilities.
- Deep drawing process advancement:Two-piece drawing and ironing technology adoption is reducing material thickness specifications to 0.15 mm for weight-sensitive beverage applications.
Market Restraints
- Steel cycle volatility:Tinplate input costs fluctuate with global steel pricing, squeezing margin stability for converters without captive sourcing arrangements.
- Import substrate concentration:Critical aluminum can-stock grades remain concentrated among ASEAN and Middle East suppliers, exposing procurement to currency and freight volatility.
- Sulfur staining limitation:Tinplate's performance ceiling in high-acid processed foods creates technical barriers against glass and flexible pouch substitution threats.
Strategic Opportunities
- Karnataka processed food corridor:Underpenetrated demand for retortable tinplate containers exists among South Indian spice and ready-meal exporters targeting Gulf markets.
- EPR framework evolution:Extended producer responsibility mandates for metal packaging waste are creating first-mover advantages for converters with closed-loop collection infrastructure.
- Digital printing convergence:Integration of inkjet decoration with coil coating lines is enabling short-run customization for craft beverage brands.
Industry Challenges
- Deep drawing technician scarcity:Qualified operators for precision die maintenance and tool calibration are concentrated among legacy tinplate facilities in Mumbai-Pune belt.
- BIS certification timeline compression:Food-contact surface approval cycles now extend 14-18 months, delaying new substrate qualification for seasonal beverage launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Metal Packaging Market |
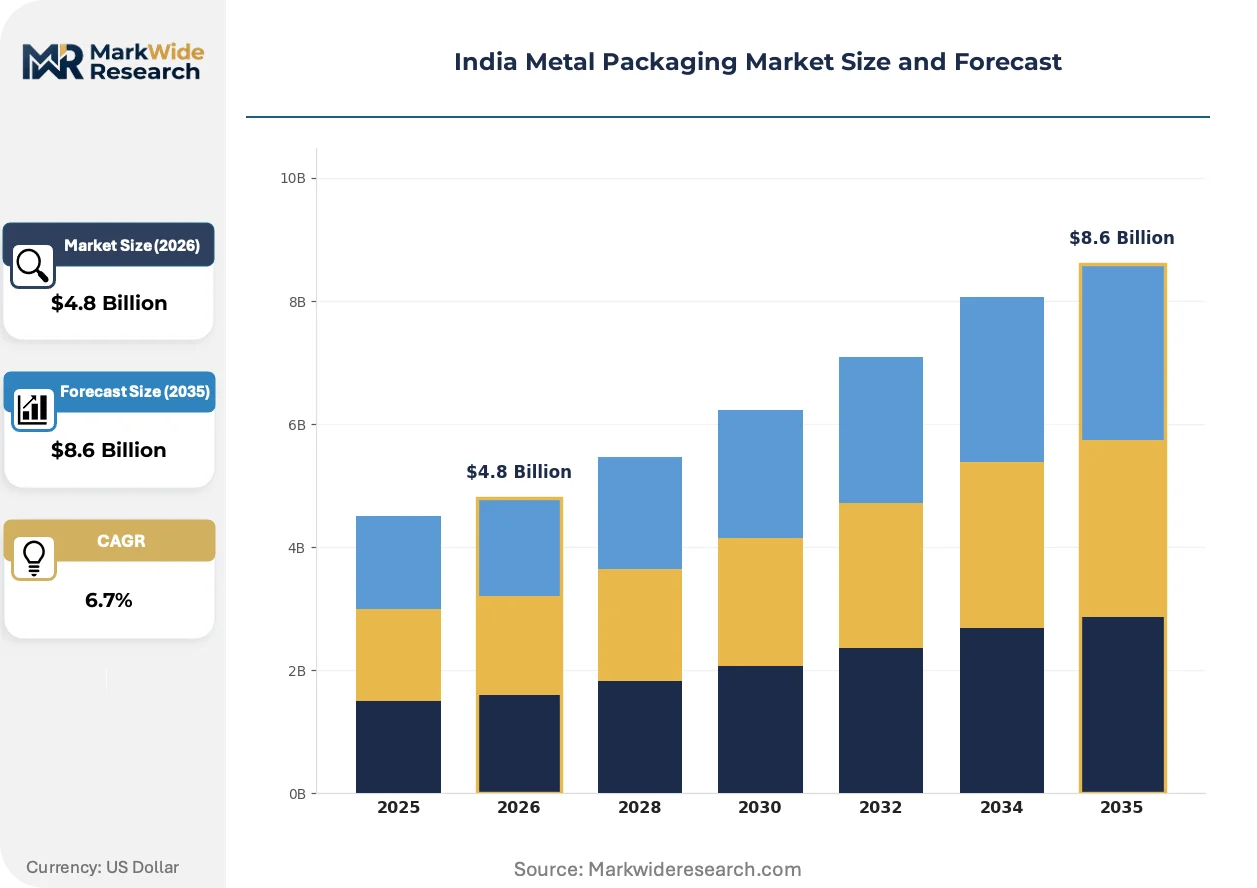
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Containers, Drums, Bottles End User: Food & Beverages, Pharmaceuticals, Cosmetics, Chemicals Technology: Printing, Coating, Forming, Sealing Material: Aluminum, Steel, Tinplate, Others |
| Companies Covered | Kaira Can Company Limited, Nikita Containers Pvt Ltd, Hindustan Tin Works Ltd, Shetron Limited, The Tinplate Company of India Limited, Zenith Tins Private Limited, Deccan Cans and Printers Pvt Ltd, Hi-Can Industries Pvt Ltd, Ball Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Metal Packaging Market Shifts & Advancements
Lightweighting imperatives and decoration flexibility are converging to reshape equipment investment priorities across Indian metal packaging converters, with technology choices increasingly tied to beverage brand sustainability commitments.
Two-piece drawing and ironing technology is migrating from standard aluminum beverage cans toward shaped bottles and slim-profile containers. Premium spirits and sparkling water brands in Mumbai and Bengaluru are specifying these formats at 15-20% volume premiums. This migration is compressing demand for three-piece welded construction in sub-250 ml categories.
BIS food-contact standards are tightening migration limits for heavy metals and epoxy-based coatings on internal can surfaces. FSSAI has aligned testing protocols with EU Regulation 10/2011, forcing reformulation of legacy lacquer systems. Processed food exporters to Europe are accelerating compliance investments ahead of domestic mandate expansion.
Asset-light leasing arrangements for can-forming equipment are displacing outright purchase models among regional beverage entrants. Maharashtra-based craft breweries and Gujarat-based flavored soda startups are accessing German and Italian forming lines through 5-year operational lease structures. This model is most visible in Ahmedabad and Pune, where facility footprints under 50,000 square feet dominate new capacity announcements.
India Metal Packaging Market Segmentation
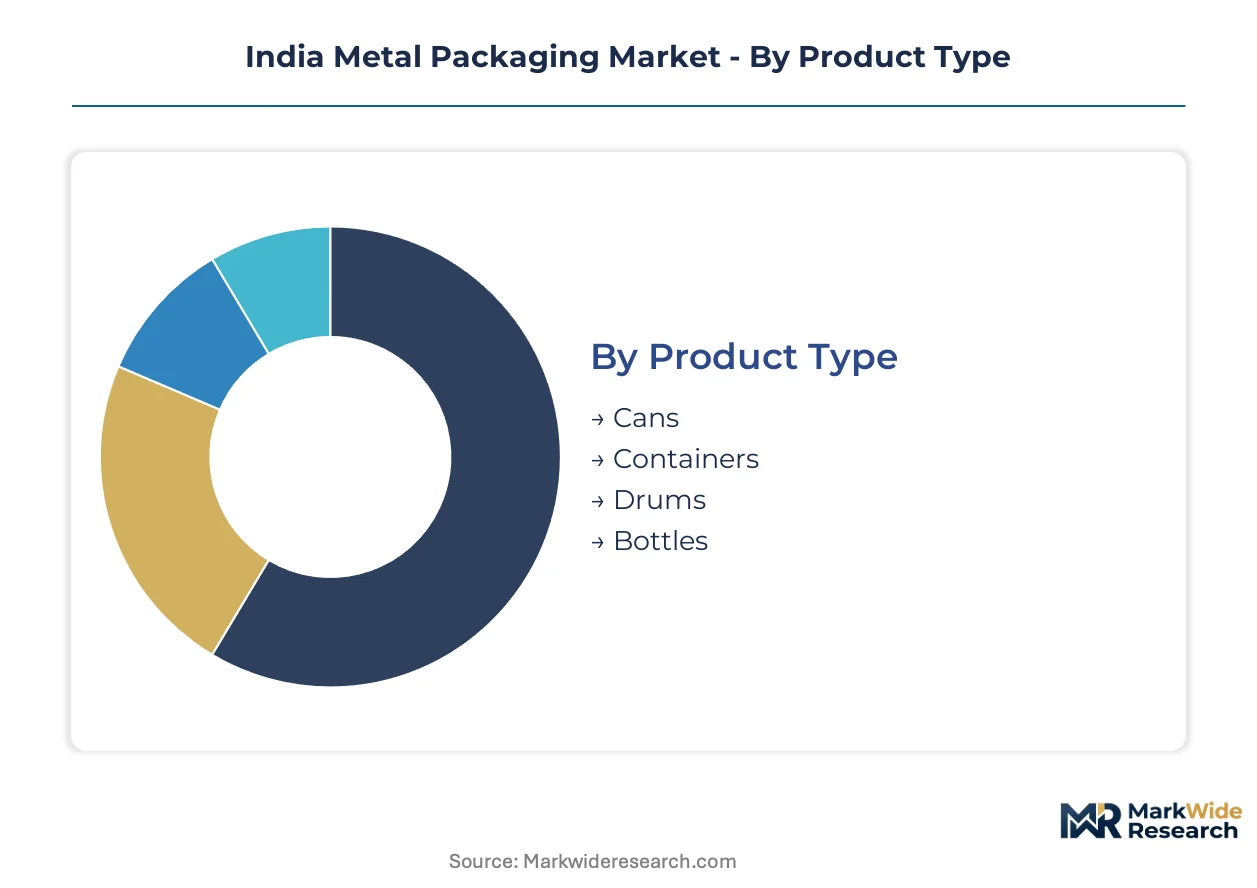
Segmentation in Indian metal packaging reveals how substrate choices, forming technologies, and end-use specifications create distinct competitive arenas with divergent margin profiles and capital requirements.
Product Type:
Mature formats dominate volume throughput while emerging shapes capture premium positioning.
- Cans:Two-piece drawing and ironing construction achieves wall thicknesses down to 0.15 mm for beverage applications. Maharashtra and Gujarat bottling corridors absorb aluminum can output for carbonated drinks and craft beer, with BIS food-contact certification now mandatory for all new substrate qualifications.
- Containers:Three-piece welded tinplate construction serves retortable processed food segments where sulfur staining resistance commands specification premiums. Karnataka spice exporters and ready-meal processors drive demand for 0.25-0.40 mm specification ranges targeting Gulf market compliance.
- Drums:Steel rolling and seaming processes produce 200-liter capacity units for chemical and lubricant bulk storage. Industrial corridors in Gujarat host concentrated drum fabrication capacity serving petrochemical downstream applications.
- Bottles:Shaped aluminum bottle formats command 15-20% volume premiums in Mumbai and Bengaluru premium spirits markets. Two-piece technology migration enables slim-profile specifications previously constrained to standard can geometries.
Cans retain volume leadership; bottles hold the steepest expansion curve.
End User:
Application-driven specifications separate commodity substrate demand from value-added conversion opportunities.
- Food & Beverages:Retort compatibility and oxygen barrier specifications dominate tinplate procurement for processed foods, while aluminum lightweighting drives beverage can specifications. FSSAI packaging safety notifications now mandate full material traceability for food-contact surfaces.
- Pharmaceuticals:Tamper-evidence and light-blocking properties command specification premiums for aluminum tube and container formats. CDSCO registration requirements shape substrate qualification timelines for drug-contact applications.
- Cosmetics:Aerosol propellant compatibility and decorative lithography precision define tinplate and aluminum specifications. Deep specialization in decorative printing separates organized converters from regional competitors.
- Chemicals:Corrosion-resistant internal coatings and UN certification for hazardous material transport govern steel drum specifications. Gujarat chemical manufacturing clusters generate concentrated demand pull for industrial packaging formats.
Food & Beverages anchors substrate volume; Pharmaceuticals posts the most rapid specification upgrading.
Technology:
Process capabilities determine which converters can access premium end-use segments with defensible margin structures.
- Printing:Digital inkjet decoration convergence with coil coating lines enables short-run customization for craft beverage brands. Asset-light leasing models for printing equipment reduce entry barriers for regional beverage entrants in Ahmedabad and Pune.
- Coating:Internal lacquer systems face reformulation pressure as BIS aligns migration limits with EU Regulation 10/2011. Processed food exporters accelerate compliance investments ahead of domestic mandate expansion.
- Forming:Deep drawing and three-piece welding capabilities concentrate among legacy tinplate facilities in the Mumbai-Pune belt. Qualified technicians for precision die maintenance remain scarce, constraining capacity expansion timelines.
- Sealing:Double-seam integrity specifications vary by internal pressure requirements and shelf-life targets. Beverage applications demand hermetic performance under carbonation stress, while food containers prioritize retort cycle durability.
Forming commands the highest capital intensity; printing is gaining share fastest through digital convergence.
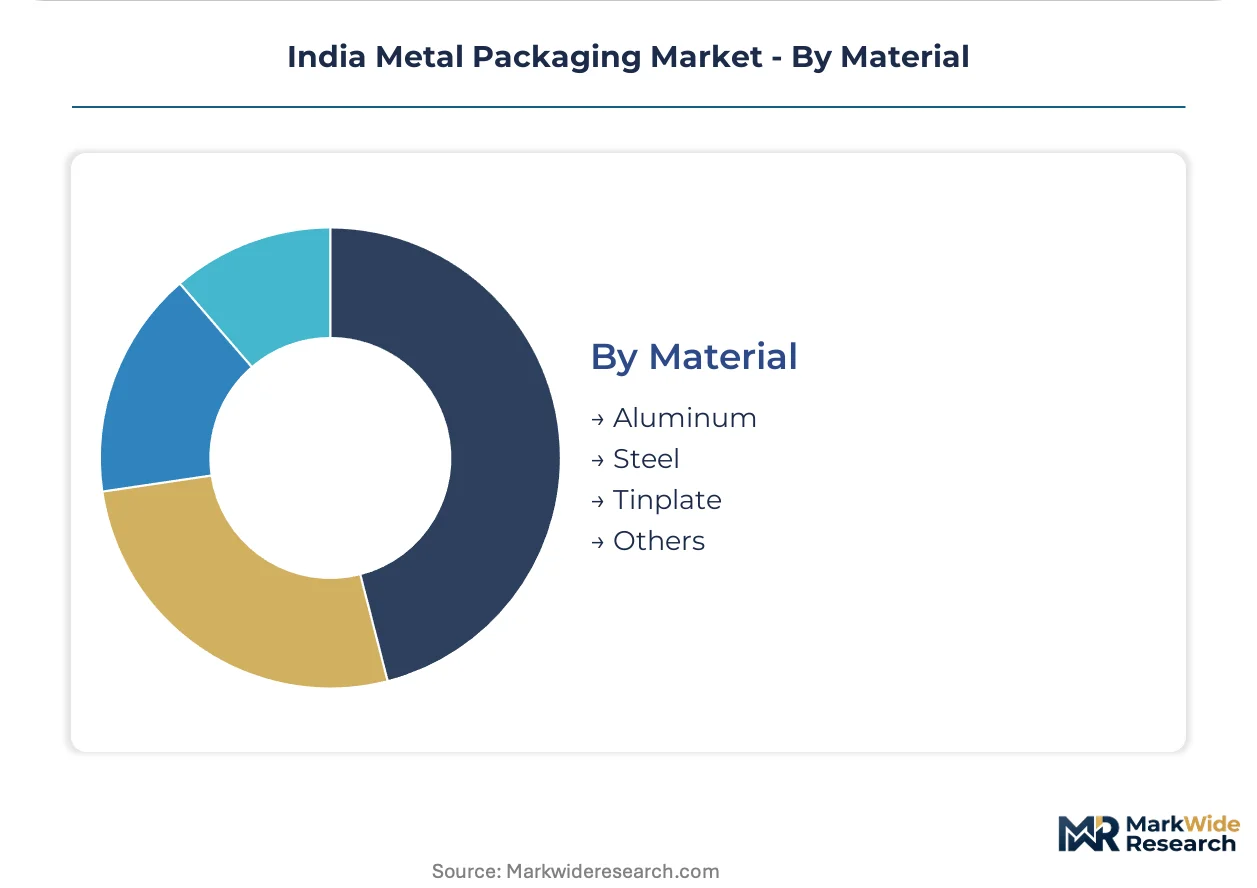
Material:
Substrate selection locks converters into distinct supply chain risk profiles and backward integration economics.
- Aluminum:Can-stock grades specified to 0.15-0.25 mm thickness ranges serve weight-sensitive beverage applications. Import concentration among ASEAN and Middle East suppliers exposes procurement to currency and freight volatility.
- Steel:Cold-rolled substrate for drum and industrial container fabrication tracks global steel pricing cycles. PLI scheme incentives for specialty steel downstream processing redirect investment toward domestic coil capacity.
- Tinplate:Electrolytic tin coating provides sulfur staining resistance for high-acid processed foods. Kaira Can Company Limited leverages captive tinplate sourcing to sustain margin stability across volatile steel cycles.
- Others:Chromium-coated steel and polymer-laminated substrates occupy niche pharmaceutical and cosmetic applications where specific barrier properties override cost considerations.
Tinplate sustains volume leadership in food-contact segments; aluminum posts the steepest trajectory in beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's metal packaging trade balance tilts toward substrate imports, with aluminum can-stock dependence on ASEAN and Middle East suppliers offsetting domestic tinplate capacity expansion under PLI incentives.
Maharashtra
Beverage bottling corridors around Mumbai and Pune absorb aluminum can output for carbonated drinks and craft beer. FSSAI packaging safety notifications mandate full material traceability for food-contact surfaces, favoring organized suppliers with certified coil coating capabilities. The Mumbai-Pune belt concentrates legacy tinplate facilities where qualified technicians for precision die maintenance remain scarce.
Gujarat
Industrial packaging demand from chemical manufacturing clusters drives steel drum fabrication capacity concentrated in Ahmedabad and Vadodara. CEA energy-efficiency mandates for metal forming operations shape compliance costs across regional facilities. Asset-light leasing models for can-forming equipment are displacing outright purchase models among regional beverage entrants in Ahmedabad.
Karnataka
Underpenetrated demand for retortable tinplate containers exists among South Indian spice and ready-meal exporters targeting Gulf markets. BIS certification timelines for food-contact surface approvals now extend 14-18 months, delaying new substrate qualification. Bengaluru anchors premium spirits and sparkling water demand for shaped aluminum bottle formats commanding volume premiums.
Tamil Nadu
Pharmaceutical and cosmetics packaging demand concentrates around Chennai, where tamper-evidence and light-blocking properties command specification premiums for aluminum tube and container formats. CDSCO registration requirements shape substrate qualification timelines for drug-contact applications. The state's industrial corridors host coil coating operations serving export-oriented processed food processors.
Delhi-NCR
North Indian processed food distribution hubs generate demand pull for three-piece welded tinplate construction in retortable applications. DGFT trade policy notifications influence import duty structures for critical aluminum can-stock grades. Noida and Faridabad host decorative lithography specialists serving aerosol and food can segments.
India Metal Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate conversion and decoration niches. The vendor base spans captive tinplate producers, independent can converters, and multinational technology licensors, creating a tiered structure where scale and specialization separate margin tiers. Three archetypes dominate: backward-integrated substrate owners, asset-light regional entrants leasing forming equipment, and technology-focused premium format specialists. Capacity expansion and digital printing convergence represent the dominant competitive moves reshaping facility investment priorities.
Among domestic integrated producers, Kaira Can Company Limited and The Tinplate Company of India Limited exemplify the backward-integrated archetype with captive substrate sourcing. Hindustan Tin Works Ltd occupies a position within the specialization tier, with its name signaling deep focus on tin-based fabrication. Ball Corporation represents the multinational technology licensor archetype, with its corporate suffix indicating US-incorporated status and beverage packaging lineage.
| Leading Market Players |
|---|
| Kaira Can Company Limited |
| Nikita Containers Pvt Ltd |
| Hindustan Tin Works Ltd |
| Shetron Limited |
| The Tinplate Company of India Limited |
| Zenith Tins Private Limited |
| Deccan Cans and Printers Pvt Ltd |
| Hi-Can Industries Pvt Ltd |
| Ball Corporation |
| Others |
Supply & Pricing Matrix
ASEAN and Middle East can-stock concentration leaves Indian converters exposed to freight and currency volatility, compressing margin pools at the substrate procurement tier while domestic tinplate capacity expansion under PLI incentives reshapes bargaining power toward Maharashtra and Gujarat beverage bottlers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across premium certified coil, standard domestic tinplate, and economy-grade imported aluminum. Price differentiation hinges on BIS certification tier and volume scale, with craft beverage brands least price-sensitive due to sustainability premiums. Cost compression in standard-grade tinplate is intensifying because Kaira Can Company's captive sourcing sets a floor that independent converters struggle to match.
Supply Chain Analysis
Tariff exposure between India and ASEAN suppliers dominates supply chain risk management, with DGFT notification delays amplifying working capital strain. Raw material procurement draws from South Korean aluminum rolling mills, Japanese tinplate coaters, and domestic JSW Steel specialty coil operations. Single-source vulnerability concentrates in 0.15 mm can-stock grades where Middle East suppliers control specification leadership. Distribution runs through Maharashtra-Gujarat beverage corridors with just-in-time coil delivery to leased forming facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India metal packaging sits in early-cycle expansion, with PLI-scheme substrate localization and craft beverage proliferation creating penetration tailwinds that favor organized converters with certified coil coating capabilities.
For Market Incumbents: Insulate margin stability by accelerating backward integration into domestic tinplate coil coating before import substrate volatility hardens into structural compression. Prioritize BIS certification pipeline investment to capture FSSAI-mandated traceability premiums. Defend against asset-light regional entrants by locking multi-year offtake agreements with Maharashtra craft breweries. For New Entrants and Emerging Players: Karnataka's underpenetrated retortable container demand among Gulf-facing spice exporters offers the most penetrable white-space target. Asset-light leasing of German forming equipment in Bengaluru micro-facilities bypasses technician scarcity constraints in the Mumbai-Pune belt. Lead with digital inkjet decoration capabilities to capture short-run craft beverage customization premiums. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional can converters in Ahmedabad and Pune lacking backward integration. Five-to-ten-year viability hinges on substrate cost pass-through mechanics and EPR infrastructure ownership. Watch for BIS certification timeline compression as the inflection signal separating scalable acquirers from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Coating | Captive tinplate supply insulates margin stability against JSW Steel pricing cycles. |
| Digital Printing Convergence | Inkjet decoration integration enables short-run craft brand customization in Pune micro-facilities. |
| EPR Infrastructure Buildout | Closed-loop collection systems create first-mover advantage under evolving metal waste frameworks. |
| Asset-Light Equipment Leasing | German forming line leases reduce entry barriers for regional beverage entrants in Ahmedabad. |
| BIS Certification Acceleration | Fast-tracked food-contact approvals capture FSSAI-mandated traceability premiums ahead of seasonal launches. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at tinplate conversion facilities, procurement leads at Maharashtra beverage bottlers, coil coating technical directors, and DGFT trade policy specialists, then refined against secondary validation from BIS certification databases, FSSAI packaging safety notifications, PLI scheme disbursement records, and customs import data for aluminum can-stock grades. Bottom-up facility capacity estimates triangulated with top-down substrate consumption models across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across product type (cans, containers, drums, bottles), material substrate (aluminum, tinplate, steel), end-use application (food and beverage, pharmaceutical, cosmetic, chemical), and technology tier (forming, coating, printing, sealing). CAGRs derived from installed capacity expansion timelines and beverage industry offtake trajectories, with PLI incentive disbursement velocity and BIS certification approval cycles as industry-specific forecast inputs across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, global steel pricing cycles, or Middle East freight indices would shift the trajectory. Forecasts embed assumptions regarding PLI scheme continuity and FSSAI notification implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Brass Foils Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Cans Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Metal Containers Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Novelty Tins Market