
 Italy Telecom Market | 2026-2036
Italy Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Telecom Market Outlook
Convergent bundling of mobile, fixed broadband, and streaming content is repositioning consumer choice architecture across the Italian market. Telecom Italia (TIM) leverages its legacy copper and fiber infrastructure to sustain wholesale dominance in underserved provinces. WindTre competes aggressively on price-positioned mobile plans while Fastweb anchors premium fiber-to-the-home penetration in metropolitan zones.
Italy Telecom encompasses the provision of voice, data, and connectivity services through terrestrial and wireless infrastructures operating across frequencies from 700 MHz to 26 GHz, utilizing packet-switched IP architectures with latency targets below 10 milliseconds for 5G standalone deployments. Its primary commercial purpose is enabling digital transaction flows for consumers, enterprises, and public administrations. Fiber Optic deployment captures the dominant share of infrastructure investment as operators replace aging copper loops, while 5G services represent the fastest-expanding revenue pool as industrial private networks gain traction among manufacturing end users. Mobile Services remain the most contested segment, with prepaid plan erosion pressuring average revenue per user across all pricing models.
AGCOM, Italy's communications regulator, enforces wholesale access pricing and net neutrality compliance under the European Electronic Communications Code, directly shaping interconnection economics and retail tariff floors. BSI and CE marking requirements govern network equipment certification, creating compliance thresholds for infrastructure vendors seeking market entry. Stakeholders must monitor spectrum auction timing and wholesale fiber unbundling rulings as decisive variables for capital allocation and partnership strategy.
Market Dynamics
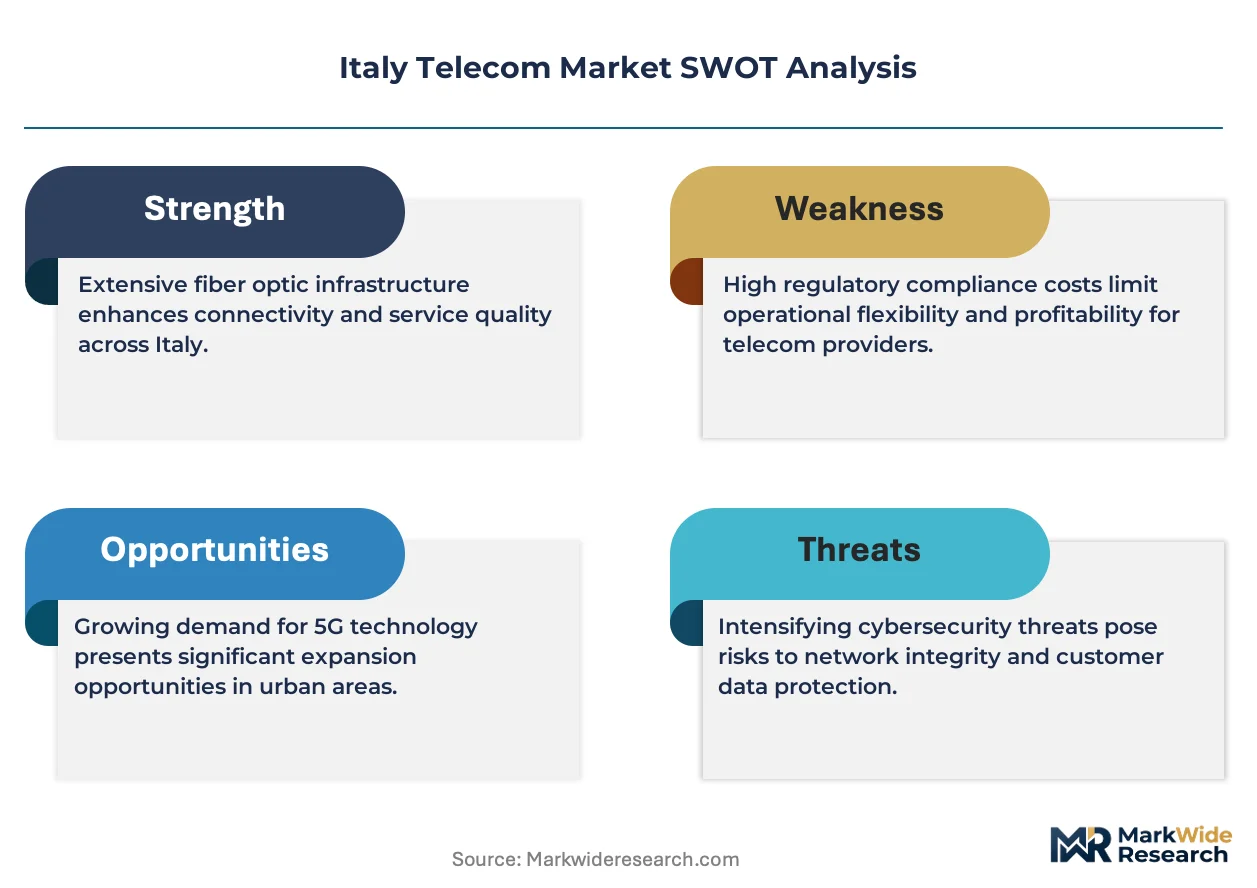
Wholesale fiber unbundling mandates under the European Electronic Communications Code are compressing incumbent margins while forcing infrastructure co-investment models across Italy's provincial networks.
Growth Catalysts
- Industrial Private Networks:Manufacturing clusters around Milan and Turin are deploying 5G standalone architectures for sub-10 millisecond latency in automated production lines.
- AGCOM Wholesale Pricing:Regulated access tariffs are lowering barriers for alternative operators to lease last-mile fiber in underserved southern provinces.
- Enterprise Cloud Migration:Italian manufacturers are consolidating legacy MPLS circuits into SD-WAN overlays with direct cloud peering.
Market Restraints
- Copper Loop Retirement Costs:Telecom Italia faces stranded asset write-downs as fiber replacement timelines accelerate in rural Lombardy and Piedmont.
- 5G Spectrum Scarcity:Mid-band allocation constraints in the 3.5 GHz range limit capacity expansion for mobile network operators.
- Permitting Delays:Municipal authorization timelines for street cabinet deployment average 18 months in historic city centers.
Strategic Opportunities
- Smart Agriculture Networks:Precision farming deployments in Emilia-Romagna require low-power wide-area connectivity with satellite backhaul integration.
- Public Administration Digitization:PNRR recovery funds are financing fiber-to-the-office mandates for municipal buildings in Sicily and Calabria.
- Edge Computing Convergence:Telecom operators are co-locating micro data centers with 5G base stations to serve industrial automation latency requirements.
Industry Challenges
- Field Engineering Shortage:Fiber splicing technician pipelines cannot match deployment targets set by Open Fiber and wholesale partners.
- Legacy Billing Integration:Convergent bundling platforms struggle to unify prepaid mobile, postpaid fixed, and streaming subscription ledgers.
- Net Neutrality Enforcement:AGCOM's zero-rating investigations create compliance uncertainty for content-inclusive tariff structures.
Report Scope
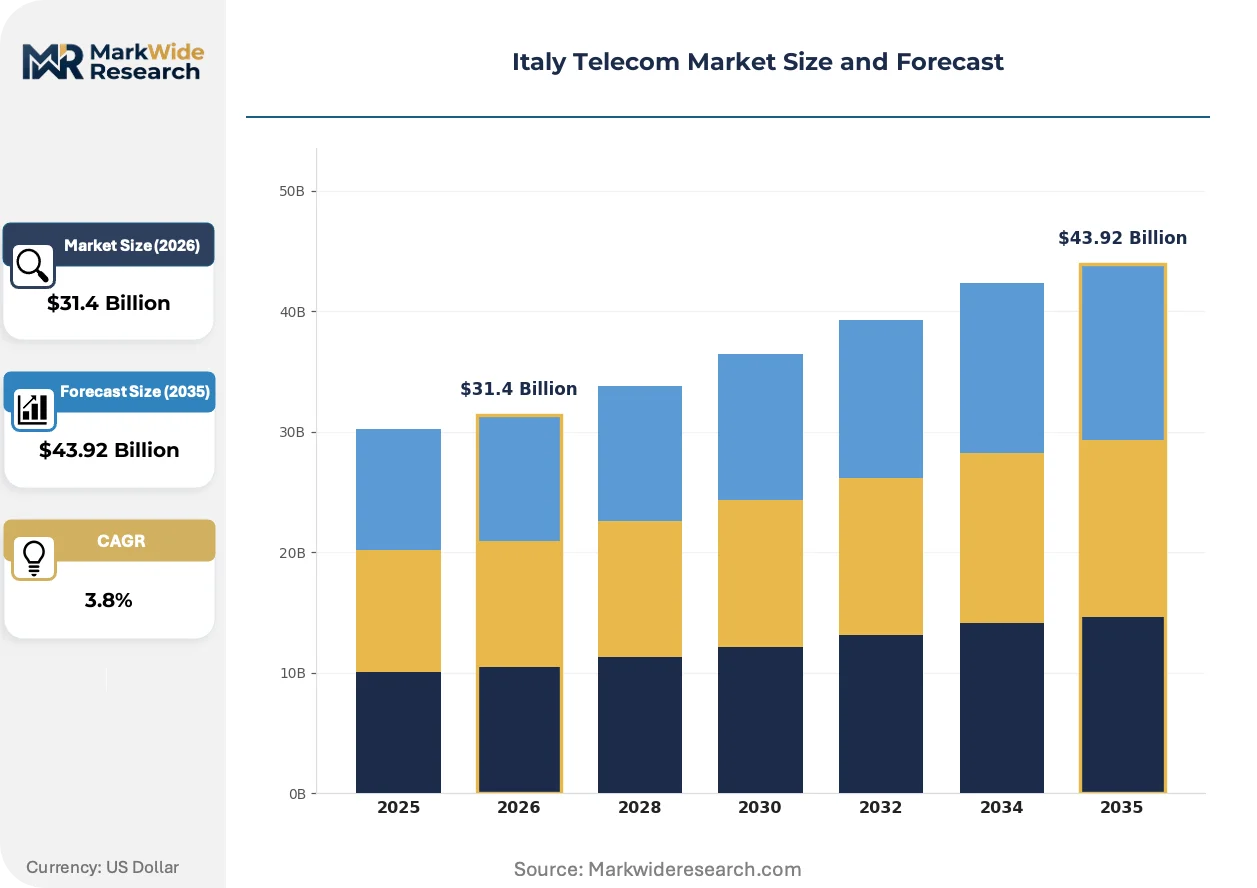
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Telecom Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $43.92 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Internet Services, Data Services End User: Residential Users, Small Businesses, Large Enterprises, Government Agencies Technology: 5G, Fiber Optic, DSL, Satellite Pricing Model: Prepaid Plans, Postpaid Plans, Bundled Services, Pay-as-you-go |
| Companies Covered | Telecom Italia (TIM), WindTre, Iliad Italia, Fastweb, Vodafone Italia, Tiscali, ho-mobile, Kena Mobile, Very Mobile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Telecom Market Strategic Shifts
Open RAN architectures are disrupting traditional vendor lock-in as Italian mobile operators seek supplier diversification for 5G network builds.
Virtualized radio access networks are modularizing hardware-software decoupling in macro cell deployments. WindTre and smaller challengers are piloting multi-vendor RAN stacks to reduce dependence on single-source equipment suppliers. This modularizing approach is compressing capital intensity per site while extending interoperability testing timelines.
AGCOM's implementation of the European Electronic Communications Code is mandating symmetric wholesale access obligations for fiber networks. The regulation forces Telecom Italia to publish reference offers for unbundled fiber loops in competitive areas. Metropolitan operators in Rome and Naples are leveraging these terms to accelerate overbuild strategies.
Enterprise buyers are consolidating multi-year connectivity contracts into shorter-term agreements with embedded flexibility clauses. Manufacturing procurement teams in Turin automotive suppliers now favor 24-month terms with technology refresh options over traditional 60-month lock-ins. This pattern is most pronounced among mid-market enterprises with hybrid cloud workloads.
Italy Telecom Market Segmentation
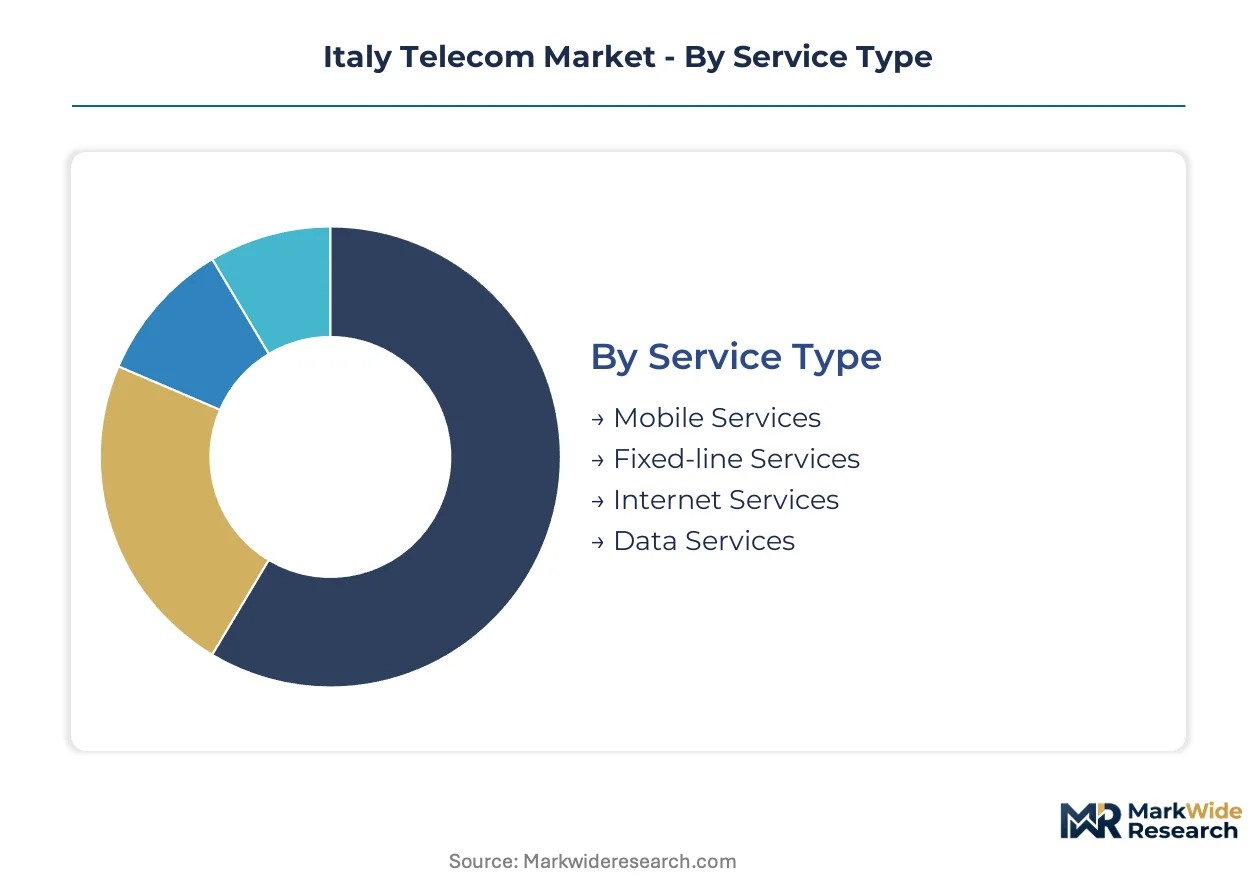
Italian telecom operators structure pricing and network investment around distinct service tiers and technology platforms. Buyer decisions hinge on latency requirements, mobility patterns, and convergence preferences across residential and enterprise segments.
Service Type:
Enterprise procurement teams prioritize guaranteed bandwidth and uptime SLAs over consumer-facing speed metrics.
- Mobile Services:Voice and data connectivity delivered over cellular architectures from 700 MHz to 26 GHz spectrum bands. Prepaid plan erosion in southern provinces compresses ARPU as subscribers migrate to data-heavy postpaid contracts.
- Fixed-line Services:Terrestrial voice connectivity through copper and fiber loops with circuit-switched legacy support. Northern industrial clusters around Milan maintain demand for PSTN-compatible lines despite national fiber transition mandates.
- Internet Services:Broadband access spanning ADSL, VDSL, and fiber-to-the-premises technologies. AGCOM wholesale pricing rulings enable alternative operators to lease Telecom Italia last-mile infrastructure in underserved markets.
- Data Services:Enterprise-grade leased lines, MPLS, and SD-WAN overlays with cloud direct-connect capabilities. Turin automotive suppliers are consolidating legacy circuits into software-defined architectures with sub-50 millisecond latency targets.
Volume sits with Internet Services; growth tilts toward Data Services.
End User:
Procurement scale and contract duration separate enterprise buyers from mass-market consumers.
- Residential Users:Individual households and multi-dwelling units consuming convergent bundles of mobile, fixed broadband, and streaming content. WindTre's aggressive price positioning targets value-conscious subscribers in metropolitan zones.
- Small Businesses:Shops, professional services, and micro-enterprises with 1-50 employees requiring basic connectivity without dedicated account management. Fastweb anchors premium fiber penetration among Milan professional services firms seeking symmetric upload speeds.
- Large Enterprises:Manufacturing, financial services, and logistics operators with multi-site networks and custom SLA requirements. Private 5G deployments in Piedmont automotive plants demand sub-10 millisecond latency for automated production lines.
- Government Agencies:National, regional, and municipal administrations procuring under public tender frameworks. PNRR recovery funds are financing fiber-to-the-office mandates for municipal buildings in Sicily and Calabria.
Residential Users generate the largest subscriber base; Large Enterprises command the steepest expansion trajectory.
Technology:
Deployment economics and spectral availability determine operator technology roadmaps.
- 5G:New radio architectures in sub-6 GHz and millimeter-wave bands with network slicing capabilities. Mid-band allocation constraints in the 3.5 GHz range limit capacity expansion for mobile network operators.
- Fiber Optic:GPON and XGS-PON passive optical networks replacing copper infrastructure. Open Fiber and wholesale partners face technician pipeline shortages that cannot match deployment targets in rural Lombardy.
- DSL:VDSL2 vectoring over existing copper pairs with diminishing coverage as fiber overbuild accelerates. Telecom Italia faces stranded asset write-downs as replacement timelines compress in competitive areas.
- Satellite:Geostationary and low-earth-orbit constellations serving remote locations beyond terrestrial reach. Precision farming deployments in Emilia-Romagna require satellite backhaul integration for low-power wide-area connectivity.
Fiber Optic dominates capital allocation; 5G climbs the fastest as industrial private networks multiply.
Pricing Model:
Payment structure reflects customer credit profiles and usage predictability.
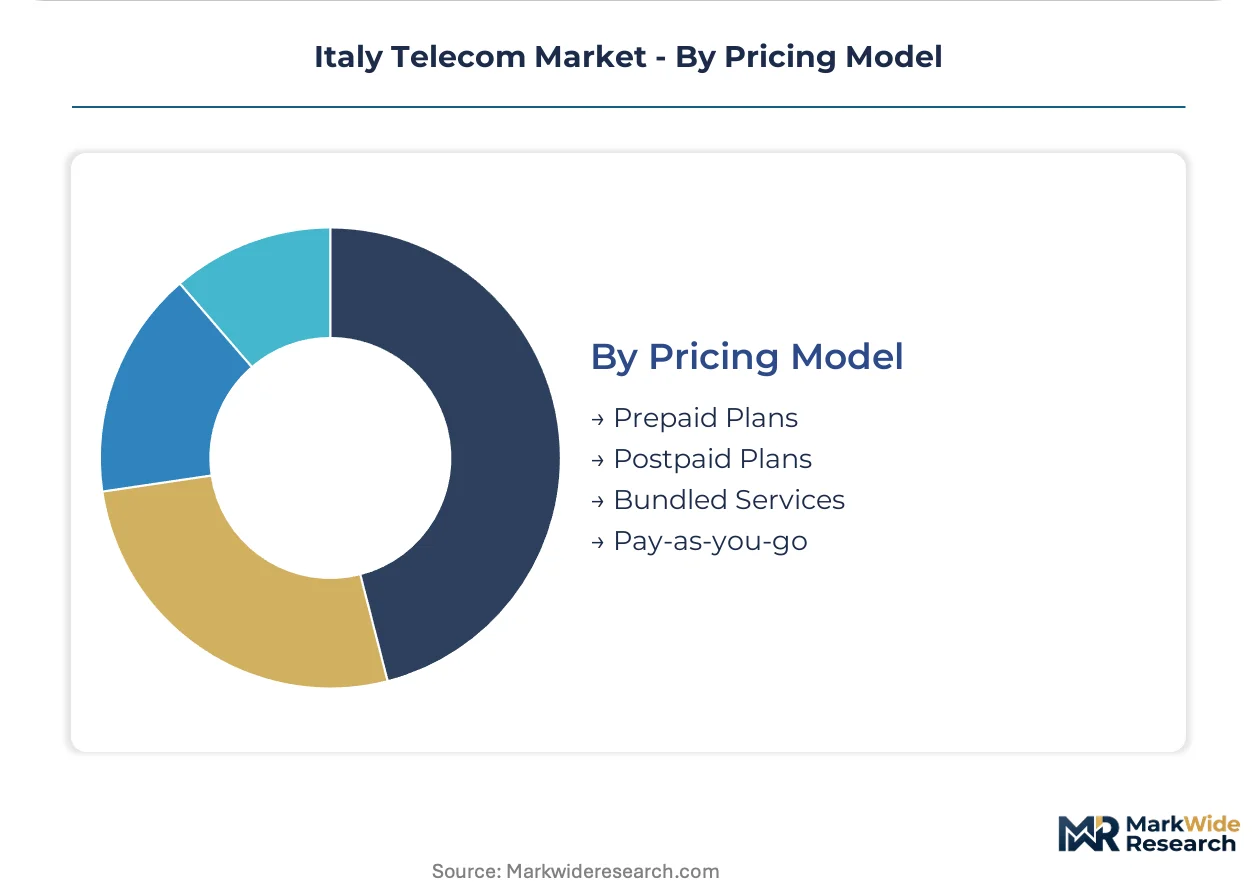
- Prepaid Plans:Advance payment for mobile voice and data allowances with no contractual commitment. Subscriber erosion across all operators pressures average revenue per user metrics in price-sensitive segments.
- Postpaid Plans:Monthly billing with device financing and family sharing options. Convergent bundling platforms struggle to unify prepaid mobile, postpaid fixed, and streaming subscription ledgers.
- Bundled Services:Combined mobile, fixed broadband, and content subscriptions with single-account management. AGCOM zero-rating investigations create compliance uncertainty for content-inclusive tariff structures.
- Pay-as-you-go:Usage-based metering for data services and international roaming. Enterprise buyers in Turin automotive supply chains now favor 24-month terms with technology refresh options over traditional 60-month lock-ins.
Postpaid Plans anchor revenue stability; Bundled Services gain share fastest as convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in northern industrial zones while consumption spreads across the peninsula. Infrastructure investment concentrates in Lombardy and Piedmont, leaving southern regions dependent on wholesale access regimes. This geographic split shapes operator strategies and regulatory intervention priorities.
Lombardy
Milan anchors enterprise demand for low-latency connectivity and cloud direct-connect services. AGCOM wholesale pricing rulings enable alternative operators to lease last-mile fiber in competitive metropolitan zones. The city hosts manufacturing procurement teams consolidating MPLS circuits into SD-WAN architectures.
Piedmont
Turin automotive suppliers drive private 5G deployments for automated production lines requiring sub-10 millisecond latency. PNRR recovery funds supplement operator capex for fiber-to-the-factory mandates in industrial corridors. Stranded copper asset risks concentrate here as Telecom Italia accelerates replacement timelines.
Veneto
Precision agriculture deployments in rural provinces require satellite backhaul integration for low-power wide-area networks. Municipal permitting delays average 18 months for street cabinet deployment in historic Verona and Padua centers. Wholesale fiber unbundling obligations under the European Electronic Communications Code reshape competitive entry economics.
Lazio
Rome concentrates government agency procurement under public tender frameworks for public administration digitization. Field engineering shortages constrain Open Fiber deployment targets in surrounding provinces. Edge computing convergence trials co-locate micro data centers with 5G base stations to serve institutional latency requirements.
Sicily
PNRR funds finance fiber-to-the-office mandates for municipal buildings in Palermo and Catania. Prepaid plan erosion pressures ARPU metrics as subscribers migrate toward data-heavy postpaid contracts. AGCOM zero-rating investigations create compliance uncertainty for content-inclusive tariff structures targeting price-sensitive segments.
Italy Telecom Market Competitive Environment
The competitive structure tilts toward infrastructure-heavy incumbents with legacy copper and fiber assets. Market concentration remains pronounced at the infrastructure layer while service-layer fragmentation intensifies through mobile virtual network operators and wholesale-dependent challengers. Two archetypes dominate: integrated infrastructure owners leveraging captive last-mile control, and asset-light retailers competing on price-positioned mobile plans. Consolidation pressure and co-investment partnerships constitute the primary competitive vectors as operators share fiber deployment burdens in marginal provinces.
Within the integrated infrastructure tier, Telecom Italia anchors wholesale dominance through legacy copper and fiber holdings across underserved provinces. WindTre exemplifies the price-competitive mobile-first archetype, while Fastweb occupies a premium fiber-to-the-home position in metropolitan zones. These three represent the structural poles around which challenger strategies orbit.
| Leading Market Players |
|---|
| Telecom Italia (TIM) |
| WindTre |
| Iliad Italia |
| Fastweb |
| Vodafone Italia |
| Tiscali |
| ho-mobile |
| Kena Mobile |
| Very Mobile |
| Others |
Value Chain & Pricing Dynamics
Fiber splicing technician shortages across Lombardy and Piedmont widen pricing-tier spreads as labor-cost differentials between northern industrial clusters and southern provinces force tiered service stratification. Premium fiber-to-the-home deployments in Milan command substantial markups over copper-replacement economics in Calabria and Sicily.
Pricing Analysis
Cost-down pressure on wholesale fiber loops accelerates because AGCOM-mandated access tariffs compress incumbent margins while enabling challenger overbuilds. Three-tier pricing structure across premium, standard, and economy levels separates enterprise SLA-guaranteed bandwidth from consumer best-effort services and basic mobile prepaid. Price differentiation traces to fiber depth and latency certification, with sub-10 millisecond 5G standalone commanding premiums over standard broadband. Small businesses in southern provinces exhibit highest price sensitivity; large manufacturing accounts in Turin automotive supply chains show lowest.
Supply Chain Analysis
Dual-sourcing requirements for 5G radio equipment now mandate multi-vendor qualification as Open RAN architectures displace single-supplier lock-in. Network hardware supply concentrates in China, South Korea, and Taiwan for baseband units and radio heads. Optical fiber and passive components draw from Corning-dominated US sources and Chinese fiber manufacturers. Single-source vulnerability in 3.5 GHz radio chipsets creates procurement risk. Distribution runs through Telecom Italia and Open Fiber wholesale platforms to retail service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's telecom market operates under acute field engineering scarcity that props wholesale pricing floors and constrains deployment velocity across underserved provinces.
For Market Incumbents: To counter Open RAN-driven vendor diversification, Telecom Italia should deepen backward integration into fiber installation crews through captive training academies in Lombardy and Piedmont. WindTre must defend mobile share against Iliad's price aggression by locking distribution through exclusive retail partnerships in metropolitan zones. For New Entrants and Emerging Players: The price-point gap between Fastweb's premium fiber and WindTre's economy mobile creates white-space opportunity for convergent challengers targeting Sicily and Calabria with PNRR-funded fiber-to-the-office bundles. Precision agriculture networks in Emilia-Romagna offer penetrable vertical entry with satellite-integrated LPWAN offerings. For Investors and Strategic Acquirers: The window for entry favors wholesale-dependent challengers with Open Fiber access agreements and industrial private network capabilities. Long-term viability hinges on 5G standalone spectrum position and edge computing co-location rights. Watch AGCOM's zero-ruling enforcement patterns as inflection signal for content-inclusive tariff compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Co-Investment Partnership | Shares deployment burden with Open Fiber in marginal provinces beyond Milan-Turin corridor. |
| 5G Standalone Network Slicing | Enables sub-10 millisecond latency guarantees for Turin automotive automation contracts. |
| Edge Computing Co-Location | Positions micro data centers at Rome base stations for public administration digitization. |
| Open RAN Multi-Vendor Integration | Reduces dependence on single-source suppliers while extending interoperability testing timelines. |
| SD-WAN Cloud Direct-Connect | Captures enterprise MPLS replacement demand from Milan manufacturing procurement teams. |
Study Parameters
Document review covered AGCOM regulatory filings, European Electronic Communications Code implementation texts, and operator wholesale reference offers, complemented by interviews with network infrastructure vendors, fiber deployment contractors, and enterprise procurement managers at Turin automotive suppliers. Secondary validation drew from spectrum auction records, PNRR fund allocation disclosures, and customs data on optical fiber imports. Bottom-up service revenue modeling and top-down infrastructure investment triangulation anchored market sizing.
Cross-reference between historical capex patterns and panel input from CTOs at integrated operators and wholesale-only challengers shaped projection parameters. Segmentation dimensions modeled include service type, end-user scale, technology platform, and regional infrastructure maturity. CAGRs were derived from deployment run-rate analysis and subscriber migration pattern extrapolation. Key inputs comprised fiber technician pipeline constraints and 3.5 GHz spectrum availability assumptions.
Inputs from AGCOM enforcement records and operator financial disclosures were available through the study window; gaps in real-time wholesale pricing negotiations and unreported private 5G contract terms introduce uncertainty bands around enterprise revenue forecasts. Deviation in Open Fiber deployment timelines or PNRR fund disbursement velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Telecommunication Service Market
Telecommunications
Voip Phone Market
Telecommunications
Romania Telecom Market
Telecommunications
Hungary ICT Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Global LTE Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Belgium ICT Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Smart Feature Phone Market