
 Thailand Flexible Packaging Market | 2026-2036
Thailand Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Flexible Packaging Market Analytics
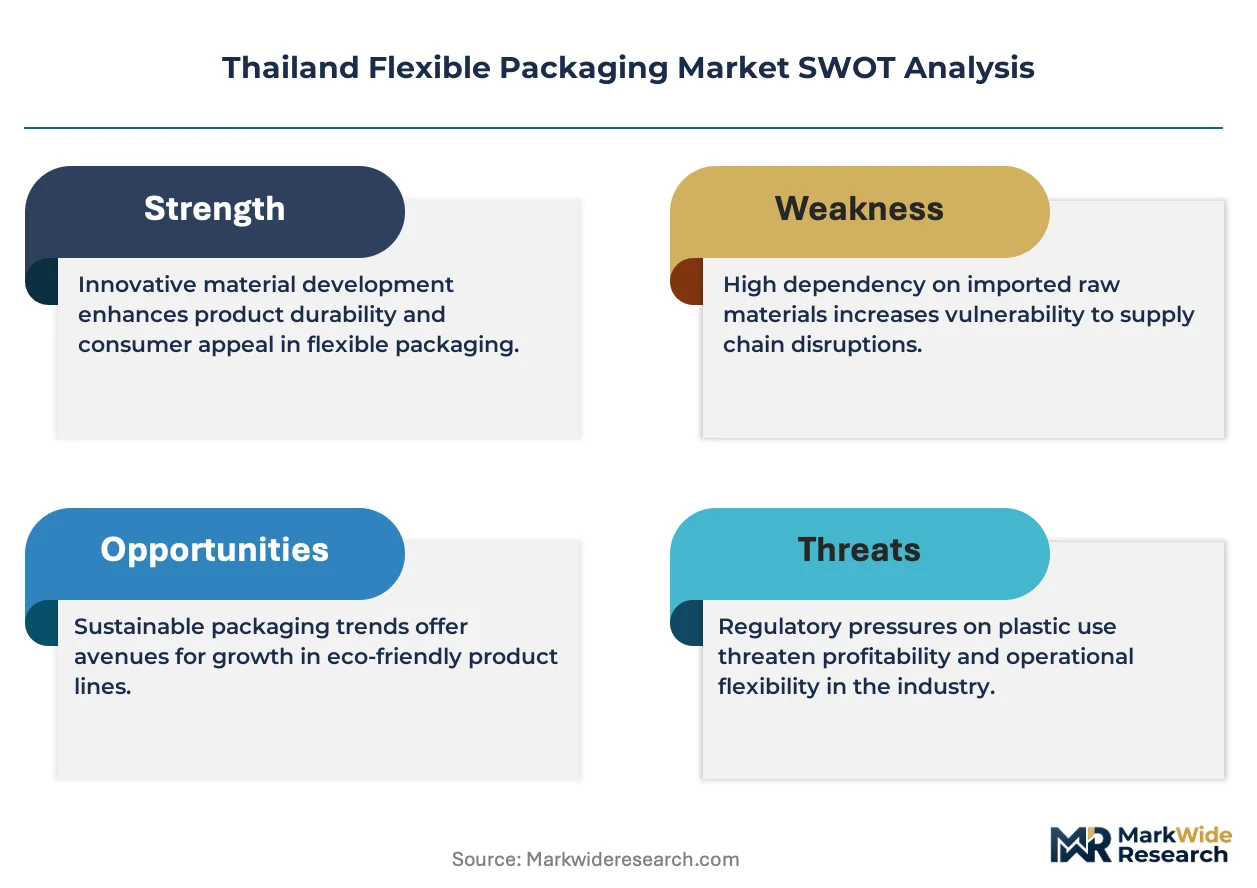
Polymer compounding expertise is reorganizing the competitive landscape as converters seek staff capable of running multilayer coextrusion lines. Siam Packaging leverages its captive resin sourcing to control cost volatility across film grades. Huhtamaki anchors its position through advanced barrier coating technologies for shelf-sensitive applications. SCG Packaging dominates the domestic supply of BOPP substrates, extending its reach into value-added pouch converting.
Thailand flexible packaging comprises laminated or monolayer films, pouches, and wrappers engineered from polyethylene, polypropylene, BOPP, or aluminum foil substrates, typically manufactured via blown film extrusion, cast film, or rotogravure printing processes to deliver moisture, oxygen, and light barrier protection for consumer and industrial goods. Stand-up pouches command premium positioning in the product type mix as brand owners shift from rigid containers to lightweight, shelf-ready formats. Polyethylene and polypropylene together anchor the material structure, though aluminum foil laminates sustain higher margin pools in pharmaceutical and retort food segments where barrier performance commands price premiums.
Thailand's Ministry of Industry enforces plastic waste management protocols aligned with national sustainability targets, while the Thai Industrial Standards Institute (TISI) certifies food-contact material safety under local GB-equivalent frameworks. These regulatory layers compel converters to reformulate toward recyclable mono-material structures and validate compliance through accredited testing. Stakeholders must monitor how forthcoming extended producer responsibility rules reshape capital allocation between barrier innovation and recycling-compatible design.
Market Dynamics
Thailand's Ministry of Industry roadmap toward sustainable packaging targets is forcing converters to reengineer multilayer structures into recyclable mono-material formats, compressing legacy barrier film margins while opening premium positions for certified sustainable alternatives.
Growth Catalysts
- Ready-to-eat food expansion:Snack and convenience food manufacturers are scaling pouch procurement as retail shelf space shifts toward lightweight, shelf-ready formats.
- TISI food-contact certification:Mandatory safety validation under Thai Industrial Standards Institute protocols is elevating compliant converters above informal competitors.
- Greater Bangkok corridor concentration:Petrochemical feedstock proximity and converting cluster density reduce logistics costs for film-grade procurement.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to regional refinery output compress converter margins on BOPP substrate contracts.
- Aluminum foil supply concentration:Limited domestic smelting capacity forces reliance on imported foil laminates for pharmaceutical barrier applications.
- Extended producer responsibility uncertainty:Pending waste management fee structures under Ministry of Industry protocols delay capital commitment to new extrusion lines.
Strategic Opportunities
- Eastern Economic Corridor expansion:Industrial zone incentives in Rayong and Chonburi provinces attract coextrusion capacity beyond Bangkok saturation.
- Retort pouch pharmaceutical applications:Barrier performance requirements in tropical climate drug distribution create margin pools above commodity food packaging.
- Mono-material recyclable structures:TISI-aligned redesign for polyethylene-only pouches positions converters ahead of mandatory recyclability deadlines.
Industry Challenges
- Multilayer coextrusion technician scarcity:Polymer compounding expertise capable of running seven-layer barrier lines commands wage premiums that inflate operating costs.
- Recyclability certification timelines:Third-party validation of mono-material claims under evolving Ministry of Industry standards extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Flexible Packaging Market |
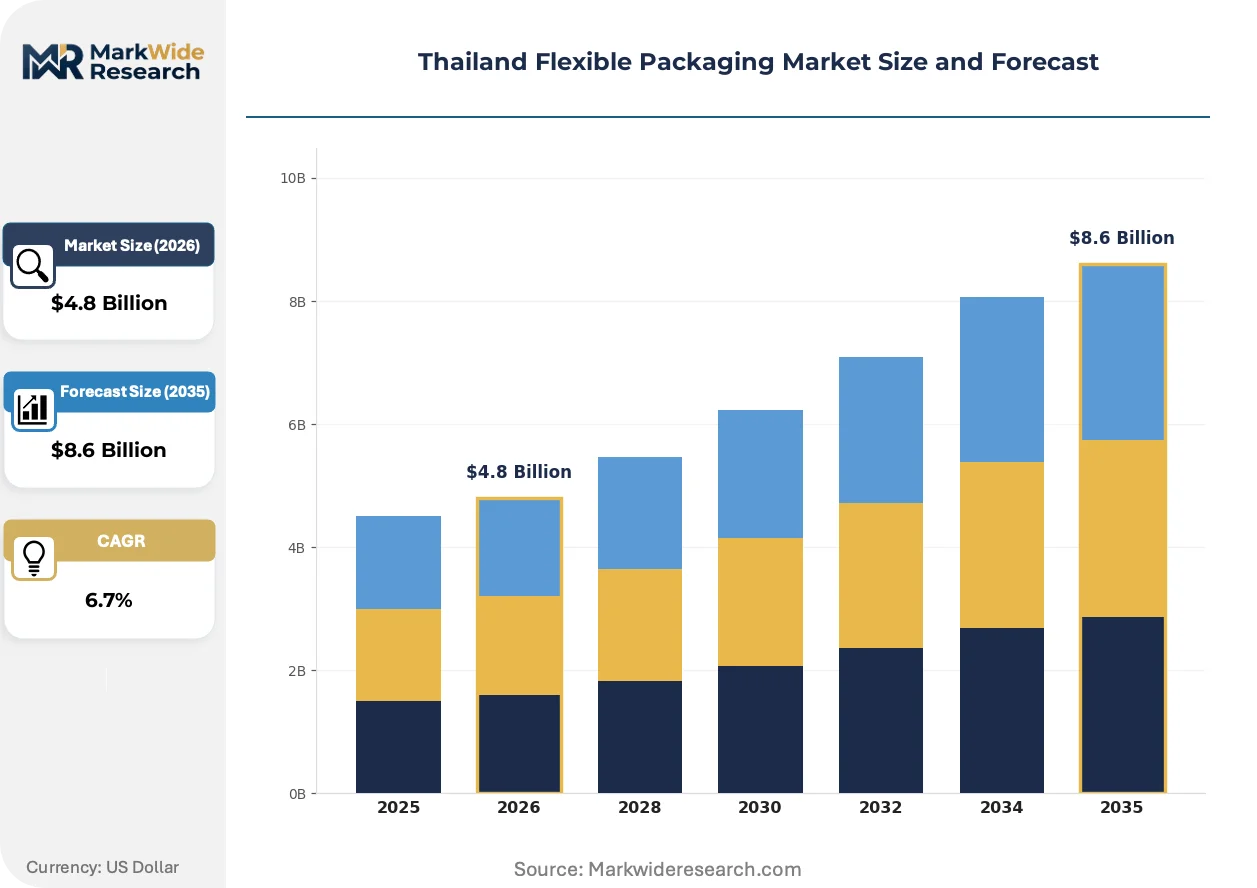
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Bags, Wrappers, Film Material: Polyethylene, Polypropylene, BOPP, Aluminum Foil End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Retailers |
| Companies Covered | Siam Packaging, Foil Packaging Thailand, PrePack Thailand Co. Ltd, Amcor, South East Packaging Industries, Huhtamaki, Thai FlexPack, SCG Packaging, Avery Dennison, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Flexible Packaging Market Evolving Landscape
Active barrier coating technologies and digital printing integration are compressing traditional rotogravure dominance while enabling shorter run lengths for regional brand owners.
Water-based barrier coatings applied via slot-die or Meyer rod processes are displacing solvent-based laminations and aluminum foil composites in shelf-stable food segments. Mid-tier snack manufacturers are adopting these coatings at pilot scale ahead of TISI volatile organic compound restrictions. The shift is displacing legacy solvent recovery infrastructure investments and redirecting capex toward coating line retrofits.
Thailand's Ministry of Industry plastic waste management protocols are tightening documentary requirements for recycled content claims and end-of-life recyclability. Converters must now submit third-party testing to TISI-accredited laboratories before marketing mono-material structures. Food-contact pouch segments face the steepest compliance burden as brand owners demand pre-certified substrate supply.
Brand owners are consolidating flexible packaging procurement under direct converter relationships, bypassing traditional trading house intermediaries that previously managed import logistics. This disintermediation concentrates volume with domestic extruders capable of in-house printing and pouch forming. The pattern is most visible in Greater Bangkok, where multinational food manufacturers have established regional sourcing hubs with mandate for local supply chain traceability.
Thailand Flexible Packaging Market Segmentation
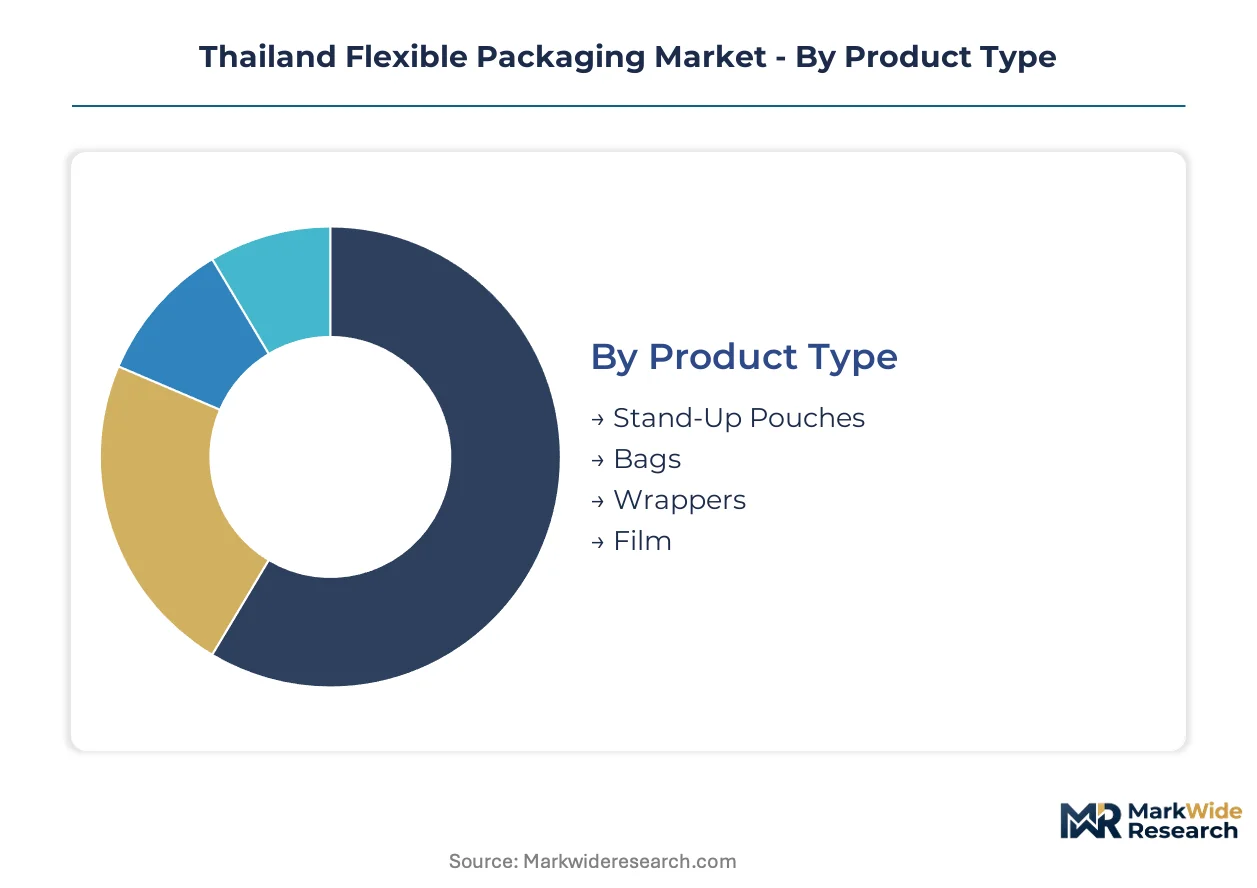
Segmentation in Thailand's flexible packaging market reveals how converter capabilities and regulatory pressures fragment procurement decisions. Brand owners select formats and materials based on barrier requirements, sustainability mandates, and channel-specific shelf presentation needs.
Product Type:
Margin pools concentrate in formed pouch structures where converting complexity creates pricing power against commodity film grades.
- Stand-Up Pouches:Multilayer laminated structures with bottom gussets enable vertical shelf display and resealable convenience. Demand concentrates in Greater Bangkok snack manufacturing corridors where brand owners replace rigid containers for premium positioning.
- Bags:Side-seal and bottom-seal configurations dominate high-volume commodity applications. TISI food-contact certification requirements elevate compliant domestic converters above informal imports in rice and frozen food segments.
- Wrappers:Single-serve formats for confectionery and instant noodles require precise barrier tuning against tropical humidity.
- Film:Rollstock supply to downstream converters faces margin compression from integrated extruder-printing operations.
The dominant share belongs to Bags, while Stand-Up Pouches is closing the gap fastest.
Material:
Feedstock proximity to Map Ta Phut petrochemical complexes shapes cost structures across polymer grades.
- Polyethylene:LDPE and LLDPE films anchor mono-material recyclable designs favored by Ministry of Industry sustainability protocols. Converters in Rayong province leverage direct resin pipeline access for cost-competitive blown film output.
- Polypropylene:Cast and oriented films serve retort and high-temperature applications where dimensional stability matters. Price volatility tied to regional refinery output compresses margins on long-term supply contracts.
- BOPP:Biaxially oriented substrates from SCG Packaging dominate domestic transparency and stiffness requirements.
- Aluminum Foil:Imported laminate supply concentrates pharmaceutical barrier applications where oxygen and light exclusion commands premium positioning.
Polyethylene holds the volume lead, though BOPP maintains the tightest supply control.
End User:
Application-specific barrier requirements create tiered margin structures across customer verticals.
- Food & Beverage:Snack, ready-to-eat, and beverage applications drive pouch procurement volume. Greater Bangkok retail corridor concentration rewards converters with integrated printing and forming capabilities.
- Pharmaceuticals:Blister packs and sachets for tropical climate drug distribution demand validated barrier performance. TISI certification and aluminum foil laminates sustain higher margin pools than commodity food segments.
- Personal Care:Flexible tubes and sachets for shampoo and cosmetics favor high-impact gravure printing.
- Household Products:Detergent and cleaner packaging prioritizes chemical resistance and child-resistant features.
Food & Beverage commands the dominant procurement volume, while Pharmaceuticals is expanding most quickly.
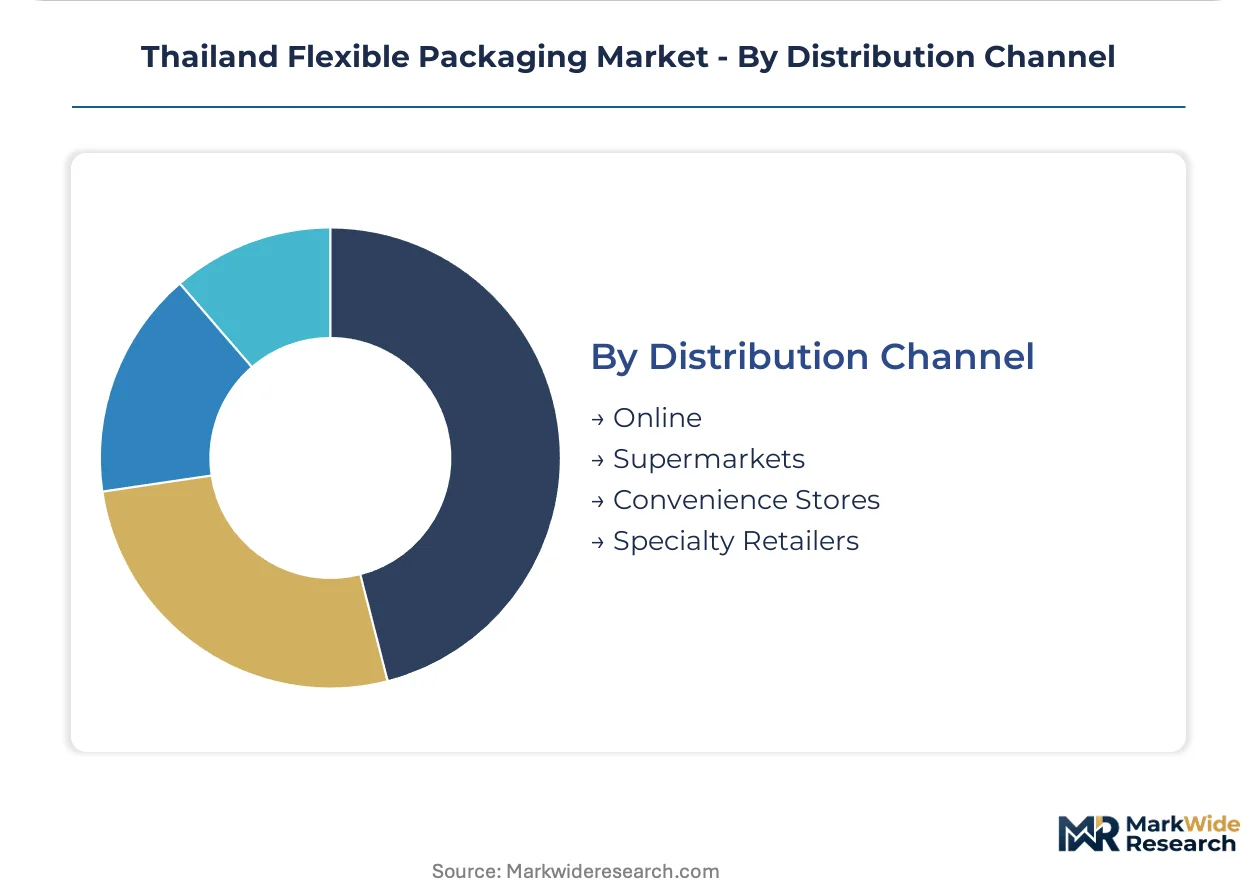
Distribution Channel:
Channel format requirements dictate size specifications and print run economics for converter capacity planning.
- Supermarkets:Large-format retail chains demand shelf-ready pouch presentations with standardized case counts. Volume concentration with domestic extruders capable of direct supply relationships is displacing traditional trading house intermediaries.
- Convenience Stores:7-Eleven and FamilyMart networks across Thailand drive single-serve and impulse-oriented packaging formats. Short replenishment cycles favor converters with digital printing flexibility for regional brand variants.
- Online:E-commerce fulfillment requires durable transit packaging with reduced material weight for shipping cost optimization.
- Specialty Retailers:Premium and organic food channels specify certified sustainable substrates with traceable supply chains.
Supermarkets retain the largest channel share, though Convenience Stores is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Ministry of Industry anchors regulatory direction across Southeast Asian flexible packaging corridors through plastic waste management protocols and TISI certification frameworks that neighboring jurisdictions increasingly reference.
Greater Bangkok Metropolitan Region
Snack and ready-to-eat food manufacturers concentrate pouch procurement in this corridor where petrochemical feedstock pipelines from Map Ta Phut terminate. TISI food-contact certification requirements elevate compliant domestic converters above informal imports. Integrated extruder-printing operations in Samut Prakan and Pathum Thani provinces displace traditional trading house intermediaries through direct supply relationships.
Eastern Economic Corridor
Rayong and Chonburi provinces attract coextrusion capacity expansion beyond Bangkok saturation through industrial zone incentives and direct resin pipeline access. The country's national industrial development authority prioritizes sustainable packaging investments in this zone. Converters here leverage polyethylene blown film output for mono-material recyclable designs aligned with forthcoming extended producer responsibility rules.
Central Plains Agricultural Belt
Rice and frozen food processors drive commodity bag demand across Nakhon Pathom and Suphan Buri provinces where logistics costs favor domestic film supply. TISI certification mandates create compliance barriers for informal competitors. Regional converting clusters lack integrated printing capabilities, forcing reliance on Greater Bangkok suppliers for finished pouch formats.
Northern Industrial Zone
Chiang Mai and Lamphun provinces host specialty food exporters requiring barrier packaging for tropical climate distribution. The national sustainable packaging roadmap pressures converters here toward recyclable mono-material structures. Limited local extrusion capacity forces dependence on Bangkok-based substrate suppliers with extended delivery lead times.
Southern Seaboard
Surat Thani and Songkhla provinces serve seafood processing and rubber glove manufacturing with film and wrapper applications. Port proximity enables aluminum foil laminate imports for pharmaceutical barrier requirements where domestic smelting capacity is absent. Converters here compete primarily on logistics efficiency rather than technical barrier innovation.
Thailand Flexible Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Thailand's flexible packaging market, with captive resin access and in-house converting capabilities separating premium positioning from commodity supply. SCG Packaging leverages backward integration into BOPP substrate production to control cost volatility across film grades. Three archetypes dominate: petrochemical-integrated conglomerates with captive resin supply, multinational converters with advanced barrier coating technologies, and regional specialists focused on specific end-use verticals. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants position for extended producer responsibility implementation.
Among Thailand-based integrated players, Siam Packaging exemplifies the petrochemical-linked archetype through its captive resin sourcing advantages. SCG Packaging anchors the domestic substrate tier with Biaxially Oriented Polypropylene supply control. Multinational specialists including Huhtamaki occupy positions defined by advanced barrier technologies for shelf-sensitive applications, representing the technology-differentiated archetype against locally integrated competitors.
| Leading Market Players |
|---|
| Siam Packaging |
| Foil Packaging Thailand |
| PrePack Thailand Co. Ltd |
| Amcor |
| South East Packaging Industries |
| Huhtamaki |
| Thai FlexPack |
| SCG Packaging |
| Avery Dennison |
| Others |
Value Network & Pricing Analysis
Map Ta Phut petrochemical scale economies anchor Thailand's flexible packaging cost floors, concentrating blown film extrusion capacity within pipeline distance of polyethylene and polypropylene resin supply. This geographic clustering compresses logistics premiums for domestic converters while creating entry barriers for distant competitors lacking feedstock proximity.
Pricing Analysis
Greater Bangkok converters command 15-20% premiums over provincial suppliers due to integrated printing and pouch-forming capabilities that eliminate downstream processing costs. Three-tier pricing structure across premium, standard, and economy levels separates TISI-certified food-contact suppliers from informal competitors and commodity film traders. Cost compression in standard-grade BOPP substrates is intensifying because SCG Packaging's captive resin supply enables aggressive contract positioning. Multinational food manufacturers exhibit lowest price sensitivity given traceability mandates, while regional rice processors remain most responsive to per-kilogram film costs.
Supply Chain Analysis
Raw material inventory cycles extend 45-60 days for aluminum foil laminates sourced from China and South Korea, versus 7-10 days for domestic polyethylene resin. Thailand's flexible packaging supply chain draws from Map Ta Phut petrochemical complexes for polymer feedstock, Chinese and South Korean smelters for pharmaceutical-grade foil, and Japanese equipment suppliers for coextrusion line components. Single-source vulnerability concentrates in seven-layer barrier film technician availability, where regional competition for skilled operators disrupts production scheduling. Distribution runs through direct converter relationships with multinational brand owners, displacing traditional trading house intermediaries that previously managed import logistics and inventory holding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's flexible packaging sector is restructuring under Ministry of Industry sustainability mandates that will obsolete multilayer barrier technologies within one regulatory cycle. Extended producer responsibility implementation creates asymmetric risk for converters lacking mono-material recyclable design capabilities.
For Market Incumbents: Fortify captive resin supply positions through pipeline capacity expansion in Rayong province, securing cost-advantaged polyethylene access ahead of Eastern Economic Corridor saturation. Accelerate TISI certification for mono-material pouch structures to defend against emerging competitors with recyclable-native architectures. Barrier coating R&D investment represents the critical lever for maintaining pharmaceutical margin pools as aluminum foil laminates face recyclability scrutiny. For New Entrants and Emerging Players: Digital printing service gaps in convenience store channel replenishment cycles expose incumbent rigidity in short-run regional brand variants. Target Chonburi province coextrusion capacity for pilot-scale water-based barrier coating adoption ahead of TISI volatile organic compound restrictions. Go-to-market positioning through direct 7-Eleven and FamilyMart supply relationships bypasses entrenched Greater Bangkok converter networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with installed mono-material recyclable capacity and validated TISI laboratory relationships over legacy multilayer specialists facing asset stranding. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than scale economics alone. Acquisition screening should prioritize Eastern Economic Corridor footprint and coating line retrofit flexibility. The signal to watch is Ministry of Industry extended producer responsibility fee structure announcements, which will immediately revalue recyclable-design asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Recyclable Capacity Expansion | Positions converters ahead of mandatory Ministry of Industry recyclability deadlines and EPR fee structures. |
| Water-Based Barrier Coating Adoption | Enables compliance with forthcoming TISI volatile organic compound restrictions while displacing solvent-based laminations. |
| Direct Brand Owner Relationship Development | Bypasses trading house intermediaries and captures volume concentration from multinational food manufacturer procurement consolidation. |
| Eastern Economic Corridor Footprint Establishment | Leverages Rayong industrial zone incentives and direct Map Ta Phut resin pipeline access for cost-competitive output. |
| Polymer Compounding Technical Workforce Investment | Addresses seven-layer coextrusion technician scarcity that commands wage premiums and constrains capacity utilization. |
Research Methodology
Initial hypotheses were tested against primary input from extrusion plant managers, brand owner packaging procurement directors, TISI certification laboratory technical leads, and petrochemical resin supply planners, then refined through secondary validation. Primary fieldwork combined structured interviews across these stakeholder roles with facility observation in Greater Bangkok and Eastern Economic Corridor converting operations. Secondary sources included Thai Industrial Standards Institute regulatory filings, Ministry of Industry plastic waste management protocol drafts, customs trade data on aluminum foil laminate imports, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity and utilization estimates were triangulated against top-down demand projections from end-use sector consumption patterns.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in segment-level outputs. The analytical framework models product type, material substrate, end-use vertical, and distribution channel dimensions, with additional granularity on TISI certification status and mono-material recyclability compliance. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points and capacity expansion announcements. Forecast inputs incorporated Map Ta Phut resin supply pipeline utilization rates, convenience store channel growth trajectories, and pharmaceutical barrier packaging technical specification evolution.
Underlying assumptions cover sustained Ministry of Industry regulatory enforcement, continued Map Ta Phut petrochemical feedstock availability, and stable Thai baht exchange rates against regional trade currencies, with deviation risk concentrated in extended producer responsibility fee structure timing and aluminum foil import tariff adjustments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market