
 Europe, Middle East and Africa (EMEA) Flexible Packaging Market | 2026-2036
Europe, Middle East and Africa (EMEA) Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe, Middle East and Africa (EMEA) Flexible Packaging Market Insights
European converter investment in extrusion and printing capacity is repositioning supply toward high-barrier mono-material films. Amcor plc leverages its integrated film manufacturing network across Western Europe to serve multinational food brands. Mondi Group anchors its competitive position through kraft paper-based flexible solutions that target plastic reduction mandates. Sealed Air Corporation differentiates via automated packaging systems bundled with engineered film portfolios.
Flexible packaging encompasses pliable substrates—typically polyethylene, polypropylene, paper, or aluminum laminates below 0.25 mm thickness—that conform to product shape while providing moisture, oxygen, and light barriers through coextrusion, lamination, or metallization processes. Its primary purpose is to reduce material usage, extend shelf life, and enable efficient distribution across food, beverage, pharmaceutical, and personal care supply chains. Stand-up pouches command substantial value share among product types due to retail shelf differentiation and consumer convenience. Polyethylene dominates material demand for cost-sensitive applications, though aluminum laminates retain critical roles in pharmaceutical blister and retort packaging where barrier performance is non-negotiable.
The EU Packaging and Packaging Waste Regulation (PPWR) and REACH chemical compliance frameworks are reshaping material specifications and recyclability requirements across EMEA, forcing converters to validate mono-material designs and recycled content claims. EFSA safety assessments for food-contact recycled plastics add a secondary compliance layer that filters market access for non-European suppliers. Stakeholders must monitor how national extended producer responsibility schemes and deposit-return system expansions alter cost allocation between brands, converters, and waste management operators.
Market Dynamics
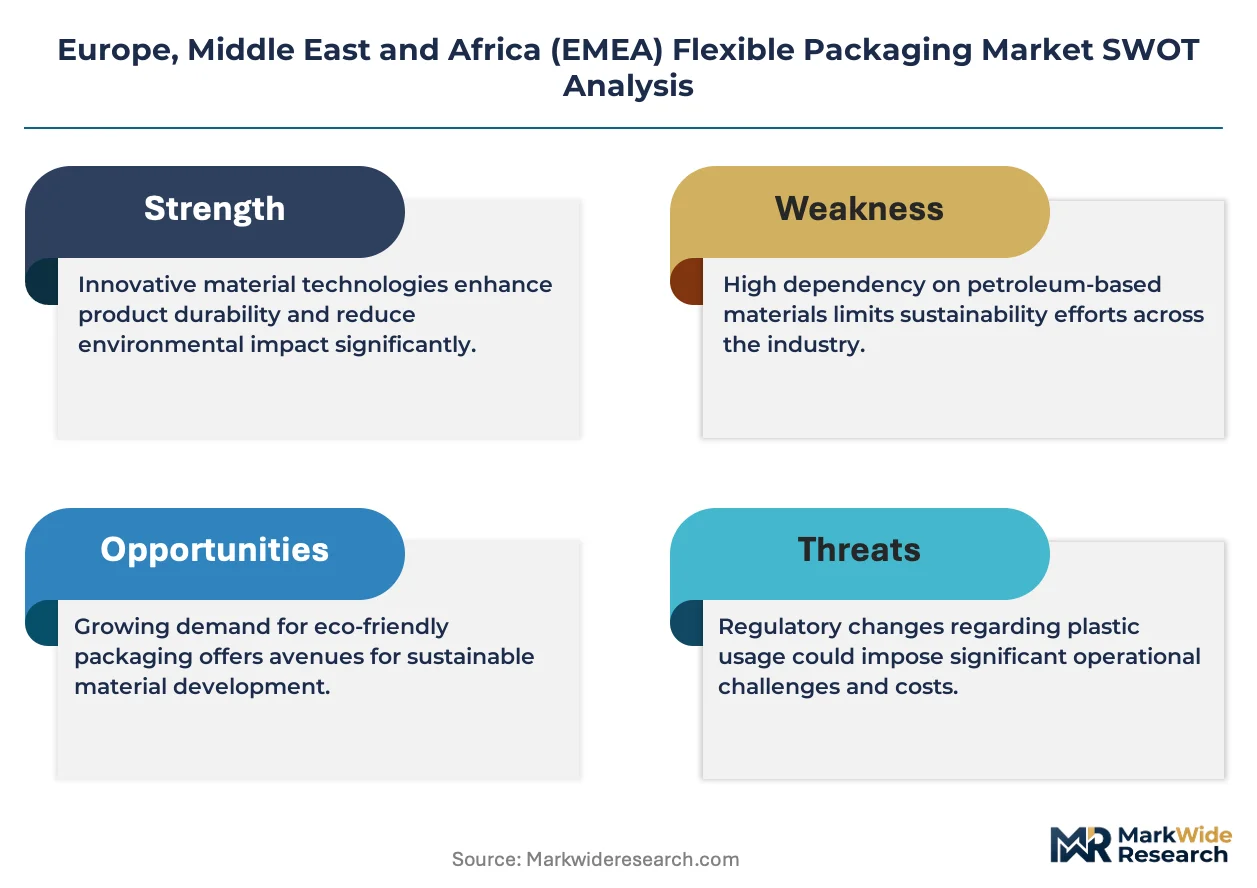
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing converters to redesign film structures around mono-material recyclability, compressing legacy multi-layer laminate architectures and redistributing value toward extrusion specialists with validated recycling streams.
Growth Catalysts
- PPWR Compliance Deadlines:The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that accelerate converter investment in polyethylene and polypropylene mono-material platforms. Food brands are reformulating packaging specifications to meet extended producer responsibility requirements ahead of enforcement phases.
- Stand-up Pouch Adoption:Ready-to-eat meal producers across Germany, France, and the United Kingdom are converting from rigid trays to high-barrier pouches for retail differentiation and logistics efficiency. This format shift expands addressable substrate volume for flexible converters.
- Post-Consumer Recycled Content Mandates:The EU Green Deal's circular economy targets are pulling rPET and rPP supply into food-contact applications. EFSA safety clearance pathways for recycled plastics are unlocking qualified material streams for compliant packaging.
Market Restraints
- Aluminum Price Volatility:Pharmaceutical and retort packaging segments face margin pressure from aluminum laminate input cost swings. Barrier-critical applications cannot substitute metallized films without shelf-life degradation.
- Recycling Infrastructure Gaps:Southern and Eastern European markets lack the collection and sorting capacity to absorb mono-material output at scale. This geographic asymmetry limits the addressable market for recyclable film designs.
- REACH Chemical Compliance:The ECHA framework restricts certain adhesives and coatings historically used in multi-layer constructions. Reformulation timelines extend product development cycles for legacy laminate portfolios.
Strategic Opportunities
- Middle East Food Export Growth:Saudi Arabia and UAE food processors are importing European flexible packaging for halal-certified ready meals targeting European Muslim populations. Local converter partnerships could capture this trade flow.
- Paper-Plastic Hybrid Films:Mondi Group's kraft paper barrier platforms demonstrate viable plastic reduction without sacrificing heat-seal performance. Premium snack brands are specifying these structures for plastic-light positioning.
- Digital Printing Convergence:HP Indigo and EFI systems are integrating with mono-material extrusion lines to enable short-run customization. This technology pairing supports brand versioning and regional regulatory label adaptation.
Industry Challenges
- Mono-material Barrier Engineering:Matching oxygen and moisture protection of aluminum laminates with single-substrate films requires nanocomposite or metallized layer innovation. R&D cycles for EFSA-compliant food-contact barriers extend 18-24 months.
- Recycled Content Verification:Mass-balance accounting for post-consumer recycled polymers demands supply chain documentation that many converters lack. Third-party certification costs compress margins on commodity-grade film contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe, Middle East and Africa (EMEA) Flexible Packaging Market |
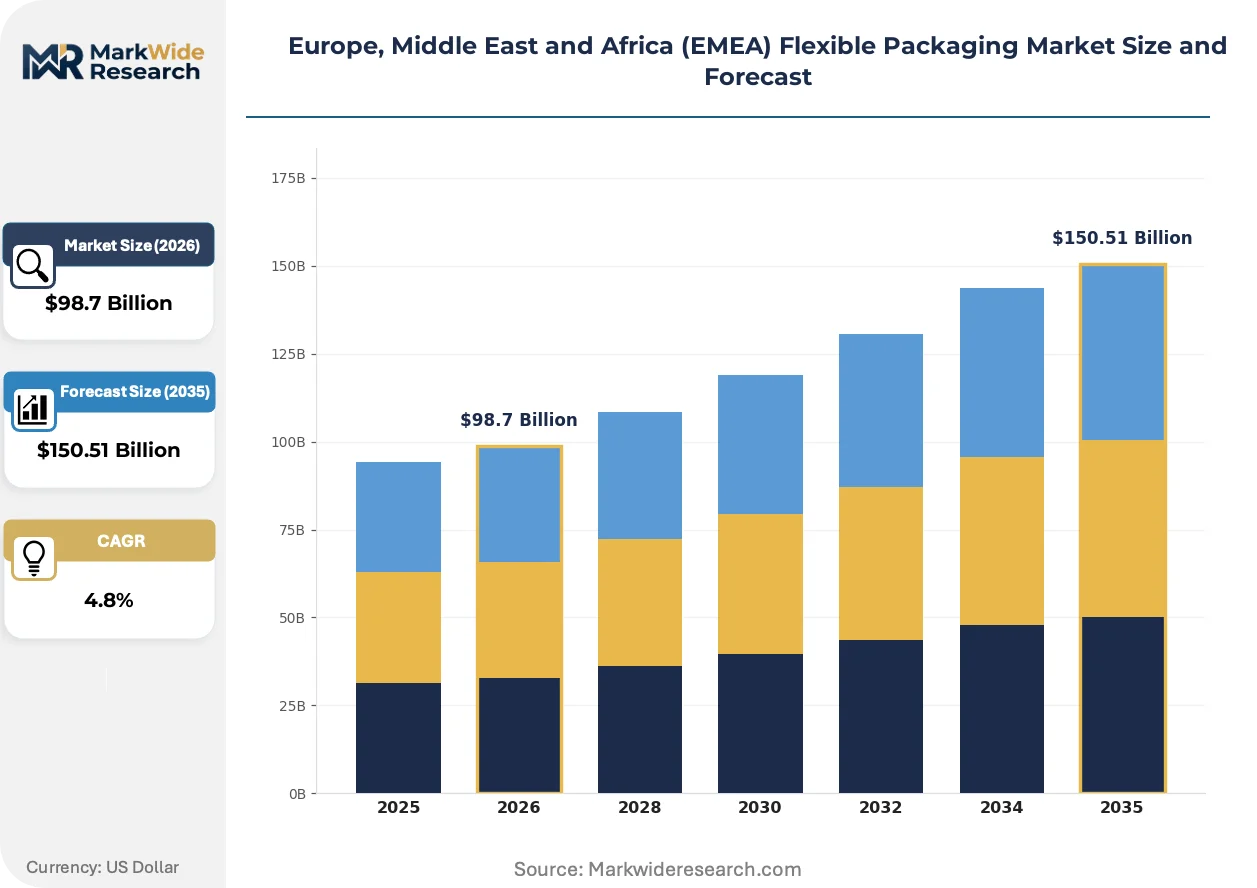
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $150.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Films, Bags, Vacuum Pack Material: Polyethylene, Polypropylene, Paper, Aluminum End User: Food, Beverages, Pharmaceuticals, Personal Care Technology: Digital Printing, Flexographic Printing, Gravure Printing, Lamination |
| Companies Covered | Constantia Flexibles, Coveris, Amcor plc, Bischof + Klein, DS Smith Plc, Mondi Group, Sealed Air Corporation, Wipak Oy, Huhtamaki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe, Middle East and Africa (EMEA) Flexible Packaging Market Trends and Innovations
Digital printing integration and mono-material barrier engineering are converging to compress minimum order quantities and enable mass customization, while regulatory frameworks harden material specifications across the value chain.
High-barrier mono-material polyethylene films are overtaking conventional PET/PE/AL laminates in ambient shelf-stable applications. European dairy and sauce brands are adopting these structures for recycling stream compatibility. The shift is compressing demand for aluminum foil laminators without integrated extrusion capacity.
REACH authorization requirements for phthalate plasticizers and certain solvent-based adhesives are eliminating legacy chemistries from food-contact laminates. Converters are migrating to water-based or electron-beam curable alternatives with reformulated bond strengths. Snack and confectionery packaging lines in Germany and France are experiencing the most acute transition costs.
Retailer-led packaging reduction commitments are shortening supplier qualification cycles and unbundling traditional converter-distributor relationships. Discounters and private-label specialists are contracting directly with extrusion houses for specification control. This pattern is most pronounced in the United Kingdom and Netherlands grocery channels.
Europe, Middle East and Africa (EMEA) Flexible Packaging Market Segmentation
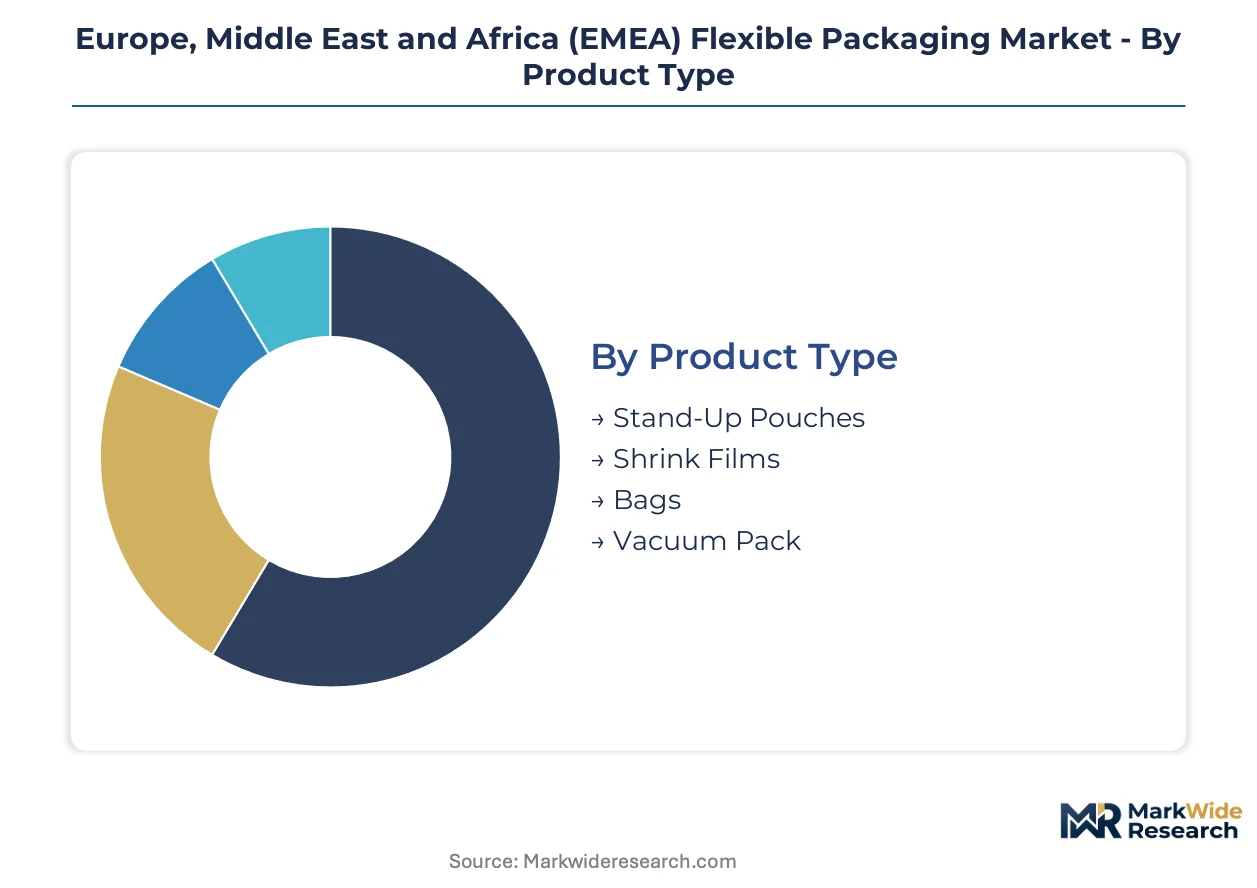
Flexible packaging converters across EMEA are reconfiguring production lines around format-specific barrier requirements and regulatory recyclability mandates. Segment boundaries are hardening as food brands consolidate specifications toward mono-material platforms and digital-enabled short runs.
Product Type:
Format selection tracks directly with shelf-life extension needs and retail display economics, driving replacement of rigid containers with pliable alternatives.
- Stand-Up Pouches:Multi-layer polyethylene or polypropylene structures with resealable zipper closures and spout fitments. German and French ready-to-eat meal producers are specifying high-barrier versions for ambient distribution, though EFSA compliance timelines for recycled content integration extend qualification cycles.
- Shrink Films:Biaxially oriented polyolefin or PVC formulations that conform tightly to product contours through heat application. Beverage multipack bundling across the United Kingdom and Netherlands is shifting toward perforated tear-strip designs for consumer convenience and reduced plastic weight.
- Bags:Pillow pouches and gusseted formats for dry goods and frozen applications.
- Vacuum Pack:Multi-layer coextrusions with oxygen barrier layers for meat, cheese, and seafood preservation.
Volume placements concentrate in shrink films for beverage logistics; the faster expansion belongs to stand-up pouches.
Material:
Substrate economics divide between commodity polyolefins and specialty barrier layers, with regulatory pressure compressing multi-material laminates.
- Polyethylene:Linear low-density and metallocene grades dominate cost-sensitive food wrapping and carrier bags. Saudi Arabian and UAE converters are expanding blown film capacity to serve halal food export packaging, though European recyclability mandates favor single-polymer PE structures over blended formulations.
- Polypropylene:Cast and oriented films for snack, confectionery, and microwaveable applications with higher temperature tolerance. French dairy brands are adopting transparent PP lidstock for yogurt multipacks to replace PS trays under extended producer responsibility schemes.
- Paper:Kraft and glassine substrates with polymer barrier coatings for dry goods and premium positioning.
- Aluminum:Foil laminates and metallized films for pharmaceutical blister packs and retort pouches where oxygen and light exclusion is non-negotiable.
Polyethylene captures the highest tonnage placements; polypropylene is climbing the fastest as snack brands convert from rigid to flexible formats.
End User:
Demand concentration varies sharply by barrier specification and regulatory scrutiny, with food-contact applications driving material innovation cycles.
- Food:The largest addressable substrate volume spanning ambient, chilled, and frozen supply chains. United Kingdom grocery discounters are contracting directly with extrusion houses for private-label pouch specifications, compressing traditional distributor margins.
- Beverages:Stand-up spouted pouches and aseptic bag-in-box for wine, juice, and dairy alternatives. German beverage brands are piloting mono-material PE pouches for recycling stream compatibility, though carbonation barrier performance limits adoption in sparkling applications.
- Pharmaceuticals:Cold-form foil and high-barrier laminates for blister packs and sachets with child-resistance and tamper-evidence requirements.
- Personal Care:Sachets, pouches, and flow-wrap for wipes, cosmetics, and household products with fragrance and moisture barriers.
Food commands the dominant volume placement; pharmaceuticals maintains the steepest specification premium despite smaller tonnage.
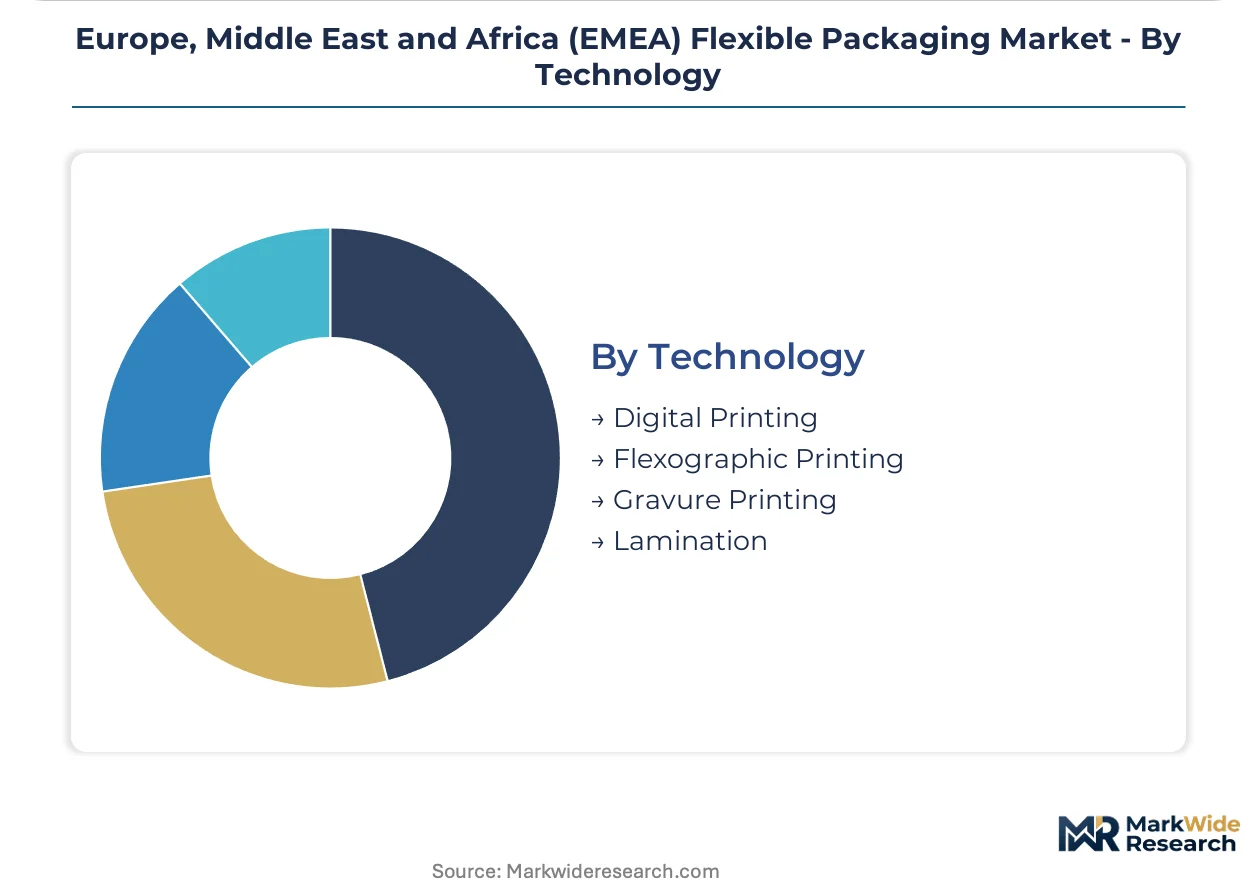
Technology:
Printing and converting process selection determines minimum order economics and regulatory label adaptability across fragmented brand portfolios.
- Digital Printing:Electrophotographic and inkjet systems enabling variable data and short-run versioning without plate costs. Netherlands-based snack brands are adopting HP Indigo workflows for regional flavor launches with country-specific ingredient declarations, compressing time-to-shelf from weeks to days.
- Flexographic Printing:Central impression cylinder and inline stack presses for medium-to-long runs with water-based or UV-curable inks. Eastern European converters are upgrading to eight-color servo-driven presses for expanded gamut reproduction on mono-material films.
- Gravure Printing:Rotogravure cylinders for ultra-long runs with consistent ink laydown and metallic effects.
- Lamination:Solventless, water-based, and extrusion lamination for multi-layer barrier construction.
Flexographic placements dominate current volume; digital printing is expanding most quickly as brand portfolios fragment across regulatory jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene feedstock from the Arabian Gulf anchors flexible packaging supply chains serving European food brands and Middle East export processors. Regional converters calibrate production between EU recyclability mandates and halal certification requirements for cross-border trade.
Germany
Ready-to-eat meal producers in Bavaria and North Rhine-Westphalia are specifying high-barrier mono-material pouches for retail distribution. Extended producer responsibility schemes under the Verpackungsgesetz (Packaging Act) enforce strict recyclability quotas that filter supplier qualification. The Rhine-Main industrial corridor hosts extrusion specialists validating EFSA-compliant recycled content streams for dairy and sauce applications.
France
Dairy brands in the Île-de-France and Auvergne-Rhône-Alpes regions are converting yogurt multipacks from polystyrene trays to transparent polypropylene lidstock. REACH restrictions on phthalate plasticizers are eliminating legacy adhesive chemistries from snack packaging lines. Lyon-based converters are piloting water-based lamination systems for confectionery barrier films.
United Kingdom
Grocery discounters in London and the Midlands are contracting directly with extrusion houses for private-label pouch specifications. The Plastic Packaging Tax mandates minimum recycled content thresholds that compress commodity film margins. Manchester and Liverpool logistics clusters are driving demand for perforated shrink films in beverage multipack bundling.
Saudi Arabia
Food processors in Riyadh and the Eastern Province are importing European flexible packaging for halal-certified ready meals targeting European Muslim populations. The Saudi Food and Drug Authority aligns import standards with EFSA safety protocols for food-contact materials. Jeddah industrial zones are attracting converter joint ventures to localize production for Gulf Cooperation Council export markets.
United Arab Emirates
Dubai and Abu Dhabi logistics hubs are consolidating flexible packaging distribution for Middle East and Africa re-export trade. The Emirates Authority for Standardization and Metrology enforces labeling and material safety requirements for imported films. Sharjah manufacturing zones are expanding blown film capacity to serve regional snack and confectionery brands.
Europe, Middle East and Africa (EMEA) Flexible Packaging Market Competitive Landscape
Global majors compete with regional champions across extrusion capacity and regulatory compliance capabilities. The vendor base organizes into three tiers: integrated film manufacturers with captive resin supply, specialized converters focused on mono-material platforms, and diversified packaging groups bundling equipment with substrate portfolios. Strategic moves center on backward integration into resin compounding and partnerships with recycling operators to secure validated post-consumer feedstock streams.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify divergent responses to plastic reduction mandates. Amcor leverages its Western European film manufacturing network to serve multinational food brands with scale-efficient supply. Mondi anchors its positioning through kraft paper-based flexible solutions that target regulatory pressure on plastic usage. Sealed Air Corporation occupies a distinct position bundling automated packaging systems with engineered film portfolios, addressing labor cost pressures in European processing facilities.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Coveris |
| Amcor plc |
| Bischof + Klein |
| DS Smith Plc |
| Mondi Group |
| Sealed Air Corporation |
| Wipak Oy |
| Huhtamaki Oyj |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EFSA-compliant recycled content films and commodity virgin polyolefins manifests in both pricing premiums and supply chain segmentation, with validated mono-material streams commanding dedicated extrusion capacity while standard grades flow through undifferentiated distributor channels.
Pricing Analysis
Extended producer responsibility bundling separates converter pricing into service-inclusive and unbundled tiers, with German and French brands paying premiums for mass-balance certification documentation. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA clearance status, volume commitment scale, and geographic delivery density. Cost compression in commodity polyethylene runs through Saudi Arabian blown film imports competing with European recyclability-compliant supply. Private-label grocery buyers exhibit highest price sensitivity; pharmaceutical blister pack specialists show lowest.
Supply Chain Analysis
Direct-to-brand channels handle multinational food manufacturer demand for mono-material specification control, while distributor networks serve fragmented snack and confectionery processors across Southern and Eastern Europe. Raw material supply draws from Saudi Arabian and UAE polyethylene feedstock, German resin compounding, and Italian biaxially oriented polypropylene capacity. Aluminum foil dependency for pharmaceutical barriers creates single-source vulnerability through limited European metallizer concentration. Distribution runs through Rotterdam and Hamburg logistics clusters for Northern European conversion, Jeddah and Dubai hubs for Middle East re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material extrusion capacity scarcity props pricing power for EFSA-validated converters, as qualification timelines stretch 18-24 months and brand reformulation deadlines compress.
For Market Incumbents: Extend backward integration into resin compounding to secure post-consumer recycled polymer streams ahead of PPWR enforcement phases. Anchor positioning through exclusive partnerships with waste management operators controlling collection infrastructure in Germany and France. Defend against emerging Middle Eastern converters by accelerating EFSA food-contact clearance for proprietary barrier formulations. For New Entrants and Emerging Players: Digital print-to-order platforms offer the lowest-capital route to serving Netherlands and United Kingdom snack brands requiring short-run regional label versioning. Target Southern European markets where recycling infrastructure gaps have delayed incumbent mono-material rollout. Penetrate through hybrid paper-plastic film partnerships with Mondi Group's kraft paper barrier technology licensees. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging groups seeking EFSA-cleared extrusion assets. Long-term viability hinges on converters with validated recycling stream access and digital printing integration capabilities. Watch for PPWR enforcement phase announcements as inflection signals for distressed asset availability among legacy multi-layer laminate specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Investment | PPWR recyclability thresholds force polyethylene and polypropylene extrusion line reconfiguration ahead of enforcement. |
| Post-Consumer Recycled Content Integration | EFSA safety clearance pathways unlock qualified rPET and rPP supply for dairy and sauce packaging specifications. |
| Digital Printing Convergence | HP Indigo and EFI system integration with extrusion lines enables Netherlands snack brand short-run regional launches. |
| Backward Integration into Resin Compounding | Captive recycled polymer supply secures mass-balance documentation for German extended producer responsibility compliance. |
| Middle East Joint Venture Formation | Jeddah and Sharjah manufacturing zones localize production for halal-certified ready meal export packaging. |
Research Methodology
Independent corroboration across converter production data, brand procurement specifications, and regulatory filing records underwrites the qualitative findings. Primary interviews with extrusion plant managers, food packaging procurement leads at multinational brands, waste management operators, and EFSA regulatory affairs specialists combined with secondary validation from EU PPWR implementation documents, ECHA REACH authorization databases, and national extended producer responsibility scheme filings. Bottom-up capacity assessments triangulated against top-down demand modeling from food and beverage production statistics.
Comparable-period anchoring used historical mono-material adoption curves and PPWR regulatory phase-in patterns to structure projection assumptions across the analysis window. Segmentation dimensions modeled include product format, material substrate, end-use industry, and technology platform. CAGRs derived from volume trajectory analysis incorporating EFSA clearance timeline assumptions, recycled content mandate enforcement schedules, and stand-up pouch substitution rates for rigid packaging. Industry-specific inputs encompassed aluminum price volatility indices and digital printing equipment installation data.
The model holds under steady PPWR enforcement timelines and stable EFSA clearance processing capacity; deviation in regulatory acceleration or recycled feedstock quality degradation would shift volume and value projections. Forecasts incorporate base-case assumptions regarding collection infrastructure expansion across Southern and Eastern Europe. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Africa Flexible Packaging Market