
 Thermoform Packaging Market | 2026-2036
Thermoform Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoform Packaging Market Intelligence
Healthcare providers is repositioning thermoform packaging procurement toward high-integrity sterile barrier systems. Amcor plc leverages its global film and medical packaging infrastructure to sustain leadership in regulated healthcare applications. Berry Global Inc. anchors North American supply through specialized pharmaceutical and food-grade thermoforming operations. Sealed Air Corporation differentiates via advanced barrier technologies and automated packaging equipment integration.
Thermoform packaging denotes plastic sheet heated to pliability then vacuum- or pressure-formed over molds, typically producing wall thicknesses of 0.005 to 0.060 inches for containment, display, and protection functions. Polyethylene Terephthalate dominates food-contact applications for its clarity and recyclability profile, while Polypropylene gains share in retort and hot-fill pharmaceutical trays due to thermal stability. Blister Packs command the largest product-type volume, though Clamshells capture premium margins in electronics and cosmetic retail display where theft deterrence and visual merchandising converge.
The FDA enforces stringent sterility and traceability standards for medical device thermoform packaging under 21 CFR Part 820 quality system regulations. The EPA advances recycled content mandates and extended producer responsibility frameworks that reshape material sourcing economics for domestic converters. EMA medical device regulations and REACH chemical restrictions in Europe compound compliance complexity for exporters. Stakeholders must monitor evolving state-level packaging EPR legislation and bio-based material certification schemes to preempt supply chain disruption and access premium contract tiers.
Market Dynamics
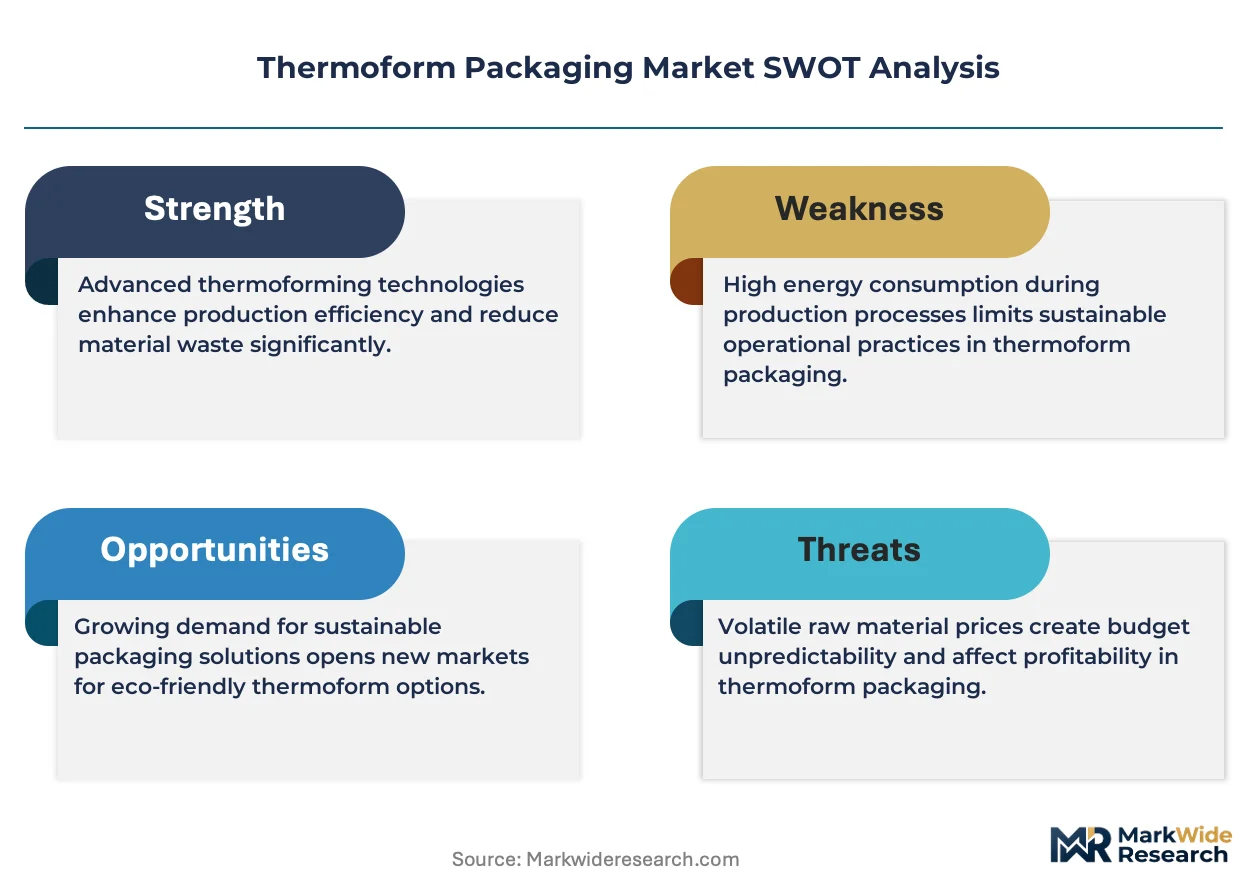
Healthcare sterile barrier requirements are compressing supplier qualification timelines while EU F-Gas Regulation and state-level extended producer responsibility laws simultaneously reshape material economics for converters.
Growth Catalysts
- EMA Medical Device Regulation:Stricter sterile packaging mandates under MDR are forcing device manufacturers to upgrade barrier integrity specifications, expanding qualified supplier rosters for high-integrity thermoform trays.
- Retort-capable Polypropylene:Thermal stability improvements in modified PP resins are displacing metal cans in pharmaceutical and ready-meal segments where hot-fill and autoclave sterilization protocols apply.
- Germany's medical corridor:Concentrated device manufacturing around Tuttlingen and Munich is generating localized demand clusters that reward just-in-time thermoform tray supply capabilities.
Market Restraints
- Recycled PET feedstock volatility:Post-consumer rPET flake supply concentrates among limited European reprocessors, creating input cost instability for food-contact clarity applications.
- Fluorinated gas phase-out:EU F-Gas Regulation restrictions on HFC blowing agents for foam-core thermoforming are forcing capital-intensive process conversions or material substitutions.
- Paper-fiber barrier substitutes:Molded fiber packaging with advanced coatings is capturing share in chilled food and limited-shelf-life pharmaceutical applications where moisture barriers are less critical.
Strategic Opportunities
- India's pharmaceutical export zone:Underpenetrated sterile barrier thermoforming capacity near Ahmedabad and Hyderabad offers first-mover positioning as CDSCO tightens packaging traceability rules for export markets.
- Automated packaging equipment convergence:Integration of thermoform-fill-seal lines with robotic handling and vision inspection is compressing labor content and enabling contract packaging scale economics.
- Bio-based certification tailwinds:EU Green Deal procurement preferences and emerging national bio-based content mandates are creating premium tier positioning for PLA and bio-PET thermoform variants with certified supply chains.
Industry Challenges
- Tooling engineer scarcity:Specialized mold design expertise for multi-cavity medical trays with tight tolerances is concentrating among aging workforces in Germany and Switzerland, constraining capacity expansion timelines.
- ISO 15378 certification backlog:Pharmaceutical primary packaging material qualification timelines extend 18-24 months, freezing supplier switching and complicating new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoform Packaging Market |
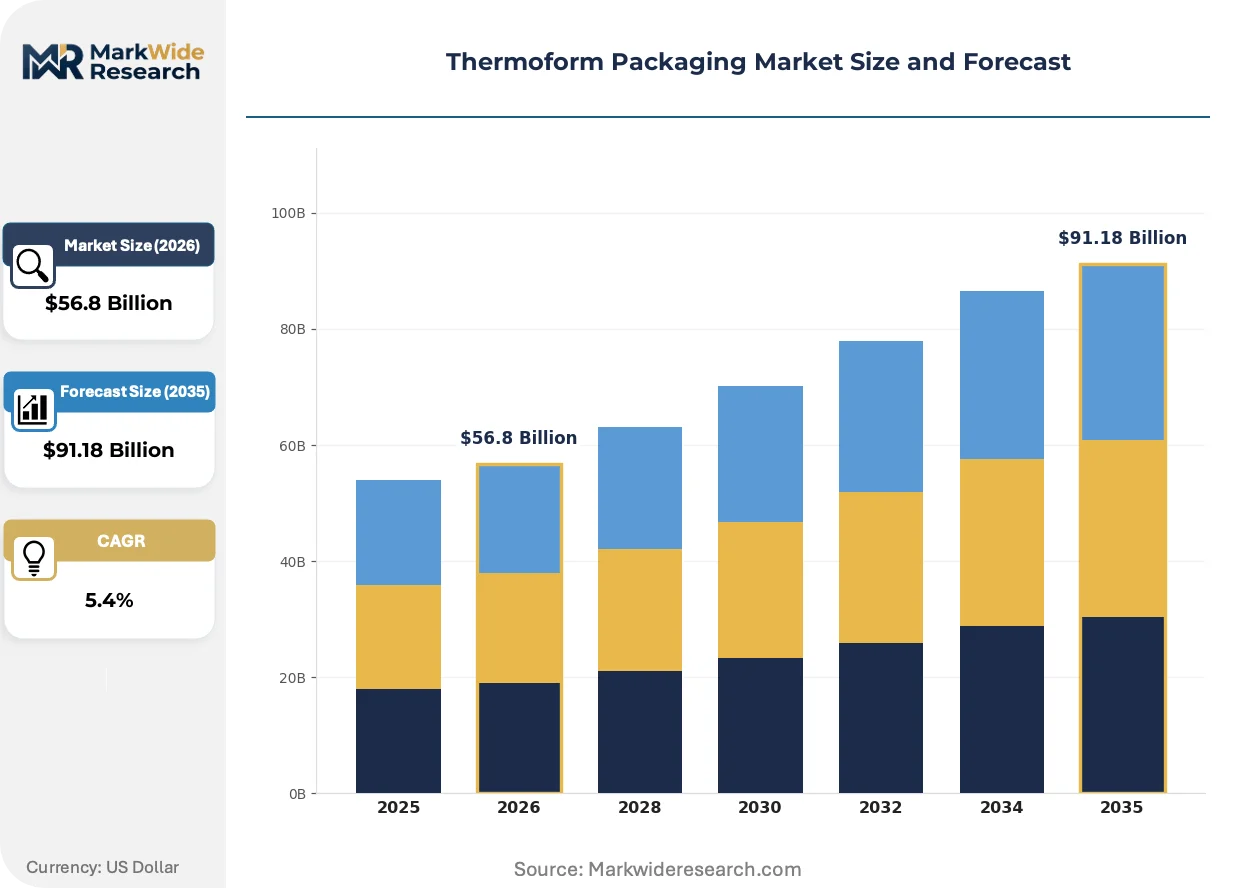
| Market Size in 2026 | $56.8 Billion |
| Market Size in 2035 | $91.18 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyvinyl Chloride, Polyethylene Terephthalate, Polystyrene, Polypropylene, Acrylonitrile Butadiene Styrene Application: Food Packaging, Pharmaceutical Packaging, Electronics Packaging, Cosmetic Packaging, Industrial Packaging Product Type: Blister Packs, Clamshells, Trays, Blisters, Clamshell Containers End User Industry: Food & Beverage, Healthcare Providers, Consumer Goods Manufacturers, Electronic Assemblers, Personal Care Brands |
| Companies Covered | Amcor plc, Sonoco Products Company, Berry Global Inc., Huhtamaki Oyj, Sealed Air Corporation, Constantia Flexibles Group, Georgia-Pacific, Mondi Group, Pactiv Evergreen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoform Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging functionalities are migrating from premium cosmetics into pharmaceutical and food safety applications, while digital print and serialization technologies compress minimum order quantities for regional brand variants.
Barrier-coated polyethylene terephthalate glycol (PETG) is integrating oxygen scavenging and moisture vapor transmission control into monolayer structures for pharmaceutical blister packs. Contract manufacturers serving generic drug makers are adopting these materials to extend shelf life without aluminum lidding complexity. The technology is integrating high-speed form-fill-seal lines previously limited to simpler barrier configurations, expanding addressable contract manufacturing scale.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in foam-core thermoforming processes used for protective packaging. Converters serving electronics and appliance sectors are retrofitting extrusion lines for CO2 or hydrocarbon blowing agent systems. German mechanical engineering suppliers dominate retrofit equipment supply, creating geographic concentration in process technology access that favors European converter investment cycles.
Hospital procurement consortia are consolidating thermoform tray suppliers to reduce qualification overhead and secure volume commitments for standardized sterile barrier configurations. Group purchasing organizations in the US Midwest and Northeast are displacing fragmented hospital-level contracting with multi-year framework agreements. This concentration is most visible in cardiovascular and orthopedic device sterilization packaging, where tray complexity and regulatory file maintenance costs favor incumbent retention.
Thermoform Packaging Market Segmentation
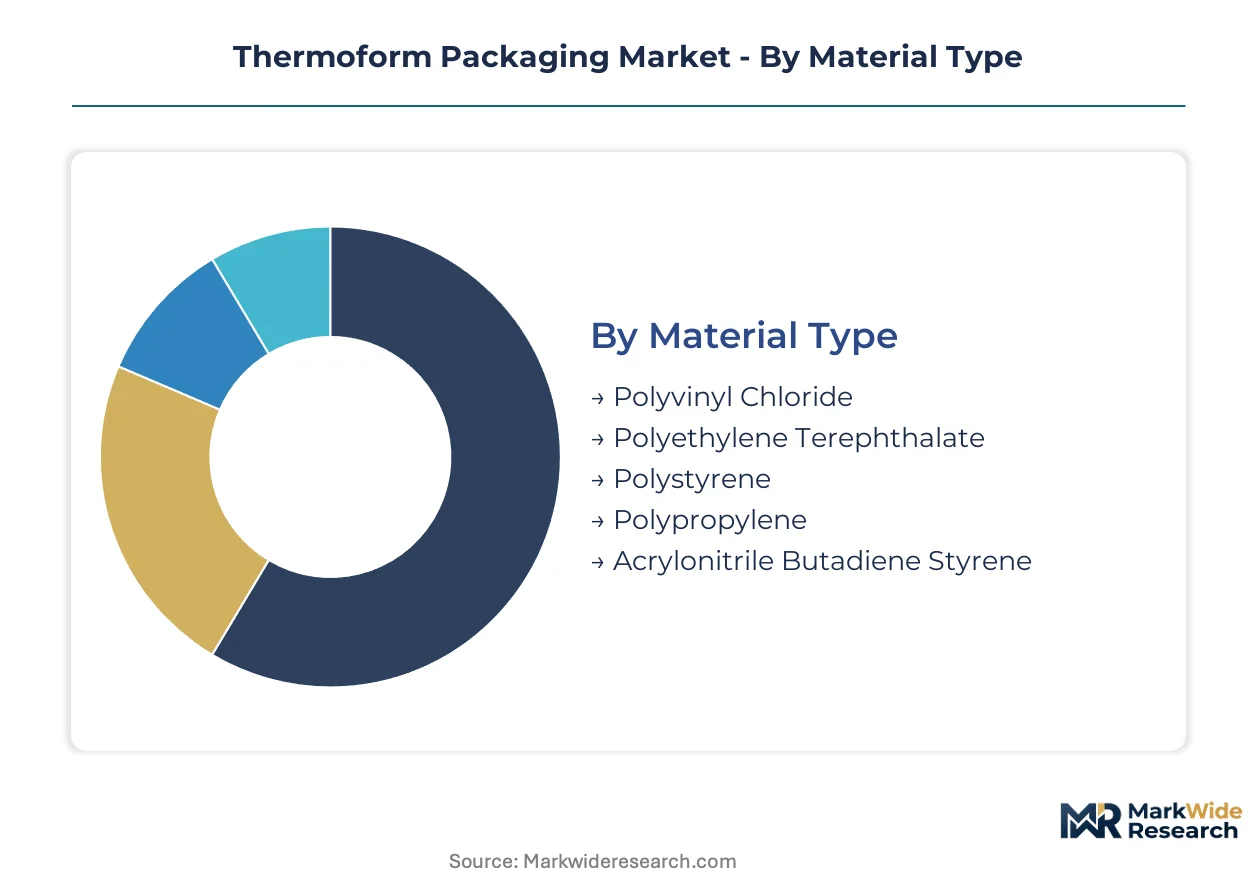
Thermoform packaging procurement splits across material chemistry, barrier performance, and sterilization requirements. Each segmentation axis reveals distinct supplier capabilities and qualification barriers that shape contract accessibility.
Material Type:
Resin supply concentrates among petrochemical majors with medical-grade certification depth, creating tiered converter access based on volume commitments and regulatory file maintenance.
- Polyethylene Terephthalate:Amorphous and crystalline grades dominate food-contact clarity applications. European reprocessors control post-consumer rPET flake supply for recycled-content variants, constraining converter sourcing flexibility.
- Polypropylene:Modified homopolymer and copolymer resins withstand retort sterilization and hot-fill protocols. Demand clusters around Germany's medical device manufacturing corridor where autoclave-compatible trays are non-negotiable.
- Polyvinyl Chloride:Plasticized formulations serve blister pack lidding and shallow-draw pharmaceutical applications with cost advantages in high-volume generic drug packaging.
- Polystyrene:Crystal and high-impact grades populate electronics protective packaging and limited-shelf-life food trays where moisture barrier demands remain modest.
- Acrylonitrile Butadiene Styrene:Engineering-grade toughness suits industrial component dunnage and reusable shipping containers requiring impact resistance across temperature cycles.
PET absorbs the bulk of installed capacity; polypropylene is expanding most quickly.
Application:
End-use requirements diverge sharply on sterility assurance, barrier integrity, and traceability mandates, fragmenting converter specialization.
- Food Packaging:Modified atmosphere and vacuum skin formats demand oxygen scavenging and moisture vapor control. Retail consolidation in North American and European grocery chains is compressing supplier rosters toward integrated form-fill-seal operators.
- Pharmaceutical Packaging:Primary barrier systems for sterile devices and unit-dose medications require ISO 15378 certification. FDA 21 CFR Part 820 quality system compliance extends qualification timelines to 18-24 months.
- Electronics Packaging:Electrostatic discharge protection and foam-core cushioning specifications favor converters with custom mold design capabilities and cleanroom thermoforming infrastructure.
- Cosmetic Packaging:Visual clarity and theft-deterrent clamshell configurations command premium pricing in prestige retail channels where shelf presence drives procurement decisions.
- Industrial Packaging:Heavy-gauge dunnage and returnable container systems prioritize durability over barrier performance, sourcing from converters with thick-sheet rotary and pressure-forming equipment.
Food packaging commands the deepest converter installed base; pharmaceutical applications carry the steepest expansion trajectory.
Product Type:
Tooling complexity and cavity count economics separate commodity producers from precision medical specialists.
- Blister Packs:The dominant product format pairs thermoformed cavities with lidding foil for unit-dose pharmaceuticals and consumer goods. High-speed form-fill-seal integration favors converters with automated packaging equipment convergence.
- Clamshells:Hinged two-piece designs serve electronics and cosmetics retail display where theft deterrence and visual merchandising converge. Premium margins attract specialized mold designers with multi-cavity expertise.
- Trays:Medical device sterilization trays require tight dimensional tolerances and sterile barrier validation. Tooling engineer scarcity in Germany and Switzerland constrains capacity expansion timelines.
- Blisters:Shallow-draw formats without lidding complexity populate food sampling and promotional applications with faster tooling turnaround and lower capital barriers.
- Clamshell Containers:Deep-draw hinged designs for produce and deli applications compete with molded fiber substitutes where moisture barriers are less critical.
Blister packs represent the highest volume category; clamshells generate the strongest margin differentiation.
End User Industry:
Customer procurement consolidation and qualification overhead reshape competitive access across verticals.
- Food & Beverage:Processor and retail private-label demand concentrates toward converters with food-grade certification and high-volume extrusion capacity. EU Green Deal procurement preferences are elevating bio-based material sourcing requirements.
- Healthcare Providers:Hospital group purchasing organizations in the US Midwest and Northeast are displacing fragmented contracting with multi-year framework agreements for standardized sterile barrier configurations.
- Consumer Goods Manufacturers:Mass-market brands prioritize unit cost and shelf impact, sourcing clamshell and blister formats through contract packaging intermediaries.
- Electronic Assemblers:Cleanroom thermoforming and static-dissipative formulations are required for semiconductor and component shipping trays.
- Personal Care Brands:Premium positioning demands visual clarity and custom shaping that supports brand differentiation in crowded retail environments.
Food and beverage absorbs the bulk of industry capacity; healthcare providers are consolidating supplier relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany's precision tooling corridor while consumption spreads across pharmaceutical manufacturing clusters in India and medical device hubs in the United States. Material conversion economics favor proximity to sterile barrier demand centers.
United States
FDA 21 CFR Part 820 enforcement tightens sterile packaging traceability for cardiovascular and orthopedic device manufacturers. Hospital group purchasing organizations in the Midwest and Northeast consolidate supplier rosters toward multi-year framework agreements. Minneapolis-St. Paul anchors medical device packaging demand with concentrated sterilization tray procurement.
Germany
EMA Medical Device Regulation drives barrier integrity upgrades across Tuttlingen's surgical instrument manufacturers. EU F-Gas Regulation accelerates hydrofluorocarbon phase-out in foam-core protective packaging processes. Munich's medical technology corridor generates localized demand for autoclave-compatible polypropylene tray supply.
India
CDSCO packaging traceability rules tighten for pharmaceutical export markets serving Europe and North America. Ahmedabad's pharmaceutical formulation cluster drives sterile barrier thermoforming capacity expansion. Hyderabad's vaccine manufacturing infrastructure creates demand for high-integrity cold-chain packaging.
China
NMPA medical device registration reforms elevate packaging validation requirements for imported sterile barriers. Dual carbon goals reshape material sourcing toward bio-based and recycled content variants. Yangtze River Delta electronics manufacturing sustains demand for electrostatic-dissipative shipping trays.
Switzerland
Swissmedic pharmaceutical packaging regulations maintain alignment with EU MDR standards for cross-border supply. Precision mold design expertise concentrates in aging workforces around Zurich and Basel. Basel's pharmaceutical headquarters cluster sustains premium sterile barrier procurement for biologics and injectables.
Thermoform Packaging Market Key Industry Players
Top-tier vendors anchor global sterile barrier supply through integrated film extrusion and medical-grade certification infrastructure, while regional specialists capture food-grade and industrial segments through flexible tooling investments. The vendor base splits between diversified packaging conglomerates with healthcare divisions and pure-play thermoforming converters with deep mold engineering capabilities. Three archetypes dominate: integrated material-to-package suppliers, automated equipment-integrated contract manufacturers, and precision medical tray specialists. Competitive positioning hinges on ISO 15378 certification maintenance and backward integration into medical-grade resin compounding.
Among diversified packaging conglomerates, Amcor plc and Berry Global Inc. occupy positions spanning pharmaceutical sterile barriers through food-grade clarity applications. Sealed Air Corporation exemplifies the equipment-integrated archetype with automated packaging system convergence. These three anchors represent distinct strategic postures: material science depth, North American manufacturing scale, and packaging automation integration respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Sonoco Products Company |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Constantia Flexibles Group |
| Georgia-Pacific |
| Mondi Group |
| Pactiv Evergreen Inc. |
| Others |
Cost & Logistics Intelligence
Hospital group purchasing organization consolidation in the US Midwest and Northeast is compressing supplier rosters toward multi-year framework agreements, forcing converters to absorb qualification overhead into contract pricing or cede volume to integrated competitors with captive sterile barrier capacity.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with 18-24 month ISO 15378 certification timelines forcing device manufacturers to pay premiums for qualified supplier slots while spot inventory from non-certified converters trades at discounts. Pricing stratifies across medical-grade certified, food-grade compliant, and industrial-grade tiers, with certification level and volume scale as the primary differentiation drivers. Cost compression in food-contact PET runs through recycled-content mandates as European reprocessor concentration limits feedstock flexibility. Generic drug contract manufacturers exhibit the highest price sensitivity, while biologics and orthopedic device makers prioritize barrier integrity over unit cost.
Supply Chain Analysis
Direct-to-medical-device-OEM channels handle sterilization tray demand from Tuttlingen and Minneapolis-St. Paul clusters, while distribution through contract packaging intermediaries serves food and consumer goods segments with fragmented buyer bases. Raw material supply concentrates in Germany, Switzerland, and the United States, with medical-grade resin compounding and precision mold engineering as critical inputs. The supply chain rests on post-consumer rPET flake from limited European reprocessors, creating single-source vulnerability for food-contact clarity applications. Tariff exposure on Chinese-manufactured form-fill-seal equipment compounds capital investment risk for capacity expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoform packaging is consolidating toward integrated suppliers with medical-grade certification depth, as EU F-Gas Regulation compliance costs and ISO 15378 qualification timelines force sub-scale converters into exit or acquisition.
For Market Incumbents: Acquire precision mold engineering capabilities in Germany and Switzerland to secure tooling engineer scarcity advantages before demographic retirement accelerates. Backward integration into medical-grade resin compounding defends margin position against petrochemical major pricing power, while automated form-fill-seal equipment convergence compresses labor content to match contract packaging scale economics. For New Entrants and Emerging Players: Contract packaging intermediaries serving generic drug makers represent the most penetrable channel, as these buyers prioritize cost over brand loyalty and lack incumbent supplier lock-in from multi-year hospital GPO agreements. Target India's pharmaceutical export zones near Ahmedabad and Hyderabad, where CDSCO traceability rule tightening creates first-mover positioning before domestic sterile barrier capacity saturates. For Investors and Strategic Acquirers: The window for entry favors precision medical tray specialists with ISO 15378 certification maintenance capabilities and established regulatory file libraries. Long-term viability hinges on exposure to healthcare provider procurement consolidation rather than food-grade commodity exposure. Watch for EMA MDR enforcement intensity as the inflection signal determining barrier integrity upgrade spending cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Qualification timelines extend 18-24 months, freezing supplier switching and protecting incumbent revenue. |
| Automated Form-Fill-Seal Integration | Robotic handling and vision inspection compress labor content for cardiovascular device tray production. |
| Backward Integration into rPET Sourcing | European reprocessor concentration creates captive feedstock security for food-contact clarity applications. |
| Precision Mold Engineering Acquisition | German and Swiss tooling expertise concentrates among aging workforces, constraining competitor expansion. |
| India Pharmaceutical Export Zone Entry | CDSCO traceability rules tighten for export markets, creating sterile barrier demand before domestic capacity saturates. |
Research Approach
Independent corroboration across converter operations managers, medical device packaging engineers, hospital GPO contracts managers, and pharmaceutical regulatory affairs leads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA 21 CFR Part 820 enforcement records, EMA MDR guidance documents, EU F-Gas Regulation implementation schedules, and customs trade data for thermoform equipment imports. Bottom-up capacity assessments at major production clusters triangulate against top-down demand modeling from end-use industry procurement databases.
Rate-of-change decomposition separates volume growth from value growth across material type, application, product format, and sterilization requirement dimensions over the projection horizon. CAGRs derive from segment-level demand elasticity modeling against regulatory compliance cost trajectories and substitution threat intensity from molded fiber and bio-based alternatives. Forecast inputs incorporate EU Green Deal procurement preference evolution and hospital GPO consolidation pace assumptions.
Several conditions sit outside the modeled scope, including abrupt shifts in FDA enforcement intensity, unilateral tariff impositions on thermoforming equipment, and breakthroughs in paper-fiber barrier coating performance that could accelerate substitution. Forecasts reflect assumptions about certification timeline stability and resin supply concentration persistence that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market