
 Thailand Data Center Power Market | 2026-2036
Thailand Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Power Market Insights
Thailand's certified electrical engineering pool is redrawing competitive boundaries in data center power deployment. Schneider Electric SE leverages its regional manufacturing footprint to shorten delivery cycles for switchgear and power distribution units. Vertiv Group Corp anchors the precision cooling and power conditioning segment with localized service networks. ABB Ltd competes on medium-voltage infrastructure integration for multi-megawatt campuses.
Data center power encompasses the generation, conversion, distribution, and backup systems that deliver conditioned electricity with uptime exceeding 99.999% across server halls, typically operating at 380-480V three-phase AC with redundant N+1 or 2N architectures. The primary purpose is eliminating single points of failure that could disrupt cloud computing, financial transactions, or telecommunications routing. UPS Systems within the Power Type category capture premium margins as lithium-ion battery adoption displaces valve-regulated lead-acid designs. The Above 10 MW capacity tier is expanding fastest as hyperscale operators consolidate into fewer, larger facilities rather than distributed footprints. Colocation Services under Service Type are maturing into commodity offerings while Managed Services retain pricing power through energy optimization and predictive maintenance contracts.
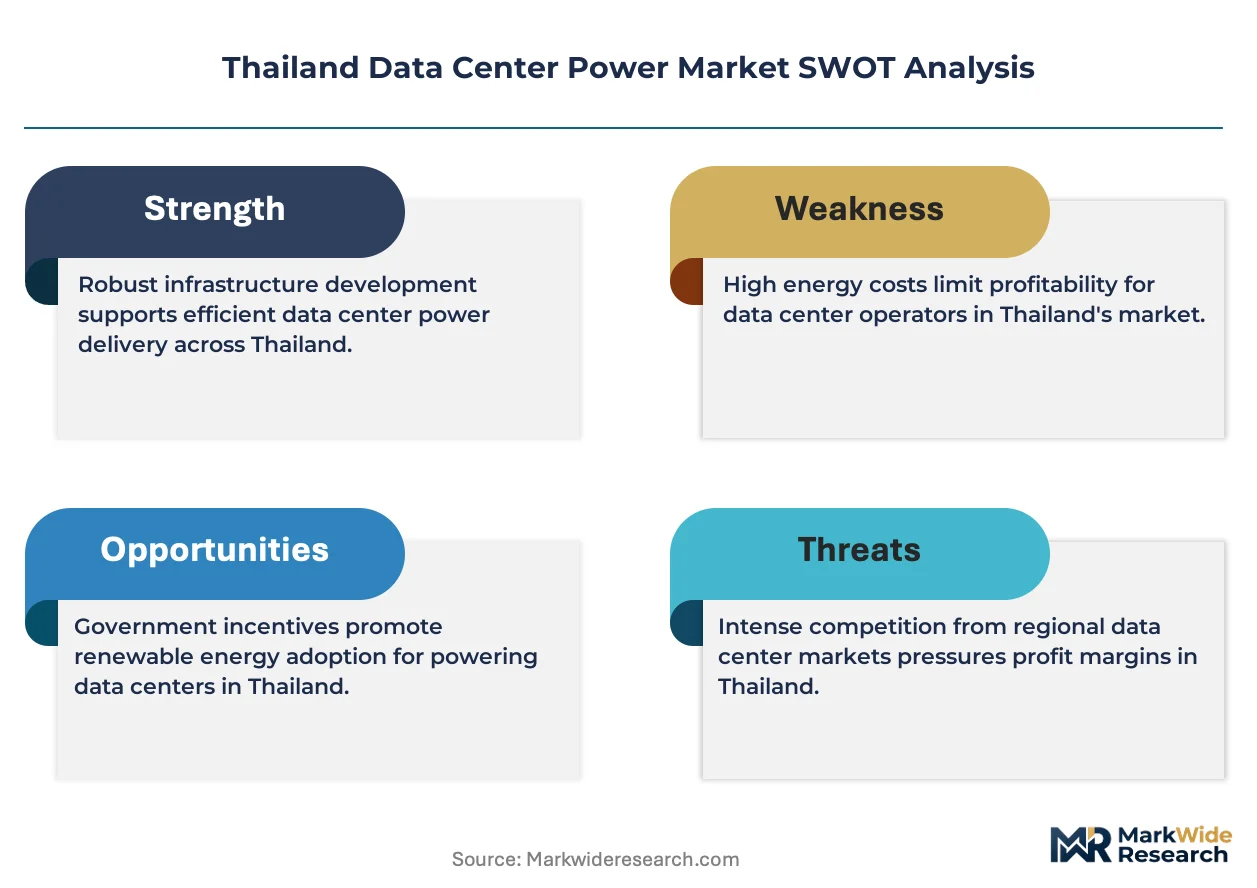
Thailand's Board of Investment promotion criteria shape facility location decisions through tax incentives tied to minimum investment thresholds and energy efficiency benchmarks. The country's national electrical regulator and metropolitan utility authority influence grid interconnection timelines and tariff structures for new data center loads. Stakeholders must monitor whether Thailand's renewable energy certificate market matures sufficiently to support corporate sustainability commitments without relying on direct power purchase agreements.
Market Dynamics
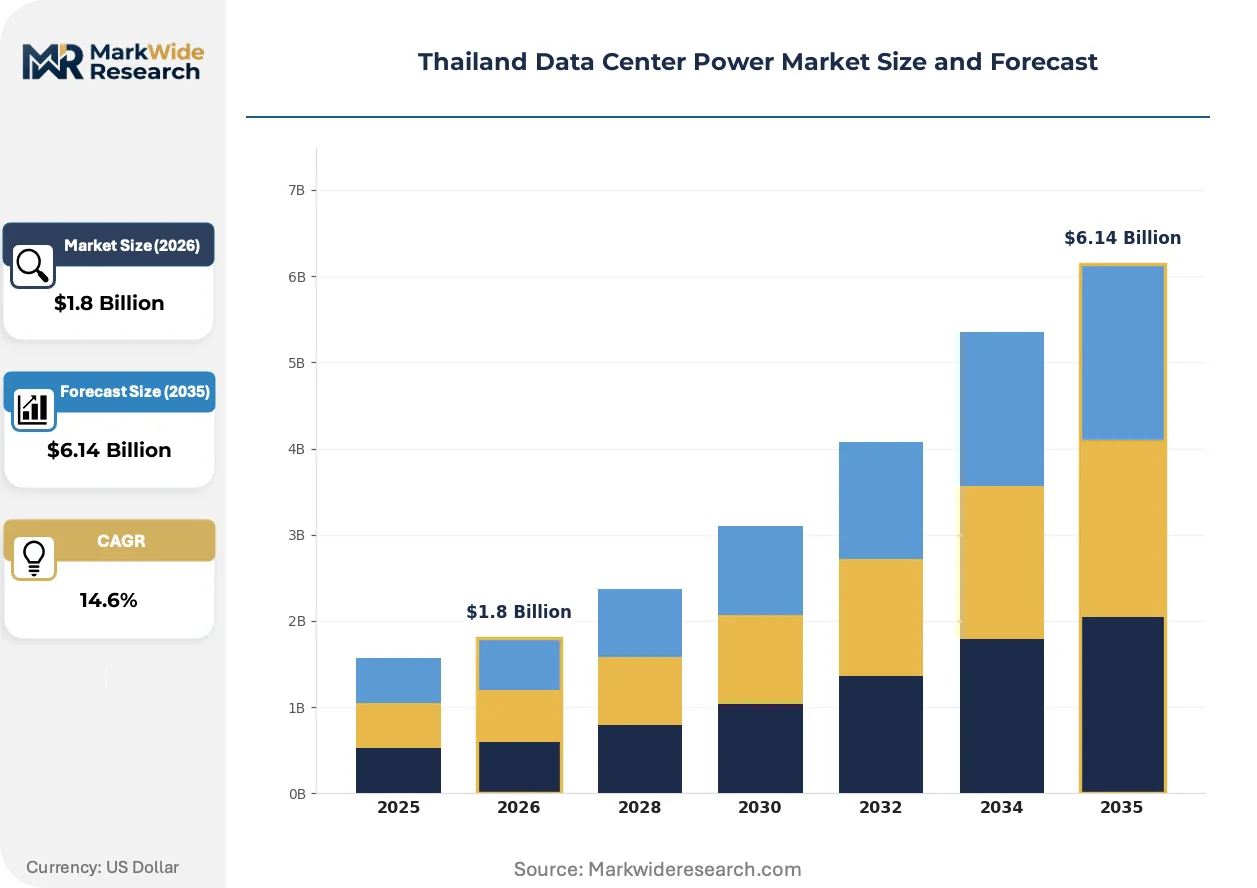
The Thai government's Board of Investment data center promotion measures are compressing facility construction timelines while hyperscale operators consolidate into fewer, larger campuses across the Eastern Economic Corridor, fundamentally restructuring deployment velocity and capital concentration patterns.
Growth Catalysts
- BOI Investment Incentives:Thailand's Board of Investment offers tax holidays and import duty exemptions tied to minimum investment thresholds and energy efficiency benchmarks, directly accelerating facility construction decisions.
- Hyperscale Campus Consolidation:Cloud service providers are expanding capacity in Greater Bangkok and the Eastern Economic Corridor, creating concentrated demand for multi-megawatt power infrastructure.
- Lithium-ion Battery Transition:UPS systems are capturing premium margins as lithium-ion designs displace valve-regulated lead-acid batteries, improving energy density and reducing footprint requirements.
Market Restraints
- Certified Electrical Engineer Scarcity:Thailand's limited pool of certified electrical engineers constrains deployment velocity for complex medium-voltage infrastructure integration.
- Grid Interconnection Timelines:The metropolitan utility authority and national electrical regulator influence connection schedules and tariff structures, creating uncertainty for new data center loads.
- Renewable Energy Certificate Immaturity:Thailand's REC market lacks sufficient depth to support corporate sustainability commitments without direct power purchase agreements.
Strategic Opportunities
- Managed Services Expansion:Energy optimization and predictive maintenance contracts retain pricing power as colocation services commoditize, creating margin expansion potential.
- Above 10 MW Tier Growth:The fastest-expanding capacity segment rewards suppliers with multi-megawatt integration capabilities and localized service networks.
- Regional Manufacturing Localization:Switchgear and power distribution unit production within Thailand shortens delivery cycles against imported alternatives.
Industry Challenges
- Legacy System Integration Complexity:New N+1 and 2N redundant architectures must interface with existing grid infrastructure and backup power configurations.
- Certification Timeline Compression:BOI incentive eligibility requires meeting energy efficiency benchmarks within strict construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Power Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: AC Power, DC Power, Solar Energy, UPS Systems Capacity: Below 1 MW, 1-5 MW, 5-10 MW, Above 10 MW Service Type: Colocation Services, Managed Services, Interconnection Services, Connectivity Services End User: IT Companies, Telecom Providers, Financial Institutions, E-commerce Platforms |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, ABB Ltd, Eaton Corporation plc, Cummins Inc, Rittal GmbH & Co. KG, Legrand Group, Fujitsu Limited, Caterpillar Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Power Market Trends and Innovations
Power infrastructure deployment in Thailand is accelerating toward higher-density, software-defined architectures as operators pursue 99.999% uptime targets while compressing commissioning schedules.
Lithium-ion battery systems are displacing valve-regulated lead-acid designs across UPS installations in hyperscale facilities. Cloud service providers deploying Above 10 MW campuses in the Eastern Economic Corridor are specifying lithium-ion for its superior cycle life and thermal performance. This chemistry transition is compressing battery room footprints by sixty percent while enabling longer runtime configurations.
Thailand's Board of Investment promotion criteria are tightening energy efficiency benchmarks for new facility approvals. The revised incentive framework requires minimum power usage effectiveness thresholds and renewable energy integration plans. Hyperscale operators are responding by procuring medium-voltage infrastructure with integrated energy management capabilities.
Managed service contracts are unbundling from traditional hardware procurement arrangements. Colocation providers in Greater Bangkok are separating energy optimization and predictive maintenance offerings from base facility leases. This shift is most visible among financial services tenants requiring guaranteed uptime without capital ownership of power assets.
Thailand Data Center Power Market Segmentation
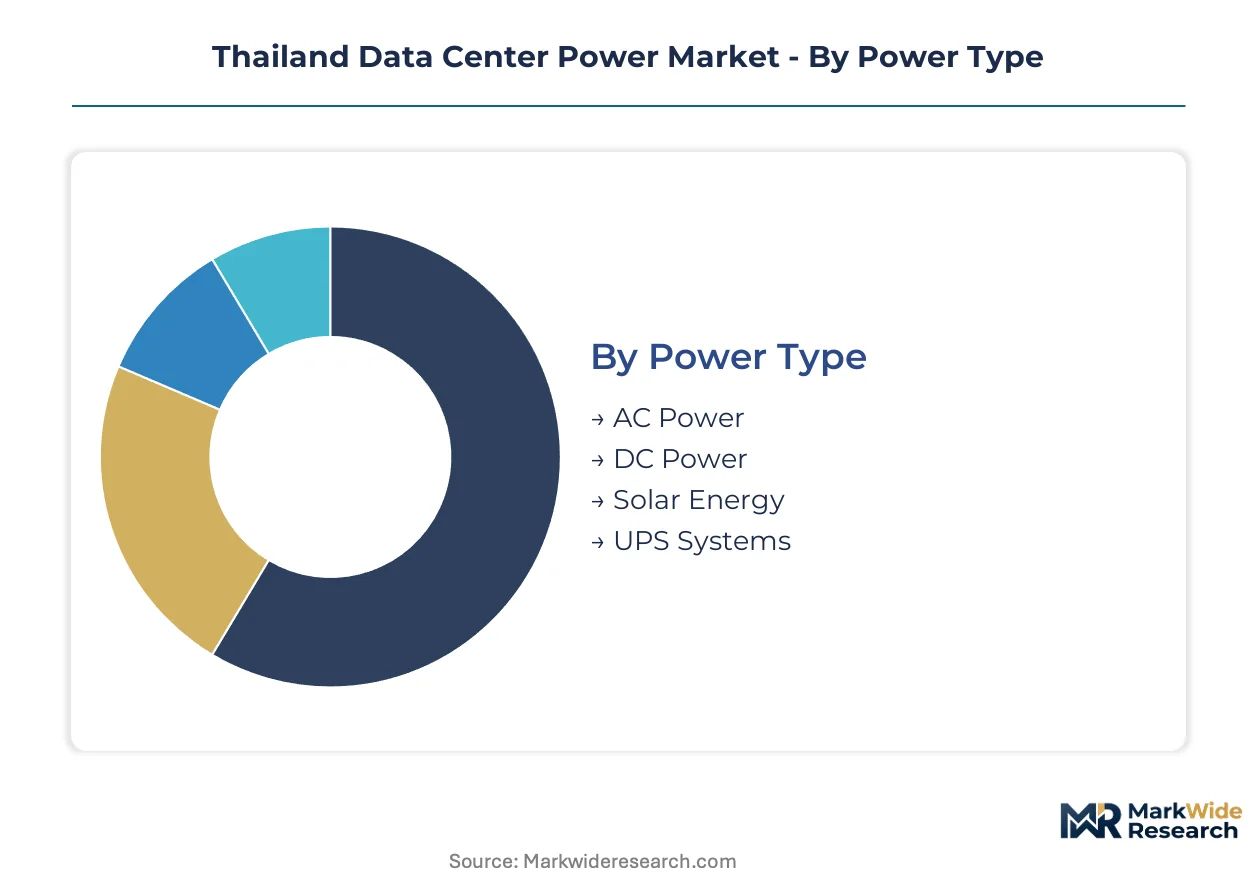
Power infrastructure procurement in Thailand clusters around four distinct dimensions that reshape vendor engagement models. The Board of Investment's tiered incentive structure rewards higher-capacity deployments, while service unbundling creates separate contracting streams for hardware and operations.
Power Type:
Thailand's Board of Investment energy efficiency benchmarks favor configurations with measurable power usage effectiveness, creating procurement bias toward certifiable architectures.
- UPS Systems:Deliver conditioned backup power through lithium-ion battery arrays that displace legacy valve-regulated lead-acid designs. Hyperscale campuses across the Eastern Economic Corridor specify these for sixty-percent footprint reduction and extended runtime configurations.
- AC Power:Distributes 380-480V three-phase electricity through redundant N+1 or 2N switchgear configurations. Greater Bangkok facilities prioritize AC infrastructure for its interoperability with existing metropolitan utility grid standards.
- DC Power:Supplies direct current for high-density server racks and telecommunications switching equipment.
- Solar Energy:Integrates photovoltaic generation with battery storage for partial load offset and renewable energy certificate eligibility.
UPS Systems handles the majority of throughput; Solar Energy is the fastest mover on share.
Capacity:
Investment thresholds under BOI promotion criteria scale with facility size, compressing capital deployment into fewer megawatt-dense locations.
- Above 10 MW:Consolidates hyperscale demand into purpose-built campuses with dedicated substations and medium-voltage infrastructure. Cloud service providers favor this tier for operational leverage and streamlined regulatory approval.
- 1-5 MW:Serves regional colocation operators and enterprise captive facilities requiring modular expansion pathways.
- 5-10 MW:Occupies a transitional zone between enterprise and hyperscale deployment models.
- Below 1 MW:Addresses edge computing nodes and branch office server rooms with standardized rack-level power.
Above 10 MW dominates capital allocation; Below 1 MW is expanding most quickly at the network edge.
Service Type:
Contract structures in Greater Bangkok are decoupling facility leases from operational responsibility, creating distinct revenue pools.
- Managed Services:Encompasses energy optimization, predictive maintenance, and uptime guarantee contracts. Financial institutions in Bangkok's central business district procure these separately to avoid power asset ownership.
- Colocation Services:Provides physical space with standardized power and cooling on a per-rack or per-cage basis.
- Interconnection Services:Facilitates cross-connects between tenants and network carriers within carrier-neutral facilities.
- Connectivity Services:Delivers IP transit, dedicated internet access, and cloud on-ramps.
Colocation Services captures the largest revenue base; Managed Services is climbing the fastest on margin expansion.
End User:
Demand composition reflects Thailand's digital economy priorities, with foreign cloud operators and domestic financial institutions driving divergent specification requirements.
- IT Companies:Encompasses hyperscale cloud providers deploying multi-megawatt campuses and software-as-a-service operators requiring elastic capacity. Eastern Economic Corridor incentives attract these operators for export-oriented data processing.
- Financial Institutions:Mandate 99.999% uptime with documented disaster recovery capabilities. Bangkok-based banks specify 2N redundant architectures and dedicated backup power islands.
- Telecom Providers:Require low-latency interconnection for 5G core networks and content delivery infrastructure.
- E-commerce Platforms:Demand scalable power for transaction processing peaks and seasonal load variation.
IT Companies anchor volume commitment; Financial Institutions is gaining share fastest on compliance-driven upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's data center power deployment concentrates in the Eastern Economic Corridor and Greater Bangkok, while regional neighbors pursue divergent infrastructure strategies shaped by distinct regulatory frameworks and investment incentive structures.
Greater Bangkok
Hyperscale cloud providers anchor power infrastructure demand across metropolitan Bangkok and surrounding provinces. The Board of Investment's tiered incentive scheme compresses approval timelines for facilities meeting minimum investment thresholds. Lat Phrao and Bang Na districts host the densest clustering of multi-megawatt campuses with dedicated medium-voltage substations.
Eastern Economic Corridor
Chonburi, Rayong, and Chachoengsao provinces consolidate export-oriented data processing capacity under specialized zone status. Thailand's national electrical regulator coordinates grid interconnection schedules with the metropolitan utility authority for these corridor loads. Amata City and WHA industrial estates attract dedicated substation investments from international operators.
Central Plains Region
Ayutthaya and Saraburi provinces emerge as secondary nodes for disaster recovery and backup capacity. Provincial utility subsidiaries manage connection queues that lag metropolitan timelines by six to twelve months. Bang Pa-in and Wang Noi industrial zones accommodate mid-tier colocation facilities seeking lower land costs than Bangkok.
Northern Thailand
Chiang Mai and Chiang Rai provinces target latency-sensitive applications for Indochina connectivity. The Digital Economy Promotion Agency extends modified incentive packages for edge computing nodes in these provinces. Mae Sai and Chiang Khong border zones experiment with cross-border power arrangements for Myanmar and Lao PDR traffic.
Southern Thailand
Songkhla and Phuket provinces pursue submarine cable landing station synergies for international bandwidth. The Energy Regulatory Commission reviews special tariff structures for these marine-connected loads. Hat Yai and Phuket Town develop smaller-scale facilities serving regional financial services and tourism transaction processing.
Thailand Data Center Power Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Thailand's data center power market. The upper tier combines switchgear manufacturing with energy management software and lifecycle service capabilities. The specialist tier fragments across battery systems, precision cooling, and backup generation. Three archetypes dominate: full-stack infrastructure integrators, component specialists with localized service networks, and power quality engineers with medium-voltage expertise. Competitive moves center on backward integration into lithium-ion battery assembly and geographic expansion through Bangkok-based service hubs.
Within the full-stack infrastructure tier, Schneider Electric SE exemplifies integrated power distribution capabilities, while Vertiv Group Corp anchors precision cooling and power conditioning specialization. ABB Ltd occupies a position among medium-voltage infrastructure engineers serving multi-megawatt campus requirements. These three represent distinct strategic postures toward Thailand's BOI incentive structure and Eastern Economic Corridor deployment timelines.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| ABB Ltd |
| Eaton Corporation plc |
| Cummins Inc |
| Rittal GmbH & Co. KG |
| Legrand Group |
| Fujitsu Limited |
| Caterpillar Inc |
| Others |
Pricing and Supply Chain Analysis
Thailand's Board of Investment energy efficiency certification gates supplier qualification and price differentiation simultaneously, compressing vendor margins for non-compliant equipment while rewarding integrated power management platforms with premium positioning.
Pricing Analysis
Long-term offtake contracts dominate hyperscale procurement in the Eastern Economic Corridor, while spot purchasing persists for Below 1 MW edge deployments. Three-tier pricing structure across premium, standard, and economy levels separates lithium-ion UPS configurations with predictive analytics from commodity valve-regulated lead-acid alternatives. Cost compression in standard-tier switchgear is intensifying because Chinese manufacturers are expanding Bangkok-based assembly operations. Financial institutions demonstrate lowest price sensitivity due to compliance mandates, whereas regional colocation operators negotiate aggressively on per-rack power fees.
Supply Chain Analysis
Inbound logistics costs from Laem Chabang port congestion and container availability constraints on the China-Thailand trade lane are extending lead times for medium-voltage switchgear imports. Manufacturing concentrates in China, South Korea, and Germany for precision power conditioning equipment, while battery cell production draws from China, Japan, and South Korea. Raw material dependencies span copper busbar, silicon carbide semiconductors, and lithium carbonate. Single-source vulnerability in IGBT module supply creates bottleneck risk for UPS system integrators. Distribution runs through Bangkok-based electrical engineering contractors with BOI-certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services contracts for energy optimization and predictive maintenance are expanding faster than hardware procurement, creating a service-attach opportunity that vendors must capture to sustain margin profiles.
For Market Incumbents: Shield installed base relationships by embedding lithium-ion battery monitoring software into existing UPS deployments before competitors unbundle hardware from service contracts. Expand Bangkok-based technical certification programs to address certified electrical engineer scarcity that constrains competitor deployment velocity. Deepen backward integration into power distribution unit assembly within Thailand's Eastern Seaboard industrial zones.
For New Entrants and Emerging Players: Lead with disaster recovery and backup capacity specifications for Central Plains Region facilities, where BOI incentives apply but metropolitan utility connection queues lag Greater Bangkok by six to twelve months. Target provincial utility subsidiaries with modular medium-voltage infrastructure that accelerates grid interconnection timelines. Position around energy management software licensing rather than capital equipment ownership.
For Investors and Strategic Acquirers: Thailand's revised BOI incentive framework reshapes the acquisition landscape by privileging vendors with integrated renewable energy certificate eligibility and power usage effectiveness certification capabilities. Five-to-ten year viability favors suppliers with captive lithium-ion battery assembly and localized service networks over pure hardware traders. Monitor whether the national electrical regulator accelerates grid interconnection approval timelines as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed Services Unbundling | Separates energy optimization contracts from base colocation leases for Bangkok financial tenants. |
| Lithium-ion Battery Transition | Compresses battery room footprints sixty percent while extending runtime for Eastern Economic Corridor campuses. |
| Regional Manufacturing Localization | Shortens switchgear delivery cycles against imported alternatives through Thailand-based assembly. |
| Medium-voltage Infrastructure Integration | Enables multi-megawatt campus consolidation with dedicated substation investments at Amata City. |
| Predictive Maintenance Platform Deployment | Captures recurring revenue from hyperscale operators seeking guaranteed uptime without asset ownership. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with data center engineering directors, electrical contractors with BOI certification, metropolitan utility interconnection planners, and lithium-ion battery system integrators; alongside secondary validation through Thailand Board of Investment incentive filings, national electrical regulator grid connection databases, and hyperscaler capital expenditure disclosures. Primary fieldwork captured deployment timelines and procurement decision criteria. Secondary sources included customs records for power equipment imports and Eastern Economic Corridor industrial estate development permits. Bottom-up facility counts triangulated against top-down power capacity estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning power type, capacity tier, service structure, and end-user vertical. CAGRs derived from facility pipeline tracking and equipment procurement patterns. Forecast inputs incorporated BOI approval velocity, certified electrical engineer supply constraints, and lithium-ion battery cost curves.
The analysis sits within stated boundaries; outcomes outside sustained BOI incentive continuity, grid interconnection schedule reliability, and renewable energy certificate market maturation would require recalibration. Forecasts reflect documented assumptions about hyperscale consolidation patterns and metropolitan utility tariff structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Spain Data Center Market