
 Converged Infrastructure Management Market | 2026-2036
Converged Infrastructure Management Market Size, Share, and Industry Trends Forecast 2026-2036
Converged Infrastructure Management Market Analysis
Subscription-based financing and infrastructure-as-a-service leasing is narrowing the capital barrier for mid-sized buyers entering converged infrastructure deployments. Dell Technologies leverages its end-to-end server-storage portfolio to anchor enterprise refresh cycles. Nutanix competes through software-centric disaggregation that reduces hardware lock-in. Huawei Technologies extends its position in Asia-Pacific through integrated networking-compute bundles tailored to telecom operators.
Converged Infrastructure Management unifies compute, storage, networking, and virtualization resources into pre-validated, centrally orchestrated systems that eliminate siloed administration overhead. These platforms typically deploy with automated lifecycle management APIs and policy-driven resource pools to support multi-tenant enterprise workloads. Hyper-Converged Infrastructure dominates procurement volumes as organizations replace three-tier architectures with scale-out nodes. Cloud Service Providers represent the fastest-growing end user category, driven by edge colocation and sovereign cloud buildouts. Hybrid deployment models capture expanding margin pools as enterprises retain sensitive workloads on-premises while bursting to public infrastructure.
FCC guidelines on data center energy reporting, EU CSRD sustainability disclosures, and ISO 27001 information security management standards collectively shape procurement criteria and vendor qualification pathways. NIST cybersecurity frameworks in the United States further mandate continuous monitoring capabilities that converged platforms must embed natively. Stakeholders should evaluate vendor API openness and cross-cloud orchestration depth before committing to long-term infrastructure contracts.
Market Dynamics
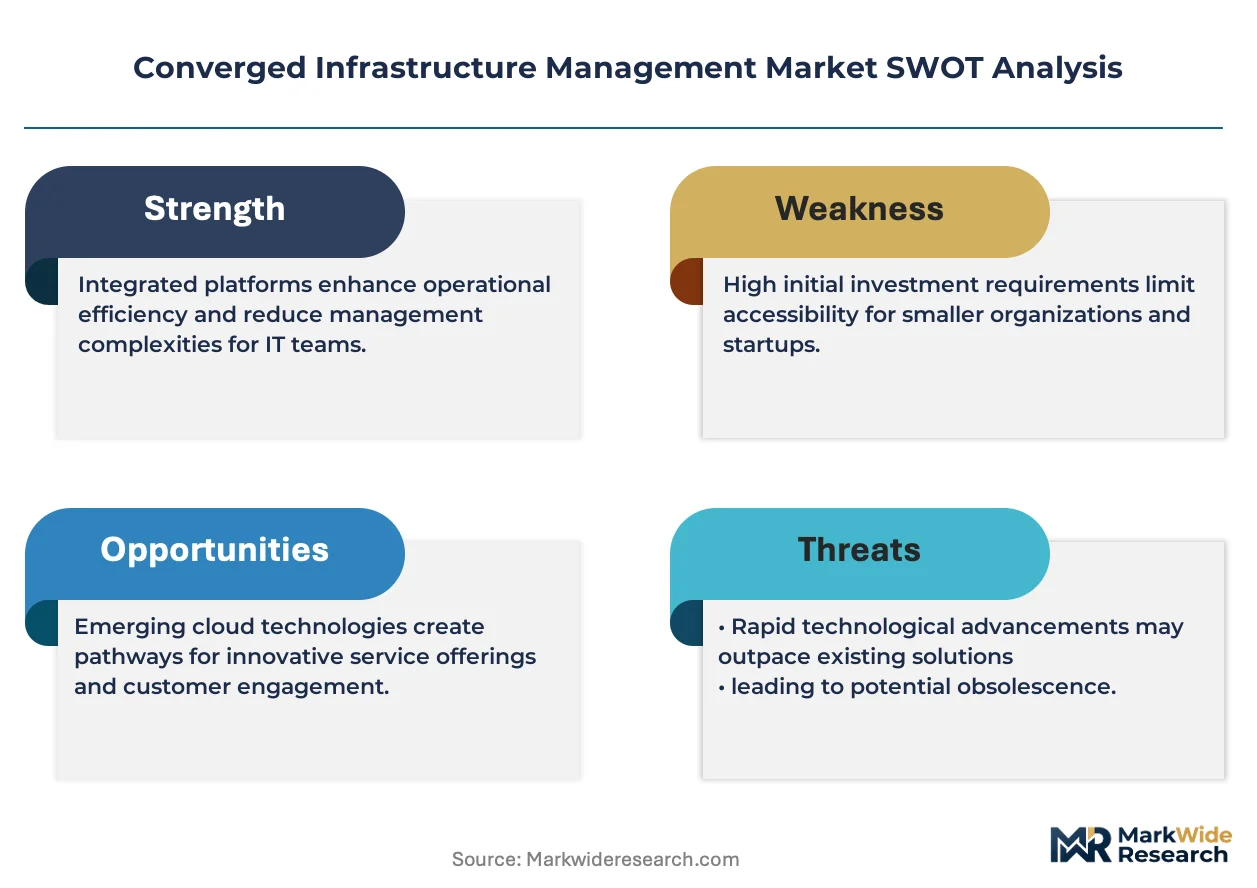
Enterprise consolidation of three-tier data center architectures into unified software-defined platforms is compressing refresh cycles and forcing incumbent vendors to restructure pricing around consumption-based models rather than perpetual licensing.
Growth Catalysts
- ISO 27001 compliance mandates:Information security management certification requirements in Germany and Japan are accelerating replacement of legacy siloed systems with centrally auditable converged platforms that embed continuous monitoring.
- Edge colocation buildouts:Telecom operators across the United States are deploying hyper-converged nodes at cell tower aggregation points to support low-latency 5G network slicing and sovereign data processing.
- Storage-class memory integration:Persistent memory technologies are collapsing the performance gap between DRAM and flash, enabling single-tier data placement that eliminates separate storage administration tiers.
Market Restraints
- Specialized engineering talent scarcity:Shortage of professionals certified in software-defined networking and hypervisor orchestration is extending deployment timelines and inflating implementation costs for mid-sized enterprises.
- Memory and processor supply concentration:Dependence on advanced semiconductor fabrication concentrated in Taiwan and South Korea creates vulnerability to geopolitical disruption and allocation constraints during demand spikes.
- Hybrid cloud substitution pressure:Native public cloud IaaS offerings from hyperscalers are capturing workloads that might otherwise deploy on-premises converged infrastructure, particularly among cloud-native application developers.
Strategic Opportunities
- Sovereign cloud infrastructure in Germany:EU data localization requirements under GDPR and the proposed Data Act are creating demand for on-premises converged systems that maintain jurisdictional control over sensitive government and financial data.
- AI/ML training cluster deployments:Convergence of GPU-accelerated compute with high-throughput NVMe storage and RDMA networking is opening specialized configurations for enterprise artificial intelligence development pipelines.
- Equipment-as-a-service channel expansion:Managed service providers in Japan are introducing subscription-based infrastructure leasing that transfers operational risk from capital-constrained buyers to vendor financing arms.
Industry Challenges
- Multi-hypervisor skill fragmentation:Enterprise IT teams struggle to maintain operational proficiency across VMware, Hyper-V, and KVM environments simultaneously, complicating platform standardization decisions.
- SOC 2 Type II audit timelines:Extended certification cycles for service organization control reporting delay customer onboarding for converged infrastructure vendors targeting financial services and healthcare verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converged Infrastructure Management Market |
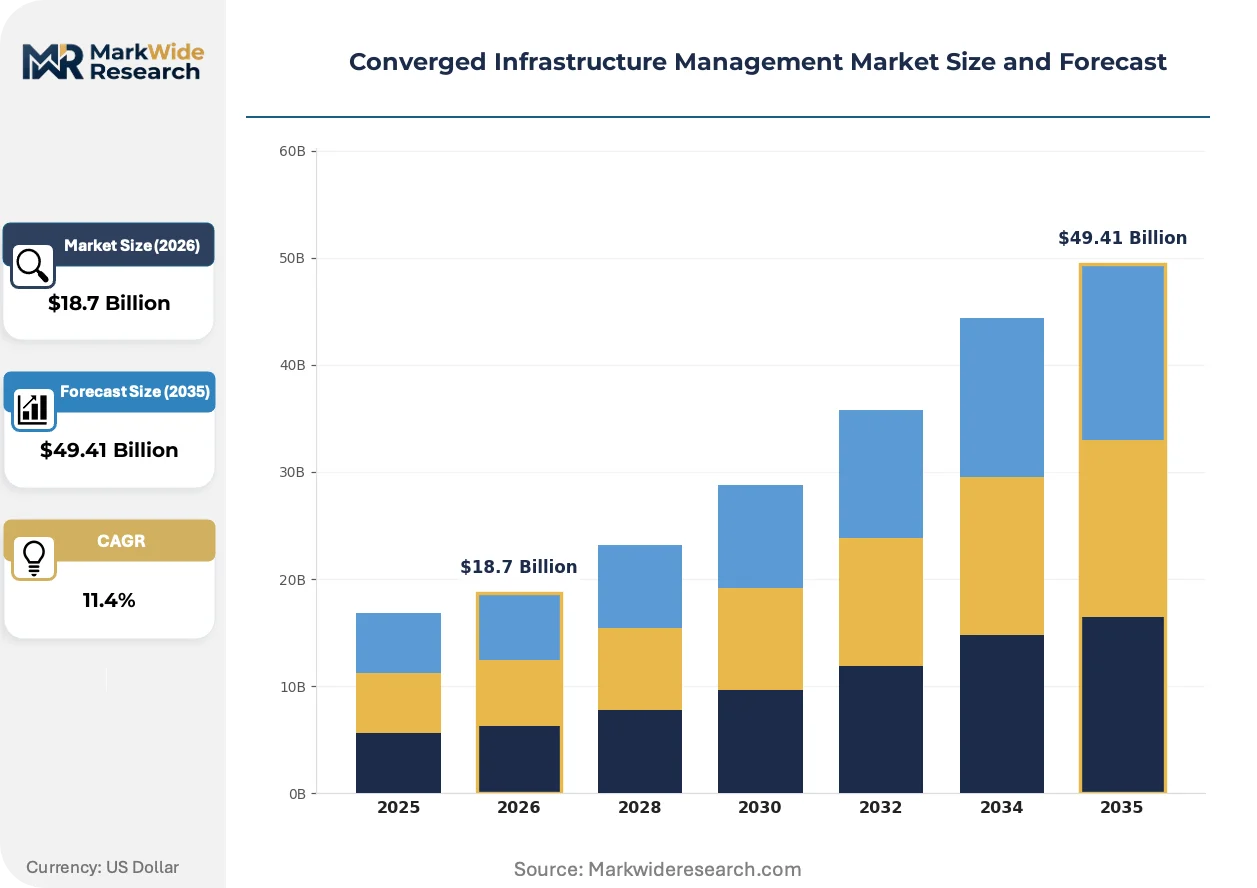
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyper-Converged Infrastructure, Converged Infrastructure, Integrated Systems, Modular Systems End User: Large Enterprises, SMEs, Managed Service Providers, Cloud Service Providers Deployment: On-Premises, Hybrid, Public Cloud, Private Cloud Service Type: Support Services, Consulting Services, Integration Services, Maintenance Services |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Cisco Systems, Nutanix, IBM Corporation, VMware, Huawei Technologies, NetApp, Scale Computing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converged Infrastructure Management Market Emerging Trajectories
Software abstraction layers are collapsing traditional hardware boundaries, enabling resource pooling that treats compute, storage, and networking as fungible capacity rather than fixed assets. This architectural shift is redrawing competitive lines between hardware-centric and software-native vendors.
Composable disaggregation is virtualizing physical infrastructure into logical resource pools that applications consume through API-driven orchestration. Large enterprises with variable workload patterns are piloting these architectures to eliminate stranded capacity during demand troughs. The approach is virtualizing the traditional server-storage-networking procurement bundle into independently scalable service tiers.
The EU CSRD sustainability disclosure requirements are mandating granular energy consumption reporting for data center operations. Deployments across Germany and France must now embed power monitoring at the workload level to satisfy scope 3 emissions tracking obligations. Vendors are responding with integrated telemetry that feeds directly into corporate ESG reporting systems.
Buyers are consolidating vendor relationships around full-stack accountability models that assign single-source responsibility for performance, security patching, and lifecycle management. This pattern is displacing the historical practice of negotiating separate maintenance contracts for servers, storage arrays, and network switches. The shift is most pronounced among United States healthcare systems navigating HIPAA technical safeguard complexity.
Converged Infrastructure Management Market Segmentation
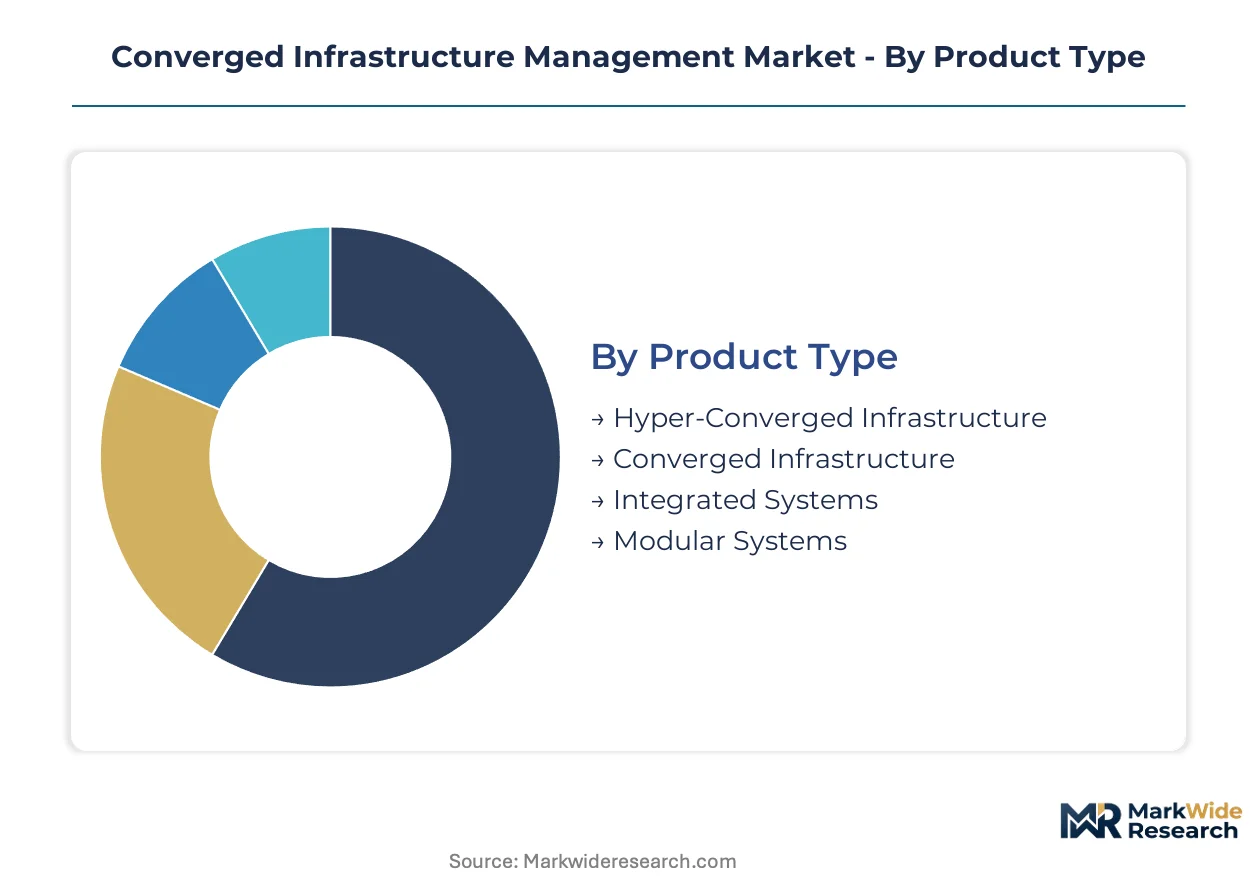
Converged infrastructure procurement patterns diverge sharply across workload characteristics, operational maturity, and capital constraints. Understanding these segment boundaries clarifies why vendors maintain parallel product architectures rather than forcing unified platforms across incompatible buyer profiles.
Product Type:
Software-defined abstraction layers now span the full hardware integration spectrum, from fully disaggregated nodes to pre-engineered appliance stacks.
- Hyper-Converged Infrastructure:Scale-out nodes collapse compute and storage into x86 building blocks managed through a single control plane. Cloud Service Providers in the United States deploy these at cell tower aggregation points for 5G network slicing and edge data sovereignty.
- Converged Infrastructure:Pre-validated server-storage-networking bundles reduce integration risk while preserving some hardware separation for specialized tuning. German financial institutions favor these configurations under GDPR data localization mandates that require jurisdictional control over primary transaction processing.
- Integrated Systems:Factory-assembled appliance stacks accelerate deployment timelines for organizations lacking deep engineering benches. Japanese healthcare systems leverage these to satisfy HIPAA-equivalent technical safeguard complexity without building in-house integration expertise.
- Modular Systems:Disaggregated chassis designs permit independent refresh cycles for compute, storage, and networking sleds. Telecom operators across Asia-Pacific pilot these architectures to eliminate stranded capacity during demand troughs in variable workload environments.
Established volume favors Hyper-Converged Infrastructure; emerging adoption favors Modular Systems.
End User:
Buyer sophistication and procurement flexibility create four distinct commercial entry points for converged platform vendors.
- Large Enterprises:Multi-tenant workload consolidation drives demand for policy-driven resource pools with automated lifecycle management APIs. These organizations negotiate full-stack accountability contracts that assign single-source responsibility for performance, security patching, and lifecycle management.
- SMEs:Capital constraints and skill scarcity push smaller buyers toward subscription-based infrastructure leasing. Equipment-as-a-service channels in Japan transfer operational risk from these buyers to vendor financing arms with consumption-based pricing.
- Managed Service Providers:Multi-tenant hosting operations require standardized platforms that support rapid tenant onboarding. These intermediaries concentrate procurement in configurations with embedded SOC 2 Type II compliance telemetry to accelerate customer certification timelines.
- Cloud Service Providers:Sovereign cloud buildouts and edge colocation requirements position this category as the steepest expansion trajectory. Providers across Germany deploy on-premises converged systems to maintain jurisdictional control over sensitive government and financial data under proposed EU Data Act provisions.
Large Enterprises anchor current revenue concentration; Cloud Service Providers command the fastest forward growth.
Deployment:
Infrastructure location strategy now follows data gravity and regulatory boundary lines rather than simple cost optimization.
- On-Premises:Retained for workloads with strict latency requirements, legacy application dependencies, or sovereign data mandates. German automotive manufacturers maintain these deployments for industrial control systems that cannot tolerate public cloud connectivity dependencies.
- Hybrid:Bursting architectures that retain sensitive processing on-premises while leveraging public infrastructure for variable demand. United States healthcare systems navigate HIPAA technical safeguard complexity through these models that partition protected health information from scalable compute tiers.
- Public Cloud:Native IaaS offerings capture cloud-native application development pipelines that might otherwise deploy on-premises. These configurations face substitution pressure from hyperscaler converged-equivalent services that reduce infrastructure ownership burdens.
- Private Cloud:Dedicated single-tenant environments delivering public-cloud operational models within controlled facilities. Japanese financial institutions deploy these to satisfy METI guidance on critical infrastructure protection while maintaining cloud-native development velocity.
Hybrid deployments capture expanding margin pools; Private Cloud configurations gain share in regulated verticals.
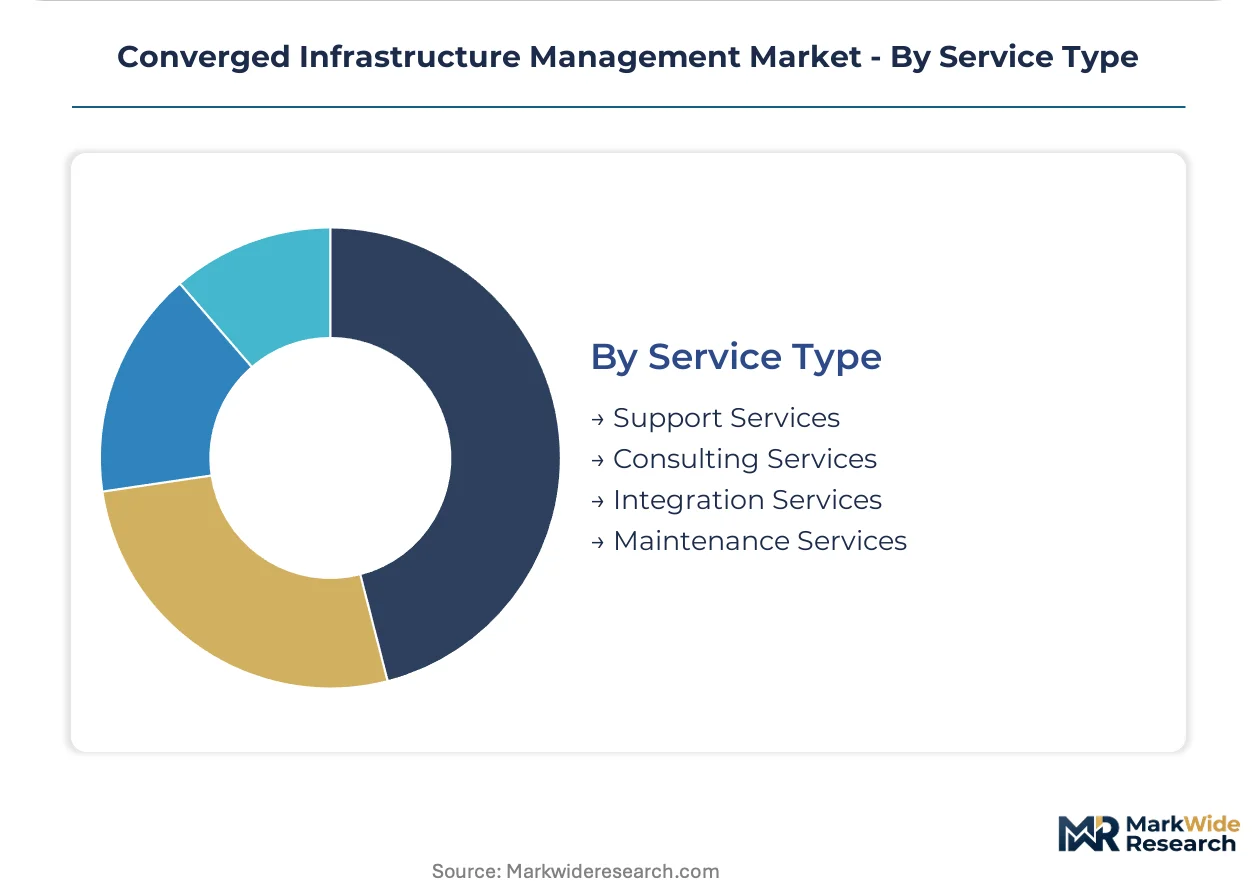
Service Type:
Revenue attachment rates vary with buyer internal capabilities and platform complexity.
- Support Services:24/7 technical assistance and break-fix coverage essential for production workload continuity. These services generate recurring revenue streams that stabilize vendor financial performance across hardware refresh cycles.
- Consulting Services:Architecture design and migration planning for three-tier consolidation projects. Demand concentrates among United States enterprises restructuring data center footprints around software-defined platforms.
- Integration Services:Professional implementation of multi-vendor or customized configurations. Mid-sized buyers lacking software-defined networking expertise rely on these services to compress deployment timelines.
- Maintenance Services:Proactive hardware replacement, firmware management, and security patch orchestration. Full-stack accountability trends are displacing separate maintenance contracts for servers, storage arrays, and network switches in favor of unified service tiers.
Support Services dominate current attachment revenue; Consulting Services expand fastest with legacy modernization waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The converged infrastructure management sector exhibits pronounced trade asymmetry, with the United States and Germany running substantial technology export surpluses while Japan and emerging Asian markets remain net importers of integrated systems.
United States
Cloud service providers and telecom operators are driving procurement of hyper-converged nodes for edge colocation and 5G network slicing deployments. FCC guidelines on data center energy reporting mandate granular power consumption disclosure that shapes vendor qualification pathways. Northern Virginia's data center corridor hosts the densest concentration of converged infrastructure deployments, with operators consolidating three-tier architectures into software-defined platforms.
Germany
Automotive manufacturers and financial institutions are replacing legacy siloed systems to satisfy GDPR data localization requirements and proposed EU Data Act provisions. EU CSRD sustainability disclosure mandates require scope 3 emissions tracking that embeds power monitoring at the workload level. Frankfurt's financial services cluster anchors sovereign cloud infrastructure buildouts that retain jurisdictional control over sensitive transaction processing.
Japan
Healthcare systems and capital-constrained mid-sized enterprises are adopting subscription-based infrastructure leasing through equipment-as-a-service channels. METI guidance on critical infrastructure protection shapes procurement criteria for private cloud configurations. Tokyo's metropolitan healthcare networks leverage factory-assembled appliance stacks to satisfy technical safeguard complexity without building in-house integration expertise.
China
Telecom operators and cloud service providers are deploying integrated networking-compute bundles tailored to domestic sovereignty requirements and edge processing mandates. MIIT standards on information security management accelerate replacement of foreign-origin platforms with auditable domestic alternatives. Shenzhen's technology corridor concentrates GPU-accelerated compute clusters for enterprise artificial intelligence development pipelines.
United Kingdom
Managed service providers and financial services firms are consolidating vendor relationships around full-stack accountability models that assign single-source responsibility for lifecycle management. NIST-aligned cybersecurity frameworks mandate continuous monitoring capabilities that reshape platform selection criteria. London's fintech cluster pilots composable disaggregation architectures to eliminate stranded capacity during variable demand patterns.
Converged Infrastructure Management Market Vendor Landscape
On the supply side, the industry is consolidating around full-stack accountability models that displace historical multi-vendor maintenance contracting. Tiered competitive positioning separates hardware-centric incumbents with captive supply chains from software-native challengers pursuing disaggregation strategies. Three archetypes dominate: integrated appliance manufacturers, software-defined abstraction specialists, and telecom-focused systems bundlers. Competitive intensity centers on consumption-based pricing restructuring and cross-cloud orchestration capability depth.
Within the integrated appliance tier, Dell Technologies and Hewlett Packard Enterprise exemplify full-stack accountability positioning, while Nutanix occupies a position representing software-centric disaggregation that reduces hardware lock-in. Huawei Technologies anchors the Asia-Pacific systems bundling archetype through integrated networking-compute offerings.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Nutanix |
| IBM Corporation |
| VMware |
| Huawei Technologies |
| NetApp |
| Scale Computing |
| Others |
Supply Flow & Price Mechanics
Taiwan's advanced semiconductor fabrication clusters anchor component availability for converged infrastructure manufacturers, with foundry allocation constraints directly translating into tiered pricing power across server-storage-networking bundles. Memory and processor supply concentration in Taiwanese and South Korean facilities creates asymmetric negotiation leverage that downstream vendors pass through as cost-plus escalation clauses in enterprise procurement contracts.
Pricing Analysis
Cloud service providers anchor subscription-based pricing structures across the converged infrastructure landscape. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 27001 certification grade and after-sales service bundling intensity. Cost compression in mid-market configurations is intensifying because hyperscaler IaaS offerings capture price-sensitive cloud-native workloads. SMEs demonstrate highest price sensitivity due to capital constraints, while large enterprises with sovereign data mandates exhibit lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities from South Korean memory manufacturers shape working capital dynamics for systems integrators. Component sourcing concentrates in Taiwan, South Korea, and China for advanced semiconductors and flash storage. Raw material dependencies span silicon wafers, DRAM modules, and NVMe controllers. Single-source vulnerability around EUV lithography equipment creates geopolitical disruption risk. Distribution runs through direct enterprise sales teams and managed service provider channels with equipment-as-a-service financing overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The converged infrastructure management market is entering a cyclical recovery phase driven by enterprise three-tier architecture refresh cycles compressing from five-year to three-year intervals.
For Market Incumbents: Insulate installed base relationships through full-stack accountability contracting that bundles lifecycle management, security patching, and performance guarantees into unified service tiers. Deepen backward integration into software-defined networking stacks to reduce VMware dependency as multi-hypervisor environments fragment operational proficiency. Prioritize SOC 2 Type II certification investment to accelerate financial services customer onboarding timelines.
For New Entrants and Emerging Players: Pursue sovereign cloud infrastructure deployments in Germany where EU Data Act provisions and GDPR localization mandates create procurement urgency for jurisdictional control solutions. Target equipment-as-a-service channels in Japan where METI guidance and capital-constrained healthcare systems favor subscription-based operational risk transfer. Lead with API-driven orchestration depth as the primary go-to-market angle against hardware-centric incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-native challengers with disaggregation architectures over integrated appliance manufacturers facing margin compression from consumption-based pricing restructuring. Long-term viability across the analysis window hinges on cross-cloud orchestration capability depth and vendor API openness. Acquisition target archetype: specialists in composable infrastructure with RDMA networking and GPU-accelerated compute integration. Signal to watch: hyperscaler converged-equivalent service launches as substitution pressure inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumption-Based Pricing Restructuring | Shifts enterprise procurement from perpetual licensing to subscription models that align vendor revenue with customer utilization patterns. |
| API-Driven Cross-Cloud Orchestration | Enables workload portability between on-premises converged systems and hyperscaler IaaS without operational re-engineering. |
| Sovereign Cloud Infrastructure Buildout | Satisfies German GDPR data localization and proposed EU Data Act jurisdictional control requirements for sensitive government workloads. |
| Edge Colocation Node Deployment | Supports United States telecom operators' 5G network slicing and low-latency sovereign data processing at cell tower aggregation points. |
| Integrated ESG Telemetry Embedding | Feeds EU CSRD-mandated scope 3 emissions tracking directly into corporate sustainability reporting systems for German and French deployments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center architects, IT procurement officers, platform engineers, and managed service provider operations leads. Secondary validation drew from SEC filings of converged infrastructure vendors, hyperscaler capex disclosures, ISO certification registries, and EU regulatory filings. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against aggregate enterprise IT spending benchmarks anchored forecast integrity.
Calibration against historical refresh cycle patterns and technology substitution elasticities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled span product type, end user category, deployment location, and service attachment rate, with additional granularity on compliance certification tier. CAGRs were derived from logistic diffusion curves fitted to enterprise adoption saturation levels. Industry-specific forecast inputs include 5G network slicing deployment timelines and EU Data Act implementation progress.
Macroeconomic conditions sit as an overlay; deviation in enterprise capital expenditure cycles or semiconductor allocation constraints would shift the trajectory. Forecasts reflect documented assumptions around refresh cycle compression rates and sovereign cloud buildout pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Malaysia Data Center Rack Market