
 Europe Data Center Server Market | 2026-2036
Europe Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Server Market Insights
REACH is expanding compliance burdens for server component sourcing and end-of-life material handling across European supply chains. Dell Technologies leverages its direct manufacturing relationships to control component traceability. Hewlett Packard Enterprise anchors its European operations through localized assembly and circular design programs. Schneider Electric differentiates with integrated power and cooling systems that streamline facility certification.
A data center server is a high-availability computing platform engineered for continuous operation, typically featuring redundant power supplies, error-correcting memory, and thermal designs rated for ambient temperatures up to 35°C. These systems process transactional workloads, virtualization layers, and artificial intelligence inference tasks for enterprise and service-provider environments. Rack servers occupy the dominant volume position across European deployments owing to standardization in hyperscale and colocation facilities. Blade servers represent a maturing architecture in financial institutions where density and shared infrastructure management offset premium chassis costs. GPU-based technology segments are capturing accelerated growth as European sovereign AI initiatives and regulated industry workloads expand training and inference capacity.
EMA energy efficiency guidelines, EU Green Deal carbon accounting rules, and national building codes in Germany and France are shaping server procurement specifications and facility power usage effectiveness thresholds. The CSRD disclosure requirements are extending reporting obligations to embodied carbon in hardware supply chains. Stakeholders must monitor how forthcoming EU AI Act infrastructure requirements intersect with existing Ecodesign regulations to determine compliant server configurations.
Market Dynamics
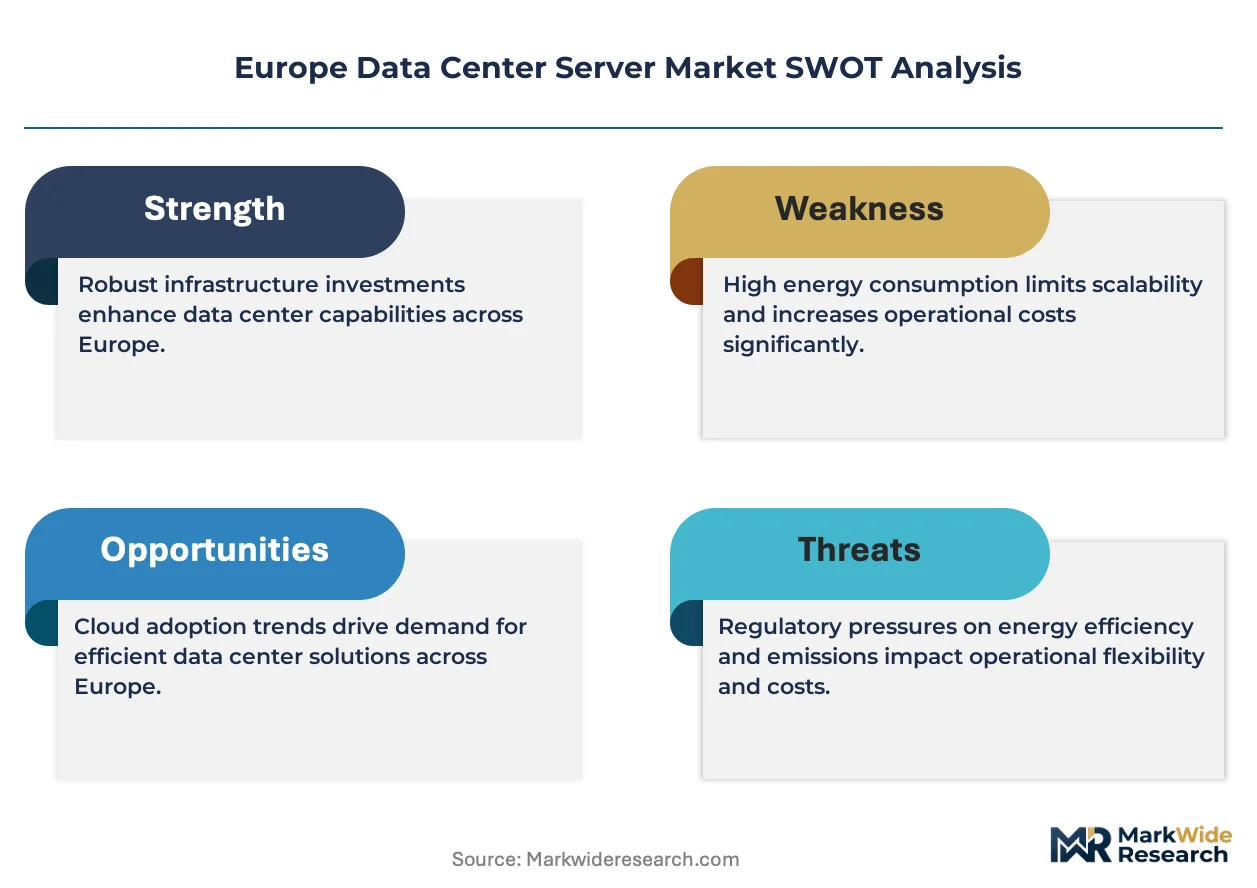
Hyperscale cloud operators are consolidating capacity across Germany, France, and the Netherlands while EU Green Deal carbon accounting rules force facility operators to redesign power and cooling architectures. This dual pressure is compressing procurement timelines and elevating energy efficiency specifications above raw compute metrics.
Growth Catalysts
- Sovereign AI mandates:National governments across France and Germany are funding domestic inference infrastructure to retain data sovereignty, creating dedicated procurement channels outside commercial cloud frameworks.
- CSRD disclosure requirements:Corporate sustainability reporting obligations are extending to embodied carbon in hardware supply chains, accelerating replacement cycles for legacy equipment.
- Liquid cooling adoption:High-density GPU deployments are driving facility operators to retrofit existing infrastructure with direct-to-chip thermal management systems.
Market Restraints
- Power grid saturation:Amsterdam and Frankfurt metropolitan clusters face connection queue delays of 24-36 months for new facility capacity.
- Critical mineral concentration:Advanced packaging substrates and high-bandwidth memory modules depend on concentrated Asian supply bases with limited European alternatives.
- F-Gas Regulation phase-down:Conventional refrigerants face quota reductions, forcing cooling system redesigns before next-generation alternatives achieve scale.
Strategic Opportunities
- Edge node expansion:Tier-2 cities across Poland and Spain remain underpenetrated for low-latency inference workloads serving manufacturing and autonomous systems.
- Heat reuse integration:District heating network connections in Nordic countries offer revenue streams from waste heat recovery, offsetting facility operating costs.
- Modular prefabrication:Factory-integrated power and cooling modules are compressing deployment timelines for colocation operators facing urgent capacity demands.
Industry Challenges
- Specialized technician scarcity:Liquid cooling infrastructure and high-voltage electrical work require certifications that outpace regional training program output.
- Legacy facility retrofit complexity:Existing raised-floor facilities face structural load limits and clearance constraints that prevent direct-to-chip cooling adoption without comprehensive redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Server Market |
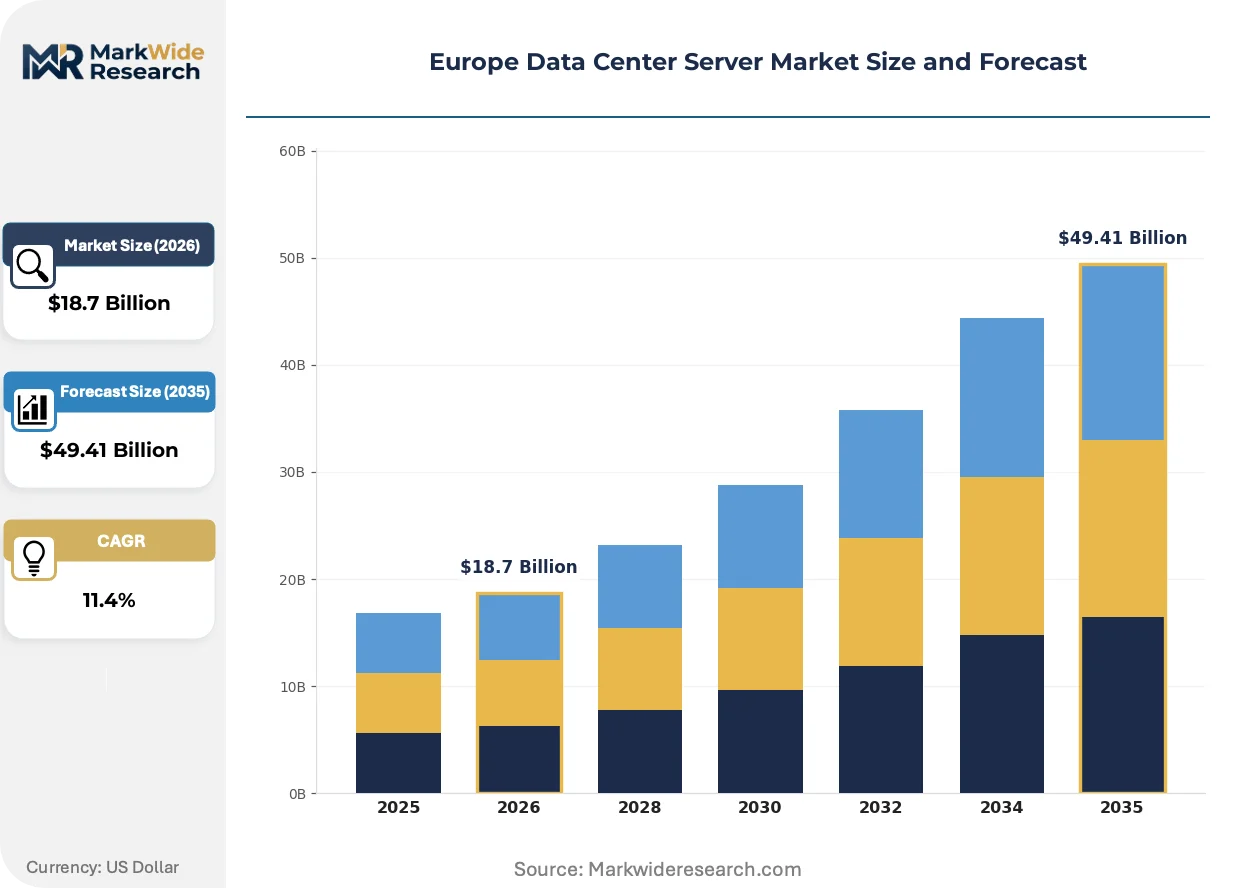
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Hyper-Converged Infrastructure End User: Telecommunications, IT Service Providers, Financial Institutions, Government Agencies Deployment: On-Premises, Colocation, Cloud-Based, Hybrid Technology: X86, ARM, FPGA, GPU |
| Companies Covered | Cisco Systems, IBM, Dell Technologies, Vertiv Group, Schneider Electric, Hewlett Packard Enterprise, Fujitsu, Eaton Corporation, Lenovo Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Server Market Trends and Innovations
Compute infrastructure across European facilities is undergoing architectural transformation as thermal density limits and energy accounting rules force abandonment of conventional air-cooled designs. Three converging developments are compressing procurement and deployment models.
Direct liquid cooling is consolidating dominance in new hyperscale builds as heat flux densities from AI training clusters exceed 50 kilowatts per rack. Facility operators in the Netherlands and Germany are specifying cold-plate or immersion systems as baseline requirements rather than premium options. This technology compression is displacing traditional CRAH unit procurement and reshaping mechanical contractor specializations.
EU AI Act infrastructure requirements are intersecting with existing Ecodesign regulations to create compound compliance burdens for server configurations. Manufacturers must now document training data provenance and inference energy intensity alongside conventional efficiency metrics. Financial services and healthcare deployments in France face the most acute certification timeline pressures as dual frameworks activate simultaneously.
Enterprise procurement patterns are fragmenting between reserved cloud capacity and owned infrastructure as sovereign data requirements harden. Regulated industries in Germany are reviving captive facility strategies abandoned during the 2015-2020 cloud migration wave. This behavioral pivot is visible most acutely in automotive and defense supply chains where cross-border data restrictions override cost optimization logic.
Europe Data Center Server Market Segmentation
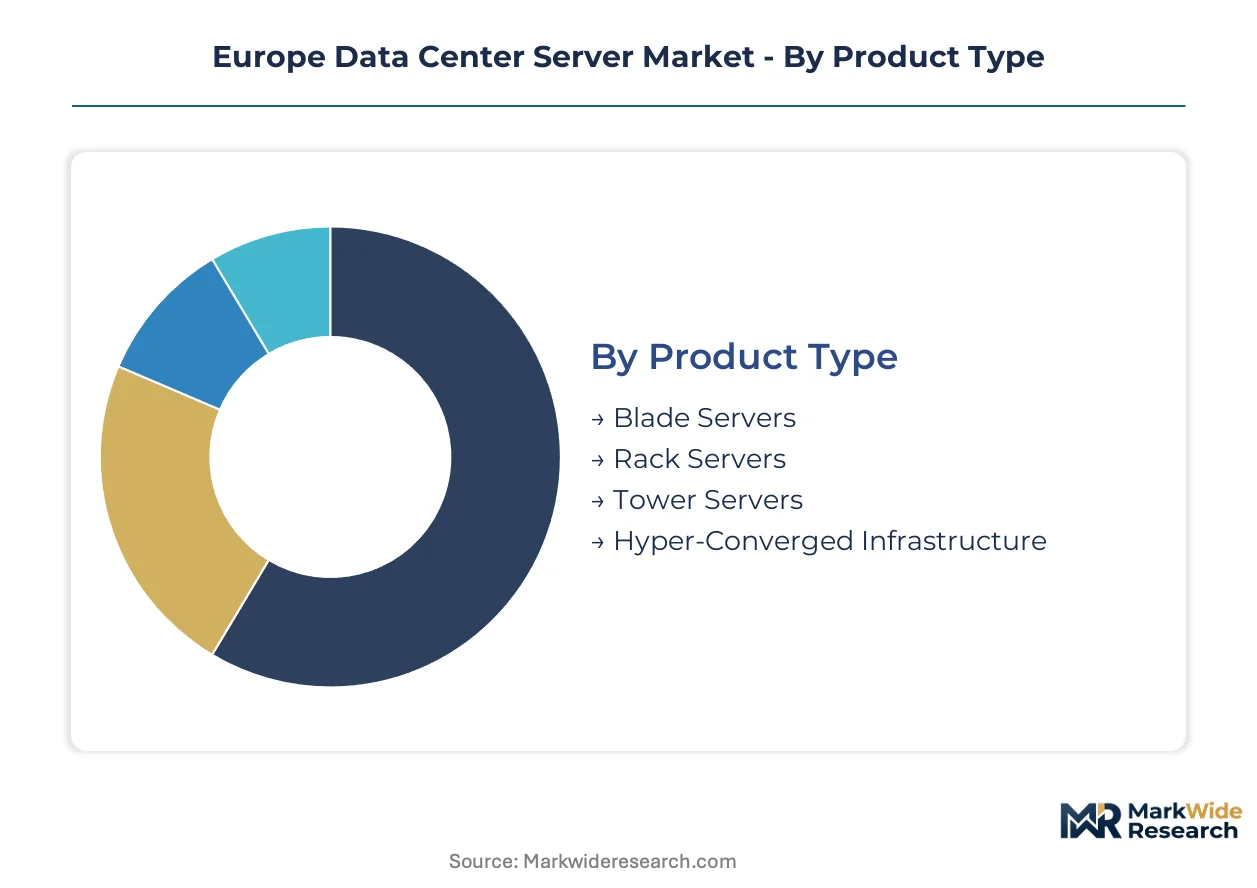
Server procurement across Europe fragments across four critical dimensions: physical form factor, customer vertical, infrastructure ownership model, and processor architecture. Each axis carries distinct regulatory, thermal, and commercial constraints that reshape vendor positioning and facility design priorities.
Product Type:
Integration depth varies sharply—rack and blade systems dominate standalone hyperscale deployments, while hyper-converged platforms embed compute within software-defined storage layers.
- Rack Servers:Standardized 19-inch chassis accommodate 1U to 4U configurations with hot-swappable power and cooling modules. Demand concentrates in Frankfurt and Amsterdam colocation facilities where hyperscale operators prioritize interoperability and rapid rack-scale deployment.
- Blade Servers:Shared chassis infrastructure consolidates networking, storage, and management controllers across multiple server nodes. Financial institutions in London and Paris maintain procurement preference for blade architectures where density premiums offset chassis costs through reduced cabling and unified management overhead.
- Tower Servers:Vertical chassis configurations suit branch office and small facility deployments with limited rack infrastructure. Regional German automotive suppliers deploy tower units for localized quality control and sensor data processing.
- Hyper-Converged Infrastructure:Software-defined platforms integrate compute, storage, and virtualization in pre-validated appliance form factors. Dutch healthcare networks favor HCI for rapid clinic-level deployment without specialized infrastructure teams.
Volume placements concentrate in rack servers; the faster expansion belongs to hyper-converged infrastructure.
End User:
Customer sophistication tiers separate specification-heavy regulated verticals from latency-sensitive communications infrastructure.
- IT Service Providers:Multi-tenant operators provision white-label capacity for enterprise customers across tiered SLA frameworks. Facilities in Frankfurt and Dublin face compressed procurement cycles as cloud repatriation demands accelerate.
- Financial Institutions:Basel III operational resilience mandates and MiFID II latency requirements drive procurement of fault-tolerant configurations with sub-microsecond failover. Paris-based clearinghouses specify liquid-cooled racks for derivatives risk calculation clusters.
- Telecommunications:Edge computing rollouts for 5G core networks and Open RAN virtualization demand ruggedized server platforms. German network operators deploy disaggregated cell site gateways across Bavaria and North Rhine-Westphalia.
- Government Agencies:Sovereign cloud mandates and classified data handling requirements restrict procurement to security-certified domestic supply chains. French defense and interior ministries operate captive facilities outside commercial cloud frameworks.
IT service providers anchor current procurement volumes; government agencies are climbing the fastest as sovereign infrastructure funding accelerates.
Deployment:
Ownership economics and data residency requirements fragment infrastructure strategies across capital expenditure and operational expenditure models.
- Colocation:Third-party facility operators provide power, cooling, and physical security while customers retain server ownership. Amsterdam and Frankfurt metropolitan clusters face 24-36 month connection queues that compress deployment timelines for available capacity.
- On-Premises:Captive facility ownership persists in German automotive and defense supply chains where cross-border data restrictions override cloud cost advantages. Legacy raised-floor facilities constrain direct liquid cooling retrofits without structural reinforcement.
- Cloud-Based:Hyperscale reserved capacity and serverless compute models dominate variable workload profiles. French AI startups route training pipelines through regional cloud zones to satisfy EU AI Act data provenance documentation.
- Hybrid:Orchestrated workloads span owned infrastructure and public cloud with policy-driven data placement. Dutch pharmaceutical manufacturers split clinical trial data across on-premises validation environments and cloud analytics sandboxes.
Colocation absorbs the largest deployment share; hybrid architectures are gaining share fastest as regulated industries partition sensitive from general-purpose workloads.
Technology:
Instruction set architecture and accelerator integration define thermal design power ceilings and software ecosystem compatibility.
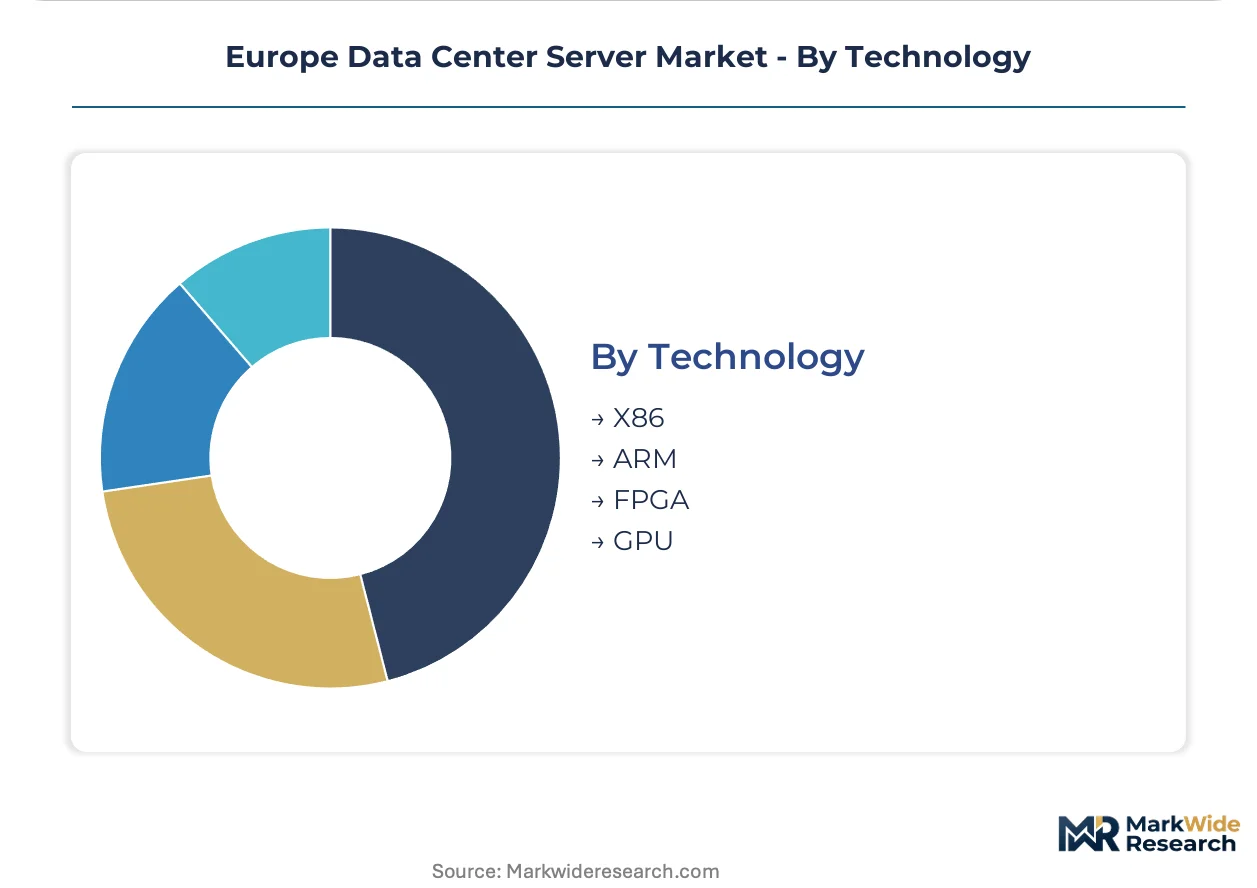
- X86:Intel and AMD processor platforms dominate enterprise virtualization and legacy application hosting. German manufacturing ERP consolidation projects specify X86 for SAP HANA certification compatibility.
- GPU:NVIDIA and AMD accelerator architectures enable parallel training and inference for sovereign AI initiatives. French national AI research clusters deploy GPU-heavy configurations for large language model development under domestic data custody rules.
- ARM:Reduced instruction set designs from Ampere and emerging cloud-native silicon optimize performance per watt for web-scale workloads. Cloud operators in Ireland evaluate ARM for cold storage and containerized microservices.
- FPGA:Field-programmable gate arrays accelerate fixed-function workloads including encryption, compression, and network packet processing. Financial exchanges in London deploy FPGA for market data feed normalization.
X86 retains dominant volume placement; GPU-based configurations show the steepest expansion trajectory as European AI infrastructure funding compounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale operators concentrate new capacity across three metropolitan clusters. Frankfurt, Amsterdam, and Paris absorb the majority of power allocation approvals as sovereign AI mandates redirect investment flows.
Germany
Automotive supply chains and defense contractors are reviving captive data center strategies abandoned during the 2015-2020 cloud migration period. The EU AI Act intersects with national IT security regulations to mandate domestic data custody for classified workloads. Frankfurt's metropolitan cluster faces 24-36 month grid connection queues that compress deployment timelines for available colocation capacity.
Netherlands
Hyperscale operators specify direct liquid cooling as baseline infrastructure rather than premium configuration for new builds. The F-Gas Regulation phase-down forces cooling system redesigns before next-generation refrigerants achieve commercial scale. Amsterdam's power grid saturation has triggered moratoriums on new facility approvals, redirecting investment toward Eindhoven and Groningen sub-markets.
France
National AI research clusters deploy GPU-heavy configurations for large language model development under domestic data custody rules. ANSM and CNIL oversight extends to healthcare and financial infrastructure certification timelines. Paris-based clearinghouses specify liquid-cooled racks for derivatives risk calculation clusters under MiFID II latency requirements.
United Kingdom
Financial exchanges deploy FPGA-accelerated platforms for market data feed normalization and sub-microsecond failover. Basel III operational resilience mandates drive procurement of fault-tolerant configurations across London clearinghouses. Slough and Docklands facilities remain the primary concentration for latency-sensitive trading infrastructure.
Ireland
Cloud operators evaluate ARM-based silicon for cold storage and containerized microservices to optimize performance per watt. CSRD disclosure requirements accelerate replacement cycles for legacy equipment across Dublin metropolitan facilities. Cork and Limerick edge nodes remain underpenetrated for low-latency inference workloads serving manufacturing supply chains.
Europe Data Center Server Market Competitive Landscape
American technology conglomerates anchor the premium systems tier; European industrial specialists hold integrated power and cooling positions. The vendor base separates into three strategic archetypes: full-stack infrastructure providers, component-integrated power specialists, and regional assembly operators. Consolidation pressure intensifies as facility operators seek single-source accountability for thermal and electrical performance. Competitive moves concentrate on vertical integration into cooling hardware and strategic partnerships with liquid cooling contractors.
Within the full-stack infrastructure tier, Dell Technologies and Hewlett Packard Enterprise represent integrated compute-platform positioning. Schneider Electric occupies a distinct position bridging power distribution and thermal management systems. These three anchors exemplify divergent responses to EU Green Deal compliance burdens—direct manufacturing control, localized circular design programs, and facility certification streamlining respectively.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM |
| Dell Technologies |
| Vertiv Group |
| Schneider Electric |
| Hewlett Packard Enterprise |
| Fujitsu |
| Eaton Corporation |
| Lenovo Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between liquid-cooled AI infrastructure and conventional air-cooled enterprise systems splits both procurement economics and supplier networks across European data center markets. Premium tiers command substantial markups for direct-to-chip thermal solutions that satisfy EU Green Deal efficiency mandates, while commodity rack configurations face margin compression as hyperscale buyers consolidate volume around standardized SKUs.
Pricing Analysis
Volume placements concentrate in rack servers where hyperscale procurement drives aggressive unit economics, while GPU-heavy configurations sustain margin premiums through specialized thermal engineering and sovereign AI certification requirements. Price differentiation hinges on energy efficiency tiering under Ecodesign regulations and liquid cooling integration depth. Cost compression in standard rack configurations intensifies as Frankfurt and Amsterdam colocation operators negotiate multi-year framework agreements. Financial institutions exhibit lowest price sensitivity due to MiFID II latency mandates, while regional IT service providers face acute budget constraints in tier-2 city deployments.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg orchestrate hub-and-spoke patterns for server component logistics across Western European markets. Manufacturing concentrates in Taiwan, China, and Malaysia for advanced packaging substrates and high-bandwidth memory modules. Raw material dependencies span gallium nitride for power electronics, cobalt-bearing substrates, and specialized cooling fluids facing F-Gas Regulation quota restrictions. Single-source vulnerability in GPU accelerator supply chains creates procurement risk for European AI infrastructure buildouts. Distribution runs through authorized distributor networks with direct OEM relationships for hyperscale accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid connection queues stretching 24-36 months in Frankfurt and Amsterdam metropolitan clusters constrain new capacity supply, propping pricing power for existing colocation operators with secured power allocations.
For Market Incumbents: Extend liquid cooling certification portfolios to capture sovereign AI infrastructure tenders in France and Germany before EU AI Act documentation requirements harden. Deepen backward integration into power distribution hardware to streamline facility certification timelines threatened by CSRD disclosure expansion. Prioritize technician training partnerships with Dutch and German vocational institutes to address specialized labor scarcity constraining deployment velocity. For New Entrants and Emerging Players: Direct-to-hyperscale digital procurement channels offer lower friction entry than established distributor relationships dominated by Dell Technologies and Hewlett Packard Enterprise. Target edge node deployments across Polish and Spanish manufacturing corridors where latency requirements for autonomous systems outpace incumbent coverage. Lead with modular prefabricated power and cooling units that compress deployment timelines for operators facing urgent capacity demands. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-stack infrastructure providers seeking single-source accountability for thermal and electrical performance. Long-term viability favors vendors with captive liquid cooling technology and established European assembly footprints. Monitor Amsterdam power grid moratorium enforcement as the critical inflection signal for sub-market redirection toward Eindhoven and Groningen.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Acquisition | Captures premium positioning as EU Green Deal mandates displace conventional air-cooled designs. |
| Regional Assembly Footprint Expansion | Satisfies CSRD embodied carbon disclosure requirements through localized circular design programs. |
| Technician Training Partnership | Addresses certification bottlenecks constraining direct-to-chip cooling retrofit timelines. |
| Heat Reuse Network Integration | Unlocks district heating revenue streams in Nordic markets offsetting facility operating costs. |
| Sovereign Cloud Certification Investment | Secures procurement preference from French defense and German automotive captive facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Data Center Server Market analysis. Primary interviews with data center facility operators, colocation procurement managers, liquid cooling system integrators, and hyperscale cloud infrastructure planners informed demand-side validation. Secondary sources included EMA energy efficiency guidelines, EU AI Act draft infrastructure requirements, national building code filings from Germany and France, and hyperscaler capital expenditure disclosures. Bottom-up server shipment modeling triangulated against top-down facility power allocation tracking across Frankfurt, Amsterdam, and Paris metropolitan clusters.
Granularity-level modeling distinguished rack, blade, tower, and hyper-converged form factors across X86, GPU, ARM, and FPGA technology segments. Deployment mode segmentation captured colocation, on-premises, cloud-based, and hybrid ownership structures. End-user verticals included IT service providers, financial institutions, telecommunications operators, and government agencies. CAGRs derived from polynomial trend fitting against historical shipment data and facility construction pipeline tracking. Forecast inputs incorporated EU Green Deal carbon accounting rule implementation timelines and sovereign AI funding allocation announcements.
The model holds under sustained grid connection queue durations and stable F-Gas Regulation phase-down schedules; deviation in power infrastructure permitting velocity or accelerated refrigerant quota reductions would shift capacity deployment timelines. Forecasts reflect documented assumptions regarding hyperscale expansion commitments and national AI infrastructure funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Switzerland Data Center Market