
 Netherlands Data Center Power Market | 2026-2036
Netherlands Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Power Market Insights
The EU Green Deal is shifting procurement priorities across Dutch data center operators toward carbon-neutral power architectures. Schneider Electric leverages its integrated microgrid portfolio to anchor large-scale deployments in North Holland. ABB sustains technology leadership through high-efficiency medium-voltage UPS systems purpose-built for hyperscale facilities. Siemens competes on digital twin integration that optimizes real-time power distribution across multi-tenant campuses.
Data center power encompasses the generation, conditioning, distribution, and backup infrastructure that ensures continuous electrical supply to server halls, with systems typically engineered for 99.999% uptime through redundant UPS strings and diesel rotary uninterruptible power supplies. The primary commercial purpose centers on eliminating downtime-induced revenue loss while enabling density scaling beyond 50 kW per rack. Grid-sourced power dominates installed base value, though renewable power is accelerating fastest as offtake agreements with Dutch wind and solar farms multiply. Liquid cooling is displacing air cooling in the above 10 MW capacity tier, where thermal loads exceed conventional HVAC economics and margin pools deepen for integrated power-thermal vendors.
The Netherlands Authority for Consumers and Markets (ACM) enforces grid connection queue transparency, while the EU F-Gas Regulation phases down fluorinated coolant use in favor of natural refrigerant alternatives. BIS certification requirements for imported electrical equipment add compliance layers for non-EU suppliers entering the Dutch market. Stakeholders must monitor whether Amsterdam's moratorium on new hyperscale permits spreads to Rotterdam and Eindhoven, reshaping deployment geography.
Market Dynamics
The EU Green Deal is compressing procurement timelines for carbon-neutral power architectures across Dutch data center operators, forcing rapid reconfiguration of electrical infrastructure sourcing strategies ahead of 2030 compliance deadlines.
Growth Catalysts
- Offshore Wind Procurement:Dutch wind farms in the North Sea are securing long-term power purchase agreements with hyperscale operators seeking 24/7 renewable matching.
- Liquid Cooling Adoption:Thermal loads exceeding 50 kW per rack are driving integrated power-thermal vendor penetration in facilities above 10 MW capacity.
- Amsterdam Metropolitan Concentration:The Randstad corridor maintains dense fiber connectivity and skilled labor pools that attract successive waves of cloud provider investment.
Market Restraints
- Grid Connection Queues:The Netherlands Authority for Consumers and Markets enforces transparency rules that do not accelerate physical infrastructure buildout timelines.
- Copper and Rare Earth Volatility:Medium-voltage switchgear and transformer manufacturing faces input cost pressure from concentrated Chilean and DRC supply channels.
- F-Gas Phase-Down:The EU F-Gas Regulation restricts fluorinated coolant availability for conventional HVAC systems, complicating retrofit economics for existing facilities.
Strategic Opportunities
- Rotterdam Port Electrification:Maritime logistics corridors adjacent to data center zones enable dual-use grid infrastructure and waste heat recovery partnerships.
- Digital Twin Convergence:Real-time power distribution optimization across multi-tenant campuses creates software-defined margin capture for integrated platform vendors.
- Industrial Heat Networks:Municipal district heating systems in Eindhoven and Utrecht present offtake pathways for data center thermal output monetization.
Industry Challenges
- Medium-Voltage Engineering Talent:Specialized expertise in 10-35 kV UPS design and commissioning remains concentrated among retiring cohorts without adequate apprenticeship pipeline replacement.
- BIS Certification Complexity:Non-EU electrical equipment suppliers face extended compliance timelines for imported switchgear and protection relay systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Power Market |
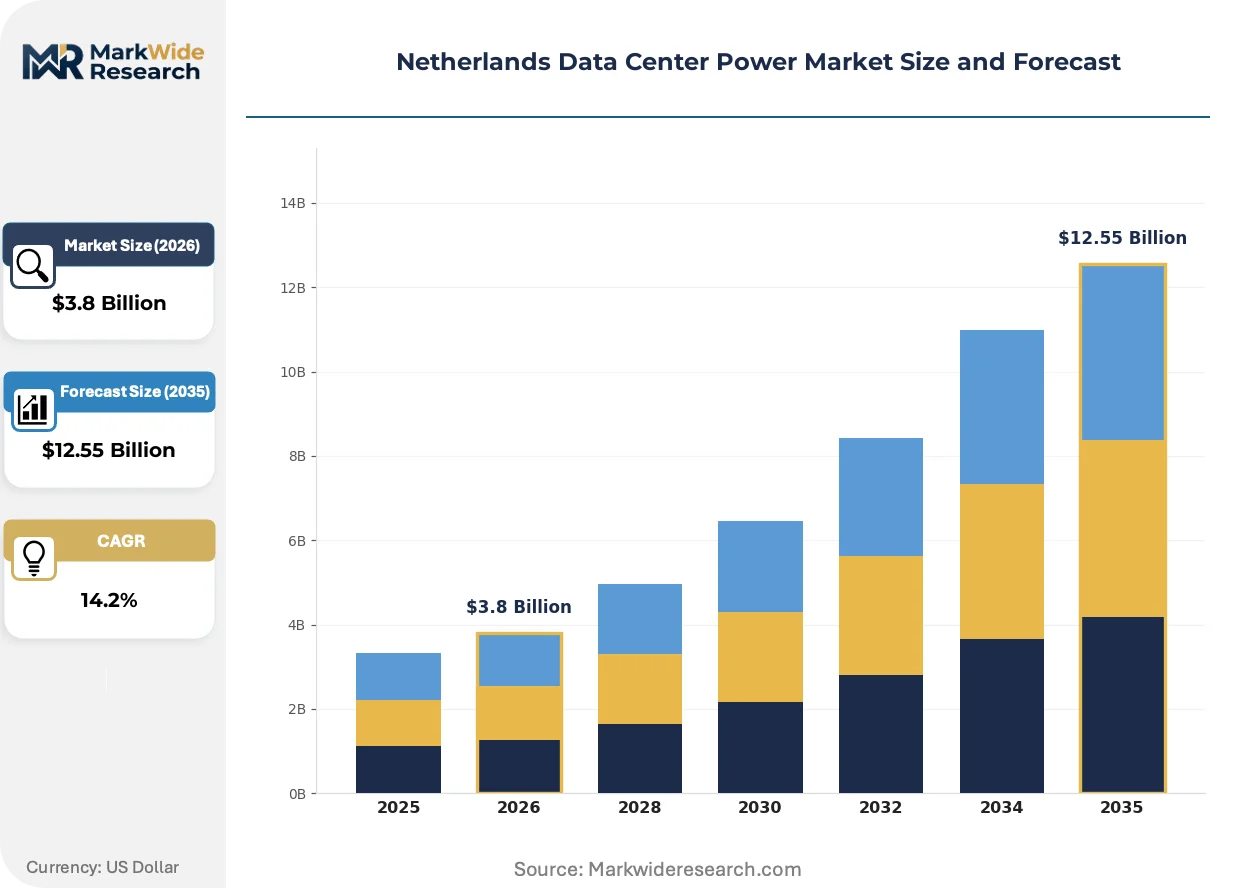
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid, Renewable, Diesel Generator, UPS Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling Power Capacity: Less than 1 MW, 1-5 MW, 5-10 MW, Above 10 MW End User: Telecommunications, BFSI, IT Services, Cloud Providers |
| Companies Covered | Schneider Electric, ABB, Eaton, Vertiv, Delta Electronics, AEG Power Solutions, Riello UPS, Cummins, Siemens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Power Market Trends and Innovations
Power infrastructure intelligence is migrating from hardware redundancy to predictive software layers, compressing commissioning cycles and enabling density scaling that outpaces conventional electrical engineering assumptions.
Artificial intelligence-based load forecasting is automating real-time power distribution decisions across multi-tenant campuses. Hyperscale operators in North Holland are deploying these systems at commissioning phase rather than retrofit. The technology is automating previously manual capacity planning workflows that required 48-hour response cycles.
The EU F-Gas Regulation is accelerating natural refrigerant adoption in thermal management systems. Industrial consequence includes disqualification of conventional HVAC designs for new hyperscale permits. Dutch operators are responding with ammonia and CO2-based cooling architectures in facilities above 15 MW.
Colocation buyers are unbundling power infrastructure procurement from real estate leases. Traditional bundled contracts are fragmenting into separate electrical engineering, renewable energy, and operations agreements. This pattern is most visible in Amsterdam's Schiphol-Rijk corridor where cloud provider direct procurement dominates.
Netherlands Data Center Power Market Segmentation
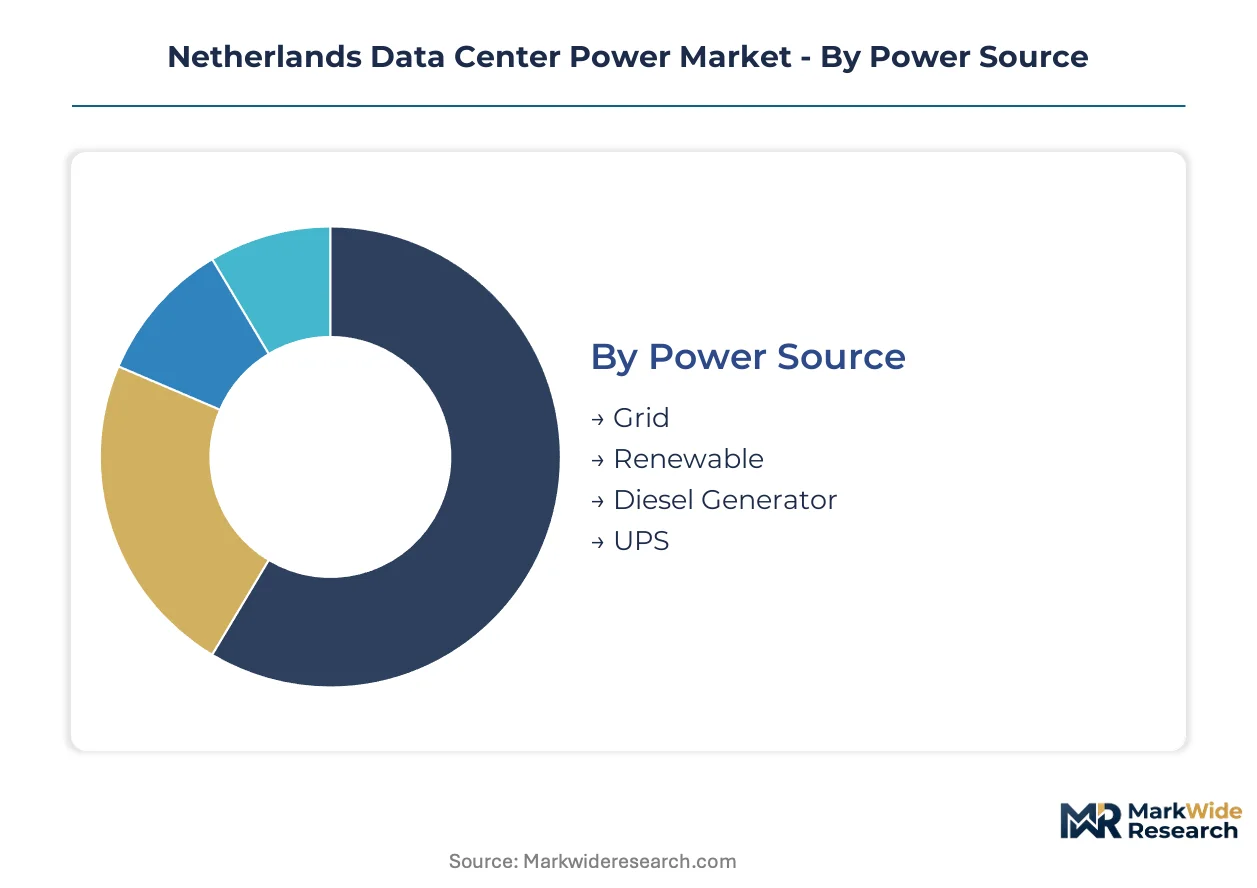
Power infrastructure procurement in the Netherlands fragments across four critical dimensions: source mix, thermal management, scale thresholds, and buyer category. Each axis carries distinct margin profiles and regulatory exposure that shape vendor positioning strategies.
Power Source:
Technology specifications determine carbon compliance trajectories and grid interconnection complexity.
- Grid:Utility-sourced electricity remains the baseline architecture for facilities under 5 MW, though Amsterdam's permit moratorium forces new entrants toward renewable procurement to secure municipal approval. Grid connections face 18-24 month queues enforced by ACM transparency rules.
- Renewable:North Sea wind PPAs and onshore solar offtake agreements dominate hyperscale procurement in North Holland. The EU Green Deal's 2030 deadlines compress procurement timelines for carbon-neutral matching.
- Diesel Generator:Backup rotary systems provide 99.999% uptime guarantees for financial services tenants. Eindhoven's industrial zones maintain dense installed bases requiring emissions retrofit compliance.
- UPS:Battery and flywheel systems bridge sub-20-second outages before generator takeover. Schiphol-Rijk corridor deployments prioritize lithium-ion density over lead-acid legacy.
Grid leads on scale; Renewable leads on momentum.
Cooling Technology:
Cost tier stratification separates legacy HVAC from next-generation thermal architectures.
- Liquid Cooling:Direct-to-chip and immersion systems handle densities above 50 kW per rack in Rotterdam's port-adjacent facilities. Hyperscale operators above 15 MW deploy these at commissioning rather than retrofit.
- Air Cooling:Conventional raised-floor HVAC dominates sub-10 MW colocation in Utrecht and Eindhoven. The EU F-Gas Regulation phases down fluorinated refrigerants, accelerating replacement cycles.
- Evaporative Cooling:Adiabatic systems exploit the Netherlands' maritime climate for free cooling hours. North Holland facilities achieve 2,800+ annual operating hours without mechanical compression.
- Hybrid Cooling:Combined air-liquid architectures optimize for variable density zones within multi-tenant campuses. Amsterdam's Schiphol-Rijk corridor shows strongest adoption for mixed-workload environments.
Air Cooling leads on scale; Liquid Cooling leads on momentum.
Power Capacity:
Application scale dictates electrical engineering complexity and vendor qualification requirements.
- Above 10 MW:Hyperscale campuses require dedicated medium-voltage substations and 10-35 kV UPS design expertise concentrated among retiring Dutch engineering cohorts. Cloud providers in the Randstad corridor drive this tier's expansion.
- 5-10 MW:Enterprise and regional colocation facilities balance density economics against grid connection feasibility. Rotterdam port zones favor this scale for dual-use maritime logistics infrastructure.
- 1-5 MW:Edge and enterprise deployments concentrate in Eindhoven's technology corridor and Utrecht's financial district. BIS certification requirements for imported switchgear extend procurement timelines.
- Less than 1 MW:Remote telecom huts and small office data rooms populate rural Gelderland and Limburg provinces. Standardized skid-mounted power modules dominate procurement.
Above 10 MW leads on scale; 5-10 MW leads on momentum.
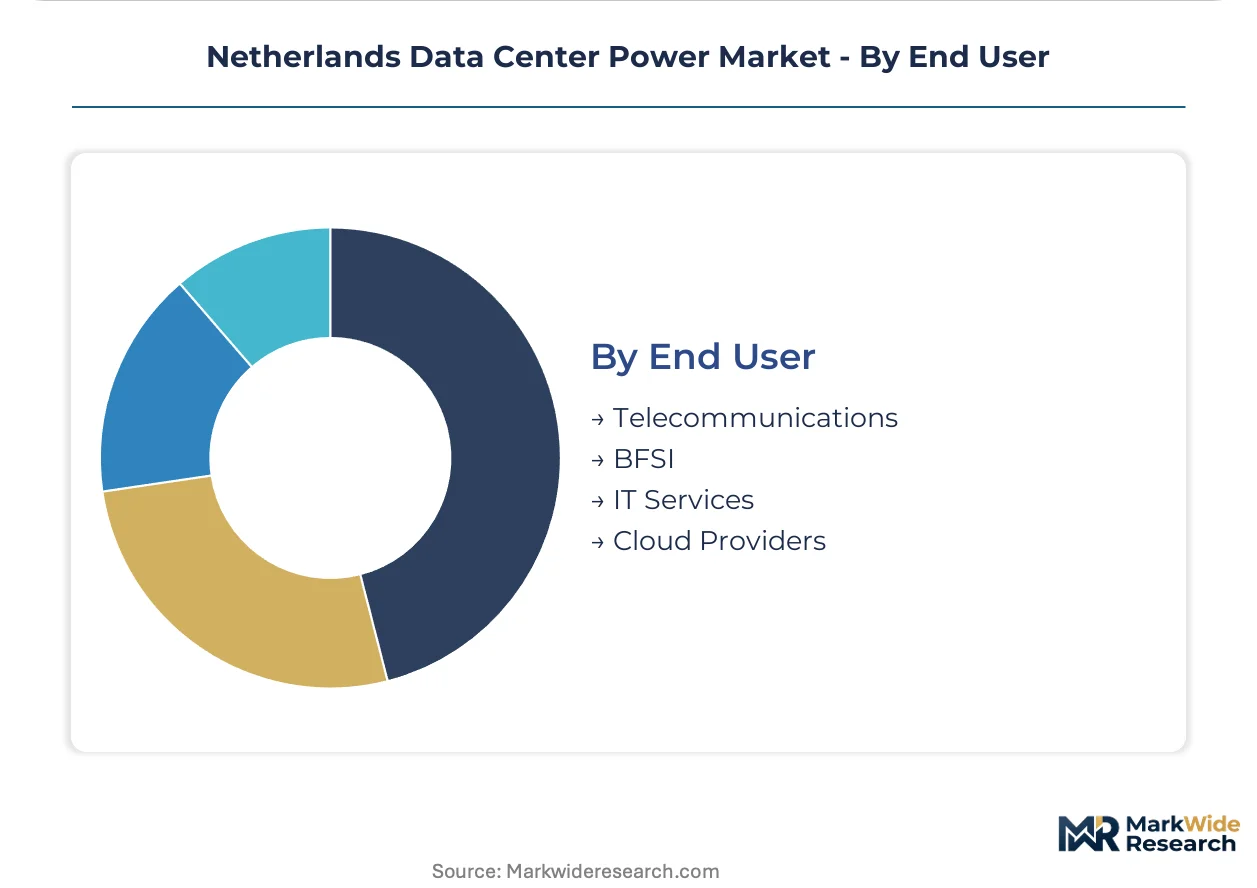
End User:
Customer type determines uptime requirements, contract structures, and thermal density specifications.
- Cloud Providers:Hyperscale operators unbundle power procurement from real estate leases in Amsterdam's Schiphol-Rijk corridor. Direct renewable PPAs and liquid cooling at commissioning define their technical specifications.
- IT Services:Systems integrators and managed service providers prioritize multi-tenant flexibility across 1-5 MW facilities. Utrecht and Eindhoven host dense concentrations serving mid-market enterprise clients.
- BFSI:Dutch banks and insurers mandate Tier III+ redundancy with diesel rotary backup for trading floor continuity. Amsterdam's Zuidas financial district concentrates demand for sub-10 MW critical facilities.
- Telecommunications:KPN and VodafoneZiggo operate distributed edge infrastructure across 500+ cell tower and metro sites. Standardized sub-1 MW power modules support 5G latency requirements.
Cloud Providers lead on scale; IT Services leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent in medium-voltage power systems concentrates in the Randstad corridor, anchoring Dutch data center infrastructure development. Cloud providers and hyperscale operators cluster where this expertise intersects with North Sea renewable energy access and dense fiber connectivity.
Randstad Metropolitan Corridor
Amsterdam's Schiphol-Rijk zone hosts unbundled power procurement from real estate leases, with cloud providers securing direct renewable PPAs. The EU F-Gas Regulation phases down fluorinated coolants, forcing ammonia-based cooling retrofits. North Holland facilities achieve 2,800+ free cooling hours annually through maritime climate exploitation.
Rotterdam Port Zone
Maritime logistics corridors enable dual-use grid infrastructure for data centers above 10 MW capacity. The Netherlands Authority for Consumers and Markets enforces connection queue transparency without accelerating physical buildout. Port-adjacent liquid cooling deployments serve hyperscale operators seeking waste heat recovery partnerships.
Eindhoven Technology Corridor
Enterprise and edge deployments concentrate in Brabant province's 1-5 MW tier, serving mid-market IT services clients. BIS certification requirements for imported electrical equipment extend procurement timelines for non-EU switchgear suppliers. Industrial heat networks present thermal output monetization pathways for municipal district heating systems.
Utrecht Financial District
Dutch banks and insurers mandate Tier III+ redundancy with diesel rotary backup for trading floor continuity. The EU Green Deal compresses timelines for carbon-neutral power architecture procurement ahead of 2030 deadlines. Sub-10 MW critical facilities concentrate in the Zuidas financial zone.
Northern Netherlands
Remote telecom huts and small office data rooms populate rural Gelderland and Limburg provinces with standardized sub-1 MW power modules. Grid connection queues face 18-24 month timelines regardless of facility scale. KPN and VodafoneZiggo operate distributed edge infrastructure across 500+ cell tower sites.
Netherlands Data Center Power Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Dutch data center power market. The vendor base consolidates around integrated platform providers with captive microgrid capabilities and specialized component suppliers focused on narrow technical segments. Three archetypes dominate: European industrial conglomerates with full-stack power portfolios, Asian electronics specialists with cost-optimized manufacturing scale, and regional engineering firms with deep local commissioning expertise. Competitive moves center on strategic partnerships for renewable energy integration and vertical integration into thermal management systems.
Among European-based industrial groups, Schneider Electric, ABB, and Siemens exemplify divergent positioning strategies. Schneider Electric anchors the integrated microgrid tier with end-to-end power distribution architectures. ABB occupies the medium-voltage specialization position, emphasizing high-efficiency UPS systems for hyperscale voltage tiers. Siemens represents the digital convergence archetype, embedding software-defined optimization layers across multi-tenant campus deployments. These three entities collectively illustrate how legacy industrial capability translates into differentiated data center infrastructure value propositions without requiring identical competitive postures.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Vertiv |
| Delta Electronics |
| AEG Power Solutions |
| Riello UPS |
| Cummins |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Cloud provider direct procurement in the Randstad corridor anchors contract-based long-term offtake structures that compress margin pools for integrated power vendors while rewarding renewable energy bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hyperscale operators with 24/7 renewable matching requirements from mid-tier colocation tenants and sub-5 MW edge deployments. Price differentiation hinges on certification grade for carbon-neutral power architectures and volume scale for medium-voltage UPS systems. Cost compression in the sub-10 MW tier is intensifying because grid connection queues extend procurement timelines and force premium payments for expedited delivery. Cloud providers exhibit least price sensitivity due to unbundled procurement models, while regional colocation operators face acute margin pressure from bundled legacy contracts.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium-ion cell manufacturing for UPS battery systems and Chilean copper concentrate for medium-voltage switchgear fabrication. Dutch data center power infrastructure draws from German transformer engineering, South Korean semiconductor components for power electronics, and Belgian cable assembly for medium-voltage distribution. Tariff exposure runs through EU-China trade corridors for battery energy storage systems. Distribution runs through EPC contractors with captive commissioning expertise in North Holland and direct vendor relationships for hyperscale self-build projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
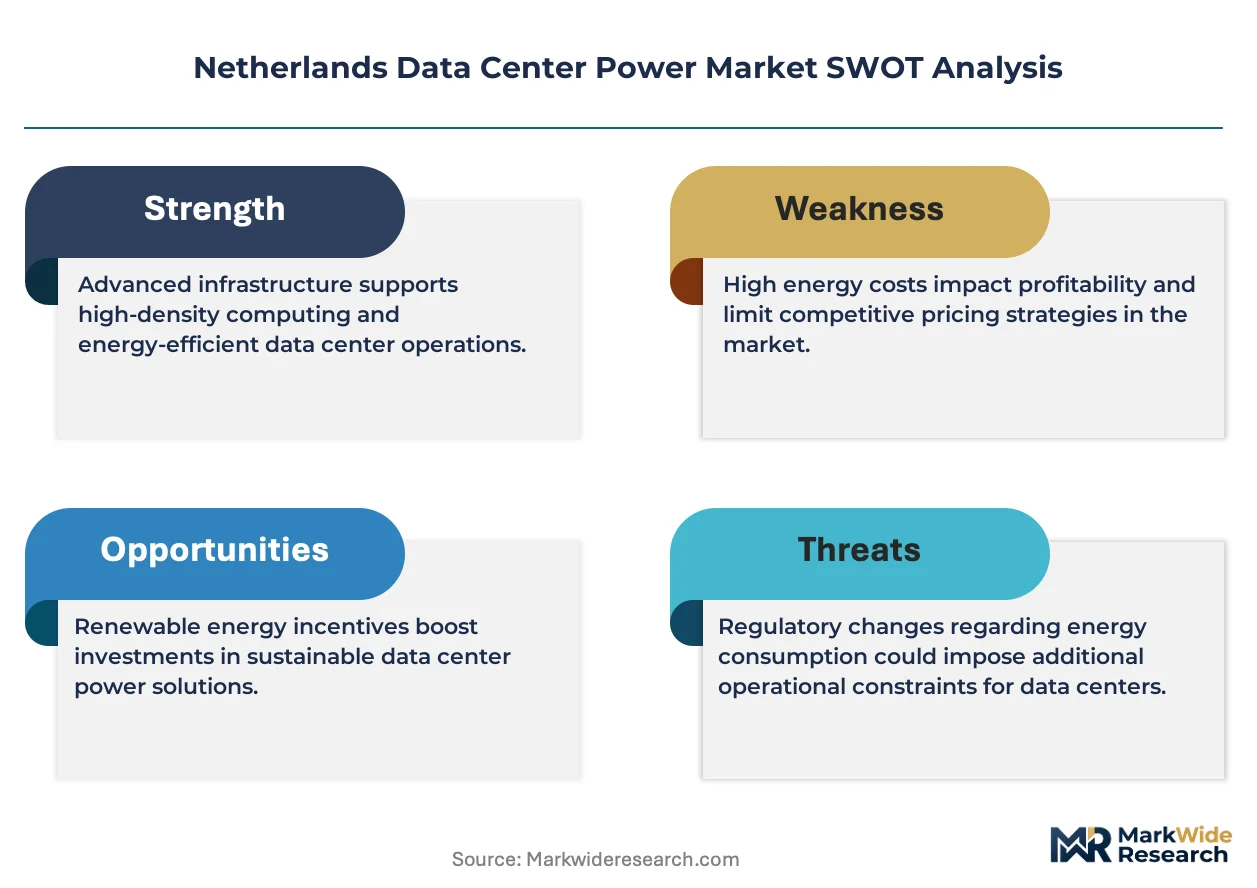
Amsterdam's permit moratorium against Rotterdam's port electrification incentives creates a regulatory arbitrage window for power infrastructure deployment, with waste heat recovery partnerships offering cost offsets unavailable in the constrained metropolitan core.
For Market Incumbents: Extend microgrid integration capabilities into thermal management systems to capture liquid cooling bundling opportunities as the EU F-Gas Regulation phases down conventional HVAC designs. Acquire specialized 10-35 kV UPS engineering talent in the Randstad corridor before retirement cohorts exit. Strengthen backward integration into renewable energy origination to defend margin position against unbundled procurement trends. For New Entrants and Emerging Players: A 40-60% price-point gap between premium Schneider Electric-ABB tier and economy Delta Electronics-Riello tier creates entry space for mid-market specialists with ammonia-based cooling expertise. Target Eindhoven's 1-5 MW enterprise segment where BIS certification barriers filter out non-EU competitors. Pursue municipal heat network partnerships as a differentiated go-to-market angle for thermal output monetization. For Investors and Strategic Acquirers: European industrial conglomerates with captive renewable development arms are the most active acquirer in this space, seeking integrated platform capabilities. The 5-10 year viability window favors vendors with software-defined power distribution layers over hardware-only component suppliers. Monitor Amsterdam's permit moratorium spread to Rotterdam and Eindhoven as the critical inflection signal for geographic deployment shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | North Sea wind offtake agreements enable 24/7 carbon matching for hyperscale cloud providers. |
| Liquid Cooling Technology Licensing | Ammonia-based thermal architectures bypass EU F-Gas Regulation restrictions on fluorinated coolants. |
| Backward Integration into Battery Storage | Captive lithium-ion supply secures UPS density advantages over lead-acid legacy systems. |
| Digital Twin Platform Integration | Real-time power distribution optimization captures software-defined margins in multi-tenant campuses. |
| Joint Venture for Heat Recovery | Municipal district heating partnerships in Eindhoven and Utrecht monetize thermal output streams. |
Research Methodology
Bottom-up facility-scale modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with data center engineering directors, utility interconnection planners, EPC contractors, and renewable energy developers were validated against secondary sources including ACM grid queue disclosures, EU F-Gas Regulation implementation reports, and hyperscaler capital expenditure filings. Triangulation across these data layers ensures supply-side and demand-side estimates converge.
Historical trendline analysis of power infrastructure deployments across the Netherlands established baseline growth patterns that inform projection modeling. Segmentation dimensions include power source mix, cooling technology tier, capacity threshold, and end-user category, with regional regulatory frameworks and grid interconnection timelines as additional forecast inputs. CAGRs were derived from fitted growth curves adjusted for policy-driven inflection points.
Caveats apply where ACM queue transparency rule changes, copper price volatility, or Amsterdam permit moratorium expansion could materially shift the outlook. Forecasts reflect assumptions about renewable energy buildout rates and engineering talent pipeline recovery. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market