
 Asia-Pacific Solar Control Window Films Market | 2026-2036
Asia-Pacific Solar Control Window Films Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solar Control Window Films Market Outlook
Commercial building portfolio managers are collapsing as the fastest-growing buyer archetype across Southeast Asia and Oceania, displacing price-sensitive residential retrofitters who previously dominated volume. 3M leverages its multi-layer optical film technology to sustain premium positioning in Australia's commercial high-rise segment. Eastman Chemical Company anchors regional supply through its dyed and ceramic film manufacturing footprint in China and South Korea. Garware Hi-Tech Films Limited dominates the Indian market with specialized metallic formulations engineered for tropical solar gain conditions.
Asia-Pacific solar control window films are thin, multi-layered polymer laminates typically constructed from polyethylene terephthalate substrates with vacuum-deposited metal oxide or nano-ceramic coatings, engineered to reject infrared radiation while transmitting visible light for energy-efficient glazing systems. Ceramic Films lead the product type landscape due to superior infrared rejection without signal interference, while Hybrid Films represent the fastest-growing category as manufacturers combine metallic reflectivity with ceramic selectivity to balance performance and cost. The Application dimension shows Commercial Buildings commanding the largest margin pool, though Automotive retrofit demand accelerates in Thailand and Indonesia where cabin thermal management drives aftermarket adoption.
India's BIS energy-efficiency standards for building envelopes, Australia's Green Star certification requirements, and China's GB standards for construction materials collectively shape product specifications and market access across the region. Australia's National Construction Code thermal performance provisions mandate minimum total system U-value and solar heat gain coefficient thresholds that directly determine film selection criteria for new commercial projects. Stakeholders must monitor evolving green building mandates in Indonesia and Vietnam, where pending regulatory frameworks will likely replicate Australian and Indian certification-driven specification models within the next development cycle.
Market Dynamics
Commercial building portfolio managers across Southeast Asia and Oceania are consolidating specification authority, displacing fragmented residential retrofit demand and forcing manufacturers to reconfigure product hierarchies around green certification compliance rather than price-per-square-meter metrics.
Growth Catalysts
- Australia's Green Star certification requirements:Mandatory thermal performance thresholds for commercial high-rises are accelerating specification of ceramic and hybrid formulations with verified solar heat gain coefficients.
- India's BIS energy-efficiency mandates:Building envelope standards issued by the Bureau of Indian Standards are compelling architects to integrate spectrally selective films into new construction specifications.
- Automotive cabin thermal management:Aftermarket retrofit demand in Thailand and Indonesia is expanding as vehicle owners seek infrared rejection without dark tinting that violates visibility regulations.
Market Restraints
- Petroleum-based substrate volatility:Polyethylene terephthalate resin costs fluctuate with crude oil derivatives, compressing margin stability for film laminators without backward integration into polymer supply.
- China-centric vacuum deposition capacity:Metal oxide coating equipment and technical expertise concentrate in eastern Chinese manufacturing clusters, creating geographic supply risk for regional formulators.
- Metallic film signal interference:Silver and aluminum reflective layers disrupt GPS, cellular, and RFID transmission, disqualifying these cost-effective formulations from connected vehicle and smart building applications.
Strategic Opportunities
- Vietnam's pending green building framework:Draft regulations modeled on Australian certification systems will replicate specification-driven demand patterns within the next development cycle.
- Nano-ceramic and sputtered metal convergence:Hybrid architectures combining infrared selectivity with electromagnetic transparency are opening premium positioning in data center and telecommunications facility glazing.
- Direct specification to facility management platforms:Bypassing traditional glass contractor channels through energy-service company partnerships reduces price transparency and builds recurring maintenance revenue.
Industry Challenges
- Vacuum deposition technician scarcity:Precision sputtering and chemical vapor deposition operations require specialized operators whose training pipelines lag regional capacity expansion.
- Multi-jurisdiction certification timelines:Securing BIS approval in India, SAI Global certification in Australia, and GB standard compliance in China for a single product platform extends commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solar Control Window Films Market |
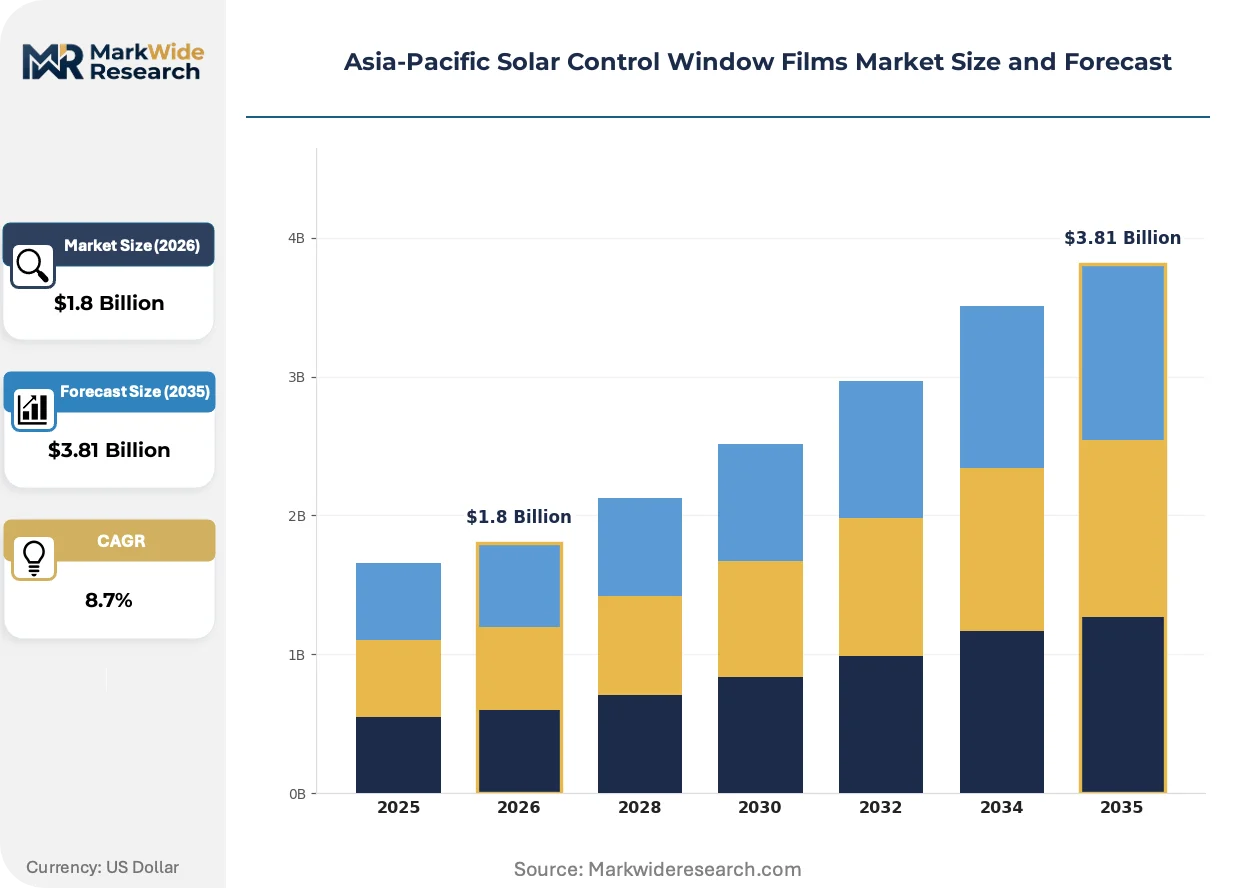
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Films, Metallic Films, Ceramic Films, Hybrid Films Application: Residential Buildings, Commercial Buildings, Automotive, Aircraft Installation Type: Professional Installation, DIY Installation, Retrofit Installation, New Construction Customer Type: End Users, Contractors, Architects, Retailers |
| Companies Covered | 3M, Saint-Gobain Performance Plastics, Eastman Chemical Company, Polytronix Inc, Garware Hi-Tech Films Limited, Avery Dennison Corporation, Lintec Corporation, Dexerials Corporation, Johnson Window Films, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solar Control Window Films Market Strategic Shifts
Formulation architectures are fragmenting into performance-optimized versus cost-optimized tracks as end-use requirements diverge, while regulatory pressure and buyer sophistication compress the viable middle ground.
Hybrid film technology is bifurcating the product landscape. These multi-layer laminates combine nano-ceramic infrared absorption with metallic reflectivity to balance thermal rejection against material cost. Premium commercial retrofitters in Australia and Singapore are specifying these formulations for Green Star compliance. The technology is bifurcating manufacturer R&D roadmaps into certification-focused premium tracks versus volume-oriented economy tracks.
India's BIS energy-efficiency standards for building envelopes are mandating minimum performance thresholds that disqualify dyed and basic metallized films from new construction specifications. Architects and glazing contractors must now document total system U-values and solar heat gain coefficients that only spectrally selective ceramic and hybrid formulations achieve. Commercial building portfolio managers in Mumbai, Bangalore, and Delhi NCR are responding by pre-specifying approved film schedules in master glazing contracts.
Facility management procurement teams are consolidating supplier relationships around energy-performance contracting models that bundle film installation with guaranteed HVAC load reduction. Traditional glass contractor distribution channels face disintermediation as building owners seek direct accountability for energy outcomes. This pattern is most visible in Australia's premium commercial retrofit segment, where portfolio-wide master service agreements with national installation networks are replacing project-by-project bidding.
Asia-Pacific Solar Control Window Films Market Segmentation
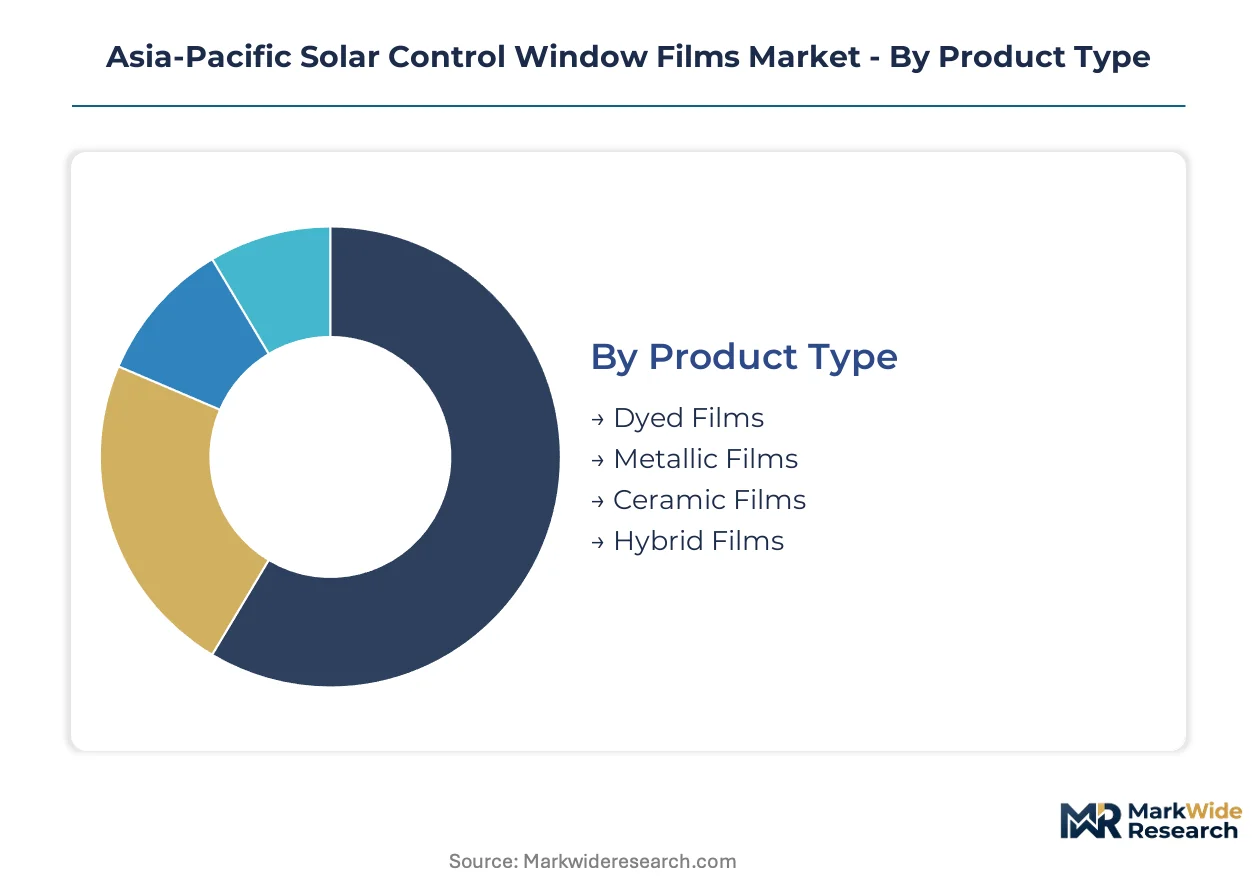
Architectural specification authority and automotive retrofit demand are fragmenting the Asia-Pacific solar control window films market across four distinct dimensions. Regulatory mandates in Australia and India now determine which product formulations qualify for commercial projects, while installation methods diverge between certified green building retrofits and emerging DIY channels.
Product Type:
Australia's Green Star certification thresholds and India's BIS energy-efficiency standards are disqualifying basic formulations from new construction specifications, concentrating procurement around performance-verified categories.
- Ceramic Films:Nano-ceramic particle layers absorb infrared radiation without metallic interference, preserving GPS and cellular signal integrity. Australian commercial high-rise portfolio managers specify these for Green Star compliance in Sydney and Melbourne CBD retrofits where electromagnetic transparency is mandatory.
- Hybrid Films:Multi-layer architectures combine sputtered metal reflectivity with ceramic absorption to balance thermal rejection against material cost. Singapore and Bangkok commercial developers are adopting these for projects requiring mid-tier performance without premium ceramic pricing.
- Metallic Films:Vacuum-deposited aluminum or silver layers deliver cost-effective solar reflectance but disrupt wireless transmission, limiting deployment to non-connected building zones and older vehicle fleets.
- Dyed Films:Absorptive polymer tints without metallic or ceramic additives dominate Thailand and Indonesia automotive aftermarket channels where regulatory visibility standards prohibit dark ceramic formulations.
Established volume favors Ceramic Films; emerging adoption favors Hybrid Films.
Application:
Margin concentration tracks specification complexity, with certified commercial projects commanding premium pricing over price-sensitive residential retrofits.
- Commercial Buildings:Green Star, BIS, and GB standard compliance mandates are collapsing buyer authority into facility management procurement teams who specify ceramic and hybrid films through master service agreements. Australian portfolio managers now require documented total system U-values and solar heat gain coefficients that only spectrally selective formulations achieve.
- Automotive:Aftermarket cabin thermal management demand is accelerating in Thailand and Indonesia where tropical climates and visibility regulations drive specification of infrared-rejecting ceramic tints over traditional dyed alternatives.
- Residential Buildings:Fragmented homeowner retrofit demand across Southeast Asia remains price-sensitive, with metallic and dyed films dominating volume despite inferior thermal performance versus commercial-grade alternatives.
- Aircraft:Specialized lightweight formulations for airline cabin glazing represent a niche specification channel concentrated in Singapore and Hong Kong maintenance hubs serving regional carriers.
Margin accretion concentrates in Commercial Buildings; volume expansion concentrates in Automotive.
Installation Type:
Channel structure is bifurcating between certified professional networks for commercial compliance and emerging direct-to-consumer platforms for residential convenience.
- Professional Installation:Certified applicator networks dominate Australian and Indian commercial projects where warranty validity and performance documentation require trained technician deployment.
- Retrofit Installation:Existing building energy upgrades across Australia's premium commercial stock are driving specification of ceramic and hybrid films through energy-service company partnerships that guarantee HVAC load reduction outcomes.
- New Construction:Architect-integrated specification during glazing system design is displacing post-occupancy retrofit in Indian commercial towers subject to BIS envelope standards.
- DIY Installation:E-commerce platforms and automotive accessory retailers in Thailand and Indonesia are expanding consumer-direct channels for pre-cut vehicle tint kits.
Compliance-critical projects favor Professional Installation; convenience-driven demand favors DIY Installation.
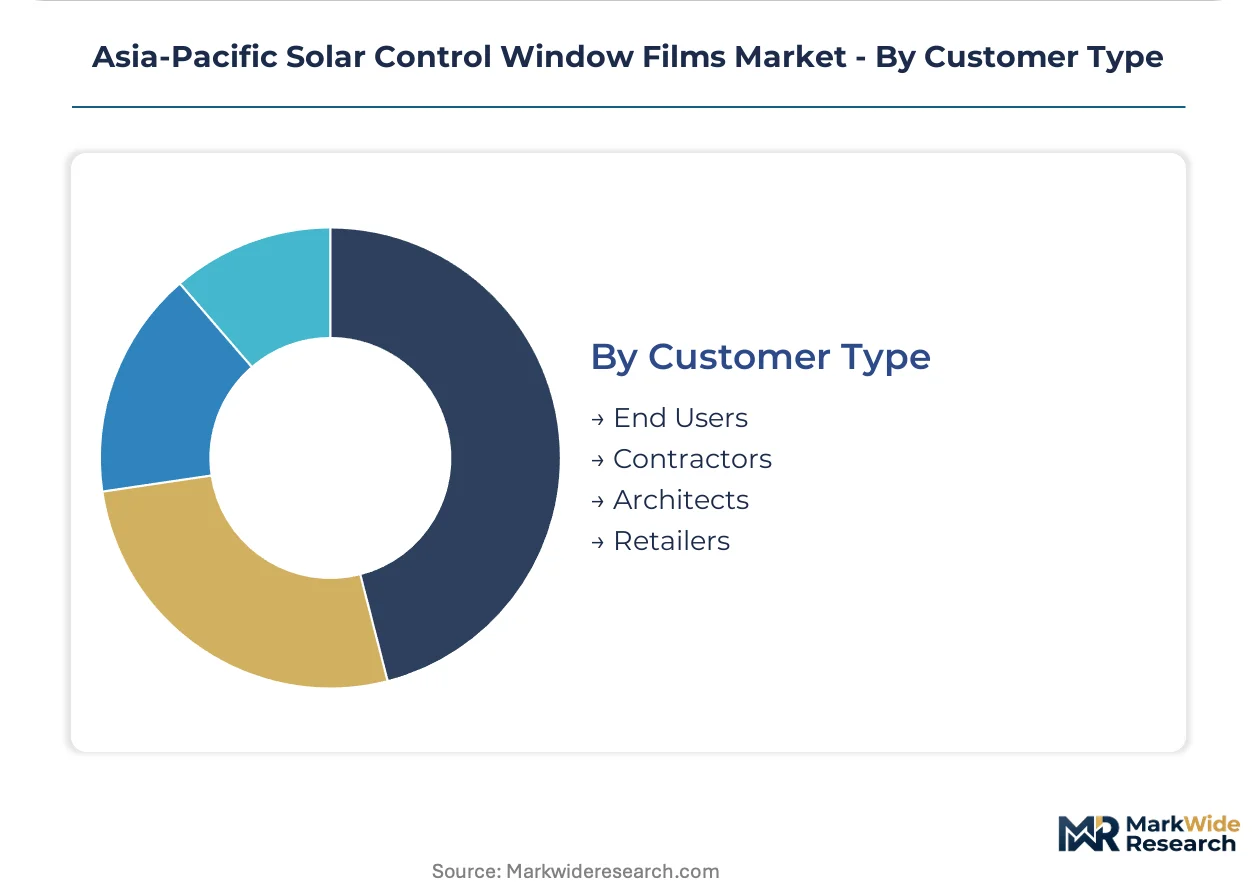
Customer Type:
Procurement authority is migrating upstream from contractors to architects and facility managers as regulatory documentation requirements intensify.
- Architects:Indian and Australian design professionals now pre-specify approved film schedules in master glazing contracts to ensure BIS and Green Star compliance, bypassing contractor substitution with lower-performance alternatives.
- Contractors:Traditional glass installation firms face margin compression as facility management platforms and energy-service companies capture specification authority and recurring maintenance revenue.
- End Users:Commercial building portfolio managers in Sydney, Melbourne, Mumbai, and Bangalore are consolidating supplier relationships around performance-guaranteed contracting models.
- Retailers:Automotive accessory chains and e-commerce platforms in Bangkok, Jakarta, and Kuala Lumpur serve price-sensitive consumer segments with DIY tint kits and basic metallic formulations.
Specification control is shifting toward Architects; volume throughput remains with Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building portfolio managers are consolidating specification authority across the Asia-Pacific region, displacing fragmented residential retrofit demand and concentrating procurement around green certification compliance in Australia, India, and emerging Southeast Asian markets.
Australia
Green Star certification requirements from the Green Building Council of Australia mandate minimum total system U-value and solar heat gain coefficient thresholds for commercial high-rises. Sydney and Melbourne CBD retrofit projects specify ceramic and hybrid formulations with verified performance documentation. Premium commercial stock in these metropolitan centers drives margin concentration through energy-service company partnerships.
India
Bureau of Indian Standards energy-efficiency mandates for building envelopes compel architects to integrate spectrally selective films into new commercial tower specifications. Mumbai, Bangalore, and Delhi NCR facility managers pre-approve film schedules in master glazing contracts to ensure compliance. Garware Hi-Tech Films Limited anchors domestic supply with metallic formulations engineered for tropical solar gain conditions.
China
GB standards for construction materials shape product specifications and market access for regional formulators. Vacuum deposition capacity and metal oxide coating equipment concentrate in eastern Chinese manufacturing clusters, creating supply-side geographic risk. Yangtze River Delta and Pearl River Delta industrial zones host the majority of ceramic and hybrid film production infrastructure serving export markets.
Thailand
Automotive cabin thermal management drives aftermarket retrofit demand as vehicle owners seek infrared rejection without dark tinting that violates visibility regulations. Bangkok automotive accessory chains and e-commerce platforms expand consumer-direct channels for pre-cut vehicle tint kits. Dyed films dominate volume in this price-sensitive segment despite inferior thermal performance versus ceramic alternatives.
Singapore
Commercial developers adopt hybrid film formulations for projects requiring mid-tier performance without premium ceramic pricing. The city-state's position as a regional maintenance hub concentrates specialized lightweight aircraft glazing formulations for airline cabin retrofits. Facility management platforms consolidate supplier relationships around energy-performance contracting models.
Asia-Pacific Solar Control Window Films Market Competitive Environment
Player mix skews toward diversified materials conglomerates with optical film expertise and specialized regional formulators with tropical climate engineering capabilities. Market structure shows moderate consolidation at the premium tier alongside fragmented mid-market supply. Two strategic archetypes dominate: multi-layer optical technology specialists and regional formulators with backward-integrated polymer supply. Competitive moves center on certification-driven portfolio diversification and energy-service company partnership structures that bypass traditional glass contractor channels.
Among diversified technology conglomerates, 3M leverages multi-layer optical film expertise to sustain premium positioning in Australia's commercial high-rise segment. Eastman Chemical Company anchors regional supply through dyed and ceramic film manufacturing footprint in China and South Korea. Garware Hi-Tech Films Limited occupies a dominant position in the Indian market as a specialized regional formulator with tropical solar gain engineering capabilities.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain Performance Plastics |
| Eastman Chemical Company |
| Polytronix Inc |
| Garware Hi-Tech Films Limited |
| Avery Dennison Corporation |
| Lintec Corporation |
| Dexerials Corporation |
| Johnson Window Films |
| Others |
Value Chain & Pricing Dynamics
Hybrid film substitution for basic metallized formulations simultaneously shifts production gravity toward eastern Chinese vacuum deposition clusters and compresses margin capture for non-integrated regional formulators lacking captive PET resin supply.
Pricing Analysis
Ceramic-to-hybrid-to-metallic generation gaps stratify pricing across three performance tiers. Premium ceramic formulations command certification-linked premiums for Green Star and BIS compliance, while hybrid films capture mid-market positioning through balanced infrared rejection. Cost compression in metallic and dyed tiers intensifies as petroleum-based PET resin volatility feeds through to laminators without backward integration. Residential retrofitters in Thailand and Indonesia exhibit highest price sensitivity, whereas Australian commercial portfolio managers prioritize documented thermal performance over per-square-meter cost.
Supply Chain Analysis
Yangtze River Delta vacuum deposition equipment chokepoints tether regional formulator output to eastern Chinese technical expertise and metal oxide coating capacity. Raw material dependencies center on PET resin feedstocks, sputtering target metals, and nano-ceramic particle supply. Single-source vulnerability concentrates in Chinese vacuum deposition technician pipelines and specialized coating equipment. Distribution runs through certified applicator networks for commercial compliance projects, while automotive aftermarket channels fragment across Bangkok and Jakarta e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific solar control window films market sits in a regulatory upcycle as green building mandates across Australia, India, and emerging Southeast Asian markets compress commercial specification timelines and accelerate replacement demand.
For Market Incumbents: Fortify certification moats by pre-positioning ceramic and hybrid formulations for Vietnam's pending green building framework replication of Australian standards. Anchor supply security through backward integration into PET resin or binding long-term offtake agreements with Yangtze River Delta deposition equipment operators. Defend against regional formulator price erosion by bundling installation warranty with energy-performance guarantees that shift buyer evaluation from upfront cost to lifecycle HVAC savings. For New Entrants and Emerging Players: Energy-service company partnership infrastructure represents an underdeveloped service layer where incumbents cede specification authority to facility management platforms. Penetrate Vietnam and Indonesia commercial retrofit pipelines ahead of regulatory finalization by aligning hybrid film portfolios with draft green building thresholds. Deploy direct-to-facility-manager sales models that bypass traditional glass contractor channels and capture recurring maintenance revenue through performance-based contracting. For Investors and Strategic Acquirers: The market sits at a pre-regulatory harmonization phase that favors vertically integrated specialists with tropical climate engineering capabilities and multi-jurisdiction certification track records. Target acquisition profiles emphasize Indian and Southeast Asian formulators possessing BIS approval infrastructure and established architect specification relationships. Monitor Vietnam's green building framework promulgation and Indonesia's energy-efficiency building code development as inflection signals for specification-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | Early BIS and Green Star alignment secures architect specification lock-in for commercial towers. |
| Backward Integration into PET Resin | Captive polymer supply insulates margin compression from crude oil derivative volatility. |
| Energy-Service Company Partnerships | Direct facility management channel access displaces traditional glass contractor intermediation. |
| Vacuum Deposition Technician Training | Proprietary sputtering expertise pipeline alleviates regional capacity expansion bottlenecks. |
| Hybrid Film R&D Convergence | Nano-ceramic and sputtered metal layering opens electromagnetic-transparent premium positioning. |
Study Parameters
The analysis maps ceramic, hybrid, metallic, and dyed film sub-sectors, each validated through primary interviews with glazing contractors, facility management procurement leads, architect specification directors, and vacuum deposition equipment operators, combined with secondary triangulation across BIS energy-efficiency circulars, Green Building Council of Australia certification databases, Chinese GB construction material standards, and customs trade flow records for PET resin and sputtering target imports.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, installation method, and customer procurement authority. CAGRs derive from bottom-up build of specification-driven commercial retrofit pipelines and top-down validation against regional construction spending and green building certification trajectories. Forecast inputs incorporate petroleum-based substrate cost curves, vacuum deposition capacity utilization, and regulatory timeline probability assessments.
Underlying assumptions cover green building mandate adoption rates, vacuum deposition equipment commissioning schedules, and PET resin price stability, with deviation risk concentrated in Vietnamese regulatory finalization delays and Chinese manufacturing cluster logistics disruptions. Practitioners should keep alternative scenarios live as Southeast Asian green building framework development and hybrid film technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Construction Films Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market