

Erbium-169 Market Size, Share, and Industry Trends Forecast 2026-2036
Erbium-169 Market Insights
Capital-intensity divergence between cyclotron-equipped manufacturers and reactor-dependent suppliers is rotating competitive advantage toward entities with captive isotope production. GE HealthCare leverages its integrated radiopharmaceutical network across North American oncology centers. Curium sustains European supply continuity through dedicated reactor partnerships. NorthStar Medical Radioisotopes anchors domestic production capacity with its accelerator-based approach, reducing import dependency for United States hospitals.
Erbium-169 is a synthetic radioisotope with a half-life of approximately 9.4 days, decaying via beta emission to thulium-169, and is produced primarily through neutron activation of erbium-168 targets in nuclear reactors or via proton bombardment in cyclotrons; its primary commercial purpose centers on targeted radionuclide therapy for bone pain palliation and emerging applications in theranostics. Medical Implants and Spectrum Sources occupy the highest margin tiers within product categories, while Nuclear Medicine applications lead volume consumption as theranostic protocols expand across major hospital networks. Oncology Centers dominate end-user procurement, though Research Laboratories represent the fastest-growing demand segment as preclinical theranostic pipelines mature.
FDA oversight of radiopharmaceutical manufacturing under 21 CFR Part 212, EMA's GMP guidelines for radiolabeled compounds, and IAEA transport regulations collectively shape production standards, distribution licensing, and cross-border market access for Erbium-169 suppliers. Stakeholders must monitor evolving theranostic reimbursement codes and reactor decommissioning schedules across Europe and North America, as these dual forces will determine supply security and commercial viability for emerging indications beyond palliative care.
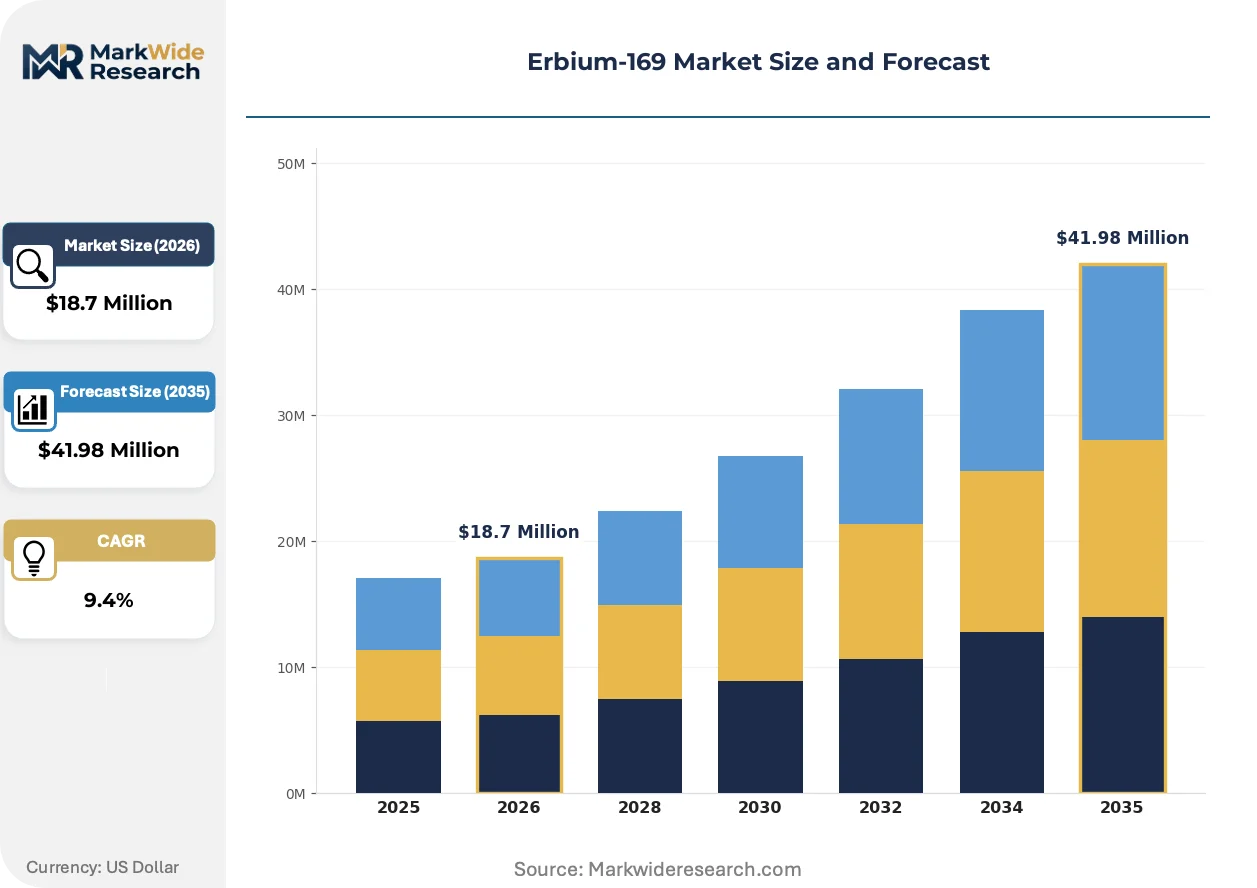
Market Dynamics
Reactor decommissioning schedules across Europe and North America are compressing Erbium-169 supply availability, forcing buyers toward accelerator-based production alternatives and reshaping procurement security calculations for oncology networks.
Growth Catalysts
- Bone metastases prevalence:Aging demographics in Germany, the United States, and Japan are expanding the addressable patient population for palliative radionuclide therapy.
- Theranostic protocol expansion:Hospital networks are integrating Erbium-169 into paired diagnostic-therapy workflows, lifting utilization rates per treatment center.
- IAEA transport standardization:Harmonized cross-border shipping protocols are reducing distribution friction for time-sensitive isotope deliveries between production facilities and clinical sites.
Market Restraints
- Reactor dependency concentration:Over half of medical isotope supply routes pass through aging high-flux reactor infrastructure in Belgium and the Netherlands, creating single-point vulnerability.
- Helium-3 scarcity:Neutron detection and target cooling requirements face input cost pressure from depleted stockpiles and export restrictions.
- Strontium-89 substitution:Competing beta-emitting radiopharmaceuticals with longer shelf stability are capturing price-sensitive procurement decisions in emerging markets.
Strategic Opportunities
- Domestic accelerator networks:The United States Department of Energy is funding distributed cyclotron capacity to reduce import reliance for critical medical isotopes.
- Preclinical pipeline maturation:Research laboratories in Switzerland and Australia are advancing Erbium-169 labeled compounds for solid tumor indications beyond bone metastases.
- EMA orphan drug incentives:Rare disease designation pathways are accelerating regulatory review timelines for novel radiotherapeutic applications.
Industry Challenges
- Qualified personnel scarcity:Nuclear pharmacy specialisation programs are producing insufficient certified radiopharmacists to staff expanding production facilities.
- GMP certification timelines:FDA 21 CFR Part 212 compliance for new manufacturing sites requires 18-24 month validation cycles, delaying market entry.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erbium-169 Market Trends and Innovations
Accelerator-based isotope production is decomposing the traditional reactor-centric supply model, while regulatory frameworks and procurement behaviors are adapting to shorter half-life logistics and theranostic integration requirements.
Cyclotron-based proton bombardment of erbium-168 targets is decomposing neutron activation as the dominant production pathway. Oncology centers in the United States are adopting accelerator-sourced Erbium-169 to secure supply continuity independent of European reactor schedules. This shift is compressing geographic concentration risk and enabling just-in-time production models that align with patient-specific dosing protocols.
EMA's revised GMP guidelines for radiolabeled compounds are tightening environmental monitoring and personnel exposure documentation requirements for European production facilities. Manufacturers must now implement continuous air sampling systems and real-time dosimetry networks. German and French suppliers are absorbing compliance costs through dedicated quality infrastructure investments, while smaller operators face consolidation pressure.
Hospital procurement departments are unbundling radiopharmaceutical sourcing from bundled oncology service contracts, creating direct purchasing relationships with isotope manufacturers. This disintermediation is compressing distributor margins and exposing price transparency across previously opaque supply tiers. The pattern is most pronounced in Japanese university hospitals, where centralized pharmacy committees are negotiating multi-year supply agreements with guaranteed volume commitments.
Erbium-169 Market Segmentation
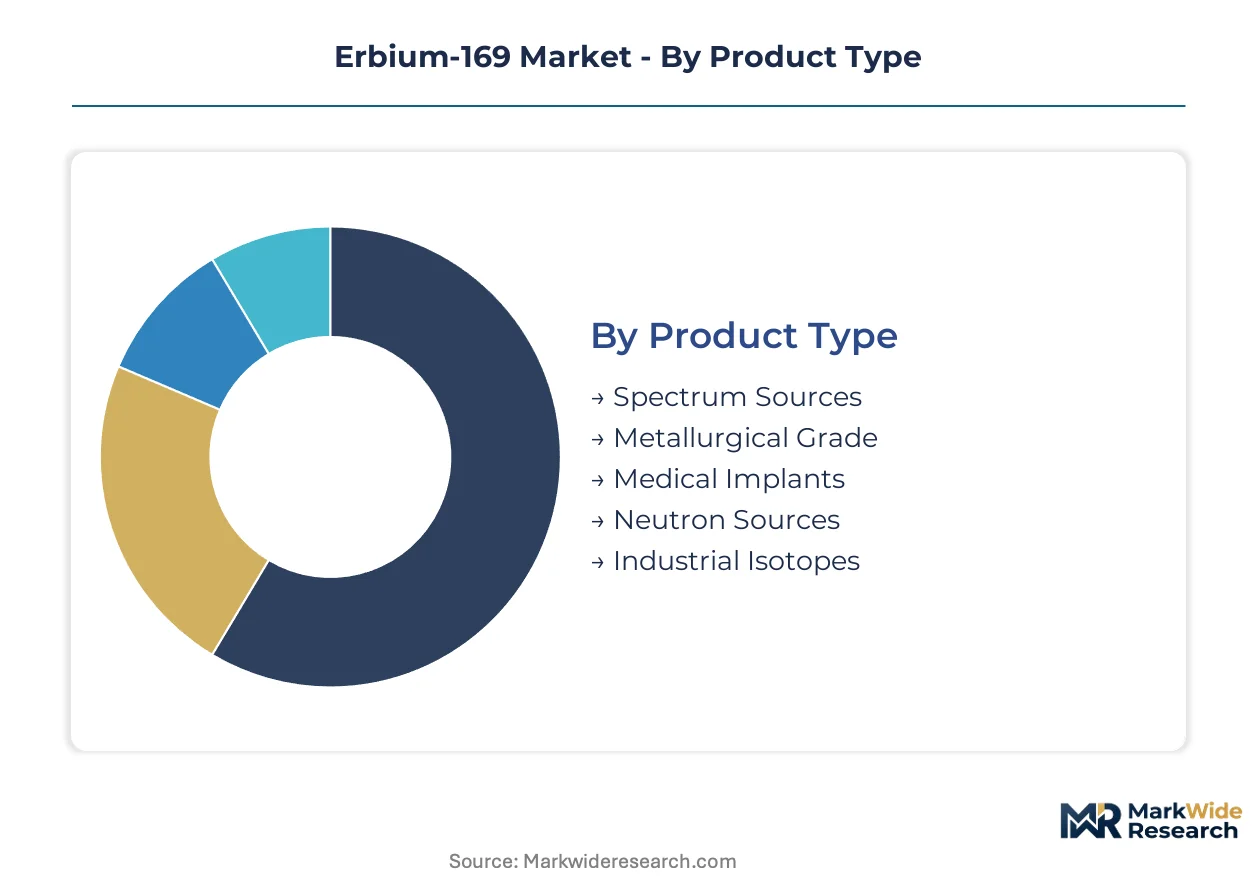
Erbium-169 market segmentation reveals divergent margin profiles across production pathways and end-use specifications. Substitute radiopharmaceuticals exert uneven pressure across categories, reshaping investment prioritization for manufacturers.
Product Type:
Substitution pressure from strontium-89 and samarium-153 radiopharmaceuticals falls most heavily on commodity-grade isotopes, while specialized medical formulations maintain defensive positioning through regulatory exclusivity.
- Medical Implants:These sealed-source devices incorporate Erbium-169 into brachytherapy seeds and bone-seeking microspheres with precise activity loading. German oncology centers and Japanese university hospitals drive procurement for palliative bone metastases protocols, with reimbursement coding under national health frameworks insulating demand from generic substitution.
- Spectrum Sources:Calibration standards for gamma spectroscopy and nuclear instrumentation require exact half-life matching. Research laboratories in Switzerland and Australia represent concentrated demand as theranostic imaging protocols expand, though longer-lived cobalt-60 alternatives capture price-sensitive industrial accounts.
- Metallurgical Grade:Trace doping applications in specialty alloys for aerospace components.
- Neutron Sources:Activation targets for portable neutron generators used in oilfield logging and security screening.
- Industrial Isotopes:Bulk unprocessed material for downstream radiopharmaceutical manufacturing.
Medical Implants retains volume leadership; Spectrum Sources holds the steepest expansion curve.
Application:
Cost tier stratification separates reimbursable clinical procedures from capital-intensive industrial testing, with divergent procurement cycles and margin structures across the application matrix.
- Nuclear Medicine:Diagnostic imaging and therapeutic administration of Erbium-169 radiopharmaceuticals within hospital nuclear medicine departments. United States cancer centers and French public hospital networks anchor volume consumption, with cyclotron-produced isotopes displacing reactor-sourced supply for patient-matched dosing schedules.
- Radiation Therapy:External beam calibration and brachytherapy source integration at radiation oncology facilities. Germany's dense network of university-affiliated cancer centers sustains premium pricing for high-specific-activity material, though reimbursement compression under statutory health insurance constrains expansion.
- Non-Destructive Testing:Industrial radiography and materials characterization for aerospace and energy infrastructure.
- Industrial Radiography:Gamma radiography for weld inspection and structural integrity verification.
- Material Analysis:Neutron activation analysis for elemental composition determination in geological and environmental samples.
Nuclear Medicine commands the dominant revenue share; Radiation Therapy is climbing the fastest among clinical applications.
End User:
Customer type determines contracting structure, with institutional procurement committees leveraging volume commitments against specialized dealers while research laboratories negotiate spot purchases for preclinical development.
- Oncology Centers:Integrated cancer treatment facilities administering Erbium-169 for bone pain palliation. Japanese university hospitals and United States National Cancer Institute-designated centers concentrate demand, with direct manufacturer relationships displacing traditional distributor intermediation under centralized pharmacy committee governance.
- Research Laboratories:Academic and commercial entities developing novel Erbium-169 labeled compounds for expanded indications. Australian nuclear science facilities and Swiss radiochemistry institutes are gaining share fastest as preclinical theranostic pipelines mature beyond bone metastases into solid tumor targeting.
- Nuclear Facilities:Reactor and accelerator operators producing Erbium-169 for captive use or commercial distribution.
- Medical Device Manufacturers:Companies integrating sealed sources into implantable or external therapeutic devices.
- Quality Testing Firms:Third-party laboratories providing radiopharmaceutical assay and certification services.
Oncology Centers retain volume leadership; Research Laboratories are expanding most quickly.
Distribution Channel:
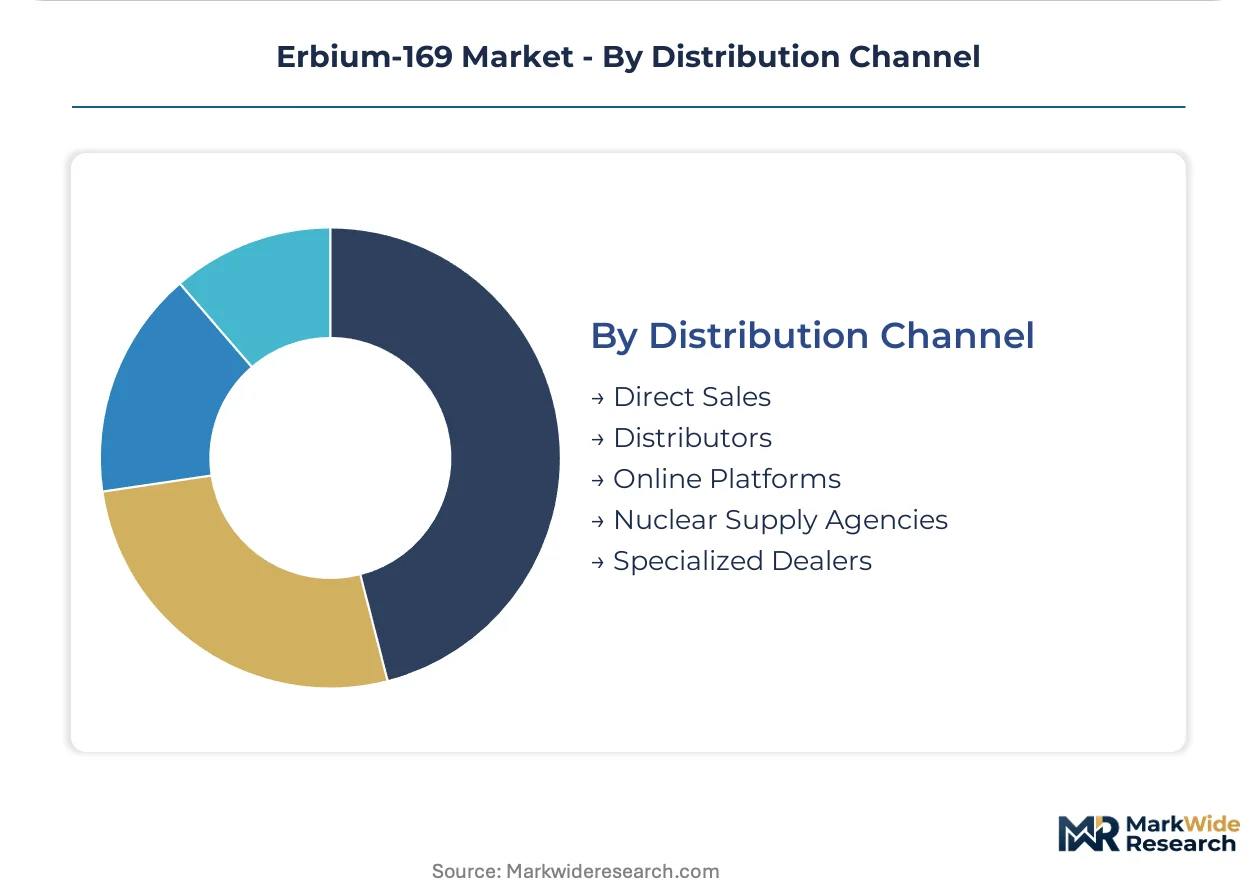
Supply concentration among reactor-dependent producers in Belgium and the Netherlands shapes channel configuration, with time-sensitive logistics favoring direct relationships over intermediated distribution.
- Direct Sales:Manufacturer-to-institution contracts for high-volume hospital networks. United States Department of Energy-funded accelerator producers and Curium's European reactor partnerships anchor this channel, with multi-year supply agreements incorporating guaranteed volume floors and price escalation clauses tied to helium-3 input costs.
- Nuclear Supply Agencies:Government-chartered entities managing strategic isotope reserves and emergency distribution. France's ANSM-coordinated national stockpile and Japan's nuclear fuel cycle organization provide supply continuity buffers against reactor maintenance outages, though procurement bureaucracies extend order-to-delivery timelines.
- Distributors:Regional intermediaries aggregating demand from smaller clinical accounts.
- Online Platforms:Digital procurement portals for standardized catalog items and reference materials.
- Specialized Dealers:Niche operators serving research and industrial segments with technical consultation.
Direct Sales retains volume leadership; Nuclear Supply Agencies are gaining share fastest amid supply security prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese university hospitals absorb Erbium-169 at premium pricing with minimal substitution elasticity, while Indian and Brazilian procurement committees exhibit acute price sensitivity toward longer-shelf alternatives like strontium-89.
United States
National Cancer Institute-designated centers drive concentrated demand for bone palliation protocols. FDA 21 CFR Part 212 governs radiopharmaceutical manufacturing compliance, extending validation cycles for new production sites. The Department of Energy funds distributed cyclotron networks across Tennessee and Missouri to reduce European reactor dependency.
Germany
Dense university-affiliated oncology networks sustain premium pricing for high-specific-activity material. Statutory health insurance reimbursement compression constrains expansion despite clinical volume. The Bavarian and Baden-Württemberg hospital clusters anchor procurement concentration for palliative radionuclide therapy.
Japan
Centralized pharmacy committees at university hospitals negotiate multi-year supply agreements with guaranteed volume floors. The national nuclear fuel cycle organization buffers supply continuity against reactor maintenance outages. Tokyo and Osaka metropolitan medical centers concentrate theranostic protocol adoption.
Switzerland
Radiochemistry institutes advance preclinical Erbium-169 labeled compounds for solid tumor indications beyond bone metastases. Swissmedic oversees radiopharmaceutical licensing with accelerated pathways for orphan disease designations. The Paul Scherrer Institute anchors accelerator-based isotope research capacity.
Australia
Nuclear science facilities gain share fastest as preclinical theranostic pipelines mature. The Therapeutic Goods Administration harmonizes with IAEA transport standards for time-sensitive isotope deliveries. Sydney and Melbourne research clusters concentrate demand for spectrum source calibration materials.
Erbium-169 Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with reactor-dependent producers and accelerator-based entrants occupying distinct competitive lanes. The upper tier commands captive isotope production and direct hospital contracting relationships. Three archetypes dominate: integrated radiopharmaceutical networks, dedicated reactor partnerships, and domestic accelerator operators. Capacity expansion through cyclotron deployment and strategic partnerships for cross-border distribution represent the primary competitive moves reshaping supply security calculations.
Among North American integrated networks, GE HealthCare exemplifies the radiopharmaceutical-distribution archetype with oncology center penetration. Curium occupies a position within the European reactor-partnership tier, sustaining supply continuity through dedicated production agreements. NorthStar Medical Radioisotopes anchors the domestic-accelerator vector, representing import-reduction strategy for United States hospital networks.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Cardinal Health |
| Curium |
| Lantheus |
| Jubilant Radiopharma |
| NorthStar Medical Radioisotopes |
| Ion Beam Applications |
| Nihon Medi-Physics |
| Others |
Pricing and Supply Chain Analysis
Cyclotron-based Erbium-169 displacing reactor-sourced supply simultaneously redistributes production geography toward United States accelerator clusters and compresses pricing premiums previously commanded by European reactor-dependent suppliers, as oncology centers gain procurement leverage through domestic sourcing alternatives.
Pricing Analysis
Multi-year service contracts anchoring lifetime value dominate Erbium-169 commercial relationships, with pricing stratifying across premium, standard, and economy tiers based on specific-activity certification and cold-chain reliability guarantees. Contract-based long-term offtake agreements incorporate helium-3 cost escalation clauses and guaranteed volume floors, while spot purchases for research-grade material face acute price sensitivity from Australian and Swiss academic laboratories. Pricing pressure stems from strontium-89 substitution in emerging markets, though Japanese university hospitals exhibit minimal elasticity due to reimbursement insulation under national health frameworks.
Supply Chain Analysis
Just-in-time production models are displacing strategic stockpiles as accelerator-based manufacturing enables patient-matched dosing schedules aligned with treatment calendars. Supply concentrates in Belgium and the Netherlands for reactor-dependent routes, while the United States and Japan anchor emerging cyclotron capacity. Raw material dependencies center on erbium-168 target material, helium-3 neutron detection systems, and specialized radiopharmaceutical packaging. Single-source vulnerability permeates aging European high-flux reactor infrastructure. Distribution runs through direct manufacturer-to-hospital contracts for oncology networks, with nuclear supply agencies providing emergency continuity buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Erbium-169 sits in early-cycle expansion as theranostic protocol adoption accelerates beyond bone palliation into solid tumor pipelines, creating penetration headroom across preclinical research segments before clinical translation matures.
For Market Incumbents: Consolidate reactor partnerships into exclusive offtake arrangements before accelerator networks achieve scale economics, while deepening backward integration into erbium-168 target production to insulate margins from raw material volatility. Curium's European reactor anchoring and GE HealthCare's North American distribution density exemplify defensive positioning against domestic accelerator entrants.
For New Entrants and Emerging Players: FDA 21 CFR Part 212 fast-track consulting services create immediate service revenue while manufacturing sites navigate 18-24 month validation cycles. White-space targets concentrate in United States Department of Energy-funded accelerator deployments across Tennessee and Missouri, plus Swiss and Australian research laboratory spot purchasing for spectrum source calibration materials. Go-to-market positioning as import-reduction partners for hospital procurement committees bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed radiopharmaceutical distributors lacking captive isotope production, presenting consolidation targets for vertical integration plays. Five-to-ten year viability hinges on theranostic reimbursement code expansion beyond palliative indications. The signal to watch is EMA orphan drug designation velocity for novel radiotherapeutic applications, which would validate pipeline optionality and accelerate regulatory review timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator Network Deployment | United States Department of Energy funding reduces European reactor dependency for hospital supply security. |
| Reactor Partnership Consolidation | Exclusive offtake agreements with Belgian and Dutch facilities lock in isotope access before decommissioning schedules bite. |
| Theranostic Pipeline Expansion | Swiss radiochemistry institutes advancing solid tumor indications validate clinical utility beyond bone metastases. |
| GMP Certification Investment | Continuous air sampling and real-time dosimetry networks satisfy EMA revised guidelines for European market access. |
| Direct Hospital Contracting | Japanese university hospital pharmacy committees disintermediate distributors through multi-year volume commitment agreements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nuclear medicine department heads, hospital pharmacy committee chairs, radiopharmaceutical manufacturing executives, cyclotron facility operators, and regulatory affairs specialists at FDA and EMA. Secondary validation drew from FDA 21 CFR Part 212 guidance documents, EMA GMP guidelines for radiolabeled compounds, IAEA transport regulation updates, hospital procurement databases, and reactor decommissioning schedules published by European nuclear agencies. Bottom-up patient-volume modeling and top-down isotope production capacity estimates were triangulated to anchor forecast integrity.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, application, end user, and distribution channel dimensions, with production pathway differentiation between reactor-neutron activation and cyclotron-proton bombardment serving as a critical industry-specific forecast input. CAGRs were derived from patient population epidemiology, theranostic protocol adoption curves, and supply capacity expansion timelines across production modalities.
Decision-makers should treat outputs as directional under assumptions of stable reimbursement coding for bone palliation and no accelerated reactor decommissioning beyond published schedules; material deviation would warrant model refresh. Revision becomes warranted when EMA orphan drug designation velocity or United States accelerator deployment funding crosses thresholds that materially alter supply geography or demand penetration trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.