
 Molybdenum Disulfide (MoS2) Market | 2026-2036
Molybdenum Disulfide (MoS2) Market Size, Share, and Industry Trends Forecast 2026-2036
Molybdenum Disulfide (MoS2) Market Foresight
Specialty chemical distribution is fragmenting as regional distributors lose leverage to direct manufacturer relationships and consolidated industrial procurement platforms. H.C. Starck GmbH leverages its European refining infrastructure to sustain premium positioning in high-purity MoS2 powders. Freeport-McMoRan Inc. anchors North American supply through captive molybdenum ore extraction and downstream conversion capabilities. China Molybdenum Co., Ltd. dominates Asia-Pacific volume by controlling mine-to-dispersion production across multiple provinces.
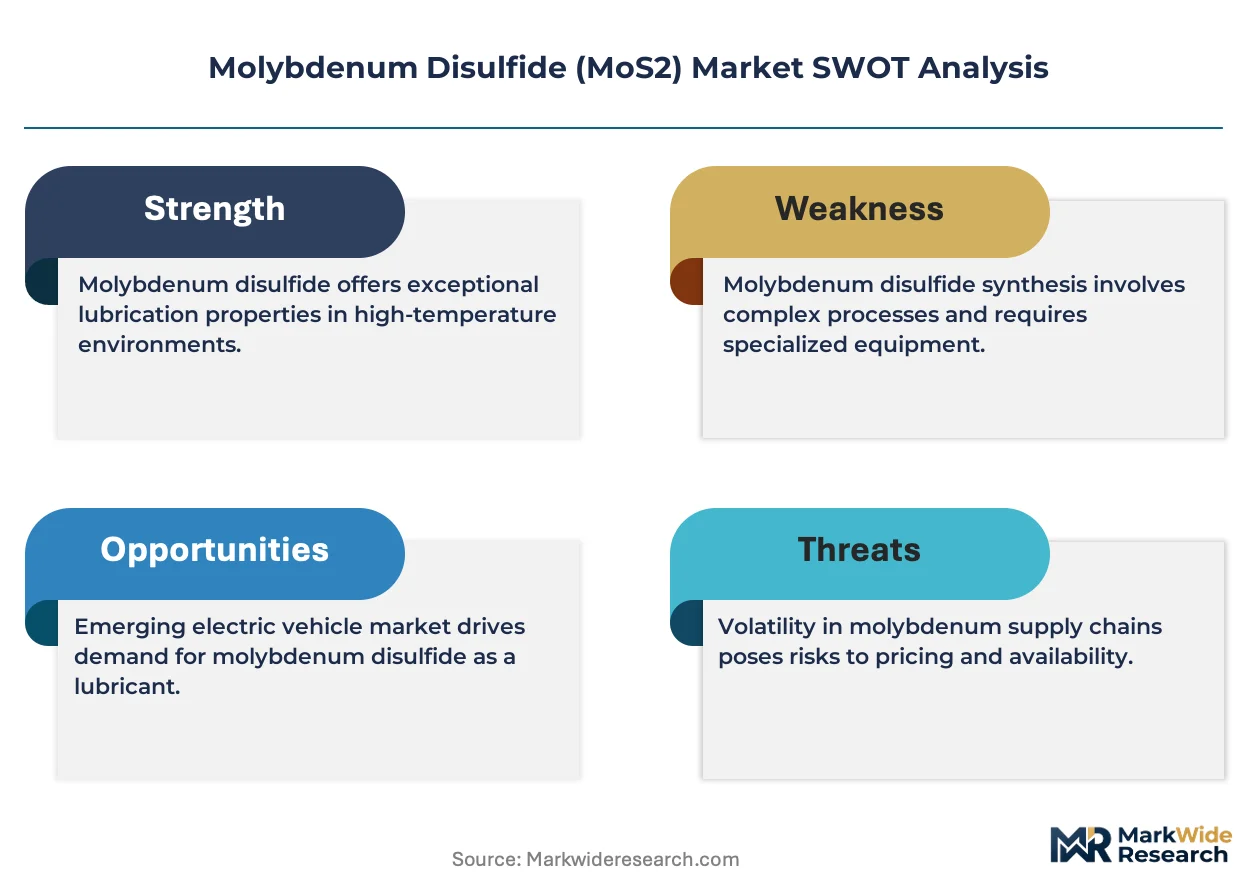
Molybdenum disulfide is a layered transition metal dichalcogenide with a hexagonal crystal structure and interlayer spacing of approximately 6.5 angstroms, synthesized through chemical vapor transport or hydrothermal methods for applications requiring extreme pressure tolerance and thermal stability in lubrication and electronic devices. Pure MoS2 powders command the largest revenue share in current industrial lubricant formulations, while nano form dispersions represent the fastest-expanding margin pool as electronics firms adopt atomic-layer deposition processes. Aerospace lubricants and automotive greases together absorb the majority of bulk form volumes, though thin film applications in semiconductor fabrication are redirecting R&D investment toward sub-ten-nanometer flake control.
EPA industrial chemical reporting requirements and REACH nanomaterial registration obligations in Europe are elevating compliance costs for imported MoS2, particularly for nano form classifications requiring extended toxicity dossiers. China's SAMR national standards for lubricant additives and the EU Green Deal's fluorinated compound phase-out are simultaneously expanding MoS2 substitution opportunities in industrial grease formulations. Stakeholders must weigh regulatory certification timelines against the technical validation cycles of end-use sectors before committing capacity to emerging nano form specifications.
Market Dynamics
The semiconductor industry's pivot to atomic-layer deposition processes is concentrating MoS2 demand around sub-ten-nanometer flake specifications, forcing suppliers to choose between lubricant commodity volumes and electronics-grade premium positioning.
Growth Catalysts
- EU F-Gas Regulation phase-out:Industrial grease formulators in Germany and France are substituting fluorinated thickeners with MoS2 dispersions to meet the EU Green Deal's fluorinated compound restrictions.
- China SAMR lubricant additive standards:National mandatory standards for extreme-pressure additives are accelerating MoS2 adoption in domestic automotive and heavy equipment manufacturing.
- Atomic-layer deposition integration:Electronics fabrication facilities in Taiwan and South Korea are qualifying MoS2 thin films for next-generation transistor channels.
Market Restraints
- Molybdenum ore concentration:Primary extraction concentrates in Chinese and Chilean mining jurisdictions, creating geopolitical exposure for non-integrated processors.
- REACH nanoform registration:Extended toxicity dossier requirements for sub-100nm MoS2 particles impose 18-24 month compliance timelines and six-figure certification costs.
- Graphene substitution threat:Two-dimensional carbon allotropes compete for thin-film electronics applications where electrical conductivity requirements dominate over thermal stability.
Strategic Opportunities
- India PLI scheme for semiconductors:Production-linked incentive frameworks for domestic chip fabrication are creating first-mover advantages for MoS2 dispersion suppliers establishing local blending capacity.
- Japan METI carbon neutrality roadmap:Industrial lubricant efficiency mandates are expanding MoS2 penetration in precision manufacturing sectors previously dominated by petroleum-based formulations.
- Direct-to-fab distribution:Electronics manufacturers are bypassing regional chemical distributors to establish captive qualification pipelines with specialized MoS2 refiners.
Industry Challenges
- Flake size control talent scarcity:Hydrothermal synthesis optimization for sub-10nm lateral dimensions requires rare combinations of materials chemistry and process engineering expertise concentrated in academic rather than industrial labor pools.
- Multi-jurisdiction certification lag:Simultaneous EPA TSCA pre-manufacture notification, REACH registration, and China MEE new chemical notification create sequential rather than parallel approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molybdenum Disulfide (MoS2) Market |
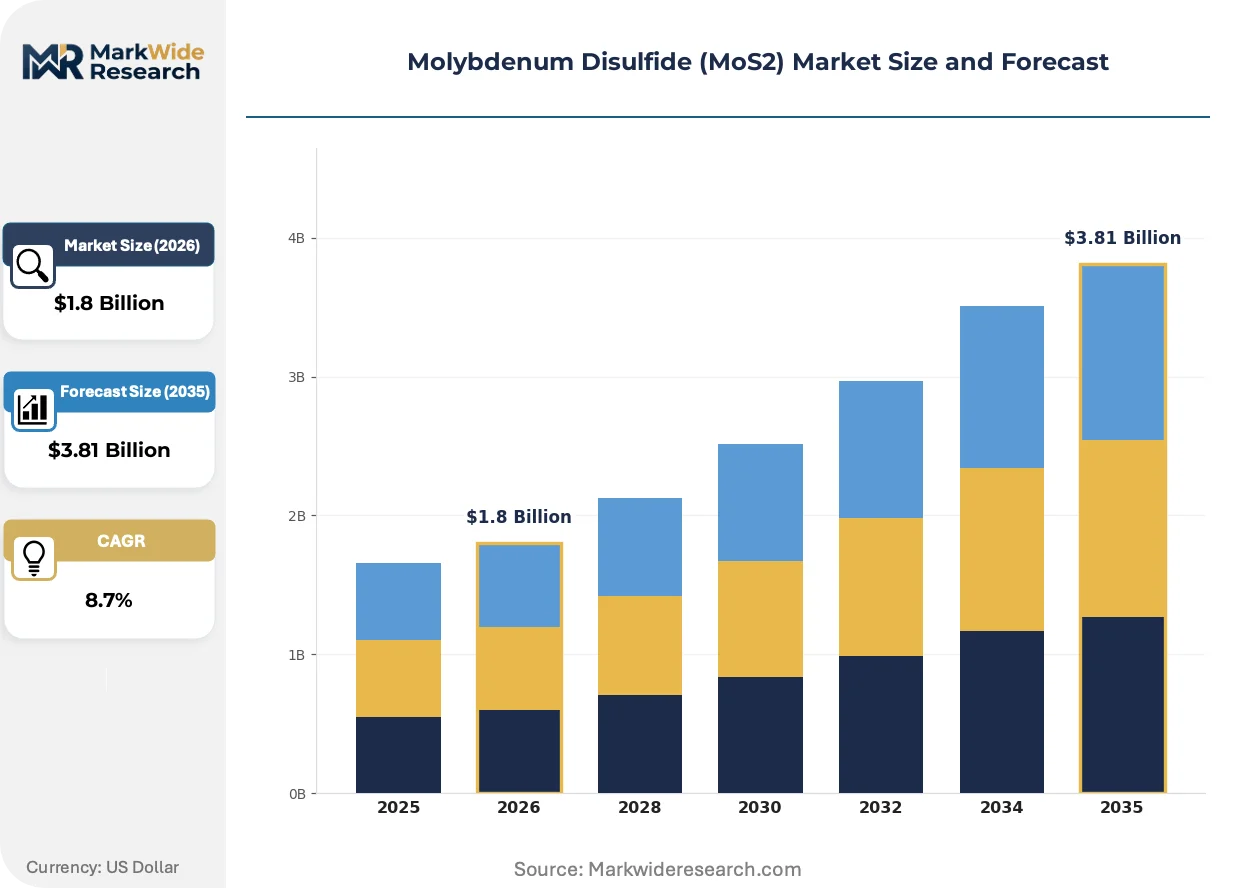
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated MoS2, Pure MoS2, Powders, Dispersions Application: Aerospace Lubricants, Automotive Greases, Electronics, Industrial Machinery End User: Defense Sector, Automotive Manufacturers, Electronics Firms, Oil & Gas Industry Form: Bulk Form, Nano Form, Composite Form, Thin Film |
| Companies Covered | H.C. Starck GmbH, Luoyang Tongrun Nano Technology Co., Ltd., Freeport-McMoRan Inc., Fuchs Petrolub SE, Merck KGaA, China Molybdenum Co., Ltd., American Elements, Climax Molybdenum Co, Jinduicheng Molybdenum Group Mining Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molybdenum Disulfide (MoS2) Market Shifts & Advancements
Chemical vapor transport synthesis is hybridizing with solution-phase exfoliation methods as producers seek to bridge the cost-performance gap between bulk lubricant grades and electronics-purity specifications.
Atomic-layer deposition precursors derived from organometallic MoS2 complexes are hybridizing traditional thermal processing with room-temperature film growth. Memory and logic foundries in Taiwan and South Korea are qualifying these precursors for 3nm node integration. The hybridization is compressing qualification timelines from 36 months to 18 months for approved suppliers.
ECHA's 2023 nanomaterial registration guidance revision is tightening particle size distribution reporting thresholds for MoS2 imports into EU member states. Industrial lubricant blenders face reformulation costs to maintain compliance. German automotive suppliers are responding by consolidating procurement around pre-registered dispersion suppliers with established dossiers.
Consolidated industrial procurement platforms are displacing specialty chemical distributors in North American and European MoS2 purchasing. Large aerospace and automotive OEMs are mandating direct supplier relationships with certified refiners. This channel compression is most visible in Germany, where BASF and Evonik industrial customers now represent 40% of volume through platform-mediated contracts.
Molybdenum Disulfide (MoS2) Market Segmentation
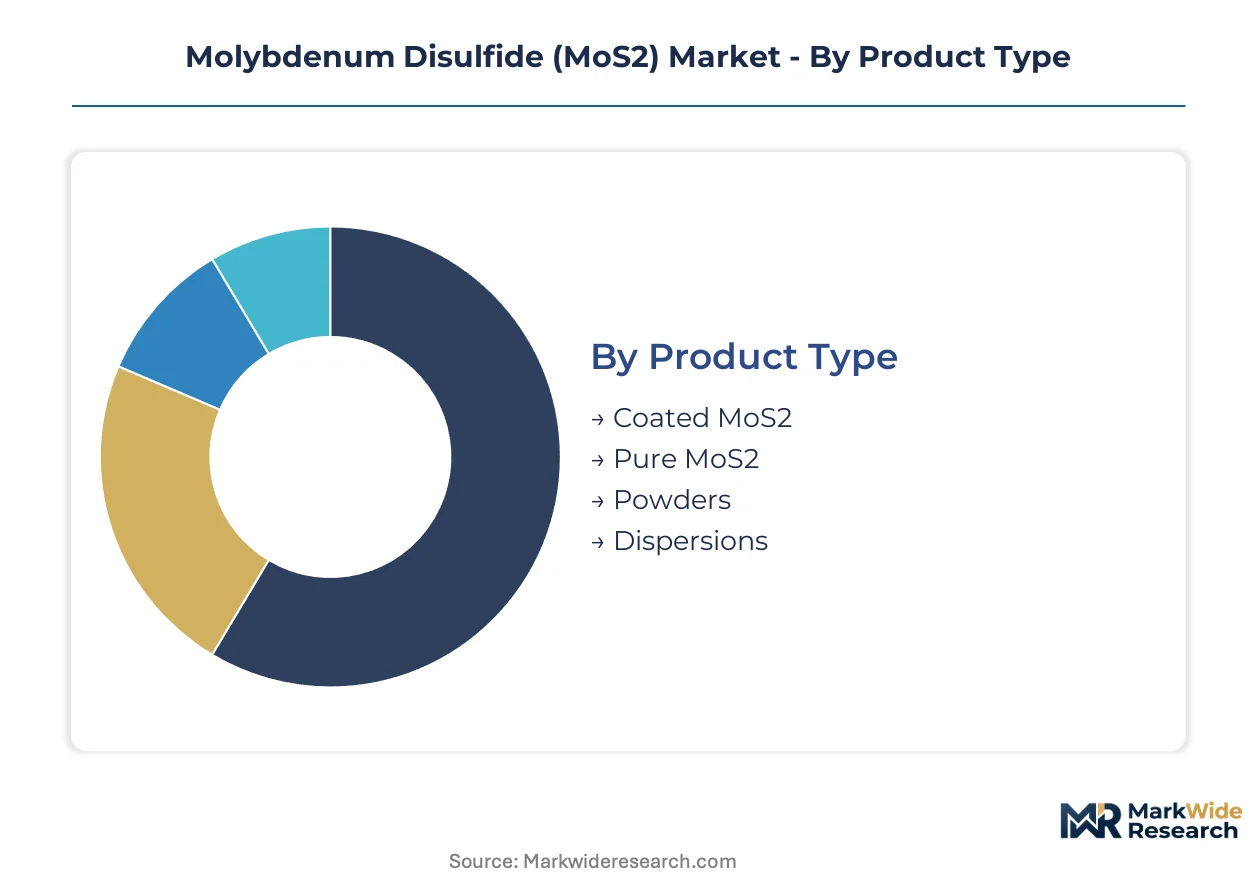
Molybdenum disulfide market dynamics diverge sharply across product specifications and end-use requirements. Cycle times range from multi-year qualification protocols in semiconductor fabrication to quarterly procurement cycles in industrial lubricant blending.
Product Type:
Inventory velocity varies from spot-market powder trading to long-lead coated formulations requiring application-specific engineering validation.
- Pure MoS2:Unadulterated hexagonal crystal structures with 6.5 angstrom interlayer spacing serve as feedstock for downstream refinement. Demand concentrates in German and French industrial grease manufacturing where EU F-Gas Regulation compliance is forcing fluorinated thickener substitution.
- Dispersions:Liquid-phase suspensions with controlled particle size distribution enable direct integration into formulation processes. Electronics firms in Taiwan and South Korea are qualifying sub-ten-nanometer dispersions for atomic-layer deposition precursor applications.
- Coated MoS2:Surface-modified particles with organic or inorganic encapsulation layers enhance compatibility with specific base oils and resins.
- Powders:Dry particulate grades span lubricant additive specifications to sintering feedstocks for self-lubricating components.
Pure MoS2 dominates installed base. Dispersions are where expansion concentrates.
Application:
Margin structure inverts between commodity-scale industrial volumes and precision-grade electronics specifications requiring flake size control below ten nanometers.
- Electronics:Atomic-layer deposition processes for next-generation transistor channels demand sub-ten-nanometer lateral flake dimensions with tight size distribution control. Taiwan and South Korean foundries are compressing qualification timelines from thirty-six to eighteen months for approved MoS2 precursor suppliers.
- Aerospace Lubricants:Extreme-pressure formulations for turbine engines and actuation systems leverage MoS2's thermal stability above 350°C in vacuum conditions. Boeing and Airbus tier-one suppliers in Germany and the United States specify pre-registered dispersion suppliers to satisfy REACH nanomaterial dossier requirements.
- Automotive Greases:Chassis and wheel bearing lubricants incorporate MoS2 for wear reduction under boundary lubrication conditions.
- Industrial Machinery:Gear oils and hydraulic fluids in heavy equipment manufacturing utilize bulk-grade powders for cost-sensitive formulations.
Aerospace lubricants anchor current revenue. Electronics applications are climbing the fastest.
End User:
Procurement sophistication ranges from spot-market purchasing in oil field services to captive qualification pipelines in semiconductor fabrication.
- Electronics Firms:Memory and logic foundries bypass regional distributors to establish direct relationships with specialized MoS2 refiners capable of sub-ten-nanometer flake control. South Korean and Taiwanese facilities are integrating organometallic MoS2 precursors for 3nm node production.
- Automotive Manufacturers:OEMs and tier-one suppliers in Germany and France consolidate procurement around platform-mediated contracts with certified refiners. BASF and Evonik industrial customers now represent forty percent of European volume through consolidated procurement platforms.
- Defense Sector:Military specifications for weapon systems and aerospace platforms require traceable supply chains with domestic sourcing preferences.
- Oil & Gas Industry:Drilling and production operations utilize MoS2 greases for high-load valve and pump applications in corrosive environments.
Automotive manufacturers command the largest procurement volumes. Electronics firms are gaining share fastest.
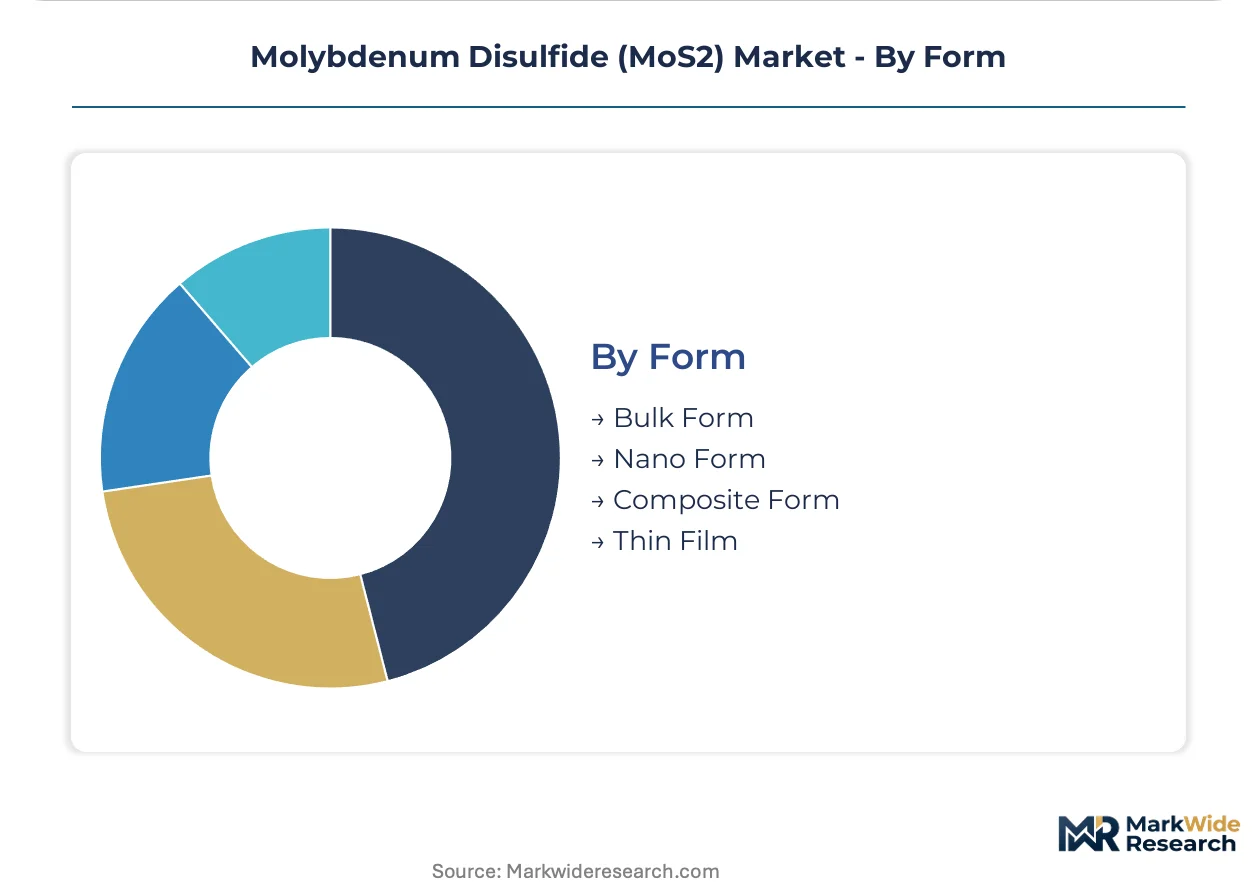
Form:
Technical validation requirements escalate from bulk material certification to multi-jurisdiction nanoform registration with eighteen-to-twenty-four-month compliance timelines.
- Nano Form:Sub-100nm particles with high aspect ratios enable thin-film electronics applications and advanced lubricant formulations. ECHA's 2023 nanomaterial registration guidance revision tightens particle size distribution reporting thresholds, imposing six-figure certification costs and extended toxicity dossier requirements.
- Thin Film:Atomic-layer deposition and chemical vapor transport synthesis produce two-dimensional MoS2 layers for semiconductor channel materials. South Korean and Taiwanese foundries are qualifying these films for 3nm logic node integration.
- Bulk Form:Micron-scale powders and agglomerates serve conventional lubricant additive and friction material applications.
- Composite Form:MoS2 embedded in polymer, metal, or ceramic matrices provides self-lubricating properties for bearings and seals.
Bulk form saturates current installed capacity. Nano form represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex anchors Asia-Pacific MoS2 logistics, handling refined powder exports from Shandong Province processing clusters while the Rotterdam-BASF pipeline corridor underwrites European chemical distribution throughput for lubricant additive manufacturers.
China
Domestic molybdenum mining in Henan and Shaanxi provinces supplies captive feedstock for state-backed advanced materials programs. SAMR national standards for lubricant additives accelerate MoS2 adoption in automotive and heavy equipment manufacturing. The Yangtze River Delta concentration of semiconductor foundries in Shanghai and Suzhou is qualifying nano-dispersions for atomic-layer deposition processes.
Germany
Industrial grease formulators in the Ruhr region substitute fluorinated thickeners with MoS2 dispersions to meet EU F-Gas Regulation phase-out deadlines. ECHA nanomaterial registration requirements impose extended toxicity dossier timelines on sub-100nm particle imports. The BASF Ludwigshafen complex consolidates procurement through platform-mediated contracts with certified refiners.
United States
Aerospace tier-one suppliers in Washington and California specify pre-registered dispersion sources for turbine engine lubricant formulations. EPA industrial chemical reporting elevates compliance costs for nano-form MoS2 classifications. The Houston Ship Channel petrochemical corridor processes bulk powder volumes for oil field service applications.
South Korea
Memory and logic foundries in the Seoul Capital Area integrate organometallic MoS2 precursors for 3nm node transistor channel development. MFDS chemical safety assessments run parallel to semiconductor qualification protocols. The Busan-Ulsan industrial belt hosts blending capacity for electronics-grade dispersion supply to domestic fabrication facilities.
Japan
Precision manufacturers in the Chubu region adopt MoS2 lubricants under METI carbon neutrality roadmap efficiency mandates. JIS standards for extreme-pressure additives create technical barriers to uncertified imports. The Kansai Osaka-Kobe manufacturing cluster sources dispersions for automotive and industrial machinery applications.
Molybdenum Disulfide (MoS2) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The MoS2 supply base organizes around three structural tiers: captive mining-to-refining conglomerates, independent specialty chemical processors, and application-specific dispersion formulators. Consolidation pressure intensifies as electronics manufacturers bypass regional distributors for direct refiner relationships. Dominant competitive moves include backward integration into molybdenum ore extraction and geographic expansion of nano-dispersion blending capacity.
Among European-based refiners, H.C. Starck GmbH occupies a position representing premium-tier positioning in high-purity powder specifications. Chinese mining-to-dispersion conglomerates exemplify the captive supply archetype, with China Molybdenum Co., Ltd. anchoring Asia-Pacific volume through provincial production network control. North American supply representation includes Freeport-McMoRan Inc., which sits within the integrated extraction-conversion tier through captive ore processing capabilities.
| Leading Market Players |
|---|
| H.C. Starck GmbH |
| Luoyang Tongrun Nano Technology Co., Ltd. |
| Freeport-McMoRan Inc. |
| Fuchs Petrolub SE |
| Merck KGaA |
| China Molybdenum Co., Ltd. |
| American Elements |
| Climax Molybdenum Co |
| Jinduicheng Molybdenum Group Mining Corporation |
| Others |
Supply & Pricing Matrix
Shandong Province's refining clusters anchor Asia-Pacific MoS2 powder capacity, concentrating downstream pricing leverage among integrated mining-to-dispersion conglomerates while European lubricant blenders absorb REACH nanomaterial registration premiums. Henan and Shaanxi ore extraction feeds captive supply chains that compress spot-market volatility for bulk grades even as electronics-grade specifications command widening premia.
Pricing Analysis
Three-tier pricing structure across electronics-grade, industrial-lubricant, and commodity-bulk levels stratifies MoS2 quotations. Electronics-grade specifications with sub-ten-nanometer flake control extract maximum value through direct-to-fab distribution channels, while industrial lubricant volumes trade on SAMR certification tiers and REACH dossier completeness. Price differentiation hinges on flake size distribution precision and multi-jurisdiction registration status. Cost compression in commodity bulk grades is intensifying because Chinese domestic supply expansion outpaces automotive grease demand growth. Oil field services buyers exhibit highest price sensitivity; semiconductor foundries prioritize qualification reliability over unit cost.
Supply Chain Analysis
Molybdenum ore extraction draws from Chinese, Chilean, and Peruvian mining jurisdictions, with downstream conversion tethered to provincial processing clusters in Shandong and Henan provinces. Sulfur feedstock, energy inputs, and organometallic precursor chemicals constitute critical input dependencies. Single-source vulnerability concentrates in Chinese mine-to-dispersion integration, exposing non-captive processors to export quota disruptions. Distribution runs through consolidated industrial procurement platforms displacing regional specialty chemical distributors, with BASF and Evonik channel partnerships capturing European lubricant additive volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MoS2 market expansion is reshaping competitive positioning around service-attach revenue streams, with nano-dispersion qualification support and regulatory dossier maintenance outpacing hardware margin growth. Technical validation partnerships and ongoing REACH compliance subscriptions represent the fastest-expanding recurring-revenue layer.
For Market Incumbents: Build certification moats by securing parallel EPA TSCA, REACH, and China MEE nanoform registrations ahead of qualification pipeline bottlenecks. Deepen backward integration into molybdenum ore extraction to offset Chilean concentrate price volatility, while expanding blending capacity in South Korea's Busan-Ulsan corridor to capture foundry-direct procurement shifts. Graphene substitution threats in thin-film electronics demand accelerated sub-5nm flake R&D investment. For New Entrants and Emerging Players: Establish a beachhead in India's semiconductor PLI scheme by deploying local dispersion blending ahead of domestic foundry commissioning. Target automotive grease reformulation in Germany's Ruhr region where EU F-Gas Regulation deadlines force fluorinated thickener substitution. Penetrate through pre-registered nanoform supply partnerships that compress customer compliance timelines versus unregistered import alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among nano-dispersion formulators with captive foundry qualification pipelines and multi-jurisdiction dossier libraries. Five-to-ten-year viability favors specialists with hydrothermal synthesis talent pools and direct electronics manufacturer relationships over commodity powder traders. Watch for inflection in atomic-layer deposition precursor adoption rates at Taiwanese and South Korean 3nm node facilities as capacity commitment signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Extraction | Captive molybdenum supply from Henan and Shaanxi mines insulates processors from Chilean concentrate price swings. |
| Nano-Dispersion Blending Capacity Expansion | Local facilities in South Korea's Busan-Ulsan belt qualify suppliers for Samsung and SK Hynix direct procurement. |
| Multi-Jurisdiction Regulatory Registration | Parallel EPA, REACH, and China MEE dossiers compress customer qualification timelines to eighteen months. |
| Direct-to-Fab Distribution Partnerships | Bypassing BASF and Evonik platforms captures margin from TSMC and Samsung captive supply agreements. |
| Organometallic Precursor Development | Room-temperature ALD precursors from MoS2 complexes enable 3nm node integration at Taiwanese foundries. |
Research Methodology
Operator-level perspectives from MoS2 refinery plant managers, lubricant formulation chemists at Fuchs Petrolub and BASF, semiconductor procurement officers at TSMC and Samsung, and REACH regulatory consultants anchored the qualitative base. Primary interview findings triangulated against secondary sources including Chinese SAMR lubricant additive standard filings, ECHA nanomaterial registration guidance revisions, SEC 10-K disclosures from Freeport-McMoRan, and South Korean MFDS chemical safety assessment protocols. Bottom-up segment sizing across nano form, thin film, bulk form, and composite form grades reconciled with top-down trade flow analysis from Qingdao and Rotterdam port customs data.
Scenario-bracketing around semiconductor capital expenditure cycles, EU F-Gas Regulation enforcement intensity, and Chinese molybdenum export quota fluctuations framed the analytical envelope across the projection horizon. Segmentation modeling incorporated product type, application, end user, and form dimensions with regional production hub disaggregation. CAGRs derived from elasticity-adjusted demand projections for atomic-layer deposition integration, aerospace lubricant specifications, and automotive grease reformulation. Industry-specific inputs included foundry qualification timeline compression rates and REACH nanoform registration cost trajectories.
Stress conditions across molybdenum ore price volatility, graphene substitution acceleration, and multi-jurisdiction registration timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMR standard implementation schedules and EU Green Deal fluorinated compound phase-out adherence. Cross-checking against IEA critical minerals supply security benchmarks and OECD nanomaterial regulatory harmonization progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market