
 Japan Formic Acid Market | 2026-2036
Japan Formic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Formic Acid Market Insights
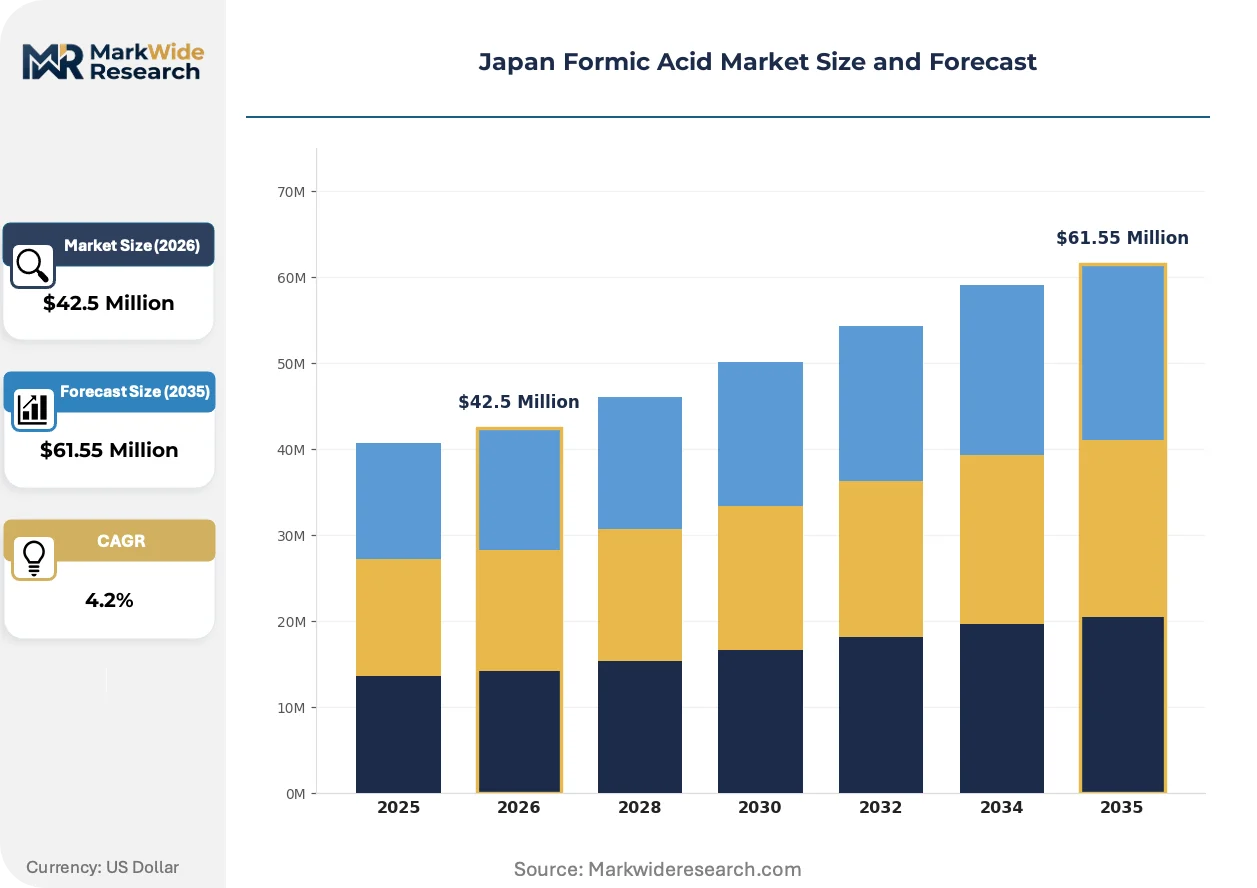
Green methanol-to-formic acid electrosynthesis is reshaping production economics for Japanese chemical suppliers. Nacalai Chemicals leverages captive laboratory distribution to sustain margins in reagent-grade segments. Kanto Chemical Co. anchors East Asian supply relationships through its Chiba-based logistics infrastructure. MITSUBISHI GAS CHEMICAL dominates industrial-grade volumes by controlling methanol feedstock access across its Kashima operations.
Formic acid (HCOOH, CAS 64-18-6) is the simplest carboxylic acid, manufactured industrially via methyl formate hydrolysis or carbonylation of methanol, with specifications typically requiring purity above 85 percent for industrial applications and above 99 percent for reagent and pharmaceutical grades. The compound functions primarily as an acidulant, reducing agent, and preservative across leather processing, silage treatment, and organic synthesis. Industrial Grade commands the largest volume share due to leather tanning and rubber coagulation demand from Osaka-Kobe manufacturing belts. Pharmaceutical Grade extracts premium pricing from Tokyo-Yokohama pharmaceutical clusters requiring USP-compliant certification. Reagent Grade competes on specification breadth rather than tonnage, with academic and analytical laboratories driving batch fragmentation.
METI enforces Chemical Substances Control Law (CSCL) reporting for formic acid handlers, while JIS standards govern container specifications and transport classification. The Fire Service Act, administered by municipal fire authorities, constrains storage volumes and facility siting near urban centers. PMDA oversight of pharmaceutical-grade material tightens impurity profiling requirements for API manufacturing inputs. Stakeholders must monitor METI's evolving carbon accounting rules for chemical production, as feedstock origin disclosure will soon differentiate domestic from import-sourced material in procurement decisions.
Market Dynamics
Green methanol-to-formic acid electrosynthesis is compressing legacy carbonylation economics and forcing Kashima-based producers to reconfigure feedstock sourcing strategies.
Growth Catalysts
- CSCL Purity Mandates:METI's tightened Chemical Substances Control Law reporting requirements are accelerating demand for reagent-grade specifications in Tokyo-Yokohama pharmaceutical corridors.
- Silage Preservation:Hokkaido dairy cooperatives are expanding formic acid uptake for fodder acidification as domestic livestock operations scale feedstock security programs.
- Chiba Logistics Infrastructure:Kanto Chemical Co.'s captive distribution networks are reducing lead times for East Asian specialty chemical procurement.
Market Restraints
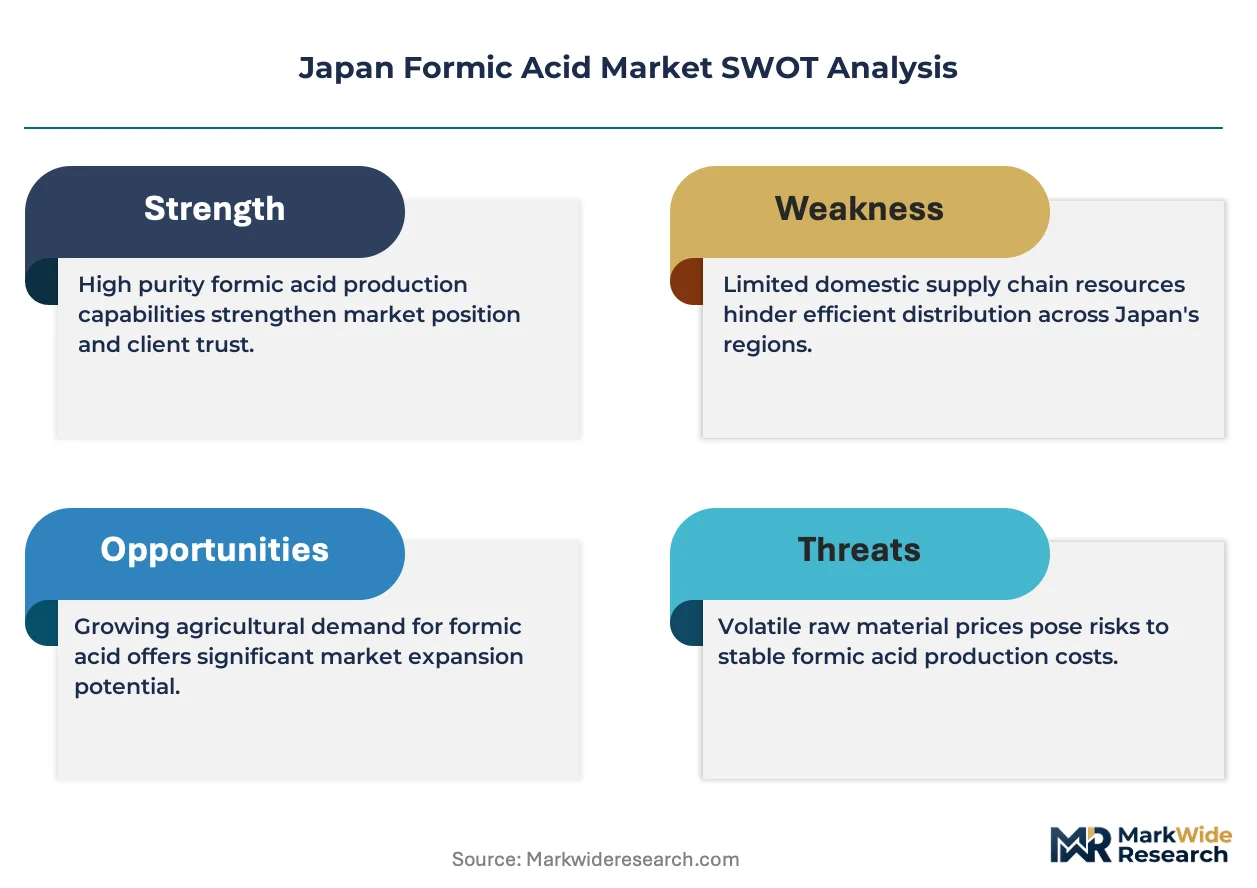
- Methanol Feedstock Volatility:Industrial-grade producers remain exposed to naphtha-linked methanol pricing swings that compress margin stability at Kashima crackers.
- Fire Service Act Constraints:Municipal fire authorities restrict storage volumes near Osaka-Kobe urban centers, forcing inventory fragmentation across satellite facilities.
- Acetic Acid Substitution:Leather processors in the Hanshin belt are trialing acetate buffers for pH adjustment in selected tanning stages.
Strategic Opportunities
- Shikoku Underpenetration:Specialty chemical distributors have established limited presence in Tokushima and Ehime prefectures, creating whitespace for reagent-grade positioning.
- Carbon Accounting Differentiation:METI's emerging feedstock origin disclosure rules will reward domestic electrosynthesis against import-sourced material in procurement decisions.
- API Manufacturing Integration:PMDA-compliant pharmaceutical-grade supply contracts are converging with Tokyo Bay cluster expansion in active pharmaceutical ingredient synthesis.
Industry Challenges
- Electrochemical Engineering Talent:Green methanol-to-formic acid pilot operations face recruitment gaps for membrane electrolyzer specialists familiar with carbon dioxide reduction kinetics.
- JIS Container Certification Timelines:New transport classification requirements are extending qualification periods for multi-modal shipment approvals.
- Legacy Hydrolysis Asset Stranding:Methyl formate route facilities face integration complexity with carbon capture retrofit requirements under evolving METI guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Formic Acid Market |
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $61.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Textile Processing, Leather Tanning, Rubber Coagulation, Agricultural Preservatives, Cleaning Agents End User Industry: Chemical Manufacturers, Agriculture Suppliers, Textile Producers, Pharmaceutical Companies Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Bottles |
| Companies Covered | Nacalai Chemicals, Ltd., Kanto Chemical Co. Inc., KOEI CHEM, Anhui Asahi Kasei Chemical Co. Ltd., Junsei Chemical Co., Ltd., Tokyo Chemical Industry Co., Ltd., FUJIFILM Wako Pure Chemical Corporation, BASF SE, MITSUBISHI GAS CHEMICAL COMPANY, INC., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Formic Acid Market Trends and Innovations
Production economics and regulatory compliance are converging to reshape competitive positioning across Japan's formic acid value chain.
Electrochemical carbon dioxide reduction to formic acid is rendering obsolete conventional methyl formate hydrolysis for mid-scale pharmaceutical-grade batches. Tokyo-Yokohama API manufacturers are piloting membrane electrolyzer installations to secure captive supply chains. This technology is compressing the cost premium between industrial and reagent grades while reducing Scope 3 emissions exposure.
METI's Chemical Substances Control Law revisions are mandating enhanced purity documentation for handlers above specified volume thresholds. The regulation is forcing Osaka-Kobe leather processors to upgrade impurity profiling capabilities or exit pharmaceutical-adjacent supply tiers. Reagent-grade distributors are responding by consolidating laboratory certification services into bundled procurement contracts.
Buyer concentration in the Kanto industrial corridor is compressing switching cycles for specialty chemical supply agreements. Pharmaceutical clusters are unbundling after-sales technical support from base chemical pricing, forcing Nacalai Chemicals and competitors to price specification breadth separately from logistics services. This pattern is most visible in Chiba and Ibaraki prefectures where Tokyo Bay chemical parks anchor procurement volumes.
Japan Formic Acid Market Segmentation
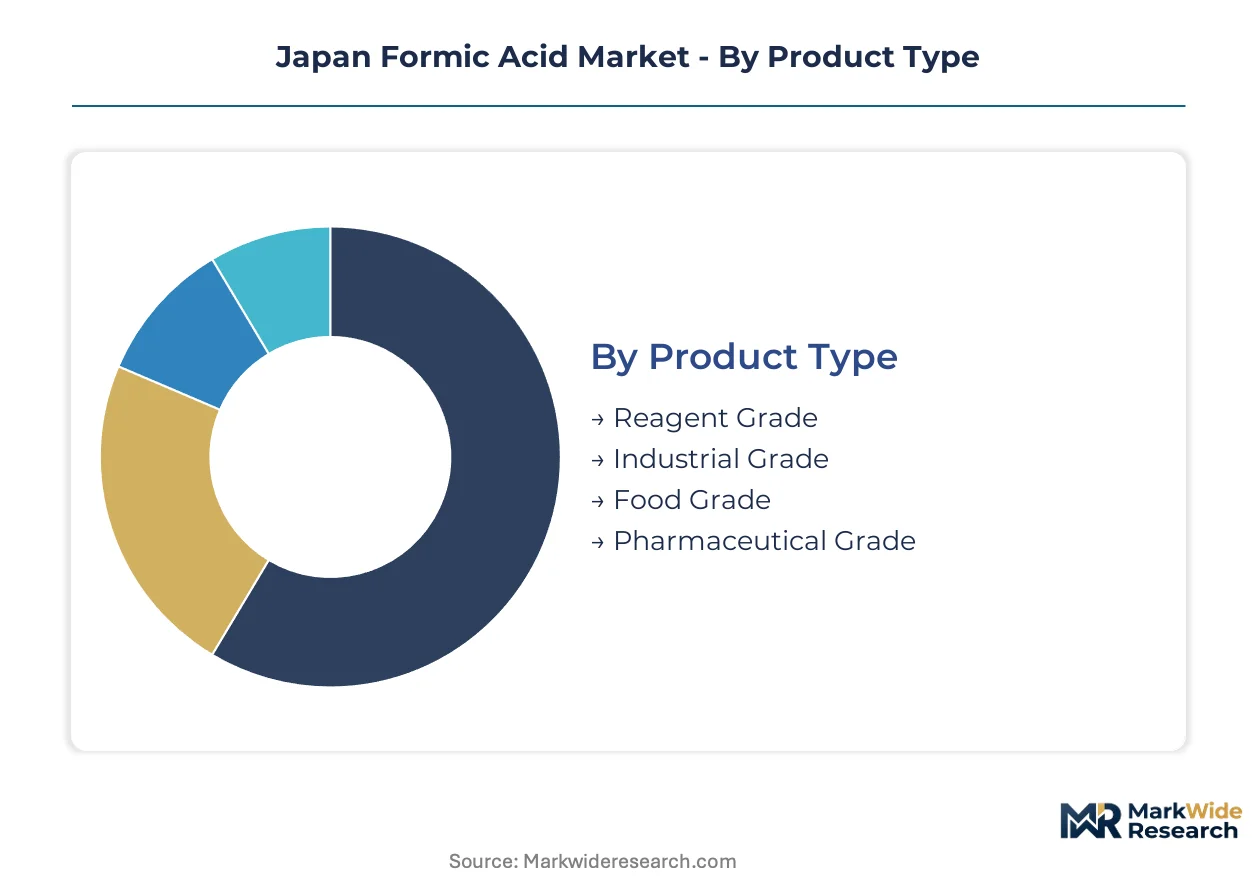
Segmentation in Japan's formic acid market reveals how technical service intensity varies dramatically across purity tiers and end-use applications. Pharmaceutical and reagent-grade buyers demand specification documentation and impurity profiling that industrial-grade leather processors rarely require.
Product Type:
After-sales technical support intensity escalates sharply with purity certification requirements, creating divergent margin structures across grade tiers.
- Pharmaceutical Grade:USP-compliant material demands exhaustive impurity profiling and Certificate of Analysis documentation for every batch. Tokyo-Yokohama API manufacturers require dedicated technical liaison support during PMDA compliance reviews.
- Reagent Grade:Academic and analytical laboratories drive specification breadth rather than tonnage, with Nacalai Chemicals bundling laboratory certification services into procurement contracts to defend positioning.
- Industrial Grade:Osaka-Kobe leather processors prioritize volume reliability over documentation depth.
- Food Grade:FSSAI-aligned importers service limited specialty fermentation applications.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is climbing the fastest as Tokyo Bay API clusters expand.
Application:
Cost tier stratification separates commodity chemical buyers from specialty processors willing to absorb premium pricing for certified supply chains.
- Agricultural Preservatives:Hokkaido dairy cooperatives are expanding formic acid uptake for silage acidification as domestic livestock operations prioritize feedstock security programs over import dependency.
- Leather Tanning:Hanshin belt tanneries consume industrial-grade volumes for pH adjustment and deliming operations, though acetic acid substitution trials threaten formic acid's incumbent position in selected process stages.
- Rubber Coagulation:Osaka-Kobe manufacturing belts anchor steady demand from latex processing facilities.
- Textile Processing:Dyeing auxiliaries and pH buffering applications concentrate in Nagoya-based synthetic fiber operations.
- Cleaning Agents:Industrial maintenance and equipment sanitation applications serve fragmented facility management procurement.
By volume, Leather Tanning leads. By growth pace, Agricultural Preservatives is gaining share fastest amid Hokkaido dairy expansion.
End User Industry:
Customer type determines whether procurement prioritizes logistics reliability or technical specification depth.
- Pharmaceutical Companies:Tokyo-Yokohama clusters unbundle after-sales technical support from base chemical pricing, forcing distributors to price specification breadth separately from logistics services.
- Chemical Manufacturers:Specialty synthesis operations in the Kanto industrial corridor drive reagent-grade fragmentation through batch-scale procurement patterns.
- Agriculture Suppliers:Hokkaido cooperative procurement concentrates seasonal demand spikes that strain Chiba-based distribution infrastructure.
- Textile Producers:Nagoya synthetic fiber operations maintain stable offtake with limited service intensity requirements.
By volume, Chemical Manufacturers lead. By growth pace, Pharmaceutical Companies is expanding most quickly.
Packaging Type:
Supply concentration in the Kanto corridor shapes container configuration preferences and multi-modal shipment economics.
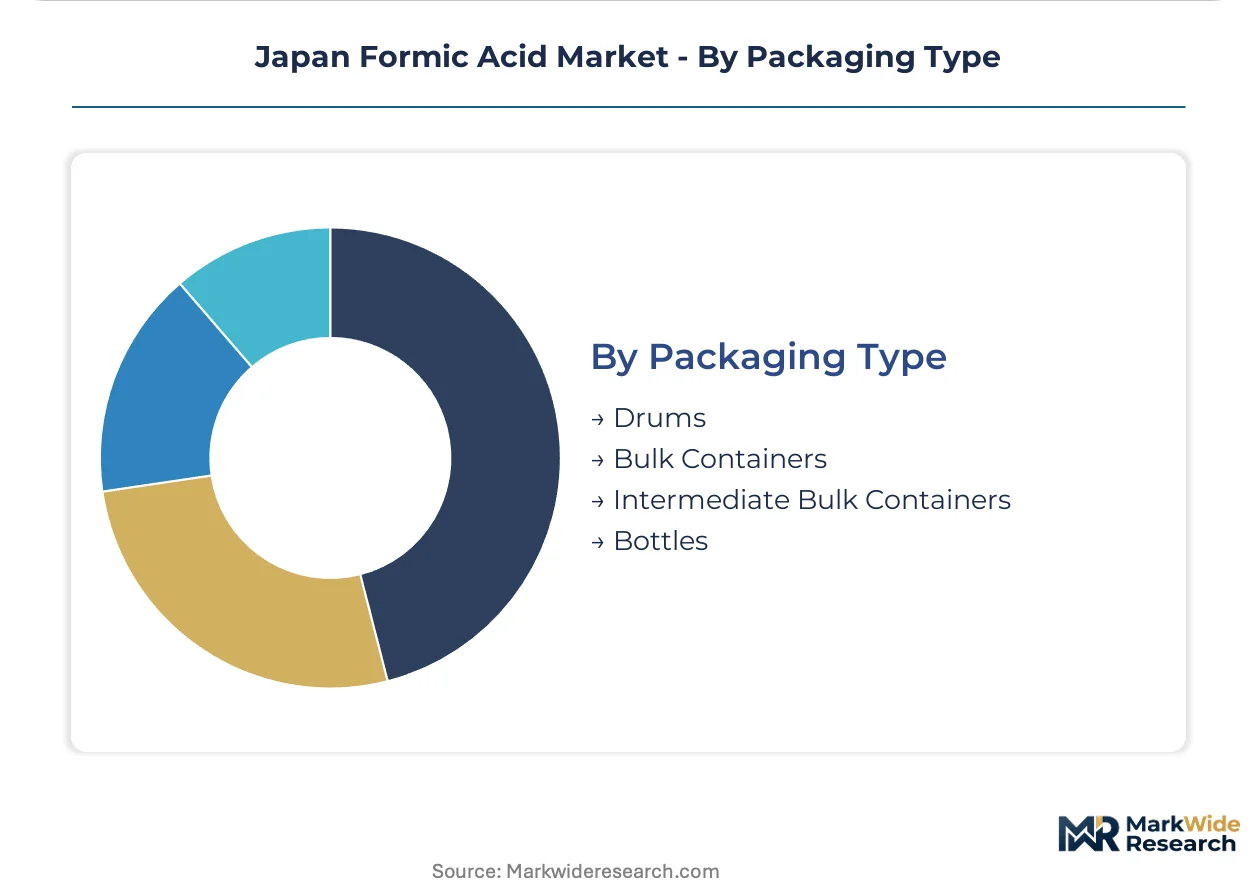
- Intermediate Bulk Containers:Tokyo Bay chemical parks favor IBC configurations that balance handling efficiency with Fire Service Act storage volume constraints near urban centers.
- Bulk Containers:Kashima crackers and methanol-integrated operations prefer rail-served bulk receipt to minimize handling stages.
- Drums:Leather processors in Osaka-Kobe maintain drum-based inventory for operational flexibility.
- Bottles:Laboratory and analytical applications in academic corridors drive small-format demand.
By volume, Bulk Containers lead. By growth pace, Intermediate Bulk Containers is climbing the fastest as Tokyo Bay clusters optimize handling economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and specialty chemical buyers concentrate procurement decisions in three industrial corridors, with leather processors and agricultural cooperatives anchoring demand in peripheral prefectures.
Kanto/Tokyo
API manufacturers in the Tokyo-Yokohama corridor drive pharmaceutical-grade consumption through PMDA-compliant supply contracts. METI's Chemical Substances Control Law revisions mandate enhanced purity documentation for handlers above volume thresholds, forcing distributors to upgrade certification capabilities. Chiba-based logistics infrastructure reduces lead times for East Asian specialty chemical procurement.
Kansai/Osaka
Hanshin belt tanneries consume industrial-grade volumes for pH adjustment and deliming operations in leather processing. Municipal fire authorities restrict storage volumes near urban centers under the Fire Service Act, forcing inventory fragmentation across satellite facilities. Osaka-Kobe manufacturing belts anchor steady rubber coagulation demand from latex processing facilities.
Chubu/Nagoya
Synthetic fiber operations maintain stable formic acid offtake for dyeing auxiliaries and pH buffering applications. Textile producers in this corridor exhibit limited service intensity requirements compared to pharmaceutical buyers. Regional chemical distributors serve fragmented facility management procurement for cleaning agent applications.
Hokkaido
Dairy cooperatives are expanding formic acid uptake for silage acidification as domestic livestock operations prioritize feedstock security programs. Seasonal demand spikes strain distribution infrastructure during peak agricultural windows. Agricultural preservative applications represent the fastest-growing demand vector outside industrial chemical corridors.
Kyushu
Industrial chemical demand remains underdeveloped relative to northern prefectures, with limited specialty chemical distributor presence. Legacy manufacturing facilities show slower adoption of reagent-grade specifications compared to Kanto-based operations. Regional buyers rely on Chiba and Osaka supply nodes for non-bulk procurement.
Japan Formic Acid Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct capability tiers. MITSUBISHI GAS CHEMICAL dominates industrial-grade volumes through methanol feedstock control at Kashima operations. Nacalai Chemicals leverages captive laboratory distribution to defend margins in reagent-grade segments. Kanto Chemical Co. anchors East Asian supply relationships through Chiba-based logistics infrastructure. Strategic moves center on carbon accounting differentiation under emerging METI feedstock origin disclosure rules and electrochemical production technology licensing.
Within the domestic specialist tier, Nacalai Chemicals and Kanto Chemical Co. exemplify laboratory-centric distribution models that bundle certification services into procurement contracts. MITSUBISHI GAS CHEMICAL occupies the integrated industrial-grade position, representing the methanol-carbonylation archetype that faces pressure from green electrosynthesis economics. Among reagent-grade specialists, Tokyo Chemical Industry Co. and Junsei Chemical Co. sit within the specification-breadth competitive vector where academic and analytical laboratories drive batch fragmentation. These three archetypes—integrated feedstock controller, laboratory distributor, and specification specialist—capture the competitive structure visible in company naming patterns and regional positioning.
| Leading Market Players |
|---|
| Nacalai Chemicals, Ltd. |
| Kanto Chemical Co. Inc. |
| KOEI CHEM |
| Anhui Asahi Kasei Chemical Co. Ltd. |
| Junsei Chemical Co., Ltd. |
| Tokyo Chemical Industry Co., Ltd. |
| FUJIFILM Wako Pure Chemical Corporation |
| BASF SE |
| MITSUBISHI GAS CHEMICAL COMPANY, INC. |
| Others |
Pricing and Supply Chain Analysis
Methanol feedstock concentration at Kashima crackers anchors margin pools downstream in reagent-grade and pharmaceutical-grade tiers where certification premiums offset commodity volatility. Buyers in the Tokyo-Yokohama corridor absorb higher unit costs for PMDA-compliant documentation while Osaka-Kobe leather processors negotiate volume discounts tied to naphtha-linked indexation.
Pricing Analysis
Cost-plus contracts with methanol price indexation dominate industrial-grade procurement from MITSUBISHI GAS CHEMICAL's Kashima operations. Price differentiation rests on USP certification grade and after-sales technical support bundling. Pricing pressure stems from green electrosynthesis pilots compressing legacy carbonylation premiums. Pharmaceutical companies show least price sensitivity; leather tanneries exhibit highest sensitivity to methanol cost pass-through.
Supply Chain Analysis
Contract manufacturing concentration sits with MITSUBISHI GAS CHEMICAL for industrial-grade carbonylation and emerging electrosynthesis specialists for pharmaceutical-grade batches. Geographic supply concentration spans Japan's Kashima corridor, Chinese methanol import nodes, and South Korean specialty chemical distributors. Raw material dependencies include methanol feedstock, carbon monoxide for carbonylation, and membrane electrolyzer components. Single-source vulnerability concentrates in methanol-integrated crackers. Distribution runs through Chiba-based logistics hubs serving Kanto pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrolyzer engineering talent scarcity constrains green production scale-up, creating asymmetric advantage for incumbents with captive R&D pipelines over entrants dependent on external hiring.
For Market Incumbents: Entrench control over methanol feedstock access at Kashima while upgrading impurity profiling capabilities to defend against electrosynthesis substitution in pharmaceutical-grade tiers. Acquire membrane electrolyzer specialists before talent scarcity intensifies. Prioritize PMDA certification investment to lock in Tokyo Bay API manufacturing contracts. For New Entrants and Emerging Players: Establish a beachhead in Shikoku's underpenetrated reagent-grade market where distributor presence remains limited. Target Tokushima and Ehime prefectures with specification-breadth positioning for academic laboratories. Lead with bundled laboratory certification services to differentiate from established Kanto distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with laboratory-centric distributors holding captive East Asian supply relationships. Long-term viability hinges on electrosynthesis technology licensing positions and METI carbon accounting compliance infrastructure. Monitor membrane electrolyzer pilot announcements as inflection indicator for green production economics tipping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstock | MITSUBISHI GAS CHEMICAL locks in margin control against naphtha volatility at Kashima crackers. |
| Green Electrosynthesis Licensing | Carbon dioxide reduction technology transfers reshape pharmaceutical-grade production economics in Tokyo Bay. |
| PMDA Certification Investment | USP-compliant impurity profiling capabilities secure API manufacturing supply contracts from Tokyo-Yokohama clusters. |
| Shikoku Distribution Expansion | Whitespace penetration in Tokushima and Ehime builds reagent-grade positioning away from saturated Kanto corridors. |
| Carbon Accounting Compliance Infrastructure | METI feedstock origin disclosure readiness differentiates domestic electrosynthesis against import-sourced material. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, JIS standard documentation, and customs trade data. Plant managers at Kashima crackers, procurement leads at Osaka-Kobe tanneries, distribution channel partners in Chiba, and technical R&D directors at pharmaceutical-grade producers provided operational perspective. Bottom-up volume triangulation against top-down value estimation validated segment-level outputs.
Forecast inputs include grade tier stratification, end-use industry demand patterns, packaging format evolution, and regional production hub shifts across the projection horizon. CAGRs derive from modeled production capacity expansion, regulatory compliance cost trajectories, and feedstock price scenario analysis. Electrosynthesis technology cost curves and METI carbon accounting implementation timelines inform long-run grade premium compression assumptions.
Stress conditions across methanol price volatility bands, electrosynthesis scale-up delays, and CSCL enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology diffusion rates and regulatory implementation cadence. Quarterly review of membrane electrolyzer pilot announcements, METI carbon accounting rulemaking, and Chiba logistics capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Enzyme Substrates Market