
 Preformulation Intermediates Market | 2026-2036
Preformulation Intermediates Market Size, Share, and Industry Trends Forecast 2026-2036
Preformulation Intermediates Market Analytics
Active pharmaceutical ingredient refinement is reconfiguring margin pools across the preformulation value chain, pulling profitability upstream from finished-dose manufacturing into early-phase chemical characterization and salt-selection services. Lonza Group AG leverages its Swiss-US manufacturing footprint to dominate high-potency API preformulation for oncology programs. WuXi AppTec Co., Ltd. sustains cost-competitive chemistry through its Shanghai-Suzhou corridor, while Thermo Fisher Scientific Inc. anchors North American demand with integrated analytical-to-GMP pathways.
Preformulation intermediates comprise raw and processed chemical entities—salts, polymorphs, co-crystals, and amorphous dispersions—subjected to solubility, stability, and permeability profiling before final dosage design, with particle size distribution and crystallinity serving as critical quality parameters that determine bioavailability outcomes. The active pharmaceutical ingredients segment leads value capture due to patent-cliff pressures forcing sponsors to optimize new molecular entities faster, while the contract manufacturing organization end-user channel represents the fastest-growing demand pool as pharmaceutical companies outsource early-phase risk. Pharmaceutical grade specifications command premium positioning over industrial and technical grades because regulatory filings require certified impurity profiles and validated analytical methods.
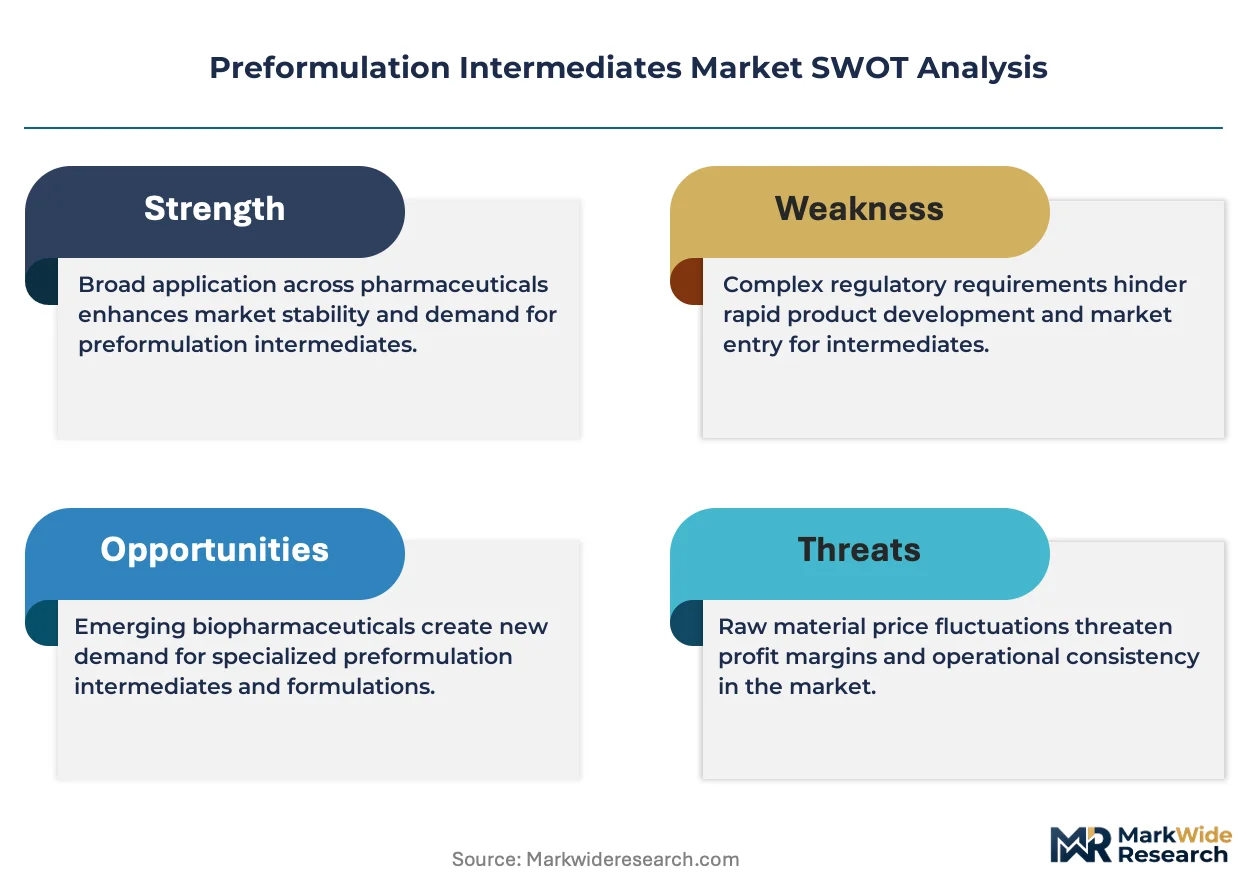
The FDA enforces ICH Q1A-Q1F stability guidelines that mandate forced-degradation studies for all preformulation batches, directly shaping analytical service demand and documentation standards for US-market submissions. EMA's REACH-aligned substance registration requirements and the EU's MDR traceability mandates impose parallel compliance burdens on European development programs. Stakeholders must monitor how FDA's evolving Real-World Evidence framework and EMA's accelerated assessment pathways reshape the speed-versus-rigor trade-off in preformulation investment decisions.
Market Dynamics
The FDA's Quality by Design mandate is compressing development timelines while elevating documentation burdens, forcing sponsors to front-load analytical investment before clinical entry and reshaping how contract development capacity gets allocated across geographies.
Growth Catalysts
- ICH Q8-Q12 adoption:The FDA's guideline framework now requires systematic documentation of critical quality attributes, expanding analytical service contracts for preformulation salt selection and polymorph screening.
- Oncology pipeline concentration:High-potency API programs are multiplying, driving specialized containment infrastructure demand for cytotoxic intermediate characterization.
- CDMO outsourcing acceleration:Pharmaceutical sponsors are transferring early-phase chemical risk to contract partners, concentrating demand in Massachusetts and North Carolina service clusters.
Market Restraints
- Specialized raw material concentration:High-purity solvents and reference standards for forced-degradation studies depend on limited German and Swiss suppliers, creating single-source vulnerability.
- Regulatory documentation friction:EMA's REACH-aligned substance registration requirements impose parallel compliance burdens that extend European program timelines without accelerating approval probability.
- Amorphous dispersion stability limits:Polymer-based solid dispersions face inherent recrystallization risks that constrain their applicability to high-dose compounds, restricting formulation options.
Strategic Opportunities
- India's CDSCO pathway alignment:India's regulatory convergence with ICH standards is opening inspection-ready manufacturing capacity for US and EU sponsor programs.
- Continuous manufacturing integration:Real-time process analytical technology is converging with preformulation design, enabling direct translation of solubility data into production parameters.
- Real-World Evidence frameworks:The FDA's evolving post-market data requirements create demand for preformulation documentation that supports later label expansion and lifecycle management.
Industry Challenges
- Pharmaceutical polymorphism expertise scarcity:Qualified crystallographers capable of predicting and controlling form transitions during scale-up remain concentrated in limited academic and industrial centers.
- Cross-functional integration complexity:Bridging preformulation analytical data into formulation development and regulatory submission systems requires customized data architecture that many mid-tier sponsors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preformulation Intermediates Market |
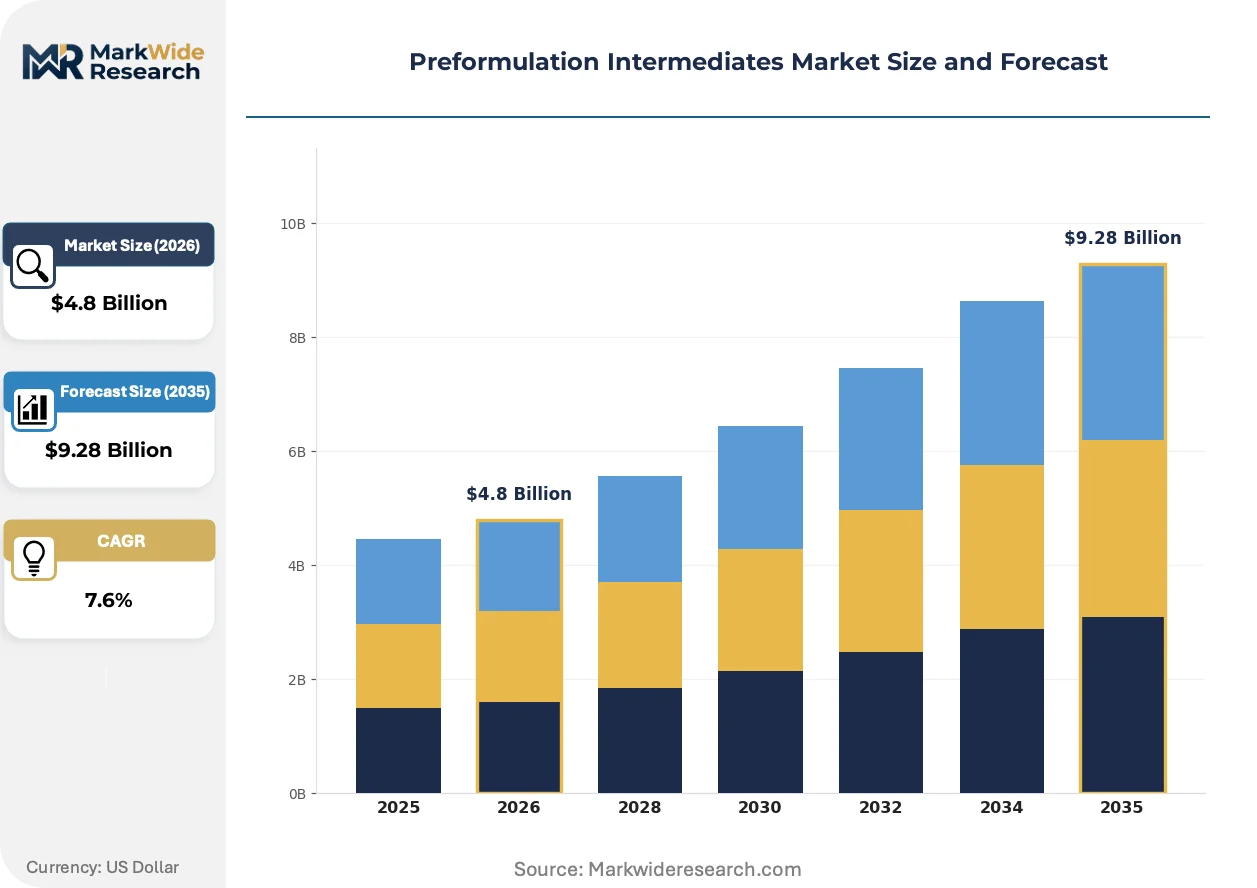
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Excipients, Formulation Additives, Stabilizers Grade: Pharmaceutical Grade, Industrial Grade, Food Grade, Technical Grade End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Institutes, Biopharmaceutical Firms Application: Solid Dosage Forms, Liquid Dosage Forms, Semi-Solid Dosage Forms, Others |
| Companies Covered | Lonza Group AG, WuXi AppTec Co., Ltd., Thermo Fisher Scientific Inc., Cambrex Corporation, BASF SE, Sanofi SA, Merck KGaA, Evonik Industries AG, Chiracon GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preformulation Intermediates Market Evolving Landscape
Artificial intelligence is penetrating physicochemical prediction while regulatory agencies tighten traceability mandates, compressing the traditional gap between exploratory chemistry and GMP-ready documentation.
Machine learning algorithms trained on crystallographic databases are digitizing polymorph risk assessment, enabling formulators to predict stability outcomes before synthesis commitment. Large pharmaceutical sponsors are deploying these tools across internal portfolios, while contract laboratories are acquiring platform licenses to differentiate screening proposals. The technology is digitizing decision gates that previously required weeks of experimental confirmation.
REACH substance registration requirements in Europe are mandating granular impurity profiling for all imported chemical intermediates, extending analytical validation timelines for non-European suppliers. The regulation forces sponsors to document supply chain provenance earlier in development, with Swissmedic-aligned certification emerging as a preferred pathway for accessing both EU and US markets. Small-molecule programs with complex synthetic routes face disproportionate compliance burden.
Biopharmaceutical sponsors are unbundling analytical services from integrated development contracts, creating direct procurement relationships with specialized preformulation laboratories. This disintermediation of traditional CDMO packages allows sponsors to match specific physicochemical challenges to niche expertise, particularly for high-throughput salt screening. The pattern is most visible among mid-cap oncology developers operating without captive analytical infrastructure.
Preformulation Intermediates Market Segmentation
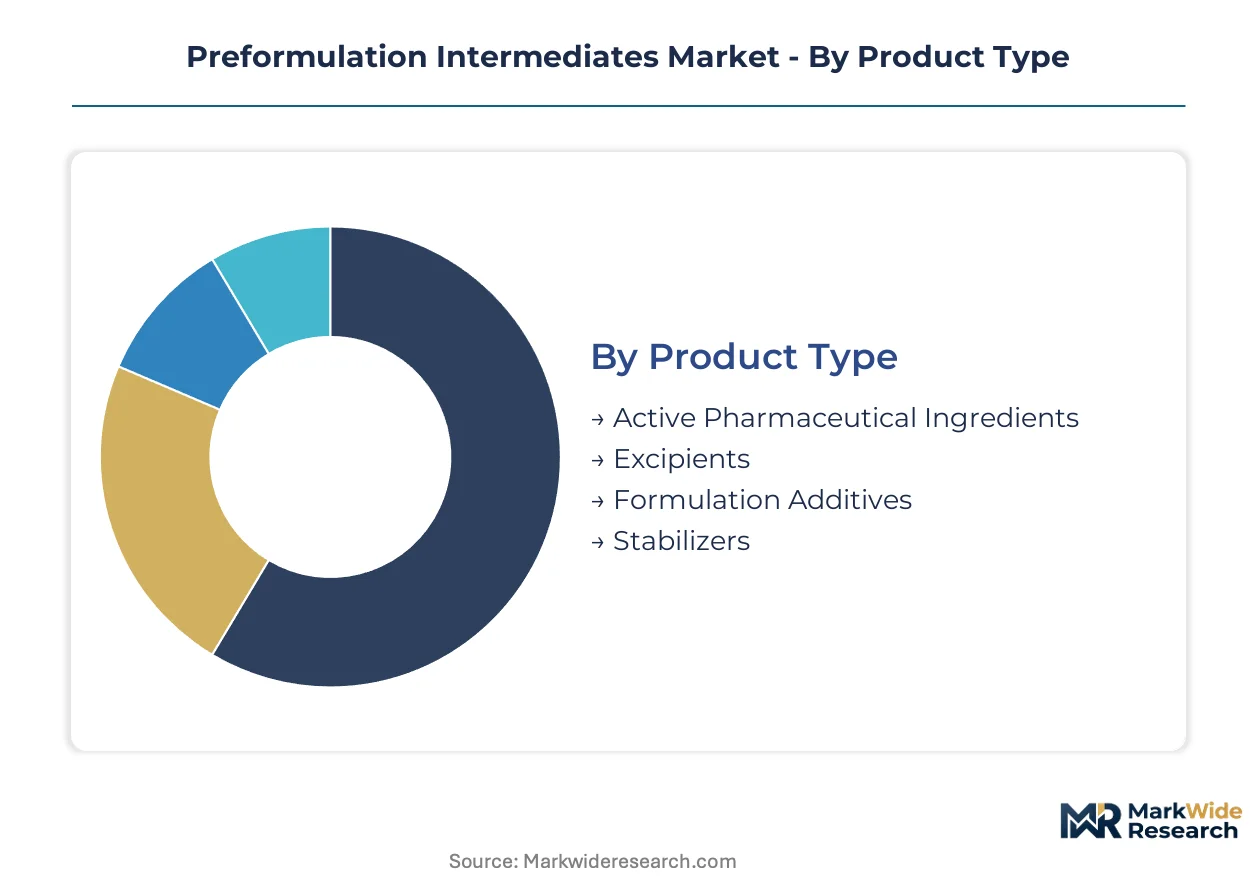
Preformulation intermediates fragment across four distinct dimensions, each governing different procurement rhythms and margin structures. Product type determines analytical complexity, while grade certification gates regulatory access. End-user channel shapes contract duration, and application dictates stability protocol requirements.
Product Type:
Cycle times vary dramatically: APIs demand months of forced-degradation documentation, whereas stabilizers turn on quarterly procurement cycles driven by formulation calendar pressures.
- Active Pharmaceutical Ingredients:New molecular entities undergoing salt selection, polymorph screening, and solubility profiling before clinical entry. Patent-cliff pressures at sponsors in the United States and Switzerland are compressing timelines for preformulation characterization of oncology candidates.
- Excipients:Inert carriers and bulking agents subject to compatibility studies with API candidates. Demand concentrates among CDMO clusters in Massachusetts and North Carolina, where integrated analytical-to-GMP pathways reduce handoff friction.
- Formulation Additives:Surfactants, binders, and disintegrants enabling dosage form manufacturability.
- Stabilizers:Antioxidants and chelating agents protecting against hydrolytic and oxidative degradation.
Active Pharmaceutical Ingredients dominates installed base. Excipients is where expansion concentrates.
Grade:
Cost tiers separate certified pharmaceutical material from commodity alternatives, with price multiples exceeding 10x for impurity-documented lots.
- Pharmaceutical Grade:Certified impurity profiles and validated analytical methods meeting FDA ICH Q3A-Q3D and EMA REACH documentation requirements. Regulatory filings in the United States and EU demand this tier exclusively, commanding premium positioning over alternatives.
- Industrial Grade:Uncertified material for early exploratory chemistry and process development. Sponsors in India leverage CDSCO-aligned pathways to source this tier for preclinical feasibility before committing to pharmaceutical-grade certification costs.
- Food Grade:GRAS-listed carriers acceptable for certain oral dosage applications with established safety profiles.
- Technical Grade:Research-use material lacking batch documentation required for regulatory submission.
Pharmaceutical Grade captures value concentration. Industrial Grade is climbing the fastest as sponsors front-load exploratory programs.
End User:
Customer type determines contract structure: pharmaceutical sponsors favor multi-year development partnerships, while biopharmaceutical firms prefer project-based procurement with milestone gates.
- Pharmaceutical Companies:Integrated developers maintaining captive preformulation laboratories for core portfolios while outsourcing specialized polymorph screening. Large-cap sponsors in Switzerland and the United States are unbundling analytical services to access niche crystallography expertise.
- Contract Manufacturing Organizations:Service providers aggregating demand across sponsor portfolios and amortizing specialized containment infrastructure. Massachusetts and North Carolina clusters anchor North American capacity, while WuXi corridors in China serve cost-sensitive programs.
- Research Institutes:Academic and government laboratories conducting exploratory physicochemical characterization without GMP obligations.
- Biopharmaceutical Firms:Mid-cap developers lacking captive analytical infrastructure and procuring direct from specialized preformulation laboratories.
Pharmaceutical Companies dominate installed base. Contract Manufacturing Organizations is gaining share fastest as outsourcing accelerates.
Application:
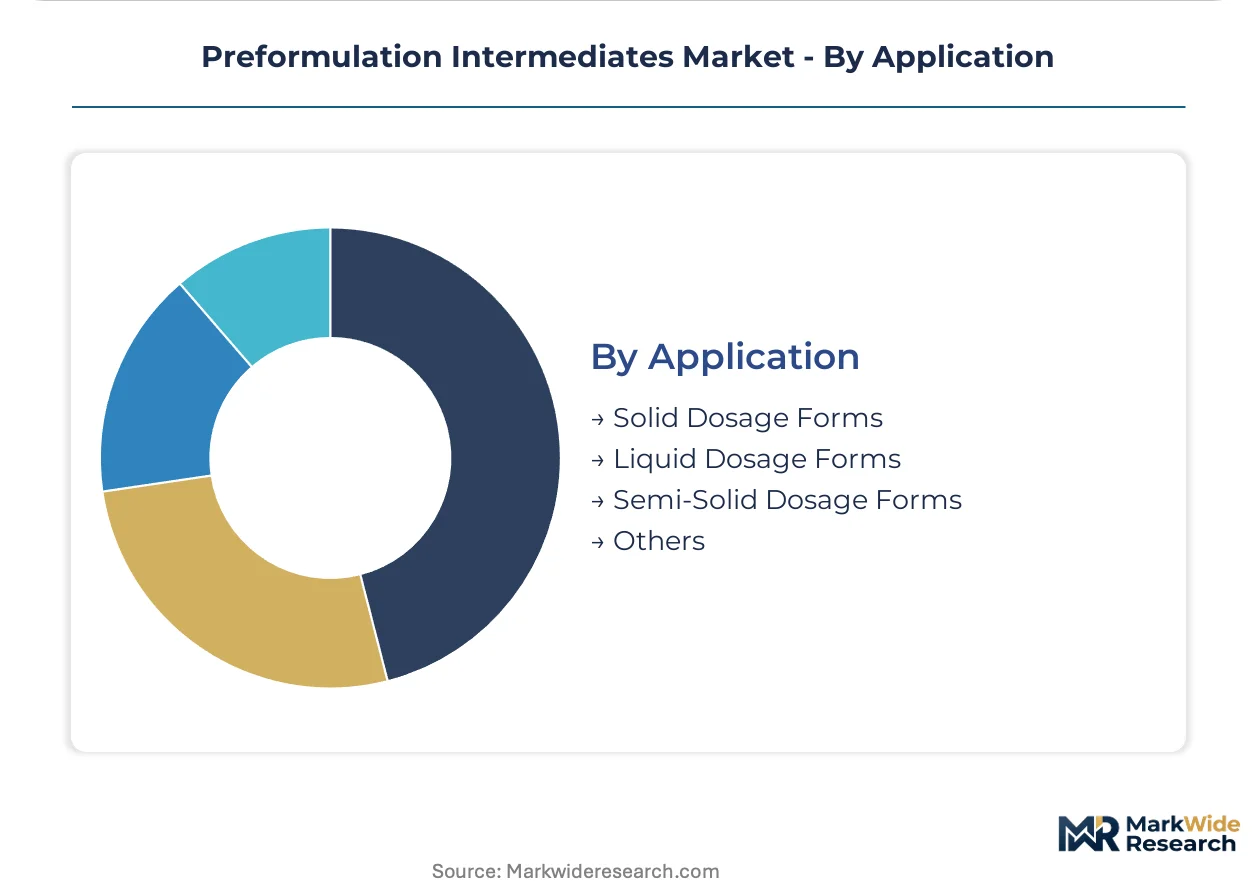
Volume concentration favors solid dosage forms, yet semi-solid applications are expanding with topical and transdermal delivery programs.
- Solid Dosage Forms:Tablets and capsules requiring particle size distribution control, powder flow characterization, and compression behavior profiling. FDA stability guidelines mandate forced-degradation studies for all solid preformulation batches destined for US-market submissions.
- Liquid Dosage Forms:Solutions and suspensions demanding solubility enhancement strategies including amorphous dispersions and lipid-based systems. Polymer-based solid dispersions face recrystallization risks that constrain applicability to high-dose compounds.
- Semi-Solid Dosage Forms:Creams, ointments, and gels requiring rheological profiling and skin permeation assessment.
- Others:Inhalation, parenteral, and novel delivery systems with specialized containment and sterility requirements.
Solid Dosage Forms dominates installed base. Semi-Solid Dosage Forms is where expansion concentrates with topical delivery growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preformulation intermediates consumption patterns diverge sharply by geography: United States sponsors prioritize early-phase risk mitigation through CDMO partnerships, while Chinese and Indian developers exploit cost differentials for exploratory chemistry before committing to pharmaceutical-grade certification.
United States
FDA's Quality by Design mandate and ICH Q8-Q12 documentation requirements drive front-loaded analytical investment across sponsor portfolios. The 21st Century Cures Act provisions accelerate oncology program timelines, compressing salt-selection and polymorph-screening windows. Massachusetts and North Carolina CDMO clusters anchor contract development capacity, with Boston-Cambridge biotech corridors generating concentrated demand for high-potency API containment infrastructure.
Germany
REACH-aligned substance registration requirements and ECHA documentation standards impose granular impurity profiling obligations on all imported chemical intermediates. The country's national pharmaceutical regulator enforces stability protocols that extend analytical validation timelines for non-European suppliers. Bavaria and North Rhine-Westphalia host specialized containment facilities serving both domestic sponsors and EU-wide development programs.
China
NMPA's convergence with ICH standards is opening inspection-ready manufacturing capacity for US and EU sponsor programs, particularly through dual-track registration pathways. The national medical products administration's accelerated review channels for innovative drugs are reshaping preformulation investment decisions. Shanghai-Suzhou chemistry corridors sustain cost-competitive salt-screening and polymorph-characterization services through integrated analytical-to-GMP pathways.
India
CDSCO pathway alignment with ICH standards enables inspection-ready capacity for Western sponsor programs, with PLI scheme incentives supporting specialized containment infrastructure buildout. The Central Drugs Standard Control Organization's streamlined approval mechanisms for preformulation batches reduce handoff friction to global sponsors. Maharashtra and Gujarat pharmaceutical manufacturing clusters concentrate cost-sensitive exploratory chemistry before pharmaceutical-grade certification commitment.
Switzerland
Swissmedic-aligned certification emerges as a preferred pathway for accessing both EU and US markets, with the national pharmaceutical regulator's stability documentation recognized across multiple jurisdictions. Patent-cliff pressures at Basel-headquartered sponsors compress timelines for preformulation characterization of oncology candidates. The Swiss-German border region concentrates crystallography expertise and high-potency API containment capacity serving global development programs.
Preformulation Intermediates Market Competitive Landscape
Capability concentration sits with specialized analytical laboratories possessing polymorph prediction expertise; scale advantage sits with integrated CDMOs amortizing containment infrastructure across sponsor portfolios. The market structures around three tiers: global diversified life sciences conglomerates with captive preformulation capacity, mid-scale contract development specialists with regional geographic anchors, and niche crystallography laboratories serving unbundled procurement relationships. Dominant competitive moves include strategic partnerships between sponsors and specialized containment facilities, plus geographic expansion through regulatory pathway alignment in India and China.
Within the integrated CDMO tier, Lonza Group AG and WuXi AppTec Co., Ltd. exemplify divergent geographic strategies: the Swiss-based conglomerate anchors high-potency oncology preformulation through its transatlantic manufacturing footprint, while the Chinese limited company exploits Shanghai-Suzhou corridor cost structures for chemistry-intensive salt-selection programs. Thermo Fisher Scientific Inc. occupies a position bridging analytical instrumentation supply into integrated development services, representing the diversified life sciences archetype that unbundled procurement patterns are now fragmenting.
| Leading Market Players |
|---|
| Lonza Group AG |
| WuXi AppTec Co., Ltd. |
| Thermo Fisher Scientific Inc. |
| Cambrex Corporation |
| BASF SE |
| Sanofi SA |
| Merck KGaA |
| Evonik Industries AG |
| Chiracon GmbH |
| Others |
Value Network & Pricing Analysis
Massachusetts and North Carolina CDMO clusters anchor contract development capacity for preformulation intermediates, translating specialized containment infrastructure scarcity into pricing power for high-potency API characterization services. Their concentrated analytical-to-GMP pathways command premium positioning over fragmented European and Asian alternatives.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade preformulation procurement, while project-based contracting governs exploratory salt-selection and polymorph-screening programs. Price differentiation rests on certification tier—pharmaceutical-grade lots with ICH Q3A-Q3D documentation command multiples over industrial-grade material—and volume scale, with large sponsors extracting favorable terms through multi-year development partnerships. Cost compression in industrial-grade chemistry is intensifying because Indian and Chinese suppliers are expanding CDSCO- and NMPA-aligned capacity. Mid-cap biopharmaceutical firms without captive infrastructure exhibit highest price sensitivity, whereas large-cap oncology developers prioritize speed-to-clinic over unit economics.
Supply Chain Analysis
Lonza Group AG and WuXi AppTec Co., Ltd. anchor contract-manufacturing concentration for preformulation intermediates, with Thermo Fisher Scientific Inc. bridging analytical instrumentation into integrated development services. Geographic supply concentration centers on Switzerland, the United States, and China, with specialized crystallography expertise concentrated in the Swiss-German border region and cost-competitive chemistry corridors in Shanghai-Suzhou. Raw material dependencies draw from German and Swiss suppliers of high-purity solvents and reference standards for forced-degradation studies. Single-source vulnerability for these specialized inputs creates structural supply chain risk. Distribution runs through CDMO clusters that amortize containment infrastructure across sponsor portfolios, with direct procurement relationships emerging between biopharmaceutical sponsors and specialized preformulation laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The preformulation intermediates market functions as a service-attach opportunity where analytical method development and stability protocol design generate recurring revenue streams expanding faster than commodity intermediate supply.
For Market Incumbents: Entrench position by deepening backward integration into high-purity solvent production and reference standard synthesis to neutralize German and Swiss single-source vulnerability. Expand certified containment capacity in Massachusetts and North Carolina to capture oncology pipeline concentration. Patent-cliff pressures at large sponsors are accelerating outsourcing decisions, making multi-year partnership structures the priority lever for capacity allocation. For New Entrants and Emerging Players: Build out inspection-ready manufacturing capacity in India aligned with CDSCO pathway convergence to serve cost-sensitive exploratory chemistry demand from Western sponsors. Target mid-cap biopharmaceutical firms lacking captive analytical infrastructure and seeking direct procurement relationships for high-throughput salt screening. A go-to-market angle emphasizing rapid polymorph characterization turnaround against established CDMO queue times offers viable penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized analytical laboratories with machine-learning-augmented crystallographic prediction capabilities over commodity chemistry providers. Long-term viability hinges on regulatory documentation intensity persisting across FDA Quality by Design and EMA REACH frameworks. Acquisition targets should demonstrate Swissmedic-aligned certification enabling dual EU-US market access. The signal to watch is FDA Real-World Evidence framework expansion creating demand for preformulation documentation supporting lifecycle management.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pathway Alignment | CDSCO and NMPA convergence with ICH standards opens inspection-ready capacity for Western sponsors. |
| Containment Infrastructure Expansion | Specialized high-potency API capacity in Massachusetts and North Carolina captures oncology pipeline growth. |
| Machine Learning Platform Integration | Polymorph prediction algorithms digitize form stability assessment before synthesis commitment. |
| Backward Integration into Solvents | In-house production of high-purity solvents neutralizes single-source dependency on German suppliers. |
| Direct Procurement Relationships | Unbundled analytical services from integrated CDMO contracts match niche expertise to specific physicochemical challenges. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, CDMO procurement managers, and analytical laboratory directors and refined through secondary validation. FDA filings, EMA submissions, ClinicalTrials.gov records, and ICH guideline documentation provided regulatory trajectory data. Bottom-up and top-down triangulation reconciled sponsor pipeline data with CDMO capacity announcements across the analysis window.
Demand-supply-balance framing anchored the forecast framework across the projection horizon. Segmentation dimensions modeled included product type, grade certification tier, end-user channel, and application with regional regulatory cluster overlay. CAGRs were derived from sponsor R&D expenditure trajectories, CDMO capacity expansion announcements, and regulatory filing velocity. Oncology pipeline concentration and ICH Q8-Q12 adoption curves served as industry-specific forecast inputs.
Stress conditions across FDA inspection readiness timelines, REACH substance registration cost inflation, and high-potency API containment capacity expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory convergence pace and sponsor outsourcing propensity. Quarterly review of CDMO utilization rates and sponsor preformulation budget allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Copper Chemicals Market