
 Global Chemical Intermediates Market | 2026-2036
Global Chemical Intermediates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Intermediates Market Foresight
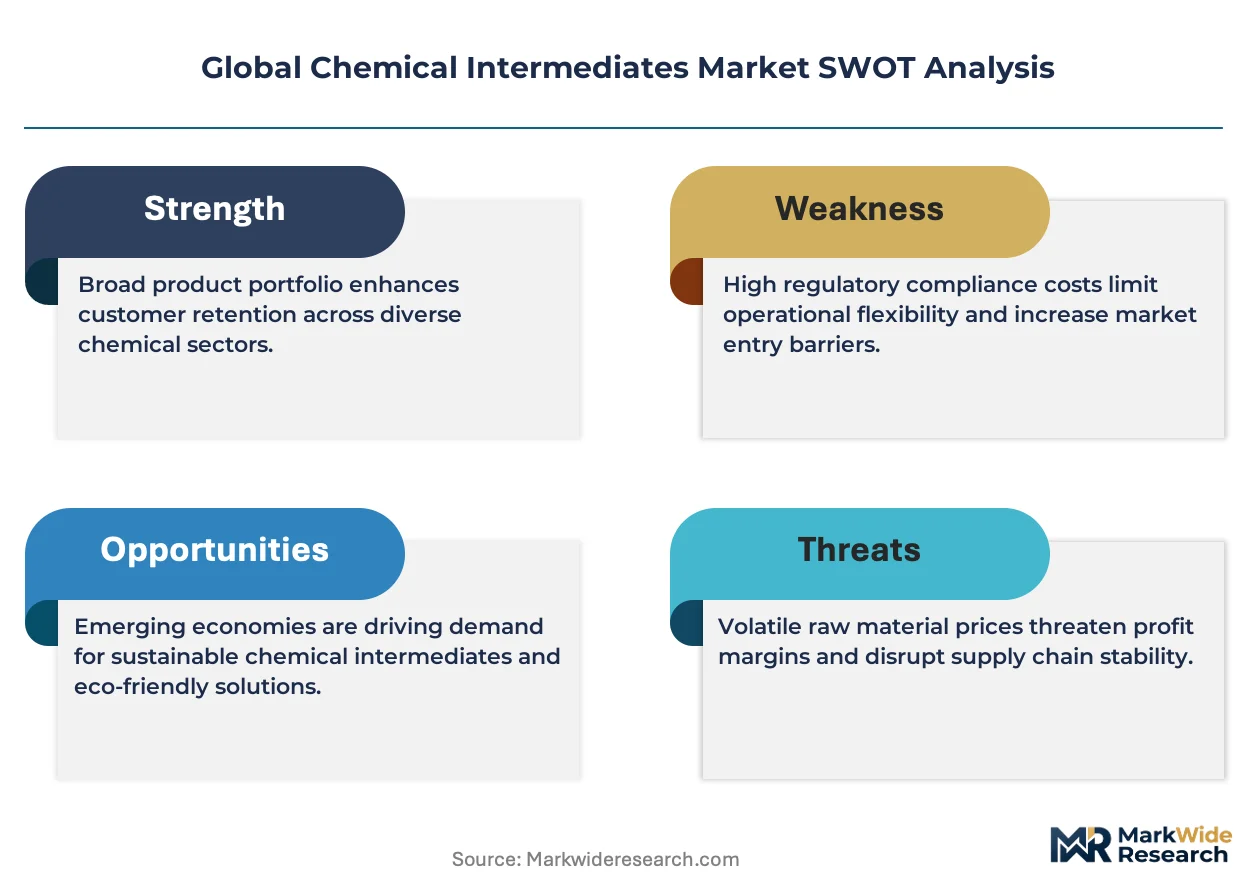
Specialty alcohol formulation revenue is reconfiguring margin pools away from commodity methanol toward higher-purity ethanolamines and glycol ethers. Dow leverages its Gulf Coast ethylene integration to anchor North American supply of ethylene oxide derivatives. BASF SE sustains European leadership in amine chemistry through Ludwigshafen complex scale. Akzo Nobel NV competes on coating-grade ester specialization across Rotterdam and Hengelo assets.
Chemical intermediates are reactive or catalytic substances—typically C2-C12 oxygenates, nitrogenates, or halogenated organics—synthesized via catalytic oxidation, hydrogenation, or nitration and consumed as precursors for polymers, agrochemicals, or active pharmaceutical ingredients rather than sold as finished goods. The alcohols segment dominates volume through methanol and ethanolamine feedstock demand, while pharmaceutical-grade amines command the widest margin spreads due to FDA and EMA impurity profiling rules. Industrial-grade ketones and esters remain mature categories with pricing tied to acetone and butyl acetate commodity cycles.
EPA New Source Performance Standards and REACH Annex XVII restrictions on hazardous substance classifications are redirecting capital toward lower-toxicity synthesis routes and closed-loop solvent recovery systems. China's MEE emission permits and India's BIS chemical purity notifications add compliance layers for exporters serving Asian formulation markets. Stakeholders must monitor regulatory divergence between EU Green Deal chemical sustainability targets and US IRA clean manufacturing incentives when siting new intermediate capacity.
Market Dynamics
REACH Annex XVII restrictions on hazardous substance classifications are redirecting capital toward lower-toxicity synthesis routes and closed-loop solvent recovery systems, compressing legacy batch-process margins while rewarding continuous-flow investments.
Growth Catalysts
- Agrochemical formulator demand:Specialty alcohols and amine derivatives for crop protection synthesis are gaining traction among Bayer CropScience and Syngenta procurement teams in Germany and Switzerland.
- EPA New Source Performance Standards:Tightening VOC emission limits are forcing solvent-grade intermediate producers to upgrade purification equipment, creating replacement demand for catalytic oxidation systems.
- India BIS chemical purity notifications:Mandatory certification for imported intermediates is driving domestic capacity expansion in Gujarat and Maharashtra chemical clusters.
Market Restraints
- Naphtha-cracker feedstock volatility:Ethylene and propylene price swings in the US Gulf Coast and Rotterdam directly compress margin on C2-C4 oxygenate derivatives.
- China MEE emission permit scarcity:Provincial authorities in Jiangsu and Shandong are capping new intermediate plant approvals, constraining export supply growth.
- Pharmaceutical amine substitution:Peptide synthesis and biocatalytic routes are displacing traditional small-molecule amine intermediates in late-stage API manufacturing.
Strategic Opportunities
- US IRA clean manufacturing incentives:Section 45X credits for qualified clean chemical production are attracting greenfield investment in Texas and Louisiana carbon-capture-enabled intermediate complexes.
- Bio-based glycol ether emergence:Fermentation-derived ethylene glycol routes are opening premium positioning for coating-grade intermediates targeting EU Green Deal procurement mandates.
- India PLI scheme for specialty chemicals:Production-linked incentives for agrochemical intermediates are luring contract manufacturers away from China-dependent supply chains.
Industry Challenges
- Process analytical technology (PAT) skill scarcity:FDA and EMA real-time release testing requirements demand chemometric expertise that contract manufacturers in Eastern Europe and India struggle to staff.
- Legacy DCS integration friction:Brownfield intermediate plants in Germany's Ludwigshafen and Marl clusters face multi-year migration timelines to connect batch historians with cloud-based compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Intermediates Market |
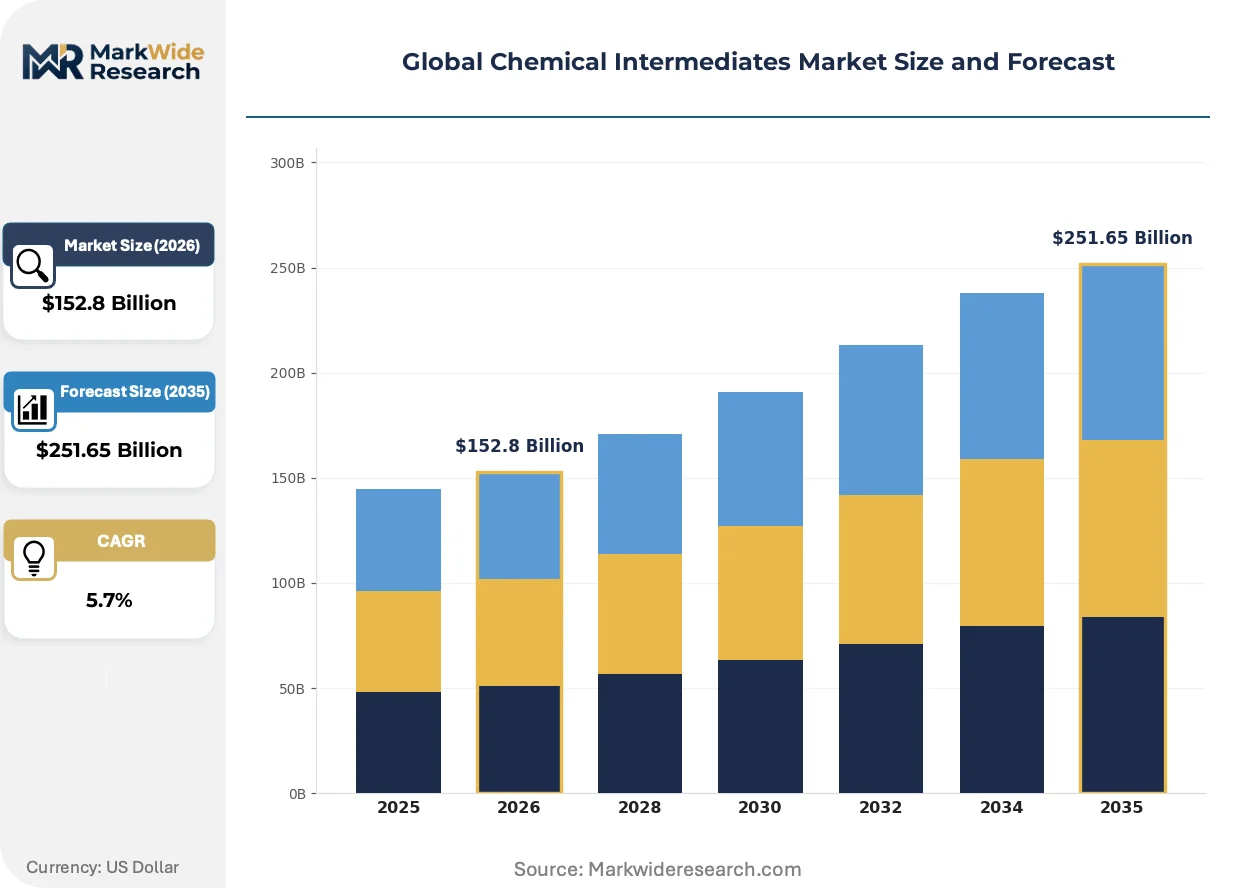
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $251.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohols, Ketones, Esters, Amines, Acids Grade: Industrial Grade, Technical Grade, Food Grade, Pharmaceutical Grade, Analytical Grade Application: Paints & Coatings, Agrochemicals, Plastics & Polymers, Detergents & Surfactants, Pharmaceuticals End Use Industry: Textile Manufacturers, Construction Firms, Cosmetic Producers, Electronics Fabricators, Adhesives Manufacturers |
| Companies Covered | BASF SE, Dow, ExxonMobil Chemical, INVISTA Nylon Chemical Co. Ltd., Stepan Company, LG Royal DSM, Chevron Corporation, Akzo Nobel NV, Deepak Nitrite Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Intermediates Market Shifts & Advancements
Continuous-flow microreactor technology is collapsing batch-cycle economics while electrochemical hydrogenation routes and AI-driven retrosynthesis tools are rewriting process development timelines across the value chain.
Flow chemistry microreactor platforms are collapsing residence-time requirements from hours to seconds for nitration and oxidation steps. Agrochemical formulators in Brazil and India are qualifying these systems for active ingredient precursors. The technology is collapsing capital intensity thresholds, enabling mid-scale producers to match the yield consistency of integrated petrochemical giants.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon containment mandates for fluorinated intermediate production. German and Belgian producers must retrofit distillation trains with closed-loop refrigerant recovery by 2027. Pharmaceutical-grade fluorinated building blocks face the steepest compliance cost escalation, pushing synthesis toward non-fluorinated bioisosteres where structurally feasible.
Buyers are consolidating intermediate procurement through platform-enabled spot auctions rather than multi-year frame contracts. Specialty chemical distributors in Southeast Asia are deploying digital marketplaces that disintermediate traditional trader networks. The shift is most visible in India, where agrochemical formulators now source ethanolamines through B2B platforms linking Gujarat producers directly with Punjab and Haryana formulation plants.
Global Chemical Intermediates Market Segmentation
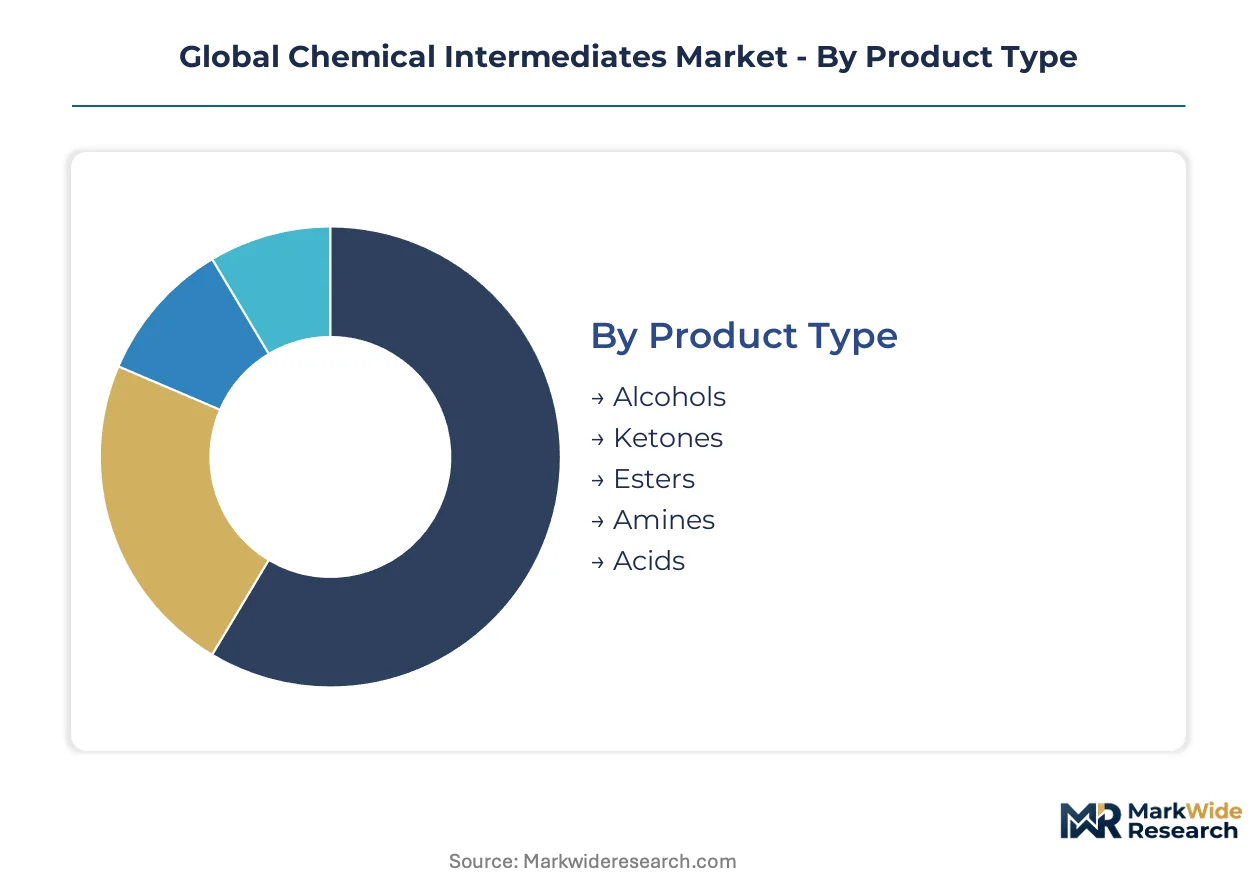
Chemical intermediates fragment across multiple axes that determine pricing power, regulatory burden, and customer loyalty. Product chemistry, purity grade, and end-use application each create distinct margin pools with incompatible technical specifications.
Product Type:
Chemistry type determines feedstock linkage and synthesis complexity, anchoring margin structures to distinct raw material cycles.
- Alcohols:Methanol and ethanolamine derivatives dominate volume through ethylene oxide and syngas routes. Agrochemical formulators in Germany and India concentrate procurement for herbicide and fungicide synthesis.
- Amines:Specialty alkylamines and ethanolamines command the widest pharmaceutical-grade spreads due to FDA and EMA impurity profiling mandates. BASF's Ludwigshafen complex anchors European supply of ethyleneamines for polyamide intermediates.
- Ketones:Acetone and methyl ethyl ketone remain mature categories with pricing tied to phenol co-product economics and solvent demand cycles.
- Esters:Butyl acetate and specialty glycol esters serve coating-grade applications with volatility tracking acetic acid and butanol feedstock swings.
- Acids:Carboxylic and sulfonic acid intermediates feed polymerization catalysts and pharmaceutical salt formation with purity tiers separating industrial from reagent grades.
Alcohols commands the established base. The steepest expansion runs through amines.
Grade:
Purity tier stratifies customers by regulatory exposure and specification tolerance, creating five distinct pricing bands.
- Industrial Grade:Bulk oxygenates and nitrogenates for polymerization and solvent applications carry minimal analytical overhead. Paint manufacturers and adhesives producers in China and India absorb most volume at commodity-equivalent pricing.
- Pharmaceutical Grade:USP and EP-compliant intermediates for API synthesis require validated impurity profiles and stability data. FDA real-time release testing mandates compress supplier qualification timelines.
- Technical Grade:Mid-tier purity for agrochemical and specialty chemical synthesis bridges industrial and food-grade specifications with flexible certificate of analysis ranges.
- Food Grade:FSSAI and FDA food additive compliance restricts solvent residues and heavy metal content for flavor and fragrance precursors.
- Analytical Grade:Reagent purity for laboratory and diagnostic applications represents minimal volume with maximum margin through certified reference material protocols.
Industrial grade anchors volume throughput. Pharmaceutical grade captures the steepest margin expansion.
Application:
Downstream use case determines regulatory jurisdiction and performance specifications, segmenting customers by compliance intensity.
- Agrochemicals:Herbicide and insecticide precursors drive ethanolamine and chlorinated pyridine demand. Bayer CropScience and Syngenta procurement teams in Germany and Switzerland qualify suppliers through multi-year field trial partnerships.
- Pharmaceuticals:API building blocks and excipients require GMP manufacturing with FDA and EMA audit trails. Peptide synthesis displacement is eroding traditional small-molecule amine volumes.
- Paints & Coatings:Glycol ether and ester solvents for waterborne formulations face REACH Annex XVII VOC restrictions and EPA New Source Performance Standards.
- Plastics & Polymers:Polymerization initiators and chain transfer agents track ethylene and propylene derivative pricing with specification tolerance for color and volatility.
- Detergents & Surfactants:Ethoxylated alcohol intermediates for household and industrial cleaning formulations concentrate procurement through integrated oleochemical players.
Agrochemicals maintains the volume foundation. Pharmaceuticals delivers the most rapid specification escalation.
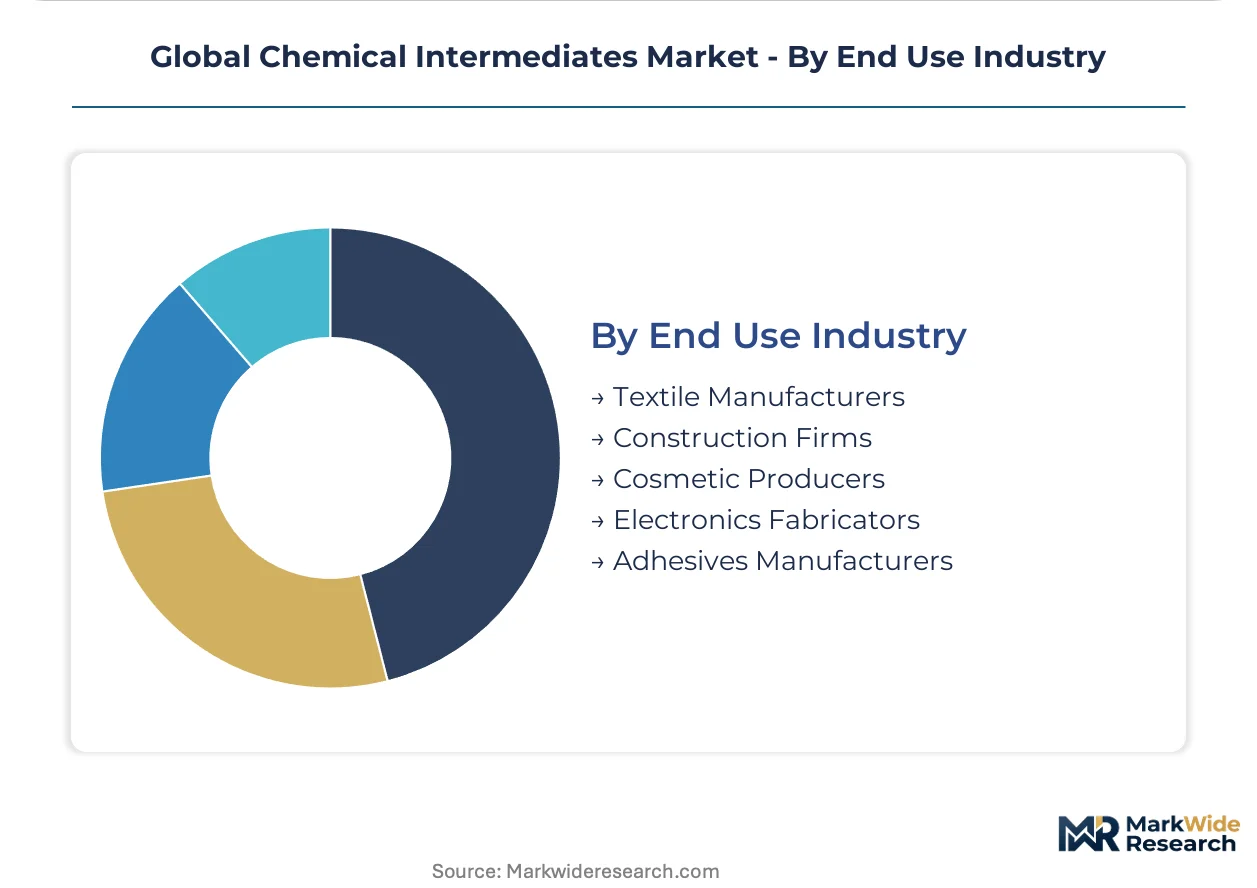
End Use Industry:
Customer industry type determines technical service intensity and contract structure preferences.
- Textile Manufacturers:Dye intermediates and finishing agents for polyester and cotton processing concentrate in Gujarat and Jiangsu clusters with seasonal procurement patterns.
- Construction Firms:Adhesive and sealant precursors for concrete additives and waterproofing membranes track infrastructure spending cycles in India and China.
- Cosmetic Producers:Emollient esters and surfactant intermediates for personal care formulations require EC 1223/2009 cosmetic regulation compliance with preservative-free certification trending.
- Electronics Fabricators:High-purity solvents and photoresist precursors for semiconductor cleaning and etching demand sub-ppb metal specifications.
- Adhesives Manufacturers:Reactive diluents and curing agents for industrial bonding applications balance viscosity control with pot-life extension.
Textile manufacturers represent the established demand anchor. Electronics fabricators are climbing the fastest on purity premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit acute price sensitivity on industrial-grade oxygenates, while pharmaceutical formulators in Germany and Switzerland absorb steep premiums for amine purity certification without volume elasticity.
United States
EPA New Source Performance Standards on VOC emissions are accelerating capital deployment into catalytic oxidation upgrades at Gulf Coast ethylene oxide derivative complexes. Section 45X clean manufacturing credits under the IRA are attracting carbon-capture-enabled greenfield investments in Texas and Louisiana. Houston-area integrated producers leverage shale gas feedstock advantage to anchor North American supply of C2-C4 oxygenates.
Germany
Bayer CropScience and Syngenta procurement teams concentrate demand for ethanolamine herbicide precursors through multi-year field trial partnerships. REACH Annex XVII hazardous substance classifications are redirecting Ludwigshafen complex investments toward closed-loop solvent recovery systems. The Marl chemical cluster faces multi-year DCS migration timelines to connect batch historians with cloud-based compliance reporting.
China
MEE emission permit scarcity in Jiangsu and Shandong provinces is capping new intermediate plant approvals and constraining export supply growth. Dual carbon goals are pressuring coal-to-chemical producers toward hydrogenation route substitution. Yangtze River Delta formulators are qualifying continuous-flow microreactor platforms for active ingredient precursors.
India
BIS chemical purity notifications for imported intermediates are driving domestic capacity expansion in Gujarat and Maharashtra chemical clusters. PLI scheme production-linked incentives for agrochemical intermediates are luring contract manufacturers away from China-dependent supply chains. Mumbai-based distributors now deploy B2B platforms linking Gujarat ethanolamine producers directly with Punjab formulation plants.
Switzerland
Swissmedic pharmaceutical-grade impurity profiling mandates command the widest margin spreads for specialty alkylamines in European API manufacturing. EU Green Deal chemical sustainability targets are redirecting Basel-area investment toward bio-based glycol ether fermentation routes. Local formulators are consolidating procurement through platform-enabled spot auctions rather than traditional frame contracts.
Global Chemical Intermediates Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing ethylene oxide derivative integration; scale advantage sits with regional specialists commanding agile batch flexibility. The vendor base stratifies into three tiers: Gulf Coast and Rotterdam-anchored multinationals with captive feedstock, Ludwigshafen-style European chemical complex operators, and India-China contract manufacturers exploiting PLI and emission permit arbitrage. Dominant competitive moves include backward integration into ethylene oxide supply and technology licensing partnerships for continuous-flow microreactor deployment.
Within the integrated multinational tier, BASF SE and Dow exemplify divergent geographic anchoring strategies, with the former sustaining European amine chemistry leadership through complex scale and the latter leveraging Gulf Coast ethylene integration for derivative supply security. Akzo Nobel NV occupies a position as a coating-grade ester specialist across Rotterdam and Hengelo assets. Deepak Nitrite Ltd. represents the India-based contract manufacturing archetype capitalizing on domestic purity certification mandates and agrochemical intermediate incentives.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| ExxonMobil Chemical |
| INVISTA Nylon Chemical Co. Ltd. |
| Stepan Company |
| LG Royal DSM |
| Chevron Corporation |
| Akzo Nobel NV |
| Deepak Nitrite Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors anchor European chemical intermediate pricing, with tanker cost swings compressing margins on solvent-grade ethanolamines while enabling premium capture for pharmaceutical-grade amines through just-in-time delivery guarantees. This logistics tension concentrates supply power among Gulf Coast and Ludwigshafen integrated producers who internalize ethylene oxide feedstock costs, forcing independent formulators to absorb volatile naphtha-cracker pass-throughs or cede volume to contract manufacturers exploiting India PLI scheme arbitrage.
Pricing Analysis
After-sales technical service contracts and validated stability data packages drive lifetime value for pharmaceutical-grade amine suppliers facing FDA real-time release testing mandates. Three-tier pricing structure across pharmaceutical, technical, and industrial grades separates USP-certified alkylamines from agrochemical intermediates and commodity solvent oxygenates. Cost compression in industrial-grade methanol derivatives is intensifying because China MEE emission permits constrain new capacity additions. Agrochemical formulators in India exhibit acute price sensitivity on ethanolamine volumes, while Swissmedic-regulated API manufacturers absorb steep certification premiums without volume elasticity.
Supply Chain Analysis
Dual-use chemical precursor export controls under Australia Group arrangements restrict flows of nitration-grade intermediates and fluorinated building blocks to designated destinations. Manufacturing concentrates in China, Germany, and India, with Jiangsu and Shandong provinces hosting coal-to-chemical complexes that feed from captive syngas and ethylene oxide derivatives. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade ethanolamines where Ludwigshafen and Basel-area complexes dominate European qualification. Distribution runs through platform-enabled spot auctions in India and traditional frame contracts in Germany, with Southeast Asian distributors deploying B2B marketplaces that disintermediate legacy trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through platform-enabled procurement consolidation, as agrochemical formulators in India and coating manufacturers in China migrate from multi-year frame contracts to spot-auction intermediation. This fragmentation among traditional distributor networks compresses margin capture for non-integrated suppliers.
For Market Incumbents: Harden ethylene oxide derivative integration through backward control over Gulf Coast crackers or Ludwigshafen complex scale expansions. Invest in continuous-flow microreactor technology licensing partnerships to match yield consistency against emerging contract manufacturers. Priority defensive moves center on locking multi-year field trial partnerships with Bayer CropScience and Syngenta procurement teams before India PLI scheme incentives mature domestic challenger capacity.
For New Entrants and Emerging Players: Gujarat and Maharashtra chemical clusters in India offer underpenetrated white-space for pharmaceutical-grade amine production serving CDMO demand from European API manufacturers. Target agrochemical intermediate contract manufacturing for Punjab and Haryana formulation plants through B2B platform direct-linkage models. Go-to-market angle: leverage BIS purity certification mandates to displace China-dependent supply chains for ethanolamine herbicide precursors.
For Investors and Strategic Acquirers: Mid-scale continuous-flow technology specialists with validated impurity profiling capabilities present acquisition targets for private equity seeking exposure to FDA and EMA compliance premium capture. Long-term viability across the analysis window hinges on regulatory divergence arbitrage between EU Green Deal chemical sustainability targets and US IRA clean manufacturing incentives. Signal to watch: provincial MEE emission permit issuance rates in Jiangsu and Shandong as inflection indicator for China export supply elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Gulf Coast ethylene oxide derivative complexes anchor feedstock cost control against naphtha volatility. |
| Continuous-Flow Technology Licensing | Microreactor platforms collapse residence-time economics for nitration steps at Brazil and India agrochemical formulators. |
| Green Manufacturing Transition | Fermentation-derived glycol ether routes open premium positioning for EU Green Deal procurement mandates. |
| Long-term Supply Agreement | Multi-year field trial partnerships with Bayer CropScience and Syngenta lock qualification barriers for herbicide precursors. |
| Joint Venture | Carbon-capture-enabled intermediate complexes in Texas and Louisiana capture Section 45X clean manufacturing credits. |
Research Methodology
A spread of perspectives from plant managers at integrated petrochemical complexes, procurement leads at agrochemical formulators, distribution channel partners in Southeast Asia, and technical R&D directors at coating-grade ester specialists converged on the working assumptions. Primary interview insights triangulated against customs and trade data from ACC and Cefic, SEC 10-K filings, and BIS chemical purity notification records. Bottom-up segment sizing across alcohols, amines, ketones, esters, and acids grades combined with top-down macro validation.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by purity grade, end-use application, and regional production hub driving volume and value outputs. CAGRs derived from regression against ethylene and propylene derivative pricing cycles, regulatory compliance cost escalation trajectories, and continuous-flow technology adoption curves. Industry-specific inputs included REACH Annex XVII hazardous substance reclassification timelines and India PLI scheme incentive disbursement patterns.
Macroeconomic conditions sit as an overlay; deviation in naphtha-cracker feedstock costs, MEE emission permit issuance velocity, or IRA clean manufacturing credit permanence would shift the trajectory. Material shifts in peptide synthesis displacement rates for traditional small-molecule amine intermediates or EU F-Gas Regulation phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Thioesters Market