
 Carboxylic Acid Chlorides Market | 2026-2036
Carboxylic Acid Chlorides Market Size, Share, and Industry Trends Forecast 2026-2036
Carboxylic Acid Chlorides Market Outlook
Pharmaceutical buyer concentration is expanding as large API manufacturers consolidate supplier relationships around qualified vendors. CABB Group GmbH leverages its integrated chlorination infrastructure to serve European pharmaceutical accounts. Shiva Pharmachem Ltd anchors supply from Gujarat's chemical corridor to Asian and Middle Eastern buyers. Transpek Industry Limited specializes in sulfur chloride derivatives that extend into acyl chloride adjacencies for agrochemical clients.
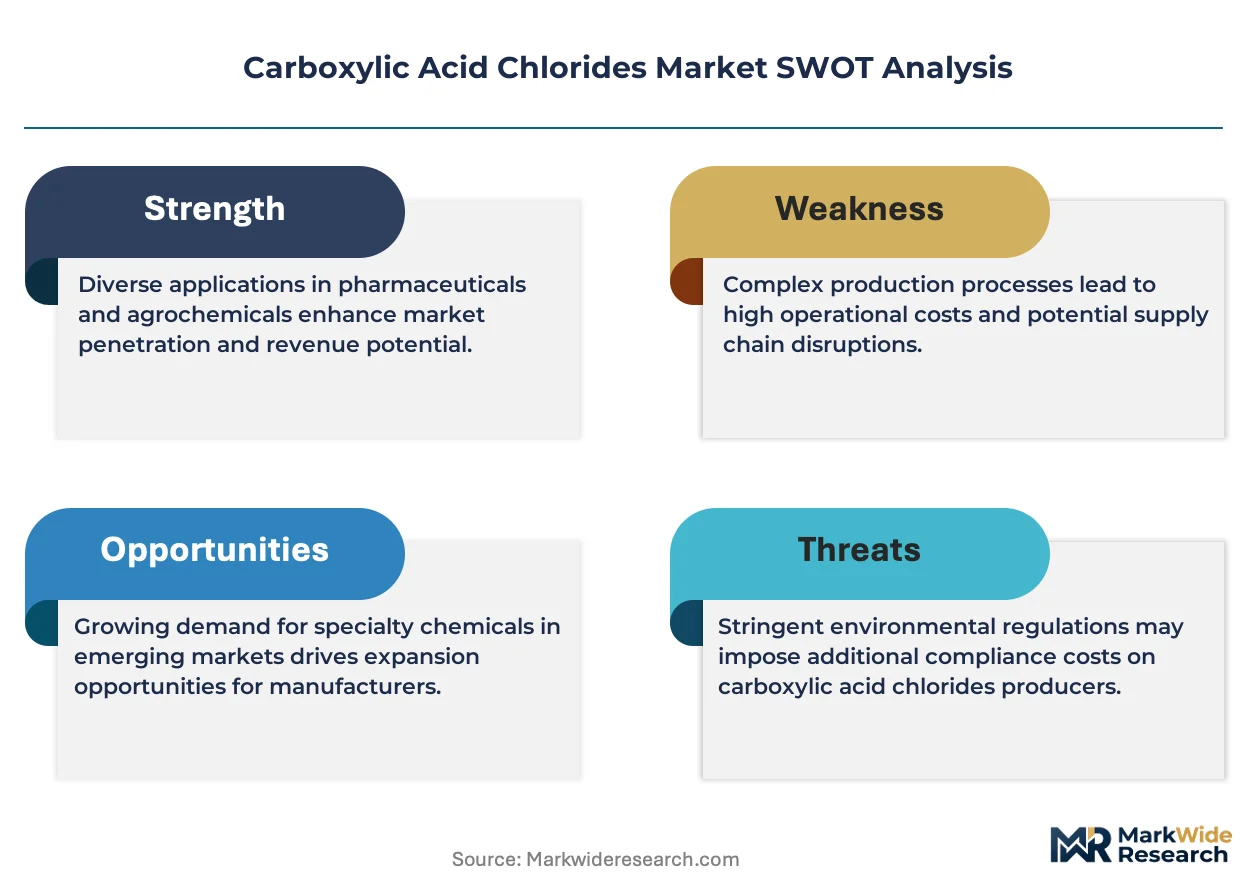
Carboxylic acid chlorides are acyl halides formed by replacing hydroxyl groups with chlorine, typically manufactured through thionyl chloride or phosgene-mediated chlorination of parent acids at controlled temperatures below 80°C. These compounds serve primarily as acylating agents in pharmaceutical intermediates, agrochemical synthesis, and polymer modification where selective electrophilic substitution drives reaction efficiency. Benzoyl chloride leads product type revenue due to its extensive use in benzophenone and antibiotic precursor manufacturing. Pharmaceutical applications command the deepest margin pools among end-use categories, while polymer production segments compete on throughput scale rather than unit economics. Catalytic process technologies differentiate producers capable of halogen recovery and waste minimization.
EPA oversight in the United States and REACH registration requirements in Europe enforce stringent handling protocols and purity documentation for acyl chloride imports. China's SAMR implements GB standards that restrict residual phosgene content in domestically produced acid chlorides. India's CDSCO mandates impurity profiling for pharmaceutical-grade acyl chlorides used in registered drug substances. Stakeholders must monitor evolving chemical inventory notifications across these jurisdictions to preempt supply chain disruptions.
Market Dynamics
Pharmaceutical-grade purity mandates from EMA and CDSCO are compressing supplier qualification timelines while concentrating procurement among integrated chlorination specialists with documented impurity profiling capabilities.
Growth Catalysts
- REACH Registration Tiering:ECHA's differentiated registration requirements for acyl chlorides above one tonne annually are consolidating demand around pre-qualified European vendors with complete dossier submissions.
- Agrochemical Formulation Expansion:Sulfur-containing acid chloride derivatives are penetrating fungicide and herbicide synthesis pipelines in India's Gujarat chemical corridor.
- Catalytic Halogen Recovery:Closed-loop thionyl chloride regeneration systems are reducing raw material intensity for benzoyl chloride manufacturers operating above fifty thousand tonne annual scale.
Market Restraints
- Phosgene Feedstock Volatility:Residual phosgene content restrictions under China's GB standards are forcing domestic producers to absorb elevated purification costs or exit pharmaceutical-grade segments.
- Specialty Supplier Concentration:Ludwigshafen and Gujarat together account for disproportionate global merchant supply, creating geographic risk exposure for buyers without dual-source qualification.
- Aqueous Quenching Limitations:Hydrolysis sensitivity during aqueous workup prevents acid chloride deployment in certain continuous-flow pharmaceutical processes.
Strategic Opportunities
- CDSCO Impurity Profiling Mandate:India's tightened pharmaceutical-grade specifications are creating first-mover advantage for suppliers with pre-validated analytical methods and reference standard libraries.
- Biocatalytic Acylation Convergence:Enzyme-mediated chlorination pathways are opening compatibility with temperature-sensitive active pharmaceutical intermediates previously excluded from acid chloride chemistry.
- Specialty Chemical Clusters:Shandong province's expanding chlor-alkali infrastructure offers backward integration potential for acyl chloride producers serving Asian agrochemical formulators.
Industry Challenges
- Process Safety Expertise Scarcity:Exothermic chlorination reactor management requires specialized chemical engineering talent that outpaces current vocational training output in major manufacturing hubs.
- Multi-Jurisdiction Certification Burden:Simultaneous EPA TSCA notification, REACH registration, and CDSCO impurity filing creates twelve-to-eighteen month qualification delays for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carboxylic Acid Chlorides Market |
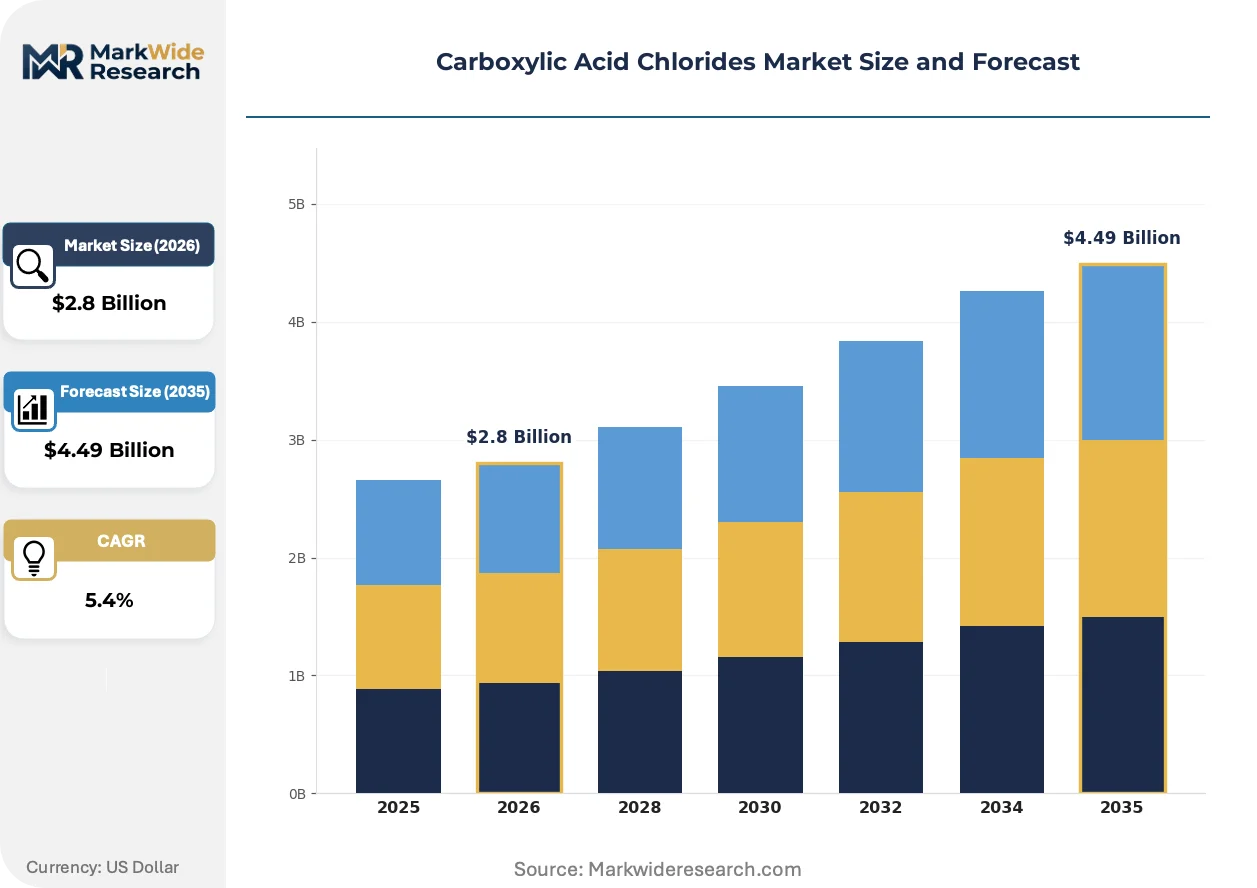
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid Chloride, Benzoyl Chloride, Butyric Acid Chloride, Lauric Acid Chloride Application: Pharmaceuticals, Agrochemicals, Polymer Production, Flavoring Agents End User: Chemical Manufacturers, Food & Beverage Industry, Agriculture Sector, Pharmaceutical Companies Technology: Synthesis Methods, Reaction Techniques, Catalytic Processes, Extraction Techniques |
| Companies Covered | BASF, ALTIVIA, CABB Group GmbH, VanDeMark, Transpek Industry Limited, Shiva Pharmachem Ltd, Novaphene Specialities Pvt. Ltd., Cangzhou Runliqing Chemical Co. Ltd, Shandong Longyuan New Material Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carboxylic Acid Chlorides Market Strategic Shifts
Continuous-flow chlorination reactor designs are displacing batch operations across pharmaceutical intermediate manufacturing, compressing reaction times and reducing thermal degradation of sensitive acylating agents.
Membrane-based chlorine recovery systems are rewriting capital efficiency calculations for integrated acid chloride producers. API manufacturers in Germany and Switzerland are retrofitting existing thionyl chloride infrastructure with these separation modules. The technology is compressing variable cost spreads between merchant and captive production modes.
REACH substance evaluation protocols are tightening documentary requirements for acyl chlorides used in polymer additives. ECHA's 2024-2025 rolling action plan targets benzoyl chloride derivatives for extended one-hundred-day comment periods. European polymer compounders are accelerating supplier audits to preempt authorization listing risks.
Long-term offtake contracting is displacing spot purchasing for pharmaceutical-grade material. Large API manufacturers in India and Germany are negotiating eighteen-to-twenty-four month supply agreements with embedded price adjustment clauses. This pattern is most visible in benzoyl chloride procurement for benzophenone precursor synthesis.
Carboxylic Acid Chlorides Market Segmentation
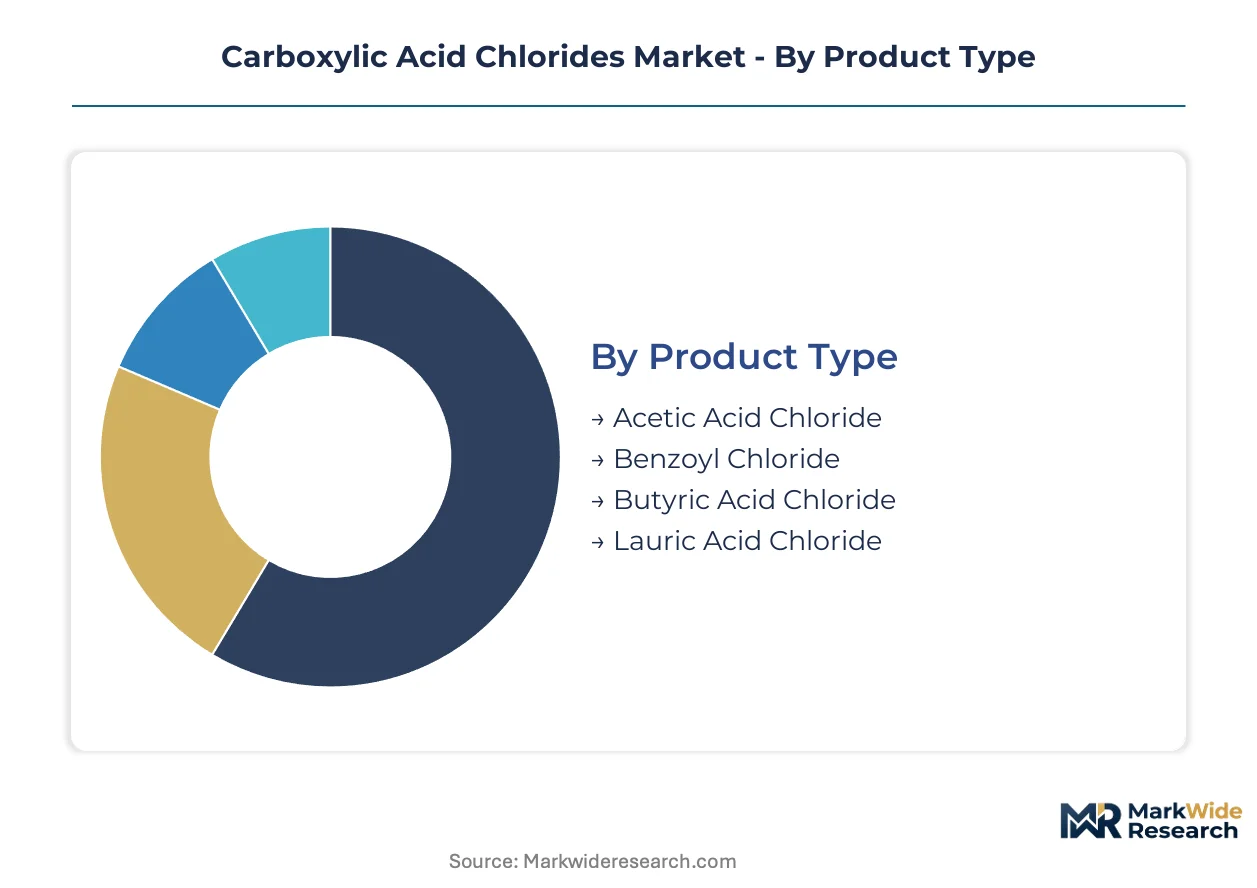
Carboxylic acid chlorides exhibit distinct demand profiles across product chemistries and end-use specifications. Segmentation reveals where margin pools concentrate versus where volume throughput dominates procurement economics.
Product Type:
Integration depth varies sharply: benzoyl chloride serves predominantly as a standalone acylating agent in pharmaceutical synthesis, while acetic and butyric variants embed more commonly into multi-step agrochemical process chains.
- Benzoyl Chloride:Aromatic acyl chloride manufactured through benzotrichloride hydrolysis or direct chlorination of benzoic acid. Demand concentrates in German and Swiss pharmaceutical corridors for benzophenone and antibiotic precursor synthesis, with EMA purity mandates compressing supplier qualification timelines.
- Acetic Acid Chloride:Simplest aliphatic acyl chloride produced via thionyl chloride reaction with acetic acid. Gujarat's chemical corridor absorbs the largest volumes for agrochemical acetylation reactions, though phosgene feedstock volatility under China's GB standards is elevating purification costs across Asian supply bases.
- Butyric Acid Chloride:Four-carbon chain acyl chloride used in specialty esterification and flavor intermediate production.
- Lauric Acid Chloride:Long-chain fatty acid derivative serving surfactant and polymer additive applications with lower purity thresholds than pharmaceutical grades.
Benzoyl chloride leads volumes today; acetic acid chloride is gaining share fastest in Asian agrochemical formulation expansion.
Application:
Cost tier stratification separates pharmaceutical-grade specifications from industrial bulk applications, with purity premiums spanning an order of magnitude between CDSCO-registered drug substances and polymer modification grades.
- Pharmaceuticals:Highest-margin application requiring impurity profiling under EMA and CDSCO mandates for active pharmaceutical intermediate synthesis. German API manufacturers are consolidating procurement around qualified vendors with documented halogen recovery systems.
- Agrochemicals:Volume-driven segment absorbing sulfur-containing acid chloride derivatives for fungicide and herbicide pipelines. India's Gujarat corridor anchors demand, with Shandong province's chlor-alkali infrastructure emerging as backward integration territory for regional formulators.
- Polymer Production:Industrial-grade acyl chlorides for polymer modification and additive synthesis, competing on throughput scale rather than unit economics.
- Flavoring Agents:Food-grade butyric and lauric derivatives subject to FSSAI and EFSA safety evaluations, with lower regulatory burden than pharmaceutical applications.
Pharmaceuticals command the steepest margin expansion trajectory; agrochemicals represent the largest absolute volume absorption.
End User:
Customer type determines contract structure: pharmaceutical companies negotiate eighteen-to-twenty-four month offtake agreements with embedded price adjustments, while chemical manufacturers retain greater spot market flexibility.
- Pharmaceutical Companies:Consolidating procurement around integrated chlorination specialists with REACH registration and CDSCO impurity filing capabilities. Long-term contracting is displacing spot purchasing for benzoyl chloride supply.
- Chemical Manufacturers:Merchant market participants serving downstream formulation with variable purity requirements across industrial and specialty grades.
- Agriculture Sector:Agrochemical formulators in India and China driving sulfur chloride derivative demand for crop protection synthesis.
- Food & Beverage Industry:Flavor and fragrance compounders utilizing short-chain acid chlorides under food safety regulator oversight.
Pharmaceutical companies anchor premium-tier procurement; chemical manufacturers represent the broadest customer base by account count.
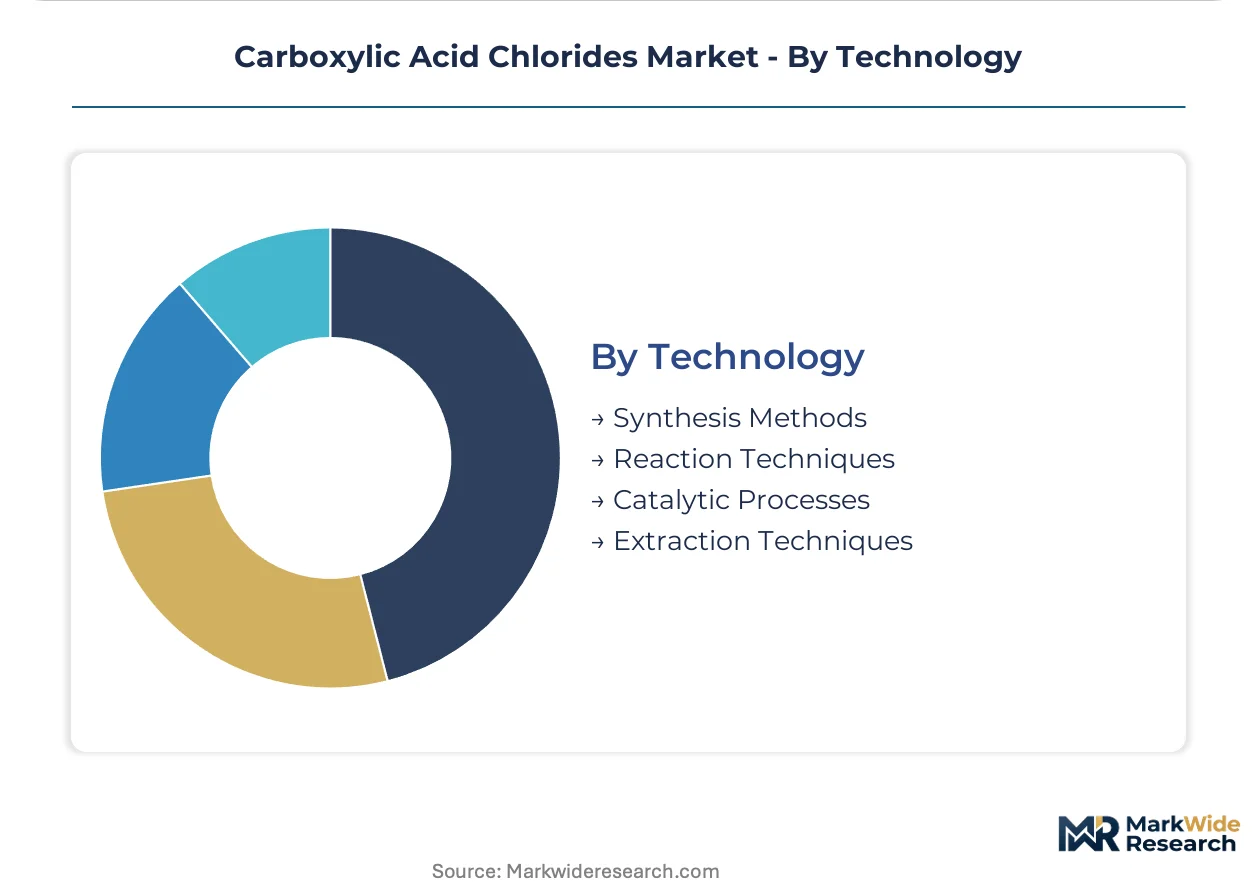
Technology:
Maturity gradients separate established thionyl chloride infrastructure from emerging catalytic halogen recovery systems that are rewriting capital efficiency calculations for integrated producers.
- Synthesis Methods:Conventional thionyl chloride and phosgene-mediated chlorination routes dominate at scale, with reaction temperature control below 80°C critical for product integrity.
- Catalytic Processes:Closed-loop thionyl chloride regeneration and membrane-based chlorine recovery systems are compressing variable cost spreads between merchant and captive production modes for benzoyl chloride manufacturers above fifty thousand tonne scale.
- Reaction Techniques:Continuous-flow chlorination reactor designs displacing batch operations in pharmaceutical intermediate manufacturing, reducing thermal degradation of sensitive acylating agents.
- Extraction Techniques:Purification and isolation methods for pharmaceutical-grade specifications, with aqueous quenching limitations excluding certain continuous-flow process deployments.
Synthesis methods retain the largest installed base; catalytic processes are climbing the fastest as membrane recovery modules retrofit existing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical corridors absorb premium-grade benzoyl chloride volumes at purity thresholds unmatched by India's agrochemical-heavy consumption patterns, yet both markets are tightening supplier qualification timelines under divergent regulatory frameworks.
United States
API manufacturers in New Jersey and Massachusetts drive pharmaceutical-grade procurement under EPA TSCA notification requirements. The FDA maintains impurity profiling standards for acyl chlorides incorporated into registered drug substances. Houston's petrochemical corridor hosts merchant producers serving agrochemical formulators with industrial-grade specifications.
Germany
BASF and specialty chemical compounders in Ludwigshafen anchor European demand for benzophenone precursors and antibiotic intermediates. REACH registration dossiers from ECHA enforce documentary rigor for acyl chloride imports above one tonne annually. Bavaria's pharmaceutical clusters are retrofitting thionyl chloride infrastructure with membrane-based chlorine recovery modules.
China
Shandong province's chlor-alkali expansion is attracting backward-integrated acyl chloride capacity for Asian agrochemical markets. SAMR's GB standards restrict residual phosgene content, elevating purification costs for domestic producers. Yangtze River Delta pharmaceutical manufacturers are qualifying European suppliers to circumvent registration bottlenecks.
India
Gujarat's chemical corridor concentrates sulfur chloride derivative demand for fungicide and herbicide synthesis pipelines. CDSCO mandates impurity profiling for pharmaceutical-grade acyl chlorides, compressing supplier qualification timelines. Shiva Pharmachem and Transpek Industry anchor merchant supply from Ankleshwar to Middle Eastern and African buyers.
Switzerland
Swissmedic oversight drives exacting purity specifications for pharmaceutical intermediates manufactured in Basel and Zurich pharmaceutical clusters. Specialty chemical producers are negotiating long-term offtake contracts with German API manufacturers. Alpine logistics constraints favor rail-linked suppliers with documented halogen recovery capabilities.
Carboxylic Acid Chlorides Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between integrated chlorination operators with captive phosgene access and merchant producers dependent on external feedstock supply. Three archetypes dominate: multinational chemical conglomerates with pharmaceutical-grade certification depth, regional specialists serving agrochemical formulators, and integrated chlor-alkali operators leveraging backward control over chlorine supply. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers seek to preempt authorization listing risks under REACH substance evaluation protocols.
Among European integrated operators, CABB Group GmbH exemplifies the conglomerate archetype with documented impurity profiling capabilities, while Transpek Industry Limited represents the sulfur chloride derivative specialist segment. Shiva Pharmachem Ltd occupies a position within India's merchant supplier tier serving Asian and Middle Eastern pharmaceutical accounts. These three companies illustrate the geographic and functional stratification that defines competitive positioning across the industry.
| Leading Market Players |
|---|
| BASF |
| ALTIVIA |
| CABB Group GmbH |
| VanDeMark |
| Transpek Industry Limited |
| Shiva Pharmachem Ltd |
| Novaphene Specialities Pvt. Ltd. |
| Cangzhou Runliqing Chemical Co. Ltd |
| Shandong Longyuan New Material Technology Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
REACH substance evaluation protocols are gating qualified supply access and premium-tier pricing power for benzoyl chloride derivatives, compressing merchant margins for producers without complete ECHA dossier submissions while rewarding integrated chlorination specialists with documented impurity profiling capabilities.
Pricing Analysis
Capacity additions in Shandong province are reshaping price floors for industrial-grade acyl chlorides across Asian agrochemical markets. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels separates CDSCO-registered drug substance specifications from polymer modification tiers. Cost compression in technical-grade segments is intensifying because phosgene feedstock volatility under China's GB standards elevates purification expenditures. Chemical manufacturers exhibit the highest price sensitivity, while pharmaceutical companies absorb premium spreads for REACH-registered supply.
Supply Chain Analysis
Thionyl chloride recovery and halogen regeneration flows are creating closed-loop material economics for integrated producers above fifty thousand tonne scale. Supply concentrates in Germany, India, and China, with Ludwigshafen and Gujarat anchoring merchant availability. Production draws from benzotrichloride, thionyl chloride, and phosgene feedstocks, with residual phosgene content restrictions creating regulatory friction. Single-source vulnerability runs through concentrated specialty chemical clusters lacking dual-source qualification. Distribution runs through long-term offtake contracting with eighteen-to-twenty-four month agreements displacing spot purchasing for pharmaceutical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EMA and CDSCO purity mandates are accelerating supplier consolidation and deepening margin pools for qualified incumbents.
For Market Incumbents: Anchor procurement relationships through backward integration into chlor-alkali infrastructure and membrane-based chlorine recovery systems. Defend against emerging biocatalytic acylation substitutes by accelerating CDSCO impurity filing capabilities and pre-validated analytical method libraries. Capacity addition in Shandong province represents the priority geographic lever for Asian agrochemical exposure. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade benzoyl chloride offers white-space entry for regional specialists with documented halogen recovery capabilities. Target sulfur chloride derivative adjacencies in India's Gujarat corridor where agrochemical formulation expansion outpaces qualified supply. Pursue joint development agreements with API manufacturers seeking dual-source qualification beyond Ludwigshafen and Gujarat concentrations. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant producers lacking REACH registration completeness yet possessing retrofit-ready thionyl chloride infrastructure. Long-term viability across the analysis window favors integrated chlorination specialists with captive phosgene access and polymer additive diversification. Watch ECHA's rolling action plan for benzoyl chloride derivative authorization listings as the inflection signal for asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive chlorine supply insulates margin compression from feedstock volatility under China's GB standards. |
| Membrane-Based Halogen Recovery | Bavaria's pharmaceutical clusters are retrofitting infrastructure with separation modules from German engineering suppliers. |
| CDSCO Impurity Filing Acceleration | Pre-validated analytical methods create first-mover advantage as India's pharmaceutical-grade specifications tighten. |
| Long-Term Supply Agreement Restructuring | Eighteen-to-twenty-four month offtake contracts with embedded price adjustments displace spot purchasing for benzoyl chloride. |
| Biocatalytic Acylation R&D Partnership | Enzyme-mediated chlorination pathways open compatibility with temperature-sensitive active pharmaceutical intermediates. |
Study Parameters
Bottom-up pharmaceutical and agrochemical end-use modeling reconciled against top-down chlor-alkali capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated chlorination facilities, procurement leads at German API manufacturers, distribution channel partners in Gujarat's chemical corridor, and technical R&D directors at specialty chemical compounders were validated against secondary sources including customs and trade data, Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and ECHA registration dossiers.
Input-output matrices mapping thionyl chloride consumption to benzoyl chloride output, phosgene availability to purification cost structures, and membrane recovery adoption to variable cost spreads drive the quantitative framework across the modeling period. Segmentation dimensions include product chemistry tier, end-use industry, purity grade specification, regional production hub, and regulatory registration status. CAGRs were derived from supply-demand balance modeling incorporating capacity expansion announcements, REACH evaluation timelines, and CDSCO mandate implementation trajectories.
Caveats apply where ECHA authorization listing decisions, phosgene feedstock supply disruptions, or biocatalytic substitution breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding continued pharmaceutical-grade premium persistence and agrochemical volume absorption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Sequencing Reagents Market
Chemical Intermediates
Natural Chelating Agents Market