
 Smart Bus Shelters Market | 2026-2036
Smart Bus Shelters Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bus Shelters Market Insights
Aftermarket service revenue is fragmenting across the competitive landscape as shelter operators seek recurring income beyond hardware installation. JCDecaux Group leverages its long-term municipal concession agreements to sustain maintenance contracts spanning multiple electoral cycles. Clear Channel Outdoor anchors its position through geographic dominance in dense North American transit corridors, while Daktronics differentiates via technology leadership in LED display integration for real-time passenger information systems.
Smart bus shelters are weather-protected passenger waiting structures incorporating photovoltaic panels, environmental sensors, wireless connectivity modules, and dynamic digital displays, typically manufactured from powder-coated aluminum extrusions with tempered glass enclosures and designed to deliver real-time transit data, emergency communication, and advertising inventory to urban mobility networks. Solar-powered configurations and IoT sensor arrays represent the fastest-growing product and technology segments as municipalities prioritize energy autonomy and predictive maintenance capabilities. Interactive display modules command premium positioning within the product mix due to their dual revenue function combining passenger utility with programmatic advertising inventory.
The Federal Communications Commission governs wireless emissions from embedded connectivity hardware in the United States, while the EU Green Deal and F-Gas Regulation constrain refrigerant-based climate control systems in European deployments, collectively elevating compliance costs for manufacturers serving multiple jurisdictions. China's Ministry of Industry and Information Technology administers GB standards for outdoor electronic display safety and electromagnetic compatibility. Stakeholders must monitor evolving procurement frameworks that increasingly bundle installation, data analytics, and advertising revenue sharing into unified long-term service contracts rather than discrete capital expenditures.
Market Dynamics
Municipal procurement frameworks are converging on unified service contracts that bundle hardware installation, connectivity infrastructure, and long-term data analytics into single concession agreements, compressing traditional capital expenditure cycles and elevating vendor operational capabilities over pure manufacturing scale.
Growth Catalysts
- EU Green Deal mandates:National smart city programs in Germany, France, and the United Kingdom now specify solar-integrated shelter specifications, accelerating replacement cycles for legacy infrastructure.
- IoT sensor convergence:Environmental monitoring arrays enabling predictive maintenance are becoming standard in tier-one Chinese metropolitan corridors as part of broader urban digitization strategies.
- FCC wireless governance:Embedded connectivity modules for real-time passenger information systems now face clearer certification pathways in the United States, reducing deployment friction for shelter operators.
Market Restraints
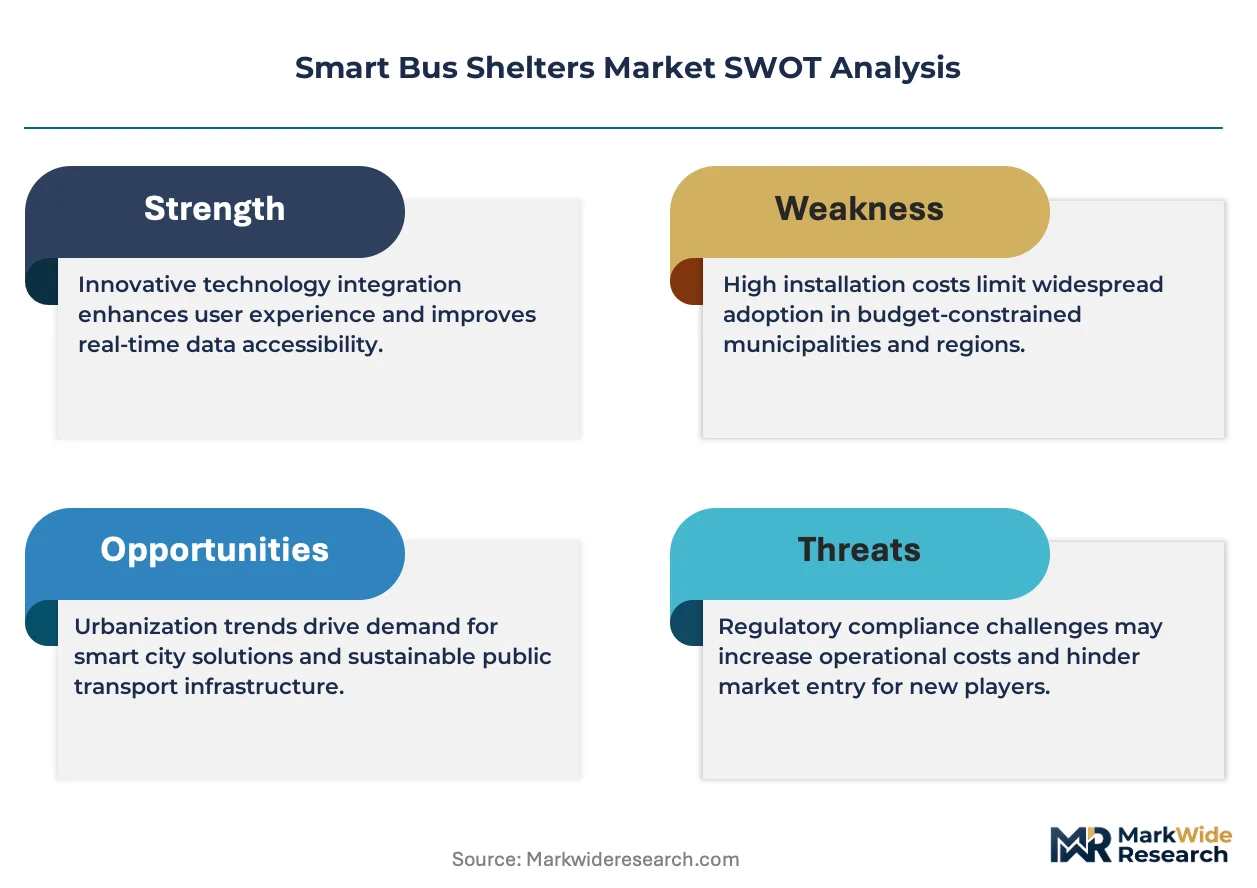
- Aluminum extrusion cost volatility:Powder-coated aluminum framing constitutes the primary structural material, exposing manufacturers to commodity price swings from smelter concentration in specific geographies.
- F-Gas Regulation constraints:The European Union's refrigerant-based climate control restrictions elevate compliance costs for manufacturers serving multiple jurisdictions with differing thermal management requirements.
- Legacy grid dependency:Non-solar configurations face rising operational cost disadvantages as electricity pricing pressure intensifies across North American and European utility markets.
Strategic Opportunities
- Programmatic advertising inventory:Interactive display modules combining passenger utility with dynamic ad serving create dual revenue streams previously uncaptured by static shelter infrastructure.
- Aftermarket service unbundling:Maintenance contracts spanning multiple electoral cycles offer recurring revenue potential beyond discrete hardware installation for operators with long-term municipal relationships.
- GB standards alignment:China's Ministry of Industry and Information Technology safety certifications for outdoor electronic displays create export pathway advantages for compliant manufacturers.
Industry Challenges
- Electromagnetic compatibility certification:Multi-jurisdictional deployments require simultaneous compliance with FCC emissions standards, EU CE marking, and Chinese GB protocols, extending product validation timelines.
- Concession agreement complexity:Revenue-sharing negotiations between shelter operators, transit agencies, and advertising intermediaries create contractual friction that delays deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bus Shelters Market |
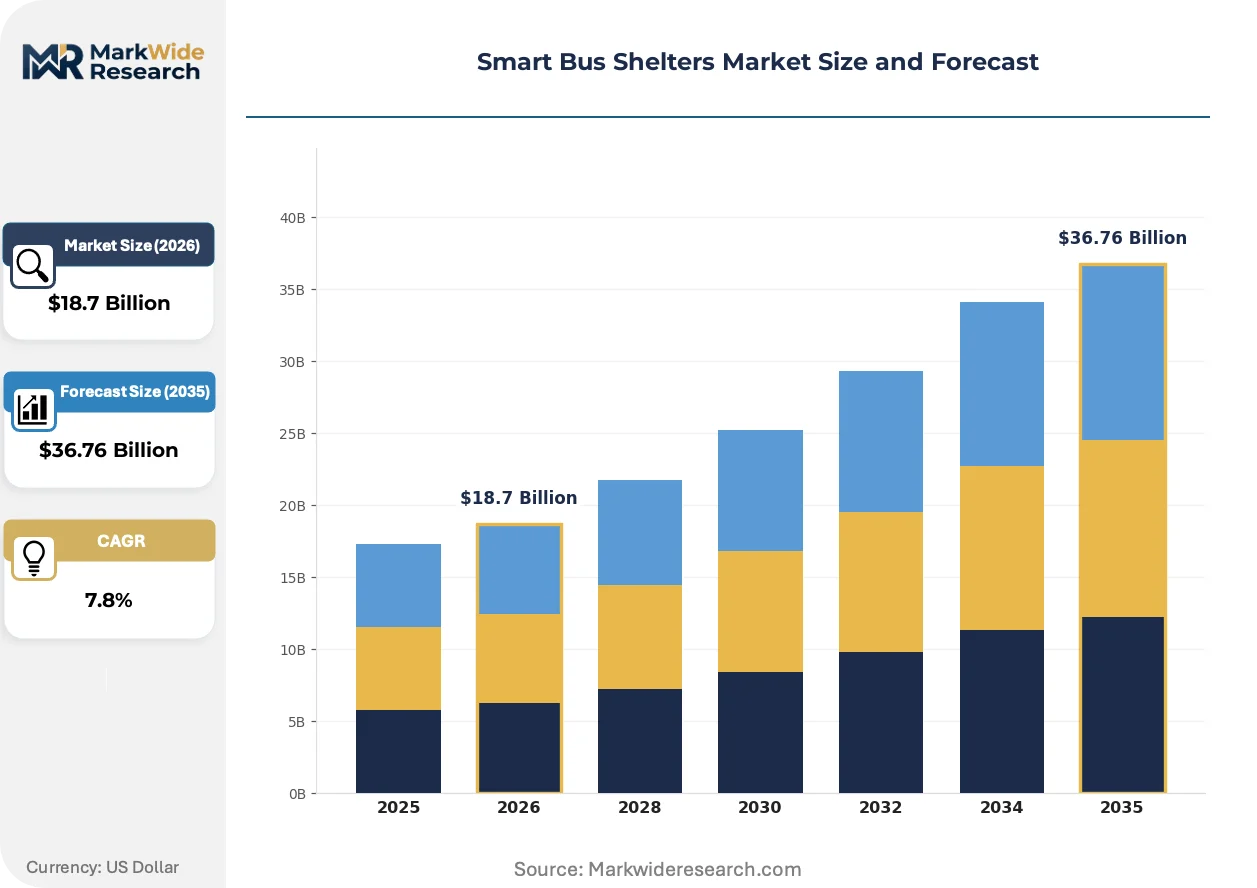
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar-Powered, Interactive Displays, Security Features, Seating Arrangements Technology: Wi-Fi, IoT Sensors, Digital Signage, Mobile App Integration End User: Public Transport Authorities, Local Governments, Private Operators, Urban Planners Service Type: Installation Services, Maintenance Services, Customization Services, Consulting Services |
| Companies Covered | Yongye Industry, Kaich Intelligence Urban Facilities, JCDecaux Group, Jiangsu Wohua Smart Technology, Hummax Display Systems, Clear Channel Outdoor, Foshan YEROO Advertising Engineering, Daktronics, Outfront Media, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bus Shelters Market Trends and Innovations
Three distinct vectors are compressing traditional shelter economics: photovoltaic integration is collapsing energy autonomy timelines, regulatory frameworks are hardening around embedded emissions and materials safety, and procurement models are shifting from capital purchase to performance-based service contracting.
Perovskite-enhanced photovoltaic laminates are achieving higher conversion efficiency in limited surface areas than conventional silicon panels, enabling meaningful energy capture even on compact shelter rooftops. Municipal agencies in sun-belt corridors are specifying these configurations as baseline requirements. Monocrystalline silicon alternatives are rendering obsolete for new-build shelter deployments where space constraints dominate design specifications.
The EU F-Gas Regulation is systematically constraining hydrofluorocarbon-based climate control systems in outdoor infrastructure, forcing manufacturers toward thermoelectric or phase-change thermal management. European shelter deployments now prioritize passive ventilation designs over active cooling. German and French procurement specifications are most advanced in mandating refrigerant-free alternatives, with United Kingdom frameworks following closely.
Advertising revenue sharing is displacing pure lease-fee structures as the dominant municipal compensation model, restructuring vendor cash flow profiles toward long-term annuity streams. Dense North American transit corridors are pioneering these arrangements, with shelter operators ceding upfront capital recovery for extended concession rights. This behavioral shift is most pronounced in metropolitan markets where programmatic ad tech infrastructure already exists.
Smart Bus Shelters Market Segmentation
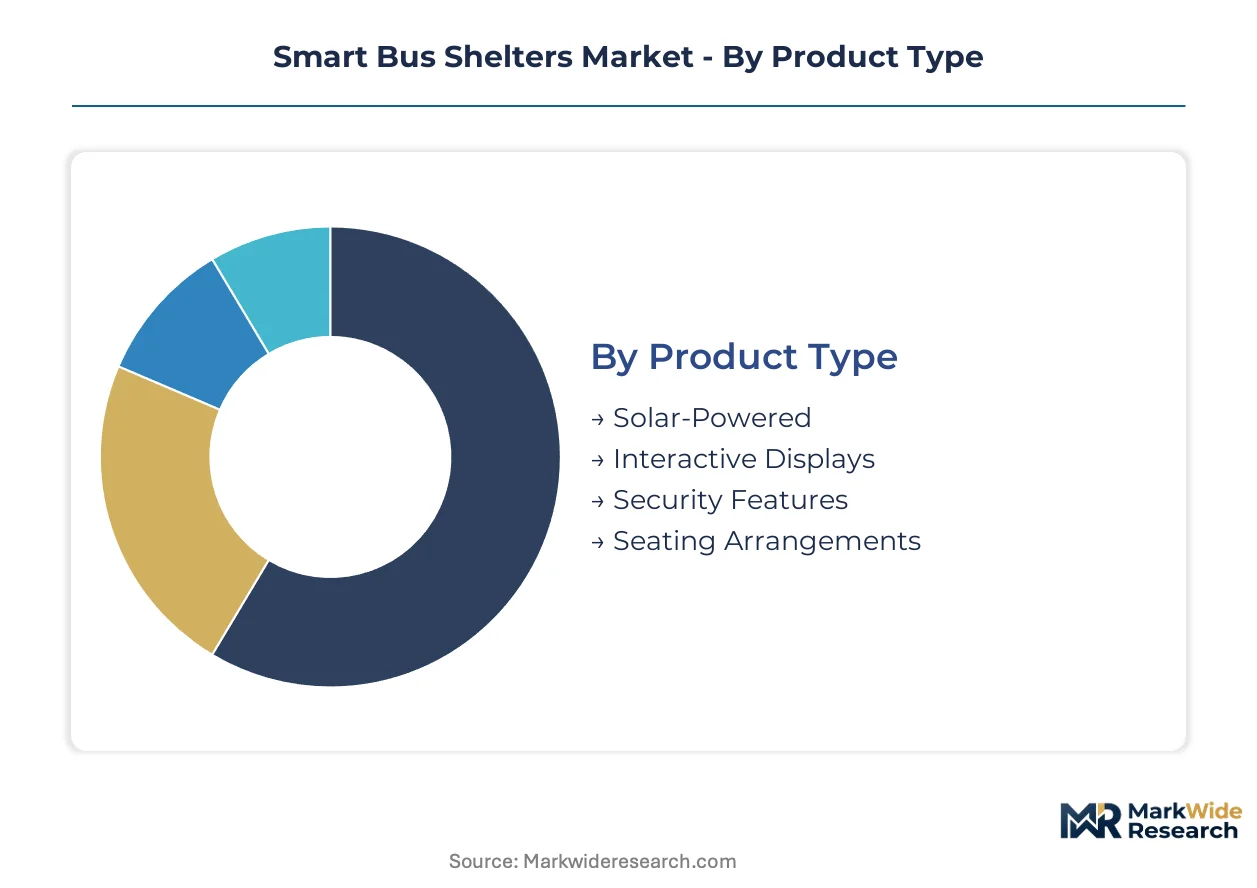
Segmentation in the Smart Bus Shelters Market reveals how procurement priorities diverge between mature infrastructure replacement and emerging technology deployment. Municipal buyers weigh energy autonomy against passenger amenities, while service models shift from capital purchase to long-term operational contracts.
Product Type:
Mature configurations dominate installed base volumes, while emerging variants capture replacement cycle specifications and new-build mandates.
- Solar-Powered:Photovoltaic laminates integrated into shelter rooftops enable grid-independent operation. Tier-one Chinese metropolitan corridors specify these as baseline requirements under urban digitization strategies, with perovskite-enhanced variants achieving superior conversion efficiency in compact surface areas.
- Interactive Displays:Touch-enabled digital panels combine real-time transit data with programmatic advertising inventory. Dense North American transit corridors prioritize these modules for dual revenue generation, displacing static advertising structures in concession negotiations.
- Security Features:Emergency communication systems and surveillance integration address passenger safety mandates.
- Seating Arrangements:Configurable bench designs accommodate accessibility requirements and passenger throughput volumes.
Solar-Powered configurations handle the majority of throughput in new municipal procurement; Interactive Displays are gaining share fastest as advertising revenue-sharing models displace pure lease-fee structures.
Technology:
Technology selection follows a cost-tier logic, with premium connectivity commanding higher procurement budgets and basic integration serving retrofit installations.
- IoT Sensors:Environmental monitoring arrays embedded in shelter structures enable predictive maintenance and air quality indexing. German and French procurement specifications now mandate these as standard components under EU Green Deal frameworks, accelerating replacement of legacy passive infrastructure.
- Digital Signage:LED display systems deliver real-time passenger information and emergency broadcasts. Sun-belt municipal agencies specify high-brightness variants for outdoor visibility compliance, with content management systems integrated into broader smart city data platforms.
- Wi-Fi:Wireless connectivity modules provide passenger internet access and backhaul for shelter telemetry.
- Mobile App Integration:API connectivity synchronizes shelter displays with transit agency applications.
IoT Sensors absorb the largest share of technology procurement budgets; Digital Signage is expanding most quickly as municipalities bundle advertising rights with infrastructure deployment.
End User:
Customer type segmentation reflects divergent procurement authority and revenue model sophistication across institutional buyers.
- Public Transport Authorities:Municipal transit agencies with dedicated capital budgets and long-term concession authority. These entities in the United Kingdom and Germany are pioneering unified service contracts that bundle installation, connectivity, and data analytics into single electoral-cycle-spanning agreements.
- Local Governments:City administrative bodies responsible for streetscape infrastructure and zoning compliance. Procurement concentrates in metropolitan corridors where smart city mandates intersect with climate action plans, particularly in France and the United Kingdom.
- Private Operators:Commercial entities managing shelter networks under advertising revenue-sharing arrangements.
- Urban Planners:Technical consultants specifying shelter integration into broader mobility corridor designs.
Public Transport Authorities control the dominant share of deployment volume; Private Operators are climbing fastest as concession models shift toward performance-based contracting.
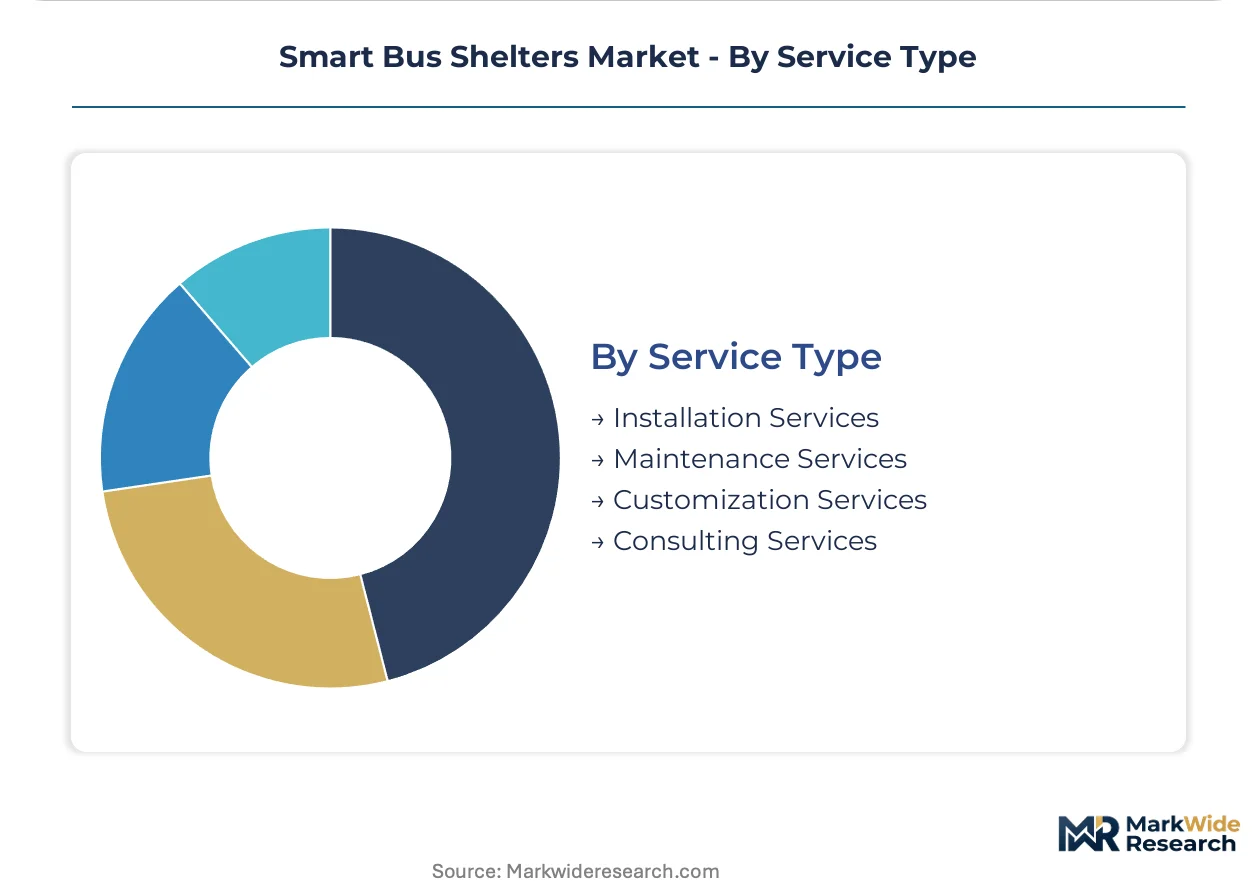
Service Type:
Service segmentation tracks the unbundling of traditional hardware sales into recurring revenue streams and specialized technical offerings.
- Installation Services:Site preparation, foundation work, and shelter assembly including electrical and network integration. French and German municipal frameworks now require installation contractors to assume multi-year operational liability, elevating vendor qualification barriers.
- Maintenance Services:Scheduled upkeep, component replacement, and connectivity troubleshooting across extended contract terms. These contracts spanning multiple electoral cycles offer shelter operators recurring income beyond discrete hardware margins.
- Customization Services:Design modifications for climate-specific or aesthetic requirements.
- Consulting Services:Procurement advisory and concession structure negotiation support.
Installation Services command the largest absolute expenditure; Maintenance Services show the steepest expansion trajectory as procurement frameworks compress capital expenditure cycles into operational contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum extrusion supply chains concentrate in Chinese smelter clusters, yet procurement authority for finished shelter systems distributes across municipal transit agencies in Germany, the United Kingdom, China, and the United States. Deployment velocity varies sharply by regulatory environment and concession framework maturity.
Germany
Municipal transit authorities in Berlin and Hamburg prioritize solar-integrated specifications under the EU Green Deal's national implementation framework. The KBA and federal building codes mandate refrigerant-free thermal management in outdoor infrastructure procurement. Bavarian manufacturers supply powder-coated aluminum framing to domestic operators while competing for export contracts across the European Union.
United Kingdom
Transport for London and regional combined authorities bundle installation, connectivity, and advertising rights into unified service contracts spanning multiple electoral cycles. The UK Net Zero Strategy accelerates replacement of legacy grid-dependent shelters in Greater Manchester and the West Midlands. Scottish procurement frameworks follow England's concession model with shorter contract durations.
China
Tier-one metropolitan corridors in Shanghai, Beijing, and Shenzhen specify IoT-enabled passenger amenities as mandatory components of urban digitization strategies. The Ministry of Industry and Information Technology administers GB standards for outdoor electronic display safety and electromagnetic compatibility. Yangtze River Delta shelter fabricators achieve cost advantages through vertical integration into aluminum smelting and glass tempering.
United States
Dense transit corridors in New York, Los Angeles, and Chicago pioneer programmatic advertising revenue-sharing arrangements that displace pure lease-fee municipal compensation. The FCC governs wireless emissions from embedded connectivity hardware, clarifying certification pathways for real-time passenger information systems. Sun-belt agencies in Phoenix and Miami specify perovskite-enhanced photovoltaic configurations as baseline requirements.
France
Île-de-France Mobilités and Lyon metropolitan authorities mandate sensor-equipped shelters under national smart city programs aligned with EU Green Deal targets. ANSM and CNIL oversight extends to data collection from passenger-facing IoT arrays. Auvergne-Rhône-Alpes procurement specifications lead European adoption of thermoelectric climate control alternatives to hydrofluorocarbon-based systems.
Smart Bus Shelters Market Competitive Landscape
Outdoor advertising concession holders and transit infrastructure specialists split the market based on revenue model sophistication and municipal relationship depth. The vendor base organizes around three strategic archetypes: integrated media operators with long-term municipal agreements, display technology integrators, and regional shelter fabricators with aluminum extrusion capabilities. Competitive positioning hardens through multi-decade concession rights and technology licensing partnerships rather than manufacturing scale alone.
Within the integrated media tier, JCDecaux Group and Clear Channel Outdoor exemplify operators leveraging concession duration to capture recurring maintenance revenue beyond hardware margins. Daktronics anchors the display technology vector through LED integration capabilities. Chinese specialists including Yongye Industry and Kaich Intelligence Urban Facilities occupy positions in the high-volume fabrication segment serving domestic procurement frameworks.
| Leading Market Players |
|---|
| Yongye Industry |
| Kaich Intelligence Urban Facilities |
| JCDecaux Group |
| Jiangsu Wohua Smart Technology |
| Hummax Display Systems |
| Clear Channel Outdoor |
| Foshan YEROO Advertising Engineering |
| Daktronics |
| Outfront Media |
| Others |
Pricing and Supply Chain Analysis
Chinese aluminum smelter clusters in Shandong and Henan provinces concentrate upstream supply of powder-coated extrusions, anchoring margin pools with shelter fabricators who command multi-year municipal concession negotiations rather than pure manufacturing scale.
Pricing Analysis
Aftermarket maintenance contracts spanning multiple electoral cycles drive lifetime value capture for operators with entrenched municipal relationships. Three-tier pricing structure across premium, standard, and economy levels separates solar-integrated IoT configurations from basic grid-dependent units and legacy retrofit installations. Cost compression in standard-tier hardware is intensifying because Yangtze River Delta fabricators achieve captive supply of tempered glass and aluminum framing. Public transport authorities in Germany and the United Kingdom exhibit lowest price sensitivity due to bundled service contracting, while private operators in emerging procurement frameworks face acute margin pressure.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Yangtze River Delta shelter fabricators and Bavarian aluminum processors serving European demand. Supply chains draw from Chinese photovoltaic laminate producers, German thermoelectric climate control specialists, and North American LED display integrators. Single-source vulnerability runs through perovskite-enhanced photovoltaic substrate supply constrained to limited production lines. Distribution runs through municipal procurement frameworks that bundle installation, connectivity infrastructure, and long-term data analytics into unified concession agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart bus shelters function as edge-computing nodes in municipal data platforms, with interoperability standards across transit agency APIs and advertising tech stacks determining which operators capture platform economics.
For Market Incumbents: Entrench position through backward integration into aluminum extrusion and photovoltaic laminate production, insulating margin pools from commodity volatility. Lock extended concession durations by assuming operational liability for multi-year maintenance contracts under French and German municipal frameworks. Counter emerging display technology integrators by embedding proprietary content management systems into broader smart city data platforms. For New Entrants and Emerging Players: Tier-two Chinese metropolitan corridors and secondary North American transit markets represent the most penetrable entry points where incumbent concession coverage remains thin. Target private operators transitioning from pure advertising revenue-sharing to performance-based infrastructure contracting as anchor customers. Differentiate through rapid-deployment solar configurations that bypass legacy grid connection timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor advertising concession holders seeking infrastructure technology capabilities. Long-term viability hinges on 5-10 year municipal digitization budget commitments rather than cyclical advertising spend. Monitor procurement specification shifts toward refrigerant-free climate control and perovskite photovoltaic mandates as inflection indicators for technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Duration Extension | Multi-cycle municipal contracts lock out competitors in Berlin and Hamburg transit corridors. |
| Photovoltaic Technology Licensing | Perovskite laminate partnerships differentiate solar configurations in sun-belt municipal specifications. |
| Platform Integration Partnership | API connectivity with Transport for London data systems embeds vendors into transit agency workflows. |
| Acquisition of Display Technology Specialist | LED integration capabilities address real-time passenger information mandates in tier-one Chinese cities. |
| Geographic Manufacturing Footprint | Yangtze River Delta production achieves cost proximity to domestic procurement and European export markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of municipal procurement databases, FCC equipment authorization filings, EU tender documentation, and Chinese GB standard certification records. Primary interviews engaged transit agency procurement directors, shelter operator concession managers, aluminum extrusion plant engineers, and LED display integration specialists. Bottom-up unit deployment estimates triangulate against top-down municipal capital expenditure disclosures and advertising revenue-sharing contract values.
Forecast inputs incorporate photovoltaic cost curves, IoT sensor penetration rates across urban digitization programs, and concession framework maturity by metropolitan market. Segmentation dimensions span product configuration, technology tier, end-user procurement authority, and service model unbundling. CAGRs derive from logistic diffusion modeling of solar-powered adoption and replacement cycle compression under EU Green Deal mandates. Aluminum commodity pricing volatility and electromagnetic compatibility certification timelines feed sensitivity bands.
Stress conditions across aluminum smelter concentration risk, municipal budget freeze scenarios, and refrigerant regulation acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on concession term standardization and advertising revenue-sharing penetration. Quarterly review of municipal tender issuance rates and GB standards revision schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Bike Sharing Market