
 Car E-Hailing Market | 2026-2036
Car E-Hailing Market Size, Share, and Industry Trends Forecast 2026-2036
Car E-Hailing Market Outlook
The EU Green Deal is repositioning fleet procurement across European operators. Uber Technologies Inc. leverages its global driver network to sustain density in high-frequency corridors. Didi Chuxing Technology Co. anchors its competitive position through deep integration with domestic mapping and payment ecosystems. ANI Technologies Pvt. Ltd. (Ola) dominates the Indian market with localized service tiers and regional language interfaces.
Car e-hailing denotes digitally intermediated on-demand passenger transport where mobile applications algorithmically match riders with private vehicle operators, typically incorporating real-time GPS positioning, dynamic fare calculation, and cashless settlement protocols. The primary commercial purpose centers on substituting personal vehicle ownership with accessible, metered mobility consumption. Standard Rides capture the volume base across most operating regions, while Electric Vehicles within the fleet mix represent the fastest-growing asset category as municipalities tighten emission mandates. Corporate Clients generate disproportionate margin contribution through contracted enterprise accounts and predictable trip scheduling.
The US Department of Transportation and the European Commission's F-Gas Regulation jointly shape vehicle eligibility and emission thresholds for platform-operated fleets. India's Ministry of Road Transport and Highways enforces vehicle fitness and driver certification standards that gate market access for aggregators. Fleet managers must monitor evolving battery-electric range requirements and charging infrastructure density as decisive variables for capital deployment timing.
Market Dynamics
The EU Green Deal and parallel zero-emission mandates in California and Beijing are forcing fleet operators to accelerate battery-electric vehicle procurement timelines. This regulatory compression is redrawing capital allocation priorities across platform economics.
Growth Catalysts
- EU F-Gas Regulation:Stringent emission thresholds for mobile air conditioning systems are pushing operators toward electric drivetrains with climate-friendly refrigerants.
- Urban corridor density:Metropolitan clusters in India, Brazil, and Indonesia generate sufficient trip velocity to justify dedicated fleet investments and driver incentive programs.
- Dynamic pricing algorithms:Real-time demand-supply matching technology is compressing passenger wait times and improving vehicle utilization rates during off-peak windows.
Market Restraints
- Lithium-ion cell supply:Concentrated cathode precursor refining in Indonesia and the Democratic Republic of Congo creates input cost volatility for battery procurement.
- Driver classification litigation:Employment status disputes under the US Fair Labor Standards Act and EU platform work directives threaten variable-cost labor models.
- Public transit substitution:Expanded metro rail networks in São Paulo, Mexico City, and Jakarta siphon short-haul demand from ride-hail platforms.
Strategic Opportunities
- Corporate mobility budgets:Enterprise account structures in Germany and the United Kingdom are consolidating ground transportation spend under contracted platform agreements.
- Vehicle-to-grid integration:Bidirectional charging infrastructure convergence with utility demand-response programs opens ancillary revenue streams for idle fleet assets.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are reducing battery pack costs for domestic fleet electrification.
Industry Challenges
- Driver retention economics:Platform commission structures and fuel price exposure are eroding net earnings in high-inflation corridors.
- Interoperability standards:Fragmented data protocols between mapping engines, payment gateways, and municipal permit systems complicate cross-border expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car E-Hailing Market |
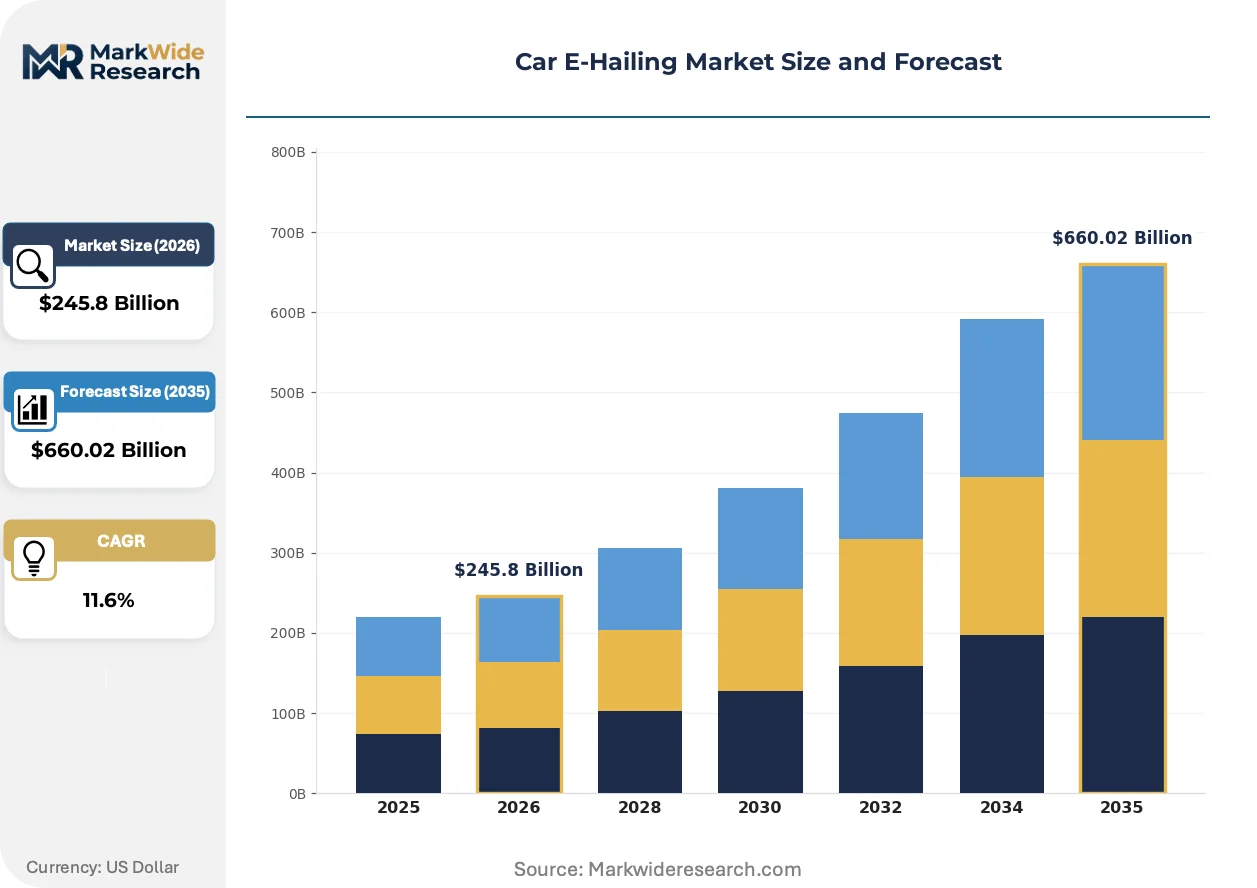
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $660.02 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride Sharing, Carpooling, Luxury Rides, Standard Rides Customer Type: Individual Users, Corporate Clients, Event Planners, Tourists Vehicle Type: Standard Sedans, SUVs, Electric Vehicles, Vans Technology: Mobile Apps, GPS Tracking, Payment Systems, User Ratings |
| Companies Covered | Uber Technologies Inc., Lyft Inc., Didi Chuxing Technology Co., Grab Holdings Inc., ANI Technologies Pvt. Ltd. (Ola), Gojek, Bolt Technology OÜ, Careem, Gett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car E-Hailing Market Strategic Shifts
Battery-electric drivetrain deployment and algorithmic fleet orchestration are compressing the cost gap between owned and shared mobility. Platform operators now compete on charging infrastructure density rather than driver headcount alone.
Swappable battery architecture is modularizing fleet operations across high-utilization corridors. Operators in Shenzhen and Taipei are adopting hot-swap stations that minimize vehicle downtime. This modularizing approach decouples energy replenishment from parking asset requirements.
The EU AI Act's risk classification framework is reshaping algorithmic transparency obligations for automated dispatch systems. High-risk categories now mandate human oversight protocols and bias auditing. European operators are retraining engineering teams to meet documentation and conformity assessment timelines.
Subscription-based mobility passes are displacing per-trip purchasing in Nordic and German metropolitan areas. Corporate procurement teams now bundle ride-hail, bike-share, and transit access under single employer-subsidized contracts. This shift is most visible in Copenhagen and Berlin, where municipal transit authorities partner directly with platform aggregators.
Car E-Hailing Market Segmentation
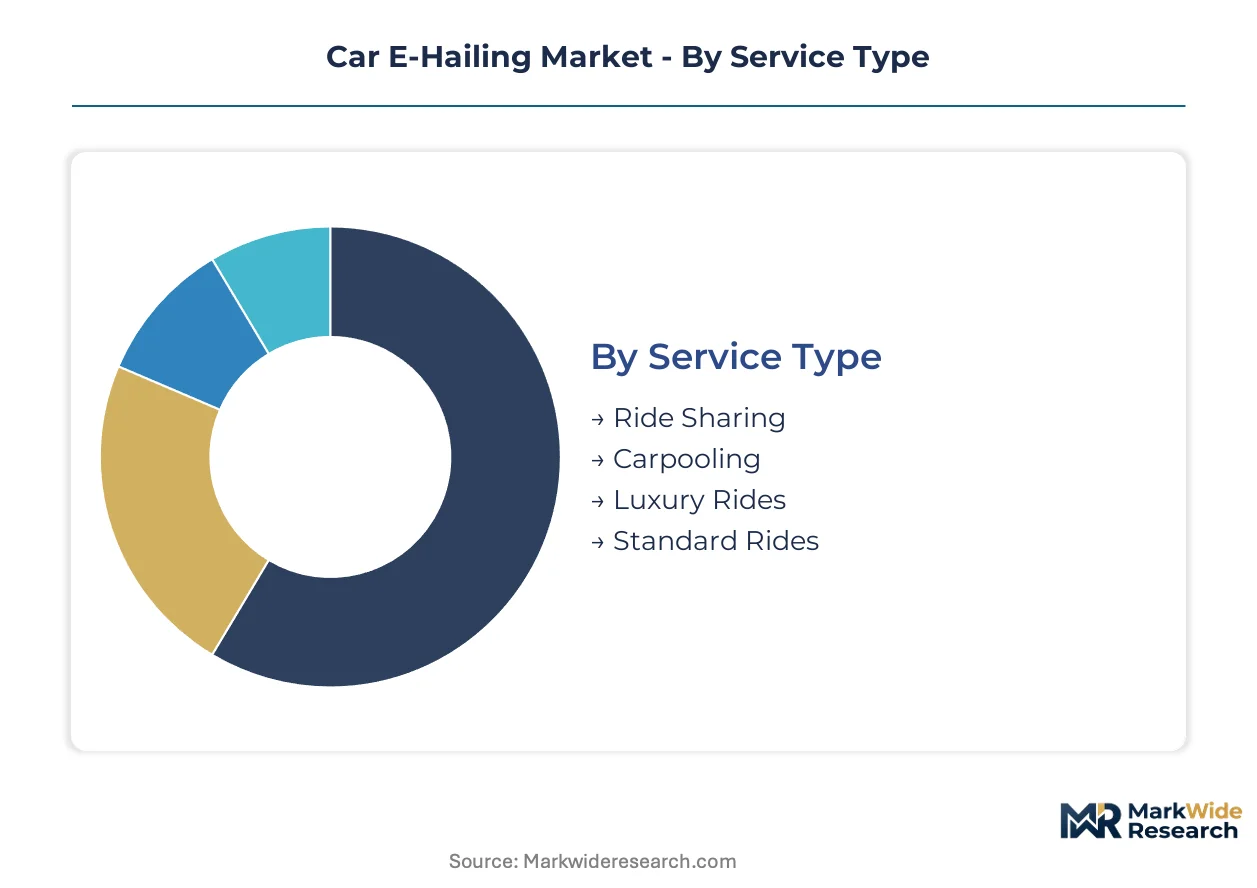
Car e-hailing platforms algorithmically match heterogeneous demand profiles with differentiated supply tiers. Segmentation discipline determines pricing architecture, fleet procurement priorities, and driver incentive calibration across metropolitan corridors.
Service Type:
Price sensitivity and trip purpose fragment demand across four distinct service tiers.
- Standard Rides:Algorithmically dispatched private vehicle transport with metered fare calculation and real-time GPS routing. Volume concentrates in India, Brazil, and Indonesia where middle-class commuters substitute personal vehicle ownership with predictable mobility consumption.
- Luxury Rides:Premium vehicle categories with professional chauffeurs and guaranteed arrival windows. Demand clusters in corporate travel budgets across Germany and the United Kingdom where enterprise procurement teams consolidate ground transportation spend.
- Ride Sharing:Multi-passenger pooling algorithms that match co-directional travelers into shared vehicle capacity. Municipal emission mandates in California and Beijing accelerate adoption as cities restrict single-occupancy vehicle access.
- Carpooling:Pre-scheduled commuter matching for recurring route patterns, typically employer-facilitated or residential cluster-organized. India's Ministry of Road Transport and Highways fitness certification requirements gate platform eligibility for this segment.
Volume sits with Standard Rides; growth tilts toward Electric Vehicles within fleet composition.
Customer Type:
Contract structure and trip predictability separate recurring revenue accounts from transactional demand.
- Corporate Clients:Enterprise accounts with contracted rate cards, centralized billing, and predictable scheduling patterns. Germany's CSRD disclosure requirements are extending supply chain due diligence to mobility procurement decisions.
- Individual Users:Episodic demand from retail consumers with price-elastic trip frequency and platform-switching behavior. Dynamic pricing algorithms compress wait times during peak windows across São Paulo and Mexico City corridors.
- Event Planners:Coordinated logistics for conferences, weddings, and entertainment venues requiring guaranteed vehicle availability and consolidated billing.
- Tourists:International visitors with limited local navigation knowledge and elevated sensitivity to payment friction and language accessibility.
Margin concentrates with Corporate Clients; expansion tilts toward Tourists as cross-border payment integration matures.
Vehicle Type:
Capital intensity and regulatory compliance create divergent fleet economics across powertrain and body configurations.
- Electric Vehicles:Battery-electric drivetrains with zero tailpipe emissions and lower per-kilometer energy costs. The EU Green Deal and California Air Resources Board mandates are compressing procurement timelines for platform-operated fleets.
- Standard Sedans:Internal combustion passenger vehicles optimized for urban fuel efficiency and maintenance accessibility. India's PLI scheme for advanced chemistry cell manufacturing is gradually eroding the total-cost-of-ownership advantage.
- SUVs:Higher-capacity vehicles serving airport transfers, group travel, and premium service tiers with luggage accommodation requirements.
- Vans:Multi-passenger configurations for corporate shuttle contracts and event logistics with consolidated trip economics.
Deployment tilts toward Electric Vehicles; residual value risk concentrates with Standard Sedans as emission zones expand.
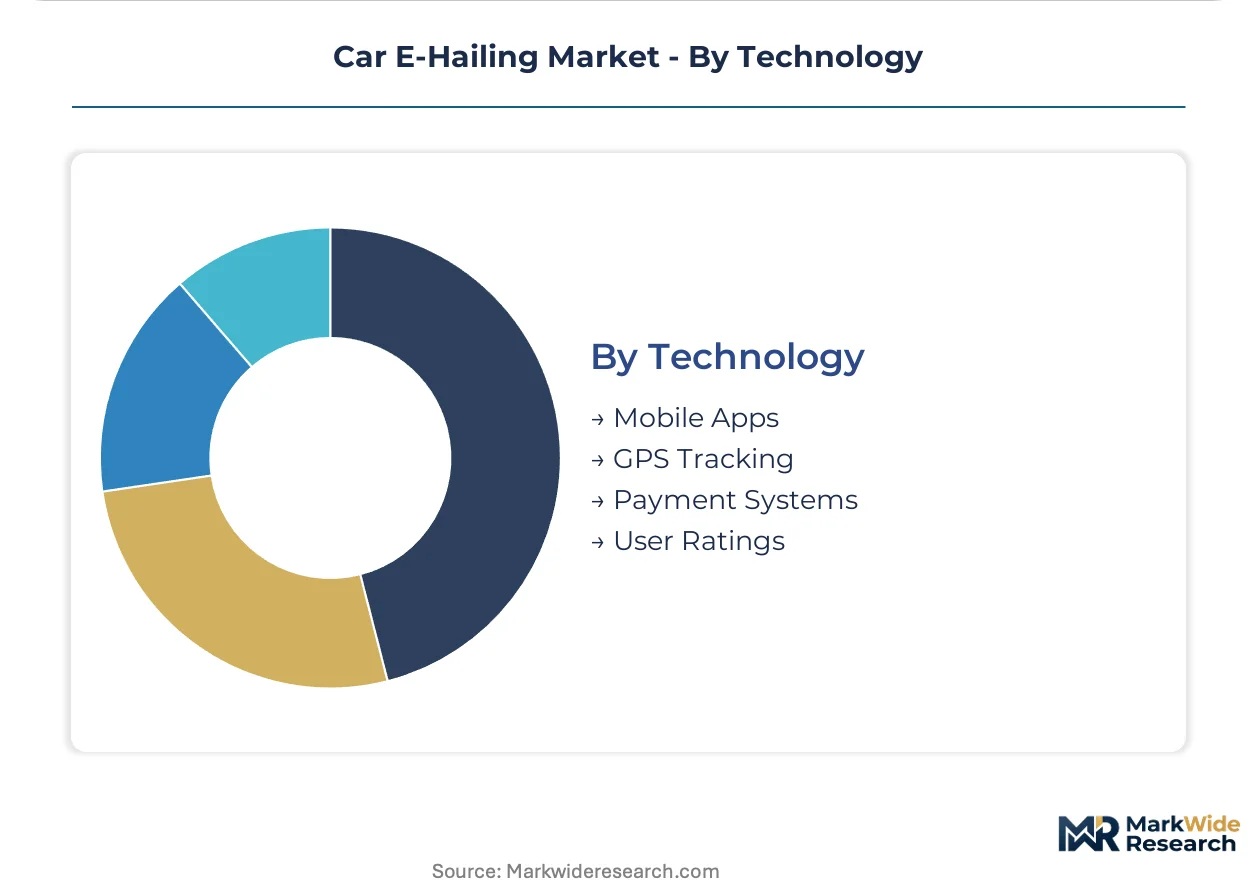
Technology:
Stack architecture determines matching efficiency, fraud exposure, and regulatory compliance burden.
- Mobile Apps:Consumer-facing interfaces for trip origination, fare estimation, and driver-rider communication. The EU AI Act's risk classification framework imposes documentation and human oversight obligations on automated dispatch systems.
- GPS Tracking:Real-time positioning infrastructure for route optimization, estimated arrival calculation, and safety monitoring. Shenzhen and Taipei operators leverage this foundation for swappable battery station placement.
- Payment Systems:Cashless settlement protocols with fraud detection, driver earnings disbursement, and cross-border currency handling.
- User Ratings:Reputation mechanisms for quality assurance and driver incentive alignment with platform service standards.
Investment concentrates on Mobile Apps; regulatory scrutiny intensifies around Payment Systems as financial licensing requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Bangalore generate the densest trip velocity corridors for app-based mobility platforms. India's tier-one metropolitan clusters sustain sufficient driver density to justify dedicated fleet investments and localized incentive structures.
United States
Corporate travel budgets in New York and San Francisco consolidate ground transportation spend under contracted platform agreements. The US Department of Transportation enforces vehicle eligibility thresholds that shape fleet procurement timelines. Los Angeles operators face California Air Resources Board mandates compressing battery-electric vehicle deployment schedules.
China
Shenzhen and Beijing municipal authorities restrict single-occupancy vehicle access during peak windows, accelerating ride-pooling adoption. The Ministry of Industry and Information Technology governs connected vehicle data protocols for dispatch platforms. Shanghai operators leverage swappable battery stations to minimize vehicle downtime across high-utilization corridors.
Germany
Enterprise procurement teams in Berlin and Munich bundle ride-hail access with transit passes under employer-subsidized mobility budgets. The EU Green Deal and F-Gas Regulation jointly force fleet operators toward electric drivetrains with climate-friendly refrigerants. Hamburg platform operators pilot vehicle-to-grid integration with utility demand-response programs.
India
Middle-class commuters in Delhi-NCR and Hyderabad substitute personal vehicle ownership with predictable mobility consumption. The Ministry of Road Transport and Highways enforces vehicle fitness and driver certification standards that gate platform market access. Bangalore's technology corridor sustains the highest trip frequency density for corporate account structures.
Brazil
São Paulo's expanded metro rail network siphons short-haul demand, forcing platforms toward airport transfer and premium service tiers. The national petroleum regulator's pricing volatility exposes drivers to fuel cost erosion. Rio de Janeiro operators concentrate on event logistics and consolidated billing for entertainment venue contracts.
Car E-Hailing Market Competitive Environment
Premium-margin players sit above commodity-margin players across service tier differentiation and fleet electrification timelines. The vendor base organizes into three distinct tiers: global network aggregators with cross-border payment integration, regional specialists with deep domestic mapping ecosystems, and emerging challengers competing on driver commission structures. Strategic archetypes include algorithmic density builders, regulatory compliance specialists, and asset-light platform licensors. Dominant competitive moves encompass strategic partnerships with charging infrastructure operators and portfolio diversification into adjacent mobility modes.
Among global network aggregators, Uber Technologies Inc. and Didi Chuxing Technology Co. exemplify divergent geographic concentration strategies. ANI Technologies Pvt. Ltd. (Ola) occupies a position as the dominant regional specialist, leveraging localized service tiers and regional language interfaces. These three entities represent the primary competitive archetypes: cross-border platform scale, domestic ecosystem integration, and emerging market localization.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| Didi Chuxing Technology Co. |
| Grab Holdings Inc. |
| ANI Technologies Pvt. Ltd. (Ola) |
| Gojek |
| Bolt Technology OÜ |
| Careem |
| Gett |
| Others |
Value Chain & Pricing Dynamics
Corporate mobility procurement teams in Germany and the United Kingdom are consolidating ground transportation spend under single-platform contracts, forcing fleet operators to absorb upfront electrification costs while competing on predictable rate structures. This buyer consolidation compresses margins for non-compliant operators while rewarding those with certified zero-emission fleets and integrated billing infrastructure.
Pricing Analysis
Per-trip transactional pricing with dynamic surge modulation anchors revenue capture, though subscription mobility passes are displacing episodic purchasing in Nordic metropolitan areas. Three-tier pricing structure across premium, standard, and economy levels separates corporate account rates from retail consumer fares and pooled ride-share discounts. Cost compression in the standard tier intensifies because battery-electric vehicle procurement timelines compress under EU Green Deal mandates. Individual users exhibit highest price elasticity, while enterprise procurement teams prioritize rate predictability over per-trip optimization.
Supply Chain Analysis
Driver recruitment constraints in Indonesia, Brazil, and India's tier-two cities limit fleet expansion velocity for platform operators targeting high-growth corridors. Battery cell production concentrates in China, South Korea, and Japan, while cathode precursor refining draws from Indonesia and the Democratic Republic of Congo. Single-source vulnerability in lithium hydroxide processing creates input cost volatility for electric vehicle procurement. Distribution runs through app-based dispatch algorithms with localized driver incentive calibration rather than asset-heavy vehicle ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for automated dispatch systems creates a compliance moat that favors incumbents with dedicated engineering documentation teams and human oversight protocols.
For Market Incumbents: Extend charging infrastructure partnerships into vehicle-to-grid integration pilots with municipal utilities, securing ancillary revenue streams that offset driver retention economics. Consolidate mapping data advantages through exclusive agreements with domestic navigation providers before interoperability mandates standardize protocols. For New Entrants and Emerging Players: Swappable battery architecture offers a technology-first wedge into high-utilization corridors where incumbent fleets face downtime constraints from conventional charging cycles. Target India's tier-two cities with localized regional language interfaces and production-linked incentive eligibility for domestic battery assembly. Pursue white-label platform licensing to established taxi cooperatives seeking digital transformation without proprietary technology investment. For Investors and Strategic Acquirers: The window for entry favors regional specialists with deep domestic payment ecosystem integration and regulatory compliance certification already secured. Long-term viability hinges on fleet electrification timelines and charging infrastructure density rather than driver headcount scale alone. Watch India's advanced chemistry cell manufacturing capacity buildout as the inflection signal for domestic cost competitiveness in battery-electric fleet deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Density of fast-charging stations determines electric fleet utilization rates in EU emission zones. |
| Vehicle-to-Grid Integration Pilot | Bidirectional charging with Hamburg utilities opens ancillary revenue for idle battery-electric assets. |
| Regional Language Interface Localization | Ola's dominance in India rests on Hindi, Tamil, and Telugu app localization for tier-two expansion. |
| Corporate Mobility Budget Consolidation | Berlin and Munich enterprise procurement teams now bundle ride-hail with transit passes under single contracts. |
| Swappable Battery Station Deployment | Shenzhen operators minimize vehicle downtime through hot-swap architecture decoupled from parking assets. |
Study Parameters
Independent corroboration across fleet operations executives, municipal transport regulators, and corporate mobility procurement managers underwrites the qualitative findings in this analysis. Primary fieldwork encompassed platform engineering directors, charging infrastructure operators, and driver cooperative representatives across India, Germany, and Brazil. Secondary validation drew from EU Green Deal implementation timelines, California Air Resources Board fleet mandates, and India's Ministry of Road Transport certification databases. Bottom-up trip velocity modeling and top-down market sizing triangulate volume estimates across metropolitan corridor clusters.
Rate-of-change decomposition separates volume growth from pricing evolution and fleet mix shifts across the projection horizon. Segmentation dimensions span service tier, customer contract structure, vehicle powertrain architecture, and technology stack configuration. CAGRs derive from corridor-specific trip frequency density, driver supply elasticity, and regulatory compliance cost trajectories. Forecast inputs incorporate battery-electric vehicle total-cost-of-ownership convergence timelines and charging infrastructure deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium-ion cell supply disruption or driver classification litigation rulings. Assumptions reflect current regulatory trajectories for EU F-Gas Regulation, California zero-emission mandates, and India's PLI scheme for advanced chemistry cell manufacturing. A small set of named triggers warrants ongoing watch: battery pack cost deflation velocity, municipal emission zone expansion schedules, and platform work directive implementations in European jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Platform Screen Doors Market