
 Pallet Truck Market | 2026-2036
Pallet Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Truck Market Intelligence
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is rotating competitive dynamics in the pallet truck sector. Jungheinrich AG leverages its captive drive-train production to sustain margin control across European distribution networks. Toyota Industries Corporation anchors its position through vertical integration into core component foundries in Aichi Prefecture. Crown Equipment Corporation differentiates via dense service-station coverage across North American industrial corridors.
A pallet truck is a wheeled material-handling device with hydraulic or electric lift mechanisms designed to raise and transport palletized loads, typically rated between 2,000 and 5,500 pounds capacity, used to move goods across warehouse floors, loading docks, and retail backrooms. Electric pallet trucks are displacing manual variants in high-throughput warehouses where operator fatigue and throughput velocity determine operational economics. The 2 Ton and 3 Ton capacity bands concentrate volume in manufacturing facilities and third-party logistics hubs where standardized European and North American pallet dimensions dominate load profiles. Hydraulic technology retains share in price-sensitive segments, though electric drive systems capture preference in food distribution and pharmaceutical cold-chain operations requiring precise maneuverability.
OSHA enforces powered industrial truck operator certification standards that directly shape training costs and fleet eligibility for electric pallet truck deployments in U.S. facilities. The EU Machinery Directive and CE marking requirements govern load-stability testing and electromagnetic compatibility for equipment sold across member states, while China's GB standards mandate safety interlocks and braking performance thresholds for domestic-market certification. Stakeholders must weigh battery chemistry transitions against regional service infrastructure readiness when configuring fleet procurement strategies.
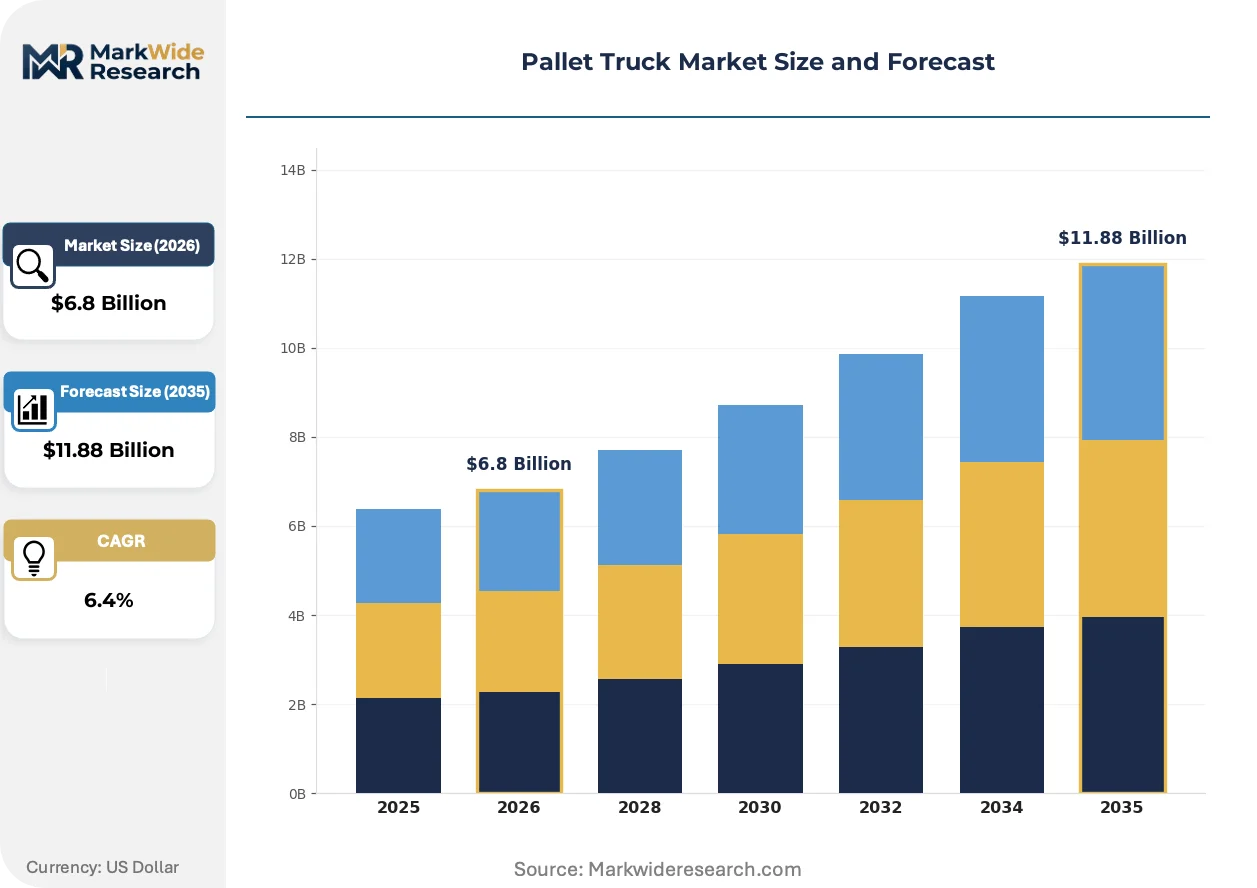
Market Dynamics
The pallet truck sector is experiencing a decisive shift from manual to electric drive systems as warehouse automation economics and operator ergonomics converge to reshape fleet procurement criteria.
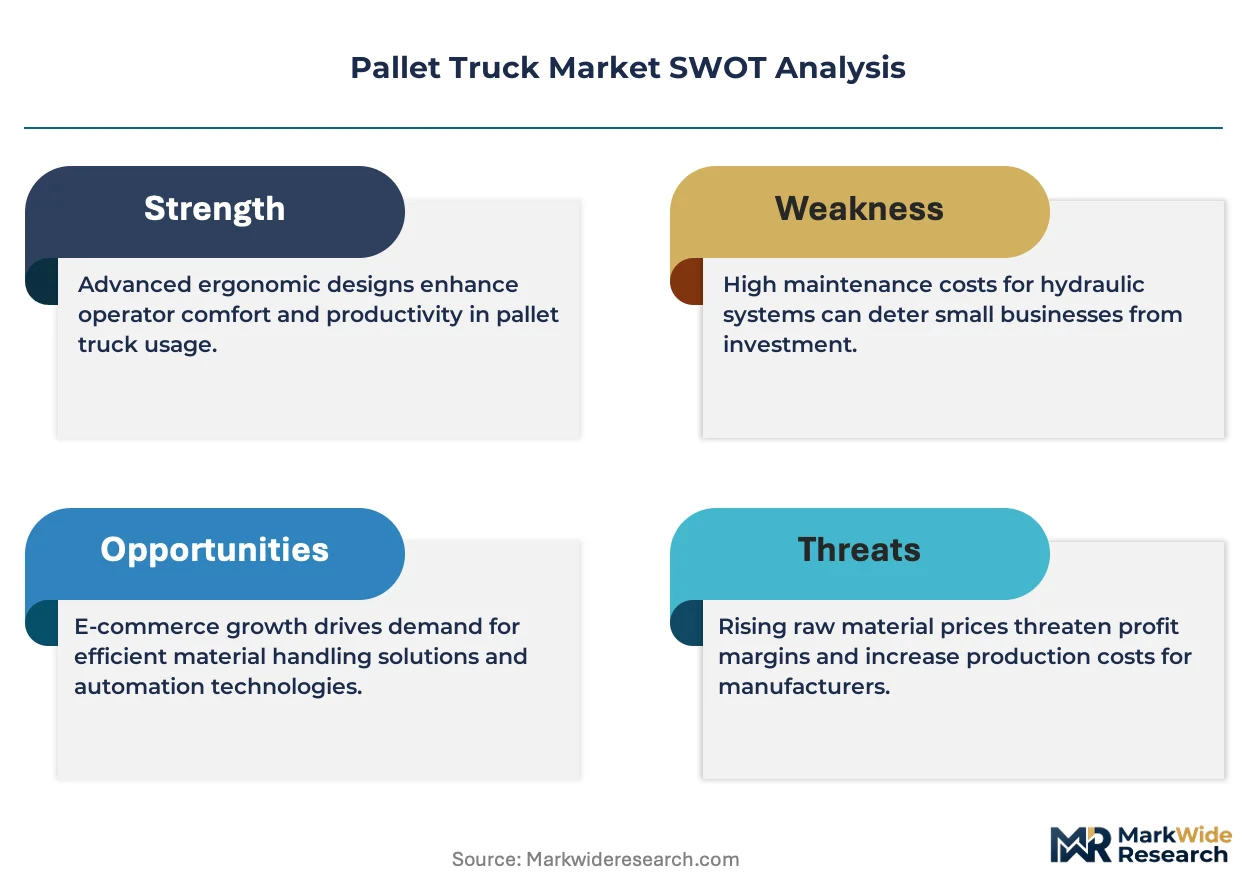
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in Germany and the United States are expanding electric pallet truck fleets to match same-day delivery velocity requirements.
- OSHA ergonomic mandates:Powered industrial truck operator certification standards are accelerating replacement of manual units in high-throughput distribution centers.
- Lithium-ion battery maturation:Cold-chain pharmaceutical facilities are adopting opportunity-charging protocols that eliminate shift-change battery swaps.
Market Restraints
- Drive-train supply concentration:Captive motor and controller production in Aichi Prefecture and Bavaria limits independent assembler access to critical components.
- Steel price volatility:Chassis and mast fabrication costs fluctuate with regional scrap metal and alloy pricing.
- EU Machinery Directive compliance friction:CE marking requirements for electromagnetic compatibility testing extend product launch timelines for non-integrated manufacturers.
Strategic Opportunities
- India warehouse modernization:Organized retail and FMCG distribution infrastructure remains underpenetrated by electric material-handling equipment.
- Battery-as-a-service models:Leasing structures decouple upfront capital from operational expenditure for mid-sized logistics operators.
- GB standards harmonization:China's safety interlock and braking performance thresholds are creating certification pathways for domestic manufacturers to export within Asia-Pacific.
Industry Challenges
- Certified technician scarcity:High-voltage battery maintenance and drive-train diagnostics require specialized training that outpaces vocational program output.
- Legacy fleet integration:Electric unit procurement must accommodate existing warehouse management system protocols and charging infrastructure layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Truck Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pallet Trucks, Electric Pallet Trucks, High Lift Pallet Trucks, Industrial Pallet Trucks End User: Warehouses, Manufacturing Facilities, Retail Stores, Logistics Companies Capacity: 1 Ton, 2 Ton, 3 Ton, 5 Ton Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | Hyster-Yale Materials Handling, Inc., Mitsubishi Logisnext Co., Ltd., Crown Equipment Corporation, EP Equipment, Komatsu Forklift, Jungheinrich AG, Raymond Corporation, Hangcha Group Co., Ltd., Toyota Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Truck Market Strategic Shifts & Innovations
Equipment intelligence and energy architecture are converging to redefine operational value propositions, with connectivity and powertrain chemistry emerging as the primary axes of product differentiation.
Lithium iron phosphate battery chemistry is fragmenting the incumbent lead-acid installed base by enabling partial-state-of-charge operation without memory degradation. Food distribution networks in the Netherlands and cold-storage operators in the United States are adopting these cells for multi-shift continuous operation. The technology is fragmenting traditional battery room infrastructure investments and compressing total cost of ownership calculations toward energy efficiency metrics rather than cycle-life alone.
REACH substance restrictions and the EU F-Gas Regulation are tightening material disclosure requirements for hydraulic fluids and refrigerants used in temperature-controlled transport applications. Manufacturers must now document full chemical composition chains for seals and lubricants to maintain CE marking validity. Pharmaceutical logistics providers in Belgium and Denmark are responding by specifying bio-based hydraulic alternatives and demanding supplier environmental product declarations.
Outcome-based fleet management contracts are displacing traditional equipment purchase and maintenance arrangements among multinational third-party logistics operators. These agreements tie payment to uptime guarantees and throughput metrics rather than asset ownership. The model is most visible in German automotive supplier parks and United States grocery distribution networks where seasonal volume spikes create utilization volatility.
Pallet Truck Market Segmentation
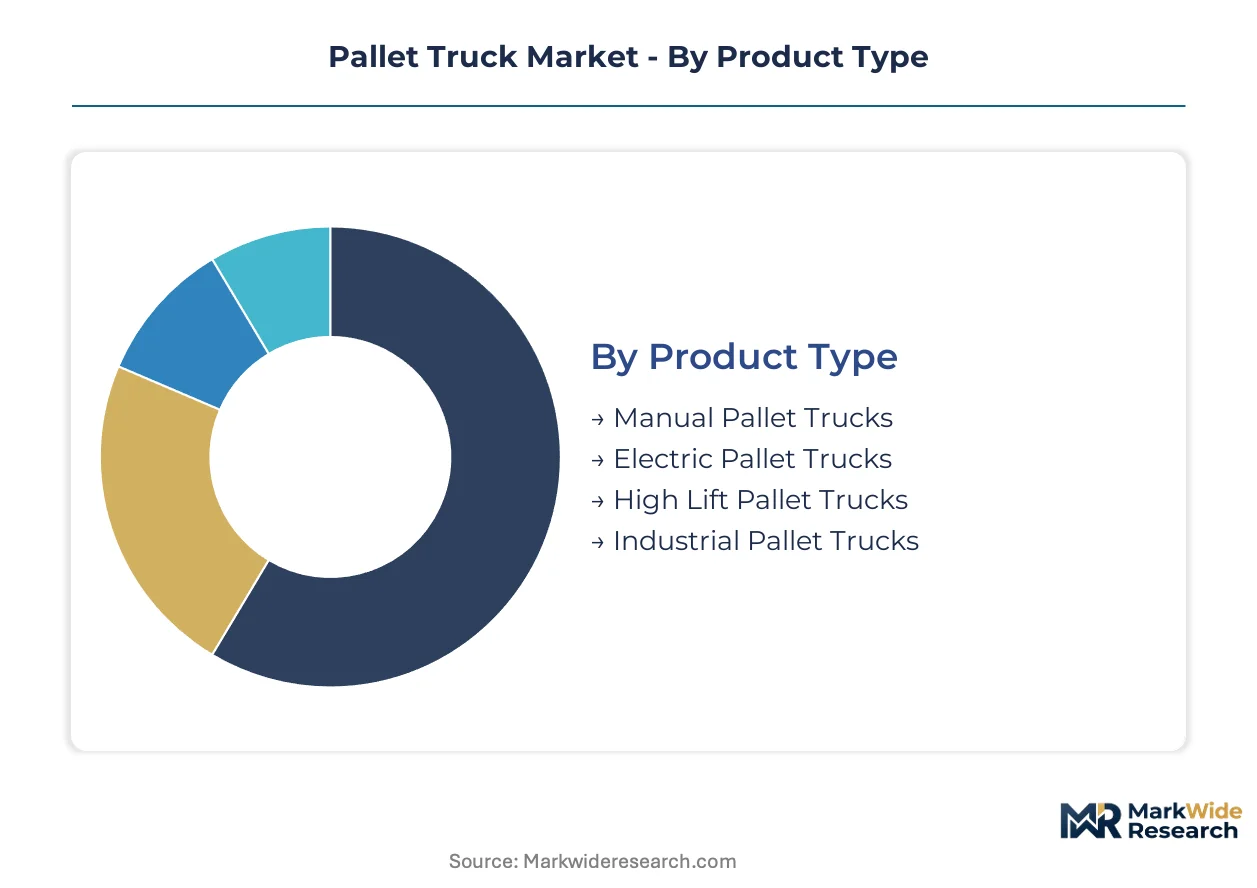
Pallet truck procurement decisions diverge sharply across facility types and load profiles. Equipment specification varies with regulatory environment, shift intensity, and floor surface conditions.
Product Type:
OSHA powered industrial truck certification requirements and EU Machinery Directive load-stability mandates create divergent compliance burdens across drive system categories.
- Manual Pallet Trucks:Hand-pump hydraulic units with single-speed lowering valves and polyurethane steer wheels rated for 2,000-3,000 pound loads. Retail backrooms in the United States and small German machine shops specify these for intermittent use where operator headcount constraints do not justify electric infrastructure investment.
- Electric Pallet Trucks:DC motor-driven walk-behind or ride-on configurations with regenerative braking and programmable acceleration curves. Food distribution centers in the Netherlands and pharmaceutical cold-chain facilities in Denmark are standardizing on lithium-ion variants to eliminate battery swap downtime and satisfy REACH substance documentation requirements for seals and lubricants.
- High Lift Pallet Trucks:Scissor-lift mechanisms enabling ground-level loading to ergonomic working heights up to 31 inches. Assembly operations in Bavarian automotive supplier parks deploy these for line-side kit sequencing.
- Industrial Pallet Trucks:Reinforced chassis designs with forged steel forks and sealed bearing systems for outdoor yard applications. Port logistics operators in Hamburg specify these for container stuffing operations.
Electric Pallet Trucks handles the majority of throughput; High Lift Pallet Trucks is the fastest mover on share.
End User:
Facility automation maturity and labor cost structures rotate equipment specification priorities across customer categories.
- Warehouses:High-bay distribution centers with warehouse management system integration requirements and opportunity-charging infrastructure. Third-party logistics operators in Germany are expanding fleets to match same-day delivery velocity mandates.
- Manufacturing Facilities:Line-side material feeding and work-in-progress transport with just-in-time sequencing constraints. Automotive tier-one suppliers in Aichi Prefecture specify electric units with programmable travel speeds for pedestrian safety zones.
- Retail Stores:Limited aisle widths and noise restrictions favor compact manual units or low-speed electric variants. Big-box operators in the United States backrooms prioritize maneuverability over throughput.
- Logistics Companies:Asset utilization volatility and seasonal volume spikes drive preference for outcome-based fleet management contracts with uptime guarantees. Multinational operators in Belgian pharmaceutical distribution networks are adopting these arrangements.
Warehouses concentrates the installed base; Logistics Companies is expanding most quickly as contract structures evolve.
Capacity:
Standardized pallet dimensions and regional load regulations anchor procurement decisions in specific tonnage bands.
- 1 Ton:Light-duty applications in retail and light manufacturing where European EUR-pallet or North American half-pallet dimensions dominate. Single-shift operations with minimal stacking height requirements.
- 2 Ton:The workhorse specification for general warehousing and manufacturing, matching the standard 48x40 inch North American pallet and 1200x800mm European pallet at full rated load. Distribution centers in Chicago and Frankfurt standardize here.
- 3 Ton:Heavy manufacturing and inbound raw materials handling where steel coils, paper rolls, or bulk containers exceed standard pallet weights. Foundries in the United States Rust Belt and Chinese steel processing facilities specify this band.
- 5 Ton:Specialized industrial applications with custom fork lengths and reinforced masts for machinery movement and container handling. Port terminals in Rotterdam deploy these for breakbulk cargo.
2 Ton carries the volume concentration; 3 Ton is climbing the fastest as manufacturing reshoring intensifies material density requirements.
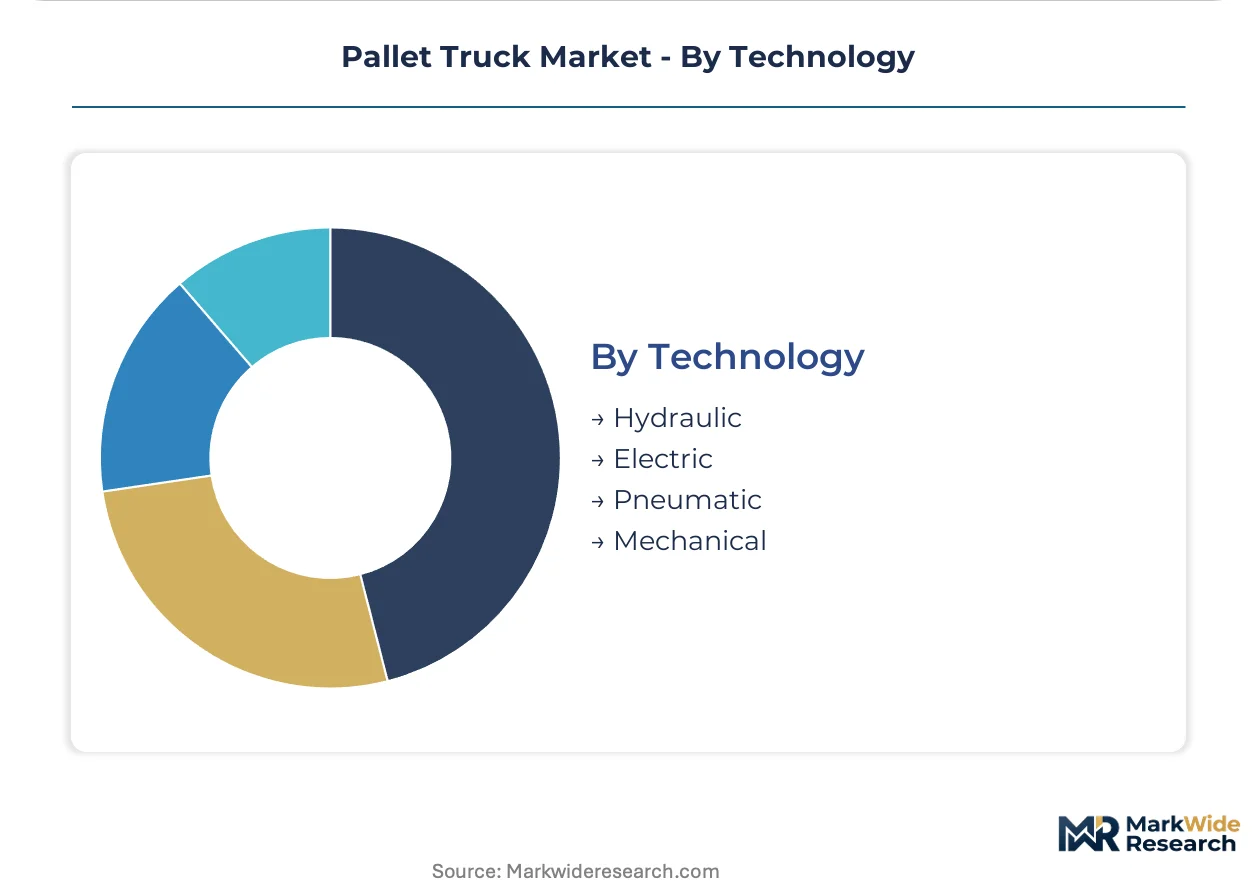
Technology:
Energy architecture and maintenance infrastructure availability determine technology selection across facility types.
- Hydraulic:Manual pump or engine-driven systems with mineral oil-based fluids subject to REACH disclosure requirements. Price-sensitive segments and outdoor applications with limited electrical infrastructure.
- Electric:AC or DC motor systems with lithium iron phosphate or lead-acid battery chemistry. Cold-chain pharmaceutical facilities in the United States are adopting opportunity-charging protocols that eliminate battery room investments.
- Pneumatic:Compressed air-powered units for explosion-risk environments where spark containment is mandatory. Chemical processing plants in Belgium specify these for solvent storage areas.
- Mechanical:Ratchet or screw mechanisms for precision height adjustment in assembly applications. Aerospace component handling in Toulouse supplier facilities.
Electric dominates new procurement; Pneumatic is gaining share fastest in regulated hazardous environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in material-handling equipment are tilting toward net surplus in manufacturing-intensive economies while import-dependent markets absorb fleet modernization debt. Germany and China maintain structural export advantages through captive component ecosystems. The United States runs persistent deficits in electric drive systems despite domestic assembly capacity.
United States
Third-party logistics operators in Chicago and Dallas are expanding electric pallet truck fleets to match same-day delivery velocity mandates from e-commerce platforms. OSHA enforces powered industrial truck operator certification standards that shape training costs and fleet eligibility. Distribution corridors in Pennsylvania and Ohio concentrate procurement for automotive tier-one suppliers.
Germany
Automotive supplier parks in Bavaria and Baden-Württemberg deploy high-lift pallet trucks for line-side kit sequencing with just-in-time constraints. The EU Machinery Directive governs load-stability testing and electromagnetic compatibility for CE marking validity. Hamburg port logistics operators specify industrial-grade units for container stuffing operations in breakbulk terminals.
China
Steel processing facilities in Hebei and Jiangsu provinces are driving 3-ton capacity demand as manufacturing reshoring intensifies material density requirements. GB standards mandate safety interlocks and braking performance thresholds for domestic-market certification. Yangtze River Delta warehouse clusters are standardizing on lithium-ion variants for multi-shift continuous operation.
Japan
Automotive tier-one suppliers in Aichi Prefecture specify electric units with programmable travel speeds for pedestrian safety zones in assembly plants. METI industrial policy supports battery chemistry transitions through subsidy frameworks for logistics equipment modernization. Osaka-Kobe port complexes maintain specialized fleets for machinery movement in container terminals.
India
Organized retail and FMCG distribution infrastructure in Maharashtra and Karnataka remains underpenetrated by electric material-handling equipment relative to manual alternatives. BIS certification requirements for industrial equipment are harmonizing with regional export standards. Delhi-NCR logistics hubs are piloting battery-as-a-service leasing structures to decouple upfront capital from operational expenditure.
Pallet Truck Market Key Industry Players
Concentration sits with integrated manufacturers possessing captive drive-train production and foundry access. The vendor base stratifies into three tiers: global scale players with full vertical control, regional specialists leveraging component outsourcing, and price-focused assemblers dependent on commodity motors. Strategic moves center on backward integration into battery cell supply and geographic expansion through distribution partnerships rather than greenfield manufacturing.
Among Japanese industrial conglomerates, Toyota Industries Corporation and Mitsubishi Logisnext Co., Ltd. exemplify the integrated archetype through upstream control over core component production. Jungheinrich AG represents the European specialist model with dense service-station coverage across industrial corridors. Hangcha Group Co., Ltd. anchors the Chinese scale-driven tier, while Hyster-Yale Materials Handling, Inc. occupies a position bridging North American assembly with global sourcing networks.
| Leading Market Players |
|---|
| Hyster-Yale Materials Handling, Inc. |
| Mitsubishi Logisnext Co., Ltd. |
| Crown Equipment Corporation |
| EP Equipment |
| Komatsu Forklift |
| Jungheinrich AG |
| Raymond Corporation |
| Hangcha Group Co., Ltd. |
| Toyota Industries Corporation |
| Others |
Cost & Logistics Intelligence
Foundry utilization rates in Aichi Prefecture and Bavaria shape both component availability floors and price discipline across electric pallet truck tiers. Scale concentration in captive drive-train production limits independent assembler bargaining power while anchoring premium pricing for integrated manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across premium, standard, and economy tiers differentiated by certification grade and after-sales service bundling. Cost compression in the standard tier intensifies as Chinese assemblers expand lithium-ion variant output. Third-party logistics operators demonstrate highest price sensitivity due to asset utilization volatility, while pharmaceutical cold-chain facilities prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes strain inbound logistics costs for motor and controller shipments from Chinese foundries. Supply concentrates in China, Germany, and Japan for drive-train components, steel chassis fabrication, and battery cell production. The chain rests on lithium carbonate, high-grade steel alloys, and semiconductor controllers, with tariff exposure on Chinese battery imports representing the dominant structural risk. Distribution runs through manufacturer-direct service stations and regional equipment dealers with aftermarket parts stocking obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for high-voltage battery maintenance and drive-train diagnostics constrains fleet expansion velocity regardless of capital availability. The gap between vocational program output and warehouse automation demand defines competitive mobility in this sector.
For Market Incumbents: Compound service-station density in German automotive corridors and United States distribution hubs to capture aftermarket revenue streams. Deepen backward integration into lithium iron phosphate cell supply through joint ventures with Chinese chemical processors. Defend against emerging battery-as-a-service entrants by embedding telemetry-enabled uptime guarantees into standard contract terms.
For New Entrants and Emerging Players: Aftermarket software layers for fleet telemetry and predictive maintenance represent the most penetrable white-space where incumbents under-serve mid-sized logistics operators. Target Indian organized retail and FMCG distribution infrastructure with leasing structures that decouple upfront capital from operational expenditure. Enter through battery-as-a-service partnerships with regional banks to circumvent captive finance advantages held by integrated manufacturers.
For Investors and Strategic Acquirers: Regional specialists with dense service coverage and foundry access in Eastern Europe or Southeast Asia offer the strongest acquisition target archetype for portfolio assembly. Long-term viability hinges on backward integration depth rather than assembly scale alone. Watch lithium carbonate price volatility as the primary inflection indicator for margin compression risk across the value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium iron phosphate production insulates margins from commodity volatility in Chinese chemical markets. |
| Telemetry-Enabled Fleet Management Platform | Outcome-based contracts with uptime guarantees displace traditional purchase arrangements in German automotive supplier parks. |
| Regional Service Station Expansion | Dense coverage across North American industrial corridors differentiates Crown Equipment Corporation from assembly-dependent competitors. |
| Battery-as-a-Service Leasing Structure | Capital decoupling models unlock Indian organized retail penetration where upfront electric fleet investment remains prohibitive. |
| GB Standards Harmonization for Export Certification | Chinese safety interlock compliance creates pathway for domestic manufacturers to capture Asia-Pacific market share. |
Research Approach
A spread of perspectives from warehouse operations directors, OEM procurement teams, aftermarket service heads, and fleet management software vendors converged on the working assumptions. Primary interviews with maintenance technicians and plant engineers in Aichi Prefecture, Bavaria, and Chicago distribution corridors combined with secondary validation from OSHA enforcement data, EU Machinery Directive filings, customs trade records, and SEC equipment manufacturer disclosures. Bottom-up unit economics triangulated against top-down regional fleet penetration estimates.
Segmentation dimensions modeled span product type, capacity band, end-use facility, battery chemistry, and regional regulatory cluster across the projection horizon. CAGRs derived from installed base turnover rates, e-commerce fulfillment center buildout pipelines, and lithium-ion substitution curves. Forecast inputs incorporate shift-intensity metrics from third-party logistics operators and cold-chain pharmaceutical facility expansion plans.
Forecasts assume regulatory continuity in OSHA certification standards, EU Machinery Directive CE marking requirements, and China's GB safety interlock mandates; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as battery chemistry transitions and regional service infrastructure readiness evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Material Handling Integration Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Heavy Equipment Movers Market