
 Telepresence Robotics Market | 2026-2036
Telepresence Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Telepresence Robotics Market Analysis
Subscription-based software layers for remote fleet management is rebalancing vendor economics toward recurring revenue. OhmniLabs leverages cloud-native architecture to sustain margin expansion across education deployments. Suitable Technologies anchors its position through premium channel control in corporate settings. Double Robotics differentiates via manufacturing scale in mobile form factors.
Telepresence robotics encompasses wheeled and stationary platforms integrating audiovisual streaming, autonomous navigation, and bidirectional control interfaces for remote human presence. These systems typically operate on lithium-ion powertrains with 8-12 hour duty cycles and HD camera arrays exceeding 1080p resolution, serving industrial inspection and distributed workforce coordination. Mobile robots lead hardware shipments while AI Integration commands the fastest expansion in value terms due to embedded obstacle-avoidance and natural-language processing modules. Healthcare applications concentrate margin pools where Remote Consultation commands premium pricing against standardized Telecommuting deployments.
The FDA classifies clinical telepresence systems under medical device pathways, while the EU AI Act imposes conformity obligations on autonomous navigation algorithms. FCC Part 15 governs wireless transmission protocols for US-deployed units, directly affecting product certification timelines and market access costs. Stakeholders must monitor evolving liability frameworks as autonomous mobility features expand beyond controlled environments into public spaces.
Market Dynamics
Subscription software layers for remote fleet management are restructuring vendor economics toward recurring revenue streams, decoupling hardware margins from long-term profitability.
Growth Catalysts
- EU AI Act Conformity Pathways:The EU AI Act's risk-based classification creates clear certification roadmaps for autonomous navigation algorithms, reducing regulatory uncertainty for vendors targeting European healthcare and industrial buyers.
- Healthcare Remote Consultation:Clinical telepresence systems command premium pricing against standardized telecommuting deployments, with hospitals in Germany's industrial automation corridor driving concentrated demand for FDA-cleared units.
- Lithium-Ion Powertrain Density:Advances in battery chemistry extend duty cycles toward 12-hour continuous operation, enabling full-shift coverage in manufacturing inspection workflows without mid-cycle docking.
Market Restraints
- FCC Part 15 Certification Timelines:Wireless transmission protocol approvals for US-deployed units extend product launch cycles by 6-9 months, elevating market access costs for smaller hardware vendors.
- Camera Array Component Concentration:HD optics supply concentrates among Japanese and South Korean sensor manufacturers, creating input cost volatility for platforms requiring 1080p+ resolution minimums.
- Autonomous Navigation Liability Gaps:Evolving tort frameworks in public space deployment lag technical capability expansion, chilling insurer appetite for commercial policies covering uncontrolled environment operation.
Strategic Opportunities
- Underpenetrated Education Vertical:K-12 and university deployments remain below saturation in North American districts, with cloud-native architecture enabling rapid scaling without on-premise infrastructure investment.
- Natural-Language Processing Convergence:Integration of bidirectional voice interfaces with large language models enables real-time translation and accessibility features, opening public sector procurement channels previously closed to English-only systems.
- India PLI Scheme for Robotics:India's production-linked incentive scheme for advanced manufacturing offers 10-year tax holidays for domestic assembly, creating a low-cost export hub for Asia-Pacific distribution.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of firmware engineers with real-time operating system expertise constrains product development velocity for mid-cap vendors competing against well-capitalized robotics divisions.
- ISO 13482 Compliance Burden:Personal care robot safety standard certification requires extensive documentation of hazard analysis and risk mitigation, extending time-to-revenue for healthcare-focused product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telepresence Robotics Market |
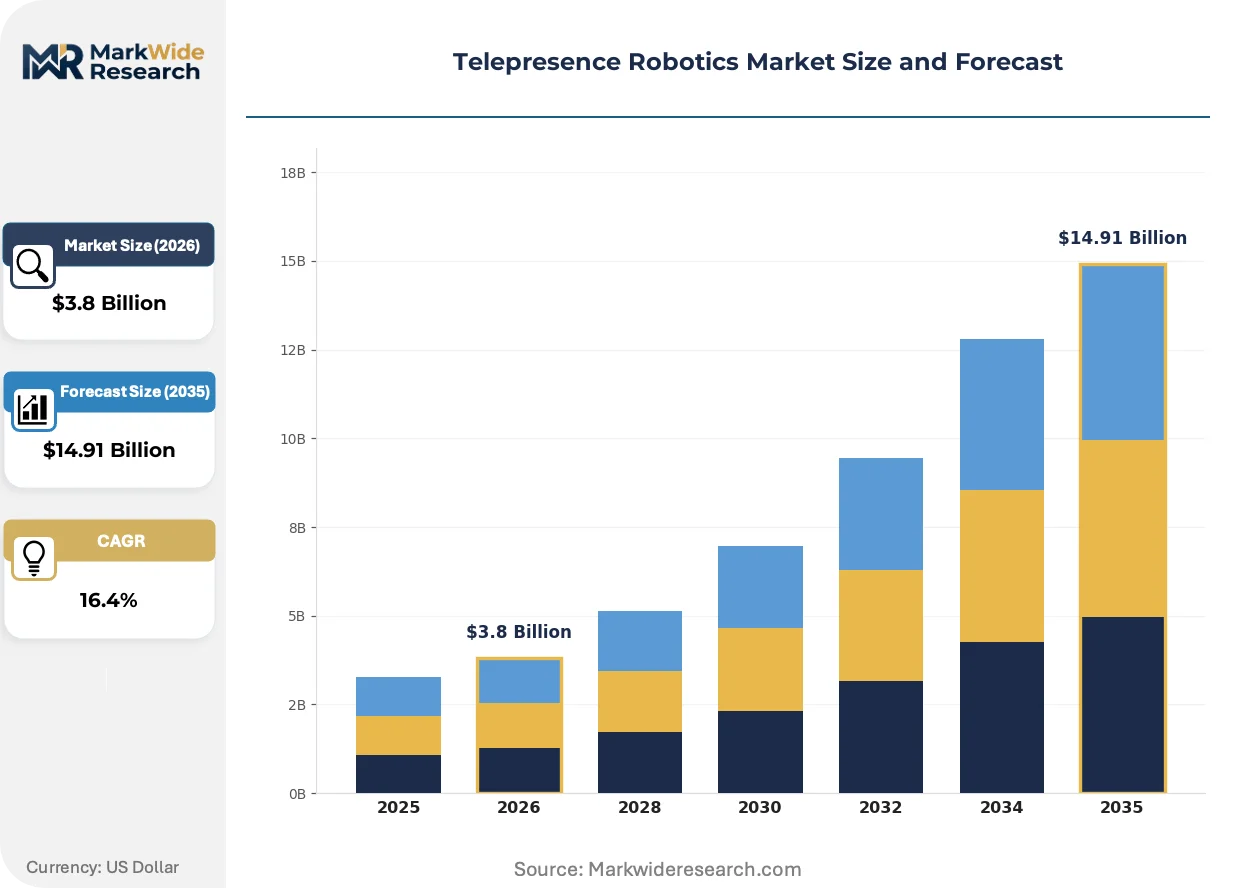
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Fixed Robots, Telepresence Systems, Robotics Platforms Technology: Virtual Reality, Augmented Reality, 5G Communication, AI Integration Industry Vertical: Healthcare, Education, Corporate, Manufacturing Application: Remote Consultation, Virtual Tours, Telecommuting, Training |
| Companies Covered | Double Robotics, Inbot Technology, Suitable Technologies, Mantaro Networks, VGo Communications, OhmniLabs, Anybots, Xandex, AXYN Robotique, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telepresence Robotics Market Emerging Trajectories
Telepresence robotics is experiencing convergence between hardware commoditization and software differentiation, with value capture migrating toward intelligence layers and fleet orchestration capabilities.
Cloud-native fleet management platforms are overtaking on-premise control systems as the dominant deployment architecture. Manufacturing and logistics buyers in Germany and the US Midwest adopt these systems to coordinate distributed inspection teams across multiple facilities. This shift compresses hardware margin pools while expanding recurring revenue attachment rates for software vendors.
The EU AI Act's conformity assessment requirements for high-risk AI systems reshape product development priorities for autonomous navigation features. Vendors must document algorithmic transparency and human oversight mechanisms before CE marking. Healthcare applications face the steepest compliance burden, with notified body involvement extending certification timelines relative to corporate telecommuting segments.
Buyer preference for outcome-based engagement models disrupts traditional capital expenditure procurement in enterprise segments. Fortune 500 facilities management departments now contract for "presence-as-a-service" rather than purchasing hardware outright. This pattern concentrates most visibly in US technology and financial services verticals, where balance sheet efficiency priorities override ownership preferences.
Telepresence Robotics Market Segmentation
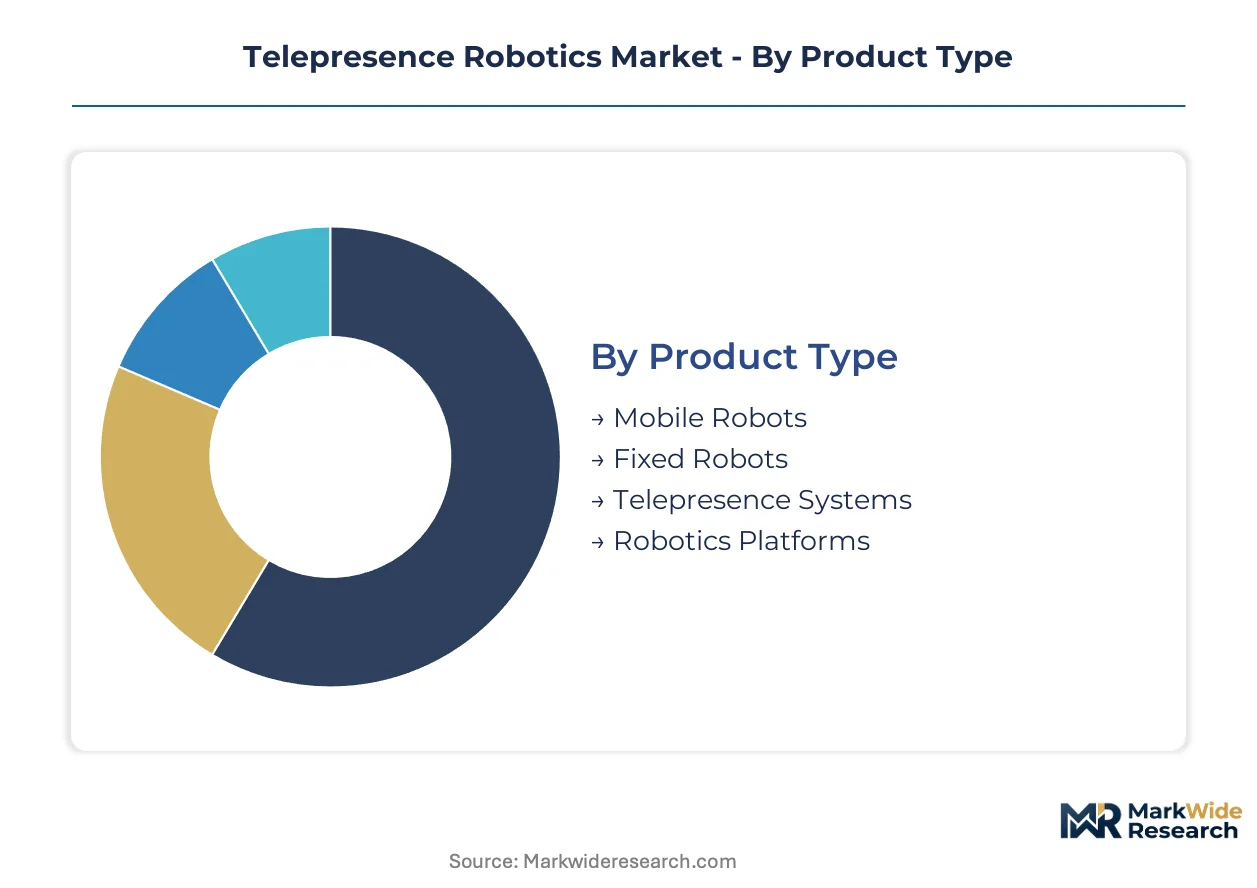
Telepresence robotics segmentation reveals distinct margin profiles across hardware form factors and intelligence layers. Buyers prioritize autonomous mobility in industrial settings while healthcare procurement emphasizes FDA-compliant audiovisual fidelity.
Product Type:
Deployment environment dictates chassis selection, with floor mobility requirements separating premium configurations from stationary installations.
- Mobile Robots:Wheeled platforms integrate lithium-ion powertrains delivering 8-12 hour duty cycles and HD camera arrays exceeding 1080p resolution. Manufacturing inspection workflows in Germany's industrial automation corridor drive concentrated procurement for units with autonomous navigation capabilities.
- Fixed Robots:Stationary mounts prioritize camera stability and audio clarity over locomotion, serving permanent installation environments. Healthcare systems in the United States deploy these for remote patient consultation where FDA medical device pathways govern certification.
- Telepresence Systems:Integrated hardware-software bundles emphasizing plug-and-operation for non-technical users.
- Robotics Platforms:Modular architectures enabling custom sensor and compute configurations for specialized deployments.
Volume sits with Mobile Robots; growth tilts toward AI-enhanced Robotics Platforms.
Technology:
Intelligence layer selection determines recurring revenue potential and regulatory compliance burden for vendors.
- AI Integration:Embedded obstacle-avoidance and natural-language processing modules command premium pricing against baseline configurations. EU AI Act conformity obligations extend certification timelines for autonomous navigation algorithms targeting European healthcare buyers.
- 5G Communication:Low-latency wireless transmission protocols enable real-time bidirectional control in bandwidth-constrained environments. FCC Part 15 certification requirements for US-deployed units elevate market access costs.
- Virtual Reality:Immersive headset interfaces for operator presence simulation in training applications.
- Augmented Reality:Overlay visualization tools for remote guidance and maintenance instruction delivery.
Deployment scale favors 5G Communication; value expansion concentrates in AI Integration.
Industry Vertical:
End-use sector selection directly maps to procurement budget cycles and compliance stringency.
- Healthcare:Clinical telepresence systems command premium pricing against standardized corporate deployments. FDA classification under medical device pathways and EU AI Act high-risk system obligations create dual-jurisdiction compliance complexity.
- Corporate:Fortune 500 facilities management departments favor outcome-based engagement models over capital expenditure procurement. Balance sheet efficiency priorities in US technology and financial services verticals accelerate presence-as-a-service adoption.
- Education:K-12 and university deployments remain below saturation in North American districts.
- Manufacturing:Distributed inspection teams across multiple facilities drive fleet management software attachment.
Revenue concentration rests with Healthcare; Education presents the steepest expansion trajectory.
Application:
Use case specificity determines hardware specification minimums and software integration depth.
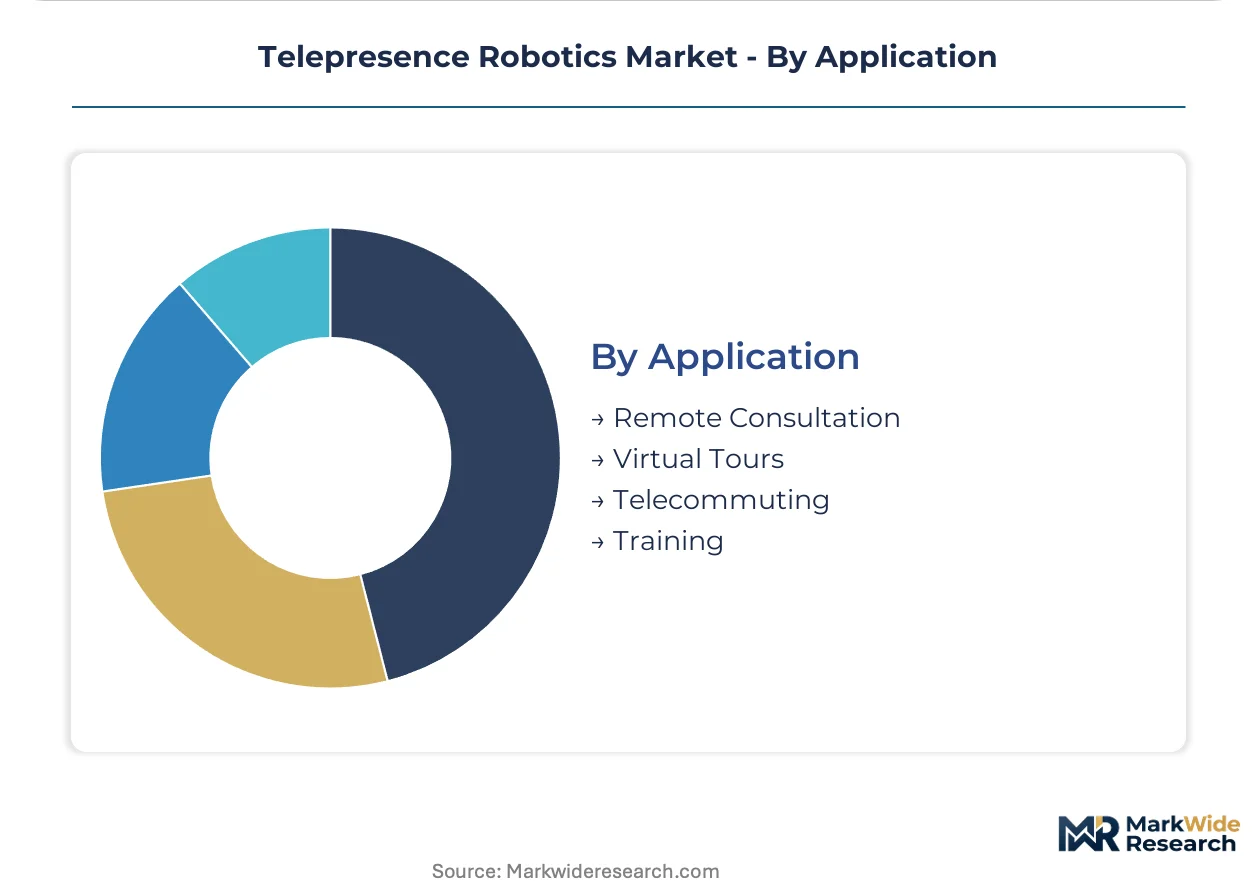
- Remote Consultation:Clinical-grade audiovisual fidelity with HIPAA-compliant data handling for patient-facing interactions. German hospitals driving demand for FDA-cleared units establish the reference specification for premium tier positioning.
- Telecommuting:Standardized feature sets prioritize cost efficiency over specialized certifications. Corporate settings anchor volume shipments with shorter replacement cycles than healthcare installations.
- Virtual Tours:Wide-angle optics and spatial audio for immersive environment navigation.
- Training:Recording and playback capabilities for competency verification and remote instruction.
Margin pools concentrate in Remote Consultation; Telecommuting sustains baseline volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in East Asian electronics hubs, while demand absorption tilts toward European healthcare systems and North American enterprise buyers. Germany's industrial automation corridor anchors European procurement volume. The United States drives software-centric deployment models.
Germany
Automotive and pharmaceutical manufacturers deploy mobile telepresence units for distributed quality inspection across Bavaria and Baden-Württemberg production networks. The EU AI Act's high-risk system classification imposes conformity assessment obligations on autonomous navigation algorithms targeting healthcare buyers. Stuttgart's industrial robotics cluster hosts integration facilities serving hospital systems in North Rhine-Westphalia.
United States
Fortune 500 technology and financial services verticals contract for presence-as-a-service rather than hardware ownership, compressing capital expenditure cycles. FDA medical device pathways govern clinical telepresence certification, extending timelines for patient-facing systems. The San Francisco Bay Area and Boston corridor concentrate vendor development activity alongside healthcare pilot deployments.
China
Domestic electronics assembly and semiconductor fabrication drive fleet management software attachment for multi-facility coordination. MIIT standards for service robot safety intersect with GB certification requirements for wireless transmission modules. The Yangtze River Delta manufacturing belt generates concentrated demand for lithium-ion powered mobile platforms with extended duty cycles.
Japan
Aging demographics accelerate remote consultation adoption in rural healthcare networks facing physician shortages. METI robotics industry roadmaps prioritize human-machine interface standardization for telepresence applications. The Nagoya industrial corridor integrates telepresence systems into automotive supply chain quality assurance workflows.
India
IT services exporters and multinational back-office operations pilot telepresence for distributed team coordination across Bangalore and Hyderabad tech parks. The PLI scheme for advanced manufacturing offers ten-year tax holidays for domestic robotics assembly, positioning the country as an export hub. Delhi-NCR hospital networks evaluate FDA-cleared units for specialist consultation reach extension.
Telepresence Robotics Market Vendor Landscape
Top-tier vendors anchor premium healthcare and enterprise segments, while mid-cap specialists compete on manufacturing scale and cloud-native architecture. The vendor base arranges across three functional tiers: FDA-cleared medical device suppliers, corporate telecommuting platform providers, and modular hardware fabricators serving vertical integrators. Strategic archetypes include subscription-first software vendors, premium channel controllers, and battery/powertrain optimization specialists. Competitive moves concentrate on M&A for navigation algorithm capabilities and strategic partnerships with 5G infrastructure providers.
Within the cloud-native tier, OhmniLabs and Suitable Technologies exemplify divergent positioning strategies. OhmniLabs occupies a position among architecture-first vendors emphasizing recurring revenue attachment, while Suitable Technologies anchors the premium channel control archetype through corporate deployment specialization. Double Robotics represents the manufacturing scale archetype, with its name signaling mobile form factor concentration. These three entities collectively illustrate how vendor economics restructure around software differentiation rather than hardware shipment volume alone.
| Leading Market Players |
|---|
| Double Robotics |
| Inbot Technology |
| Suitable Technologies |
| Mantaro Networks |
| VGo Communications |
| OhmniLabs |
| Anybots |
| Xandex |
| AXYN Robotique |
| Others |
Supply Flow & Price Mechanics
FDA-cleared medical device procurement in US hospital systems demands specialized component sourcing that compresses margin pools for non-certified suppliers. This specification divergence forces vendors to choose between premium certification investment or commodity positioning, segmenting pricing power across compliance tiers.
Pricing Analysis
Cost compression in standard telecommuting tiers reflects manufacturing scale advantages among East Asian fabricators serving volume corporate buyers. Three-tier pricing structure across FDA-cleared medical, enterprise-grade, and basic telepresence levels separates premium remote consultation systems from standardized office deployments. Certification grade and after-sales service bundling drive price differentiation, with healthcare buyers showing lowest price sensitivity due to liability and compliance requirements. Pricing pressure intensifies in education and corporate segments as cloud-native software vendors decouple hardware margins from recurring revenue attachment.
Supply Chain Analysis
Freight cost volatility from East Asian electronics hubs to European and North American assembly points elevates landed costs for lithium-ion powertrains and HD camera modules. Component manufacturing concentrates in China, South Korea, and Japan, with sensor arrays and battery cells drawing from concentrated supplier bases. Raw material dependencies span cobalt and lithium chemistry for powertrains, CMOS sensors for optics, and rare earth elements for motor assemblies. Single-source vulnerability in Japanese and South Korean sensor manufacturers creates input disruption risk. Distribution runs through direct enterprise sales teams for healthcare and Fortune 500 accounts, with education and mid-market corporate segments served through channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems firmware engineering scarcity constrains product development velocity, propping pricing for vendors with captive technical capacity. This talent bottleneck limits supply expansion and sustains margin premiums for established players.
For Market Incumbents: Deploy cloud-native fleet management software layers to deepen recurring revenue attachment and defend against hardware commoditization. Prioritize backward integration into lithium-ion powertrain assembly to reduce dependency on East Asian battery suppliers facing export restriction risk. Reinforce channel control in FDA-cleared healthcare segments where certification timelines create defensive moats against unqualified entrants. For New Entrants and Emerging Players: The EU AI Act in Germany and neighboring healthcare markets opens a window for autonomous navigation algorithm specialists to capture premium positioning before incumbents complete conformity assessments. Target underpenetrated K-12 education districts in North America with simplified hardware-software bundles requiring minimal IT infrastructure. Pursue white-label manufacturing partnerships with India PLI scheme beneficiaries to achieve cost parity for Asia-Pacific price-sensitive procurement. For Investors and Strategic Acquirers: The window for entry favors navigation algorithm and natural-language processing capability specialists with demonstrated CE marking progress. Long-term viability hinges on software differentiation rather than hardware shipment scale, positioning AI integration modules as priority acquisition targets. Watch FDA 510(k) clearance velocity for clinical telepresence systems as the inflection signal distinguishing premium-tier vendors from commodity competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation Algorithm Acquisition | EU AI Act conformity requirements elevate autonomous mobility capabilities as scarce assets for CE marking pathways. |
| Cloud-Native Fleet Platform Launch | OhmniLabs and similar architecture-first vendors demonstrate recurring revenue attachment rates that restructure vendor economics. |
| India PLI Manufacturing Footprint | Ten-year tax holidays for domestic robotics assembly create low-cost export positioning for Asia-Pacific education and corporate segments. |
| 5G Infrastructure Partnership | FCC Part 15 certification alignment with carrier network specifications compresses wireless transmission protocol approval timelines. |
| ISO 13482 Safety Certification | Personal care robot standard documentation satisfies notified body requirements for EU healthcare market access. |
Methodological Framework
SEC filings, EU medical device regulatory databases, and robotics industry association reports formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers at German hospital systems, GPO contracts managers in US healthcare networks, and fleet management software procurement officers at Fortune 500 manufacturers validated demand assumptions and pricing dynamics. Bottom-up shipment estimates by product tier and top-down value analysis by vertical application were triangulated to constrain forecast variance.
Historical trendline analysis of lithium-ion powertrain cost curves, HD camera module pricing, and autonomous navigation software licensing rates informed the projection framework. Segmentation modeling spanned hardware form factor, intelligence layer technology, end-use vertical, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves incorporating EU AI Act implementation timelines and FDA medical device pathway completion rates.
The model assumes a particular technology adoption path; alternative pathways for embedded AI processing at the edge versus cloud-dependent architectures would alter the outlook for bandwidth requirements and hardware specification minimums. Forecasts reflect assumptions about regulatory harmonization progress and battery chemistry advancement that may revise with policy shifts or materials science breakthroughs. Stakeholders should weight assumptions against their own operating context and certification investment capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Asia-Pacific AUV and ROV Market