
 Search and Rescue Robots Market | 2026-2036
Search and Rescue Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Search and Rescue Robots Market Intelligence
Aftermarket service revenue for deployed rescue fleets is reshaping profitability across the value chain. Boston Dynamics sustains technology leadership through advanced locomotion systems for rubble traversal. Kongsberg Maritime dominates underwater search configurations with pressure-rated autonomous platforms. Teledyne FLIR leverages thermal imaging integration to anchor its position in smoke-penetration applications.
Search and rescue robots are mobile robotic systems engineered for deployment in hazardous environments, typically incorporating IP67-rated sealing, multi-spectral sensors, and real-time telemetry links to human operators. These platforms execute reconnaissance, victim location, and supply delivery functions in conditions that compromise human safety. Ground robots lead current procurement volumes across disaster response agencies, while aerial drones represent the fastest-growing category as battery density improvements extend flight endurance for wide-area search patterns. Sensor integration technology captures expanding margin pools as end users prioritize fused data outputs from LIDAR, thermal, and gas detection arrays over single-modality systems.
FAA regulations governing beyond-visual-line-of-sight drone operations shape aerial platform deployment protocols for US emergency responders, while the EU AI Act's risk-based classification imposes conformity requirements on autonomous navigation capabilities sold into European government agencies. ISO 17840 standards for first responder equipment interoperability further constrain product design specifications across export markets. Stakeholders must monitor evolving certification harmonization between FAA and EASA frameworks to anticipate which sensor and communication architectures will unlock cross-border procurement channels.
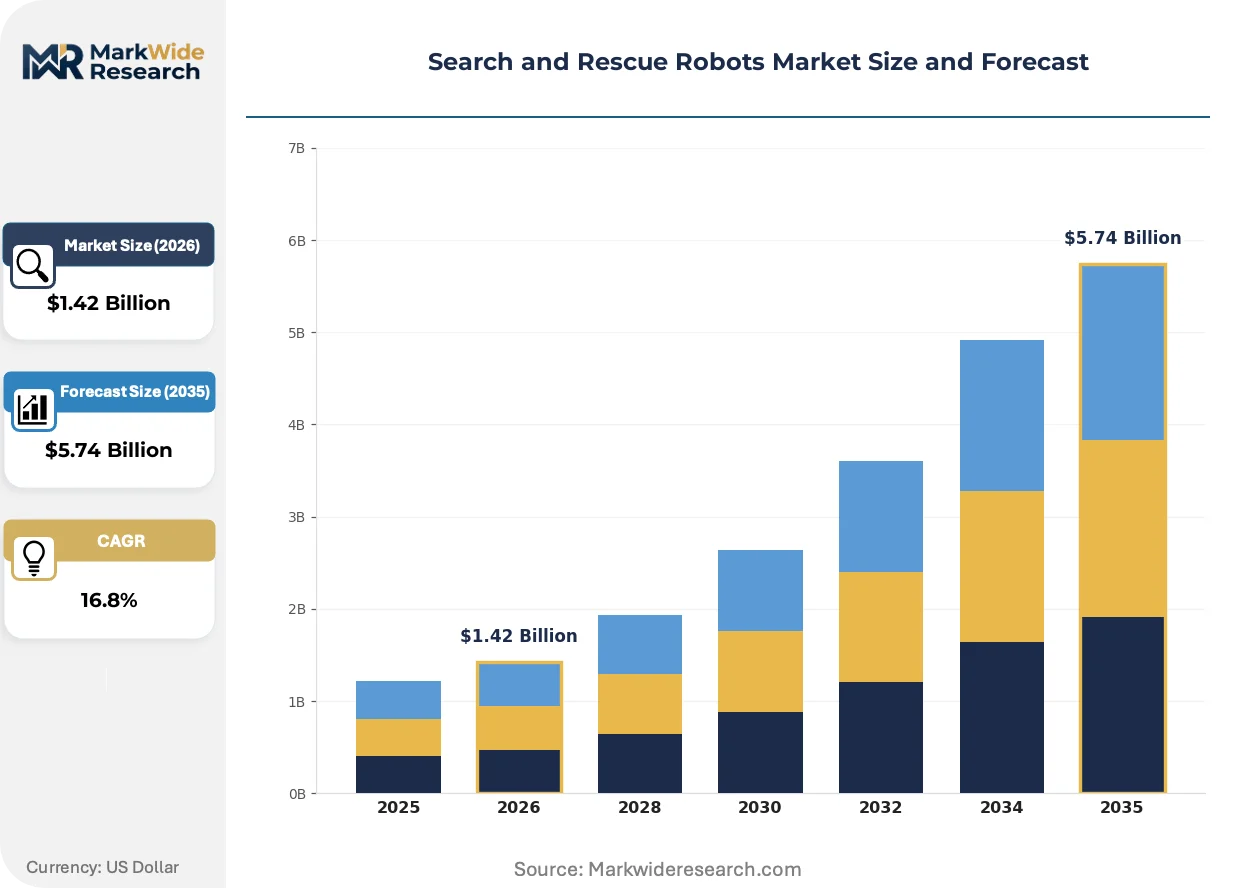
Market Dynamics
The aftermarket service revenue model is restructuring competitive economics across the search and rescue robotics value chain, as deployed fleet maintenance contracts now generate recurring income streams that rival initial hardware sales.
Growth Catalysts
- FAA beyond-visual-line-of-sight rulemaking:The FAA's evolving BVLOS framework for emergency response drones is unlocking expanded aerial search operations for US fire departments and urban search teams.
- Sensor fusion architectures:Multi-spectral integration of LIDAR, thermal imaging, and gas detection arrays is enabling single-platform reconnaissance that previously required multiple specialized units.
- Japan METI disaster resilience funding:Municipal procurement subsidies from Japan's Ministry of Economy, Trade and Industry are accelerating sensor-integrated ground robot deployment across prefectural emergency response networks.
Market Restraints
- Lithium battery supply concentration:Cell production for extended-flight aerial platforms clusters in East Asian manufacturing hubs, exposing procurement timelines to concentrated supply risk.
- EU AI Act conformity costs:The European Union's risk-based classification for autonomous navigation systems imposes certification burdens that extend sales cycles for European government agency contracts.
- IP67 sealing material costs:Specialized elastomers and precision-machined housings for hazardous environment protection consume disproportionate bill-of-materials share versus standard industrial robotics.
Strategic Opportunities
- Underwater platform expansion:Pressure-rated autonomous configurations for maritime search and submarine rescue remain underpenetrated relative to ground and aerial segments, with coastal municipalities representing untapped demand.
- ISO 17840 interoperability compliance:First responder equipment standardization creates specification advantages for vendors architecting cross-compatible communication protocols from initial design stages.
- Swarm coordination algorithms:Convergence of distributed computing and mesh networking is enabling coordinated multi-robot search patterns that compress area coverage timelines for wide-scale disaster zones.
Industry Challenges
- Autonomy software certification timelines:Validation protocols for self-navigation in GPS-denied environments extend development cycles and delay revenue recognition for platform developers.
- Human-robot interface skill gaps:Emergency response agencies face recruitment friction for operators capable of interpreting fused sensor outputs under time-constrained disaster conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Search and Rescue Robots Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Robots, Aerial Drones, Underwater Drones, Hybrid Robots Application: Disaster Response, Military Operations, Building Inspection, Environmental Monitoring Technology: Teleoperation, Autonomous Navigation, Sensor Integration, Communication Systems End User: Government Agencies, NGOs, Military, Private Sectors |
| Companies Covered | Teledyne FLIR, Hydronalix, Boston Dynamics, Saab AB, Thales Group, Lockheed Martin Corporation, Kongsberg Maritime, Howe & Howe Technologies, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Search and Rescue Robots Market Strategic Shifts & Innovations
Real-time telemetry and edge computing architectures are compressing decision timelines for incident commanders, replacing delayed video relay with instantaneous situational awareness.
Multi-spectral sensor fusion is digitizing reconnaissance workflows for structural collapse response teams. Fire departments in Tokyo, Los Angeles, and London are deploying unified LIDAR-thermal-gas detection platforms that stream composite environmental maps directly to command posts. This convergence is digitizing the traditional sequential search process into simultaneous multi-threat assessment.
The EU AI Act's risk classification framework for autonomous systems is mandating conformity assessments that reshape European procurement specifications. Government agencies now require documented safety case submissions for self-navigating platforms, filtering vendor pools toward established certification capabilities. Ground robot categories with limited autonomy face lighter compliance burdens than aerial swarms with independent decision authority.
Aftermarket service unbundling is separating hardware ownership from operational support across municipal procurement. Japanese prefectures pioneered multi-year fleet management contracts that bundle maintenance, software updates, and operator training into subscription structures. This model is displacing capital-intensive purchase patterns in Germany and South Korea, where budget-constrained emergency services prefer predictable operational expenditures.
Search and Rescue Robots Market Segmentation
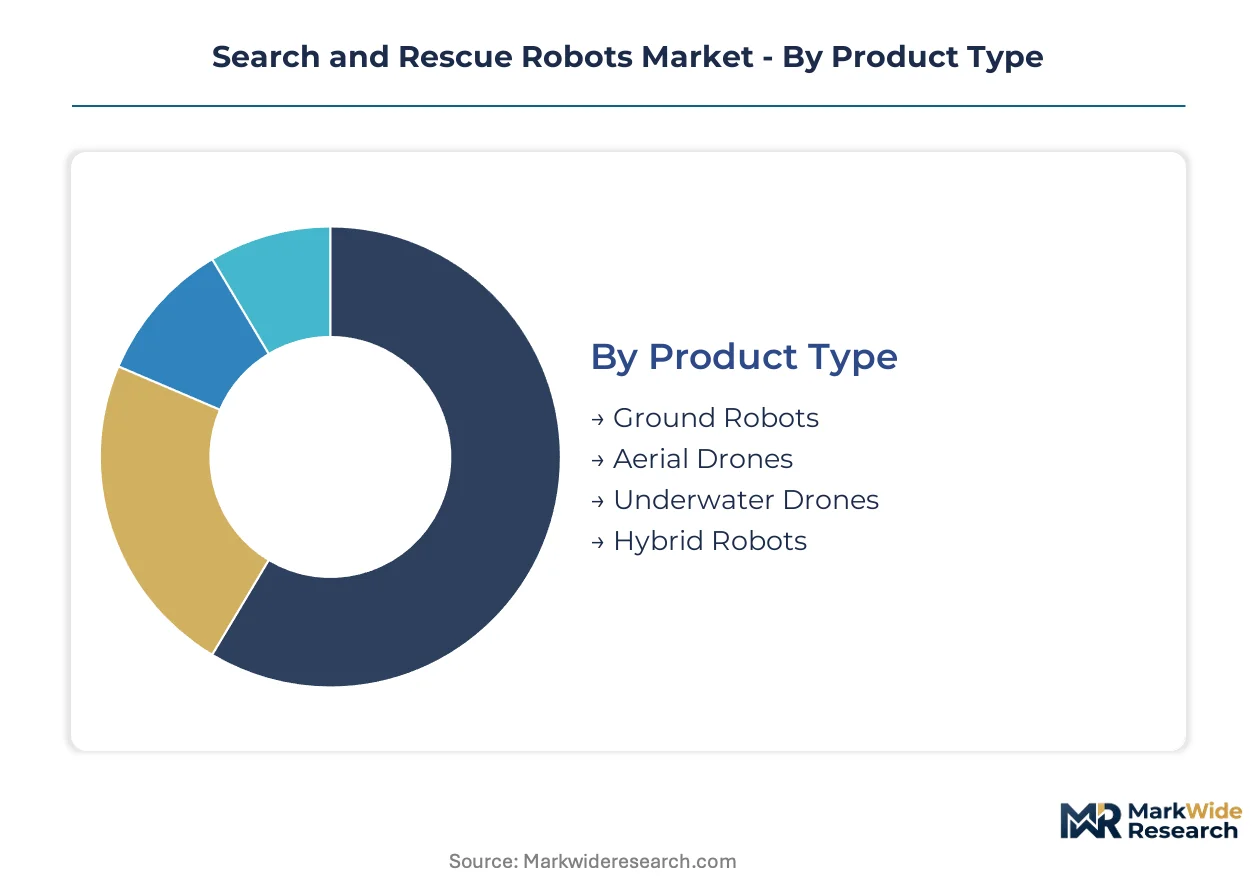
Segmentation in search and rescue robotics reveals divergent service intensity profiles across product architectures. Ground platforms generate recurring calibration and sensor fusion maintenance contracts, while aerial systems concentrate warranty exposure in battery replacement cycles.
Product Type:
After-sales service intensity varies sharply across mobility platforms, with sealed-environment ground units requiring the most intensive field maintenance programs.
- Ground Robots:IP67-sealed locomotion platforms with tracked or legged configurations dominate municipal procurement in Japan and Germany. Fire departments in Tokyo and Los Angeles deploy these units for structural collapse reconnaissance, where elastomer seal replacement and actuator calibration drive multi-year service contracts.
- Aerial Drones:Battery-powered rotary-wing and fixed-wing configurations extend search coverage through BVLOS-certified operations. FAA rulemaking for emergency response flights is unlocking expanded deployment for US urban search teams, though lithium cell supply concentration in East Asian hubs creates procurement vulnerability.
- Underwater Drones:Pressure-rated autonomous platforms from Kongsberg Maritime and Teledyne FLIR serve maritime search and submarine rescue missions.
- Hybrid Robots:Amphibious and multi-domain platforms combine aerial deployment with ground mobility for flood response scenarios.
Ground robots hold the largest share; momentum sits with aerial drones.
Application:
Cost tier differentiation separates capital-intensive military specifications from municipal budget constraints.
- Disaster Response:Multi-spectral reconnaissance for earthquake, flood, and structural collapse scenarios concentrates demand in Japan's prefectural networks and California's urban search teams. METI subsidies and FEMA preparedness grants accelerate sensor-integrated platform adoption.
- Military Operations:Battlefield casualty extraction and CBRN reconnaissance require hardened communication architectures and GPS-denied navigation capabilities.
- Building Inspection:Confined-space structural assessment for industrial facilities and infrastructure maintenance.
- Environmental Monitoring:Wildfire perimeter tracking and hazardous gas plume mapping for EPA and EEA compliance programs.
Disaster response commands the largest installed base; military operations are climbing the fastest.
Technology:
Margin pools concentrate in sensor fusion architectures that consolidate multiple detection modalities onto single platforms.
- Teleoperation:Direct human control via radio or tethered links remains standard for high-stakes casualty extraction where autonomous failure carries unacceptable risk.
- Autonomous Navigation:Self-driving capabilities in GPS-denied environments demand extended software certification timelines under EU AI Act conformity requirements.
- Sensor Integration:Unified LIDAR-thermal-gas detection arrays digitize reconnaissance workflows for fire departments. Los Angeles and London agencies stream composite environmental maps directly to incident command posts, replacing sequential search with simultaneous multi-threat assessment.
- Communication Systems:Mesh networking and satellite backhaul for beyond-line-of-sight coordination in remote disaster zones.
Sensor integration captures the steepest expansion trajectory; teleoperation retains the largest deployment footprint.
End User:
Customer type determines procurement rhythm, with government agencies running formal tender cycles and NGOs prioritizing rapid field deployment.
- Government Agencies:Municipal fire departments and national emergency management authorities in Japan, Germany, and the United States drive volume procurement through structured RFP processes. EU AI Act risk classifications and ISO 17840 interoperability standards filter vendor participation.
- NGOs:Humanitarian organizations deploy lighter, rapidly configurable platforms for international disaster response without lengthy certification requirements.
- Military:Defense ministries specify hardened platforms with encrypted communications and independent navigation authority.
- Private Sectors:Industrial facility operators and insurance risk assessors purchase inspection-configured units for confined-space and hazardous environment surveys.
Government agencies hold the largest share; NGOs are gaining share fastest through rapid procurement protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Japanese prefectures prioritize sensor-integrated ground platforms for seismic response, while US municipalities favor aerial BVLOS deployments for wide-area search coverage. European procurement filters through the EU AI Act's conformity framework.
United States
FEMA preparedness grants and urban search team modernization drive municipal procurement of multi-spectral reconnaissance platforms. FAA beyond-visual-line-of-sight rulemaking for emergency response drones unlocks expanded aerial operations for fire departments. Los Angeles and New York City agencies deploy unified LIDAR-thermal-gas detection systems for structural collapse scenarios.
Japan
METI disaster resilience funding accelerates sensor-integrated ground robot adoption across prefectural emergency networks. The Ministry of Economy, Trade and Industry subsidizes municipal procurement of IP67-sealed locomotion platforms for earthquake response. Tokyo Fire Department maintains the largest deployed fleet of elastomer-sealed tracked units for rubble traversal operations.
Germany
Budget-constrained emergency services prefer operational expenditure models over capital-intensive purchases. ISO 17840 interoperability standards filter vendor participation in federal and municipal tenders. North Rhine-Westphalia and Bavaria lead Länder-level procurement of cross-compatible communication protocol systems.
United Kingdom
London Fire Brigade digitizes reconnaissance workflows through composite environmental mapping platforms. The country's national emergency management authority structures multi-year fleet management contracts bundling maintenance and operator training. Greater Manchester and West Midlands urban search teams coordinate deployment protocols for GPS-denied navigation scenarios.
South Korea
Municipal budget constraints favor subscription-based service models over hardware ownership. The country's national standards body aligns procurement specifications with emerging ISO frameworks. Seoul Metropolitan Fire and Disaster Headquarters deploys amphibious platforms for flood response scenarios in the Han River basin.
Search and Rescue Robots Market Key Industry Players
Capability concentration sits with specialized locomotion and sensor integration developers; scale advantage sits with diversified defense contractors and maritime technology conglomerates. The vendor base stratifies across three tiers: pure-play robotics specialists, diversified industrial technology groups, and defense-prime system integrators. Dominant competitive moves include strategic partnerships for sensor fusion architectures and geographic expansion through certification-compliant product localization.
Within the specialized mobility tier, Boston Dynamics and Kongsberg Maritime exemplify divergent capability anchors. Boston Dynamics occupies a position in advanced legged locomotion for rubble traversal, while Kongsberg Maritime represents pressure-rated autonomous platform specialization for underwater search configurations. Among diversified technology groups, Teledyne FLIR sits within the thermal imaging integration archetype, anchoring smoke-penetration applications through multi-spectral sensor convergence. These three entities collectively illustrate how vendor positioning fragments across locomotion modality rather than consolidating around unified platform architectures.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Hydronalix |
| Boston Dynamics |
| Saab AB |
| Thales Group |
| Lockheed Martin Corporation |
| Kongsberg Maritime |
| Howe & Howe Technologies |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
Shenzhen's lithium cell manufacturing cluster anchors global battery supply for extended-flight aerial platforms, concentrating pricing power among East Asian producers and exposing municipal procurement budgets to concentrated input cost volatility. Fire departments in Los Angeles and Tokyo negotiate multi-year fleet management contracts to buffer against spot-market fluctuations in high-density cell chemistries.
Pricing Analysis
Long-term fleet management contracts dominate municipal procurement, displacing capital-intensive purchase patterns across budget-constrained emergency services. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17840-certified interoperability platforms from sealed-environment ground units with basic teleoperation. Pricing pressure stems from EU AI Act conformity costs extending vendor sales cycles for autonomous navigation capabilities. NGOs exhibit highest price sensitivity through rapid-deployment procurement protocols, while defense ministries absorb premium tiers for hardened communication architectures.
Supply Chain Analysis
Export-control regimes limiting autonomous navigation software flows constrain component sourcing for GPS-denied platform developers. Manufacturing concentrates in China, South Korea, and Japan for lithium cells, precision elastomers, and multi-spectral sensor arrays. Raw material dependencies center on rare-earth magnets for actuator motors, specialized sealing compounds for IP67 housings, and thermal imaging cores. Single-source vulnerability runs through concentrated lithium refining capacity. Distribution runs through defense-prime integrators and specialized robotics distributors serving municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors must defend against substitution from lower-cost teleoperation platforms as budget-constrained agencies defer autonomous navigation investments. The threat of simplified manual-control systems displacing premium self-navigating configurations intensifies across European and Asian municipal markets.
For Market Incumbents: Harden certification capabilities against EU AI Act conformity requirements to maintain access to European government agency contracts. Deepen backward integration into sensor fusion architectures to capture margin pools from LIDAR-thermal-gas detection convergence. Lock in multi-year aftermarket service contracts with Tokyo and Los Angeles fire departments to secure recurring revenue streams against hardware commoditization.
For New Entrants and Emerging Players: Build out pressure-rated autonomous configurations for maritime search and submarine rescue missions, the most underpenetrated mobility segment relative to ground and aerial platforms. Target coastal municipalities in Japan and Germany with subscription-based operational expenditure models that bypass capital budget constraints. Establish go-to-market partnerships with Kongsberg Maritime or Teledyne FLIR for rapid technology access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor integration specialists with documented safety case submission capabilities over pure-play locomotion developers. Five-to-ten year viability hinges on compliance infrastructure rather than hardware differentiation alone. Signal to watch: harmonization progress between FAA and EASA certification frameworks unlocking cross-border procurement channels for unified platform architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Investment | Multi-spectral convergence captures margin pools from fire departments digitizing reconnaissance workflows. |
| EU AI Act Conformity Certification | Risk-classification compliance filters vendor participation in European government agency tenders. |
| Aftermarket Service Unbundling | Subscription-based fleet management contracts displace capital-intensive purchase patterns across German municipalities. |
| Underwater Platform Development | Pressure-rated configurations address untapped coastal municipality demand for maritime search capabilities. |
| ISO 17840 Interoperability Compliance | Cross-compatible communication protocols create specification advantages in structured RFP processes. |
Research Approach
Desk research of regulatory filings from FAA and EASA, EU AI Act implementation guidance, and METI disaster resilience program documentation preceded structured interviews with municipal fire department procurement officers, autonomous navigation software developers, and sensor integration engineering leads. Primary fieldwork encompassed urban search team commanders in Los Angeles, Tokyo, and London alongside defense-prime system integrators. Secondary validation drew from ISO standards repositories, SEC 10-K disclosures from diversified technology groups, and customs data for lithium cell trade flows. Bottom-up platform deployment estimates triangulated against top-down emergency services budget allocations.
Assumptions held fixed include current FAA BVLOS rulemaking trajectory, EU AI Act risk classification stability, and lithium cell supply concentration patterns. The forecast framework models mobility platform type, autonomy technology tier, end-user procurement channel, and geographic regulatory cluster across the analysis window. CAGRs derive from segment-level adoption curves weighted by municipal budget elasticity and defense ministry modernization cycles. Key inputs include FEMA preparedness grant disbursement patterns and METI subsidy allocation trajectories.
Practitioners should monitor FAA-EASA certification harmonization progress and EU AI Act enforcement consistency for early signals of platform architecture standardization. Forecasts reflect assumptions regarding battery density improvement curves and elastomer sealing material cost stability. Material shifts in export-control regime stringency for autonomous navigation software would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Europe Educational Robot Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market