
 Warehouse Robotics Market | 2026-2036
Warehouse Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Robotics Market Intelligence
The customer base for warehouse robotics is consolidating as large third-party logistics providers and e-commerce giants expand their automated facility networks. Amazon Robotics leverages its extensive operational data to refine its proprietary systems for internal fulfillment centers. In contrast, KION Group AG competes with a broad portfolio of solutions for diverse industrial clients, while Locus Robotics specializes in collaborative mobile robots for picking operations.
Warehouse robotics encompasses automated systems designed to perform logistics tasks within a controlled environment, often utilizing technologies like LiDAR for navigation and object avoidance. The primary purpose is to increase throughput, accuracy, and safety in material handling and order fulfillment operations. Autonomous Mobile Robots (AMRs) represent the fastest-growing product type, valued for their flexibility and ease of integration. Within applications, order picking remains the largest segment due to its direct impact on labor costs and fulfillment speed.
Regulatory frameworks like ISO 3691-4 govern the safety requirements for driverless industrial trucks, ensuring operational security. In parallel, compliance with standards such as the CE marking in Europe and OSHA guidelines in the United States dictates market access and deployment protocols. Stakeholder success depends on developing interoperable systems that can integrate seamlessly with existing warehouse management software and scale with operational demand.
Market Dynamics
Intense demand from the e-commerce fulfillment sector for drastically reduced order processing times is the central force shaping the warehouse robotics market. This pressure dictates technology development towards greater speed, accuracy, and integration with existing warehouse management systems to achieve competitive advantage.
Growth Catalysts
- Chinese Industrial Policy:Government support for automation in China accelerates robotics adoption, creating a concentrated, high-volume demand center for warehouse automation systems and related software.
- AI-Enhanced Navigation:The integration of AI algorithms improves robot pathing and task execution, boosting throughput in complex order fulfillment environments for the e-commerce sector.
- 3PL Sector Expansion:Growth of third-party logistics providers creates a large-scale customer base requiring standardized, scalable robotic solutions to manage diverse client inventories efficiently.
Market Restraints
- High Initial Investment:Significant capital expenditure for hardware and software integration remains a primary adoption barrier for small and medium-sized enterprises (SMEs).
- Integration Complexity:Lack of standardization complicates the integration of robotic systems with legacy Warehouse Management Systems (WMS), increasing deployment time and costs.
- Component Supply Concentration:Dependence on a few suppliers for critical components like LiDAR sensors creates vulnerability to shortages and price volatility.
Strategic Opportunities
- Emerging Market Entry:Targeting e-commerce sectors in Southeast Asia and Latin America, where warehouse automation is underpenetrated, presents a significant growth vector for vendors.
- New Application Development:Expanding beyond picking into automated truck loading and complex returns processing addresses unmet operational needs and opens new revenue streams.
- Digital Twin Integration:Using digital twin technology to simulate and optimize robotic workflows before physical deployment de-risks large-scale investments and improves return on investment.
Industry Challenges
- Technical Talent Scarcity:A shortage of technicians skilled in robotics and AI hinders the deployment and maintenance of automation projects, limiting scalability for end-users.
- Legacy System Integration:Integrating autonomous robots with existing, often outdated, warehouse management software and physical infrastructure presents a major technical and operational hurdle.
- Navigating Safety Compliance:Adhering to evolving safety standards like ISO 3691-4 for robots operating alongside humans requires continuous investment in certification and risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Robotics Market |
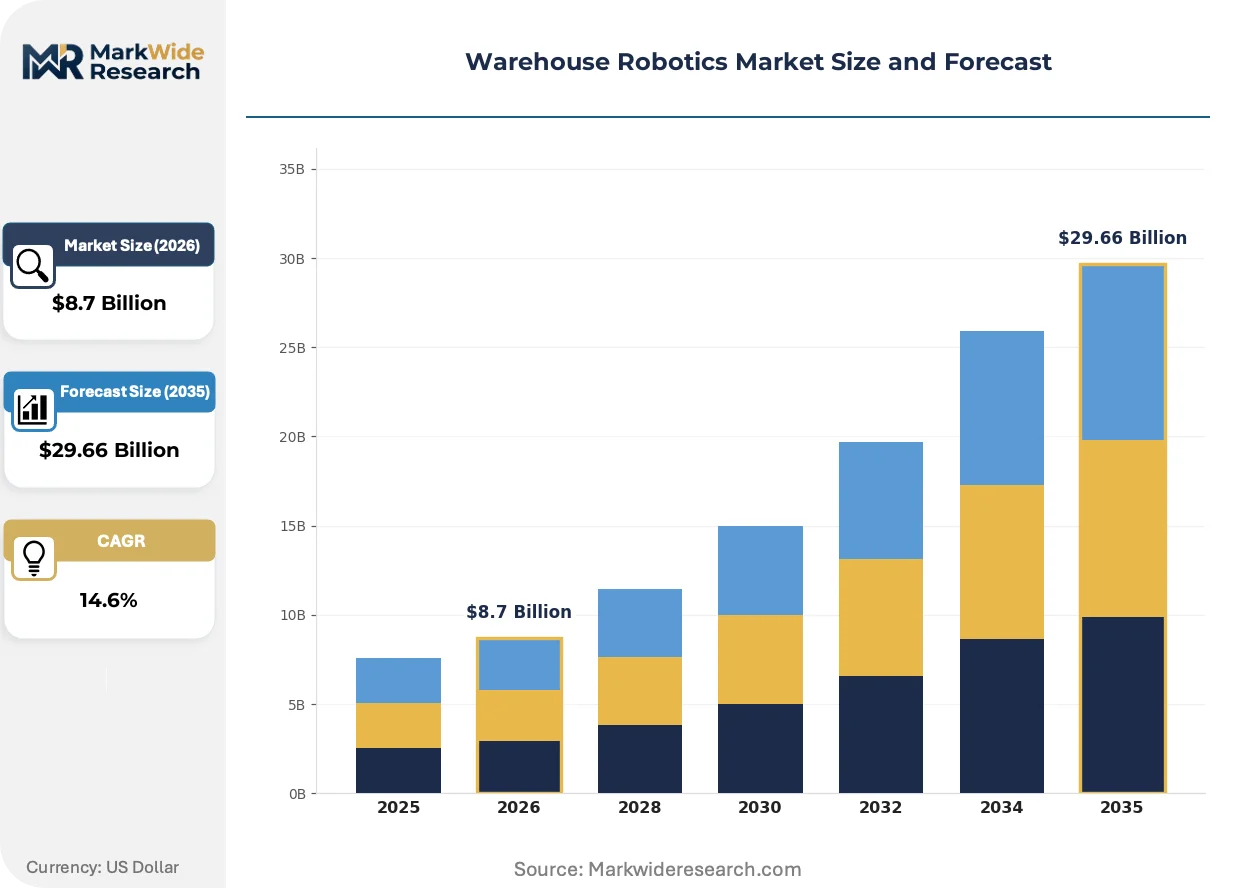
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Mobile Robots, Automated Guided Vehicles, Robotic Arms, Sorting Robots, Palletizing Robots Technology: Machine Vision, LiDAR, RFID, AI & Machine Learning, Sensor Fusion Application: Inventory Management, Order Picking, Sorting & Packaging, Palletizing & Depalletizing, Material Handling End User Industry: E-commerce Fulfillment Centers, Third-Party Logistics Providers, Retail Warehouses, Manufacturing Facilities |
| Companies Covered | Amazon Robotics, Daifuku Co., Ltd., KION Group AG, ABB Ltd., FANUC Corporation, Locus Robotics, Geek+ Technology Co., Ltd., KUKA AG, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Robotics Market Strategic Shifts & Innovations
Software-defined capabilities and system modularity are fundamentally transforming warehouse robotics from isolated hardware to interconnected, intelligent networks. This evolution prioritizes flexibility and data-driven optimization over single-task automation, enabling more dynamic and resilient logistics operations.
Autonomous Mobile Robots (AMRs) utilize LiDAR and advanced vision systems for infrastructure-free navigation within dynamic warehouse environments. E-commerce fulfillment and third-party logistics providers are rapidly adopting these systems for their flexibility and quick deployment times. The AMR platform is modularizing automation, enabling operators to scale fleets and swap task-specific modules to adapt to fluctuating operational demands.
International standards such as ISO 3691-4 are establishing a unified safety framework for driverless industrial trucks and autonomous mobile robots. This codification of safety requirements de-risks adoption for end-users and clarifies design targets for manufacturers, facilitating market access. The collaborative robot segment is particularly impacted, as compliance is essential for validating safe operation alongside human workers under guidelines from regulators like OSHA.
Customers are increasingly favoring Robotics-as-a-Service (RaaS) subscription models over traditional, large-scale capital equipment purchases. This opex-based approach lowers the financial barrier to automation, offering scalability to match seasonal demand fluctuations without long-term asset ownership. The shift is most prominent among mid-sized e-commerce firms and 3PL providers in the United States and Europe seeking operational flexibility.
Warehouse Robotics Market Segmentation
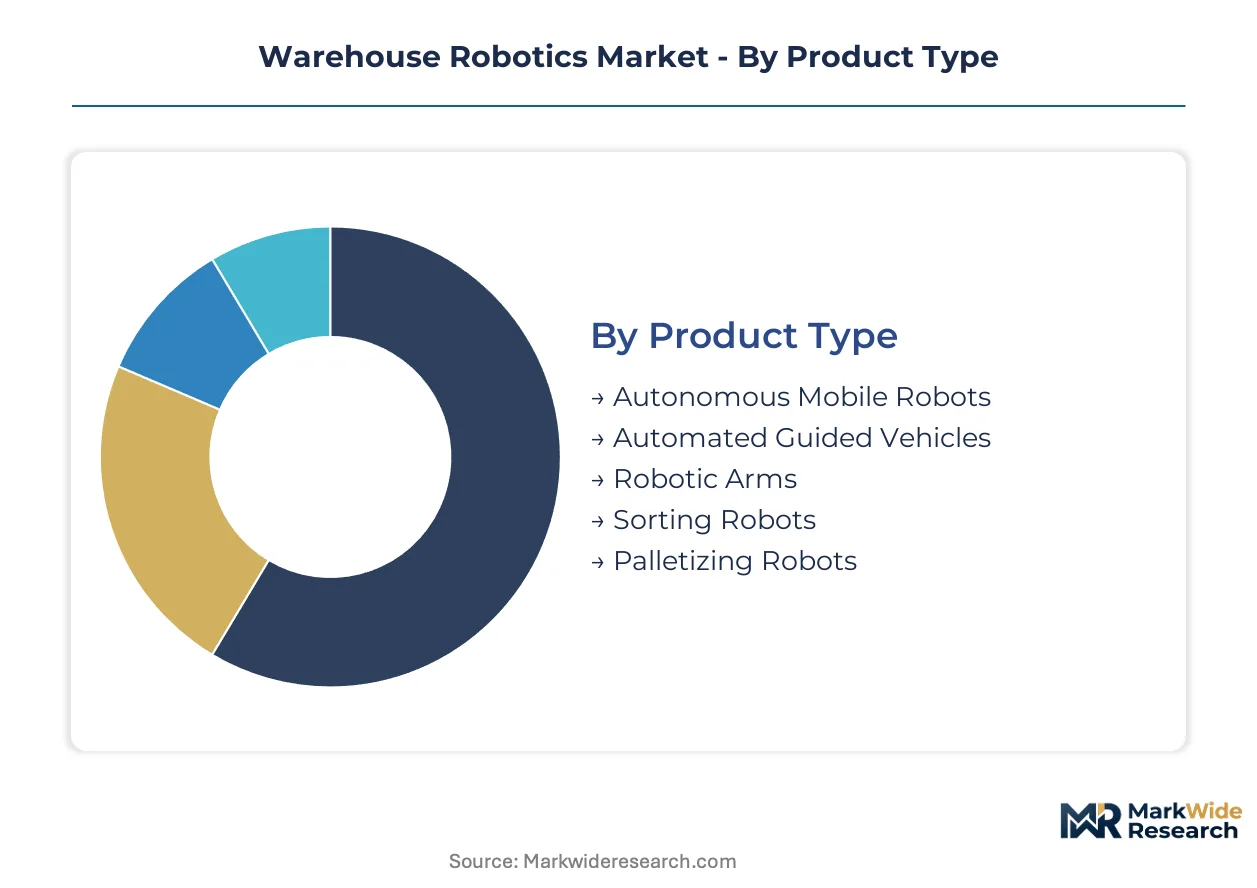
Understanding the distinct segments within the warehouse robotics market illuminates the varied technological adoption patterns and operational priorities driving investment. Each segment reflects specific challenges and opportunities, influencing product development and strategic market positioning for vendors.
Product Type:
The market for warehouse robotics is bifurcated by the complexity and autonomy of the systems, ranging from volume-driven, fixed-path solutions to premium, flexible autonomous units.
- Autonomous Mobile Robots:These intelligent systems navigate dynamic warehouse environments without fixed infrastructure, utilizing sensors and AI for flexible material transport. Demand concentrates in e-commerce fulfillment centers across the United States, where rapid scalability is critical.
- Automated Guided Vehicles:AGVs follow predefined paths, often marked by wires or magnetic tape, for repetitive material transport tasks in structured environments. Manufacturing facilities in China frequently deploy AGVs to optimize internal logistics flows and reduce labor costs.
- Robotic Arms:These articulated manipulators perform precise and repetitive tasks like picking, packing, and assembly within a fixed workstation.
- Sorting Robots:Specialized robots categorize and direct parcels or goods to specific destinations within a distribution center, significantly increasing throughput.
- Palletizing Robots:These systems automatically stack goods onto pallets for storage or shipment, enhancing efficiency and reducing manual labor in warehousing.
Today's leader: Autonomous Mobile Robots. Tomorrow's challenger: Robotic Arms.
Technology:
Robotic system capabilities are defined by their integrated technologies, with advancements in sensing and intelligence unlocking new operational applications across the supply chain.
- AI & Machine Learning:These algorithms enable robots to learn, adapt, and make autonomous decisions, improving navigation, task execution, and predictive maintenance. E-commerce platforms leverage AI to optimize robot pathing and order fulfillment processes.
- LiDAR:Light Detection and Ranging sensors provide high-resolution 3D mapping of environments, crucial for precise navigation and obstacle avoidance in dynamic warehouses. Third-party logistics providers deploy LiDAR-equipped AMRs for enhanced safety.
- Machine Vision:Cameras and image processing software allow robots to identify, locate, and inspect objects, essential for picking, quality control, and inventory scanning.
- RFID:Radio-Frequency Identification technology provides automated tracking and identification of inventory items, streamlining warehouse management and reducing errors.
- Sensor Fusion:This technology combines data from multiple sensors (e.g., LiDAR, cameras, ultrasonic) to create a more robust and accurate perception of the robot's surroundings.
AI & Machine Learning represents the fastest-growing trajectory, while LiDAR offers the steepest expansion trajectory in sensing capabilities.
Application:
The utility of warehouse robotics spans various operational areas, with specific applications directly addressing critical pain points for different customer types.
- Order Picking:Robots autonomously retrieve items from storage locations to fulfill customer orders, directly impacting labor costs and fulfillment speed. E-commerce fulfillment centers prioritize this application to meet demand for rapid delivery.
- Material Handling:This broad application involves the movement, storage, protection, and control of materials throughout the warehouse, often using AMRs and AGVs. Third-party logistics providers adopt these systems for efficient internal transport.
- Inventory Management:Robotic systems assist in tracking stock levels, locating items, and conducting cycle counts, improving accuracy and reducing manual effort.
- Sorting & Packaging:Robots automatically sort products by destination or type and prepare them for shipment, enhancing throughput in high-volume operations.
- Palletizing & Depalletizing:These applications involve robots stacking and unstacking goods on pallets, reducing ergonomic risks and increasing efficiency in repetitive tasks.
Order Picking is currently gaining share fastest, while Material Handling solutions are climbing the fastest in overall operational impact.
End User Industry:
Different industries adopt warehouse robotics at varying rates, reflecting their unique operational complexities and investment capacities.
- E-commerce Fulfillment Centers:These facilities demand high-speed, high-volume order processing to meet consumer expectations for rapid delivery, making them primary adopters of automation. Amazon Robotics exemplifies this intensive use for internal operations.
- Third-Party Logistics Providers:3PLs manage diverse client inventories and require flexible, scalable robotic solutions to optimize operations across multiple warehouses. KION Group AG offers broad solutions for these varied industrial clients.
- Retail Warehouses:These warehouses manage inventory for brick-and-mortar stores, utilizing robotics to streamline replenishment and optimize space utilization.
- Manufacturing Facilities:Robotics in manufacturing warehouses supports production lines through automated material supply, work-in-progress transport, and finished goods storage.
E-commerce Fulfillment Centers demonstrate the highest maturity in robotics deployment, while Third-Party Logistics Providers are rapidly maturing their automation strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives warehouse robotics adoption through e-commerce fulfillment, China's industrial policies significantly accelerate its market expansion. These distinct national priorities shape technology integration and deployment strategies across various regions. Other key geographies also contribute to the market's evolution.
United States
United States e-commerce fulfillment centers demand rapid scalability for warehouse robotics, driving significant investment in automation. OSHA guidelines influence the design and deployment of collaborative robots operating alongside human workers. Major tech hubs like Silicon Valley concentrate AI and machine learning development, enhancing robot navigation capabilities.
China
China's government support for automation propels warehouse robotics adoption within its vast manufacturing facilities and logistics networks. Compliance with GB standards ensures the safety and quality of domestically produced robotic systems. Industrial upgrade initiatives in the Yangtze River Delta foster high-volume demand for AGVs and AMRs.
Germany
Germany's advanced manufacturing sector and robust logistics infrastructure drive demand for sophisticated warehouse robotics solutions. CE marking compliance is essential for market access, ensuring robots meet stringent European safety standards. Industrial automation clusters in Bavaria focus on developing interoperable systems for diverse industrial clients.
Japan
Japanese manufacturing facilities increasingly adopt warehouse robotics to address labor shortages and enhance operational efficiency. JIS standards guide the development and deployment of advanced robotic arms and automated material handling systems. The Kanto region remains a hub for robotics innovation, with companies focusing on precision and reliability.
India
India's burgeoning e-commerce sector fuels demand for rapid order fulfillment and efficient warehouse automation. The PLI scheme stimulates local manufacturing of robotics components and integrated systems. Major logistics hubs like Delhi-NCR are witnessing increased deployment of AMRs to manage growing parcel volumes.
Warehouse Robotics Market Key Industry Players
North American technology developers anchor one tier; Asian manufacturers and European industrial conglomerates hold significant market positions. The market structure exhibits a blend of consolidation among established industrial automation players and fragmentation from nimble robotics startups. Key strategic archetypes include integrated solution providers, specialized mobile robot developers, and component suppliers. Companies primarily focus on strategic partnerships, geographic expansion, and portfolio diversification to expand their market reach and address evolving customer requirements.
Within the integrated solution provider archetype, KION Group AG exemplifies a broad portfolio approach for diverse industrial clients, leveraging its extensive experience in material handling. Amazon Robotics, an internal developer, represents the extensive operational data-driven refinement of proprietary systems for e-commerce fulfillment centers globally. Locus Robotics, specializing in collaborative mobile robots for picking operations, highlights the focus on flexible, task-specific automation solutions. These entities illustrate the varied strategies adopted to serve distinct customer needs across the warehouse automation landscape, from large-scale enterprise solutions to agile, specialized deployments.
| Leading Market Players |
|---|
| Amazon Robotics |
| Daifuku Co., Ltd. |
| KION Group AG |
| ABB Ltd. |
| FANUC Corporation |
| Locus Robotics |
| Geek+ Technology Co., Ltd. |
| KUKA AG |
| Omron Corporation |
| Others |
Cost & Logistics Intelligence
The bifurcation between Robotics-as-a-Service (RaaS) models and traditional capital expenditure purchases significantly shapes both pricing and supply chain configurations. RaaS offers operational expenditure flexibility, drawing from a distributed service and component supply network, while large-scale capital investments often rely on vertically integrated suppliers for complex, proprietary systems.
Pricing Analysis
Capacity additions in China are reshaping price floors for Automated Guided Vehicles and other fixed-path systems. The dominant pricing model is a hybrid, combining project-based capital expenditure for large deployments with subscription-tiered models for RaaS solutions. Price differentiation stems from customization level for specific warehouse layouts and the breadth of after-sales service agreements. Pricing softness reflects intense competition among solution providers, especially for mid-tier offerings. Small and medium-sized enterprises exhibit the highest price sensitivity, while large e-commerce giants prioritize performance and integration over initial cost.
Supply Chain Analysis
Logistics and freight costs influence the regional competitiveness of warehouse robotics components. Geographic supply concentration includes China for AGV manufacturing and basic components, the United States for advanced AI and software, and Germany for sophisticated mechanical engineering. The market draws from critical components like LiDAR sensors, specialized AI processors, and precision motors. Component supply concentration, particularly for LiDAR sensors, creates single-source vulnerability. Distribution runs through a mix of direct sales channels and strategic partnerships with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, driven by a demand-shift toward highly flexible, AI-enhanced autonomous systems that offer superior operational efficiency.
For Market Incumbents: Acquire specialized AI software development firms to integrate next-generation pathing and task execution algorithms. Expand Robotics-as-a-Service offerings to counter the threat from nimble, modular solution providers. Focus R&D investment on interoperability standards to ensure seamless integration with diverse warehouse management software. Invest in ISO 3691-4 certification to maintain a competitive edge in regulated markets.
For New Entrants and Emerging Players: The PLI scheme in India opens a window for local manufacturing of robotics components and integrated systems. Target underpenetrated e-commerce sectors in Southeast Asia with flexible, modular Autonomous Mobile Robot solutions. Develop new applications in complex returns processing or automated truck loading for white-space opportunities. A strong go-to-market angle involves offering easy-to-deploy, scalable systems with clear return-on-investment metrics.
For Investors and Strategic Acquirers: Consolidation pressure builds where integration complexity and technical talent scarcity limit organic growth. Long-term viability hinges on sustained e-commerce expansion and increasing labor cost pressures across industries. Target acquisition archetypes include specialized software developers for robot orchestration and niche component manufacturers. The successful integration of digital twin technology by solution providers serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Modular AMR Systems | Enables rapid deployment and scalability for diverse customer operational needs. |
| Form Strategic WMS Integration Partnerships | Ensures seamless data exchange and operational coherence with existing warehouse systems. |
| Acquire AI/ML Expertise Firms | Enhances robot intelligence for improved navigation, task execution, and predictive maintenance. |
| Expand into Emerging E-commerce Markets | Captures new demand in regions with high growth potential and underpenetrated automation. |
| Invest in ISO 3691-4 Certification | Validates safety standards for collaborative robots, facilitating market access and adoption. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary research from official publications, and competitive intelligence databases — were reconciled. This approach combined insights from robotics engineers, warehouse operations managers, logistics executives, and regulatory compliance officers. Secondary sources included government industrial policy documents, financial filings of public robotics companies, and academic research on AI/ML in robotics. Bottom-up and top-down triangulation validated market size and growth projections.
The analytical framework systematically reconciled various data streams across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional market maturity. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key industry-specific forecast inputs included e-commerce growth rates and global labor availability indices.
Revisions become necessary when geopolitical trade tensions affecting component supply or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding regulatory stability and market adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Robot Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Commercial Security Robots Market