
 Global Medical Robotic Systems Market | 2026-2036
Global Medical Robotic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Robotic Systems Market Foresight
Hospital buyer concentration is expanding as integrated delivery networks and multinational health systems consolidate procurement budgets across multiple facilities. Intuitive Surgical leverages decades of da Vinci platform refinement to sustain technology leadership in soft-tissue procedures. Medtronic competes through its Hugo robotic-assisted surgery system, while Stryker Corporation anchors orthopedic robotics via its Mako SmartRobotics platform.
Medical robotic systems integrate electromechanical actuators, sensor arrays, and software-controlled kinematic chains to perform or assist precision clinical tasks with sub-millimeter accuracy. These systems serve primarily to augment surgeon capability, reduce procedural variability, and enable remote or minimally invasive interventions that manual techniques cannot replicate. Surgical robots occupy the largest value pool given capital intensity and recurring instrument revenue, while rehabilitation robots represent the fastest-expanding category as post-acute care automation gains traction. Pharmacy automation robots capture steady institutional demand as labor costs and medication error liability drive hospital formulary modernization.
FDA premarket notification pathways and EU MDR conformity assessments shape product launch timelines and clinical evidence requirements for manufacturers seeking market access. Japan's PMDA and Germany's BfArM impose additional localization testing that filters which platforms achieve commercial scale in those jurisdictions. Stakeholders must monitor how reimbursement coding decisions by CMS and parallel authorities in other countries determine whether robotic procedures achieve cost parity with conventional surgery.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while demanding integrated service contracts that bundle hardware, software, and training into multi-year agreements. This buyer concentration is forcing manufacturers to restructure pricing models and deepen clinical support capabilities.
Growth Catalysts
- EU MDR clearance pathways:Streamlined conformity assessments for robotic surgical platforms are accelerating product launches across European health systems. Manufacturers prioritize CE marking to access reimbursement pools in Germany, France, and the Netherlands.
- Japan's aging surgical workforce:Demographic contraction among trained surgeons is driving hospital investment in robotic assistance systems that extend operative capacity. PMDA fast-track reviews for autonomy features support this transition.
- Cloud-based surgical analytics:Real-time procedure data capture is enabling outcome tracking that satisfies payor evidence requirements. Health systems in the United States leverage this infrastructure to negotiate bundled payment contracts.
Market Restraints
- Capital intensity of da Vinci-class platforms:Single-unit acquisition costs exceeding $2 million limit deployment to tertiary academic centers. Community hospitals face extended depreciation cycles that delay replacement purchases.
- Concentrated sensor supply:Force-sensing haptic feedback modules rely on Japanese and German component suppliers. Geographic concentration creates vulnerability to export licensing delays and input cost volatility.
- FDA premarket notification timelines:510(k) pathways for autonomous navigation features require extensive clinical validation. Submission backlogs extend time-to-revenue for novel kinematic control algorithms.
Strategic Opportunities
- India's tier-2 city hospitals:Underpenetrated secondary markets present whitespace for compact, lower-cost robotic platforms. CDSCO regulatory harmonization with IMDRF standards reduces entry barriers for multinational manufacturers.
- Rehabilitation robotics in post-acute settings:Skilled nursing facilities represent an emerging application segment with limited incumbent competition. Medicare Advantage plan expansion is creating reimbursement tailwinds for stroke recovery automation.
- AI-actuated preoperative planning:Convergence of machine learning with patient-specific anatomical modeling is enabling procedure simulation. EU AI Act risk classification frameworks provide clarity for clinical deployment of decision-support algorithms.
Industry Challenges
- Mechatronics engineering talent scarcity:Specialized expertise in surgical kinematics and biocompatible actuators concentrates in Boston, Stuttgart, and Tokyo metro areas. Recruitment competition with automotive and aerospace sectors inflates compensation costs.
- Legacy EMR integration complexity:Robotic platforms must interface with heterogeneous hospital information systems that lack standardized data exchange protocols. Proprietary vendor architectures force costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Robotic Systems Market |
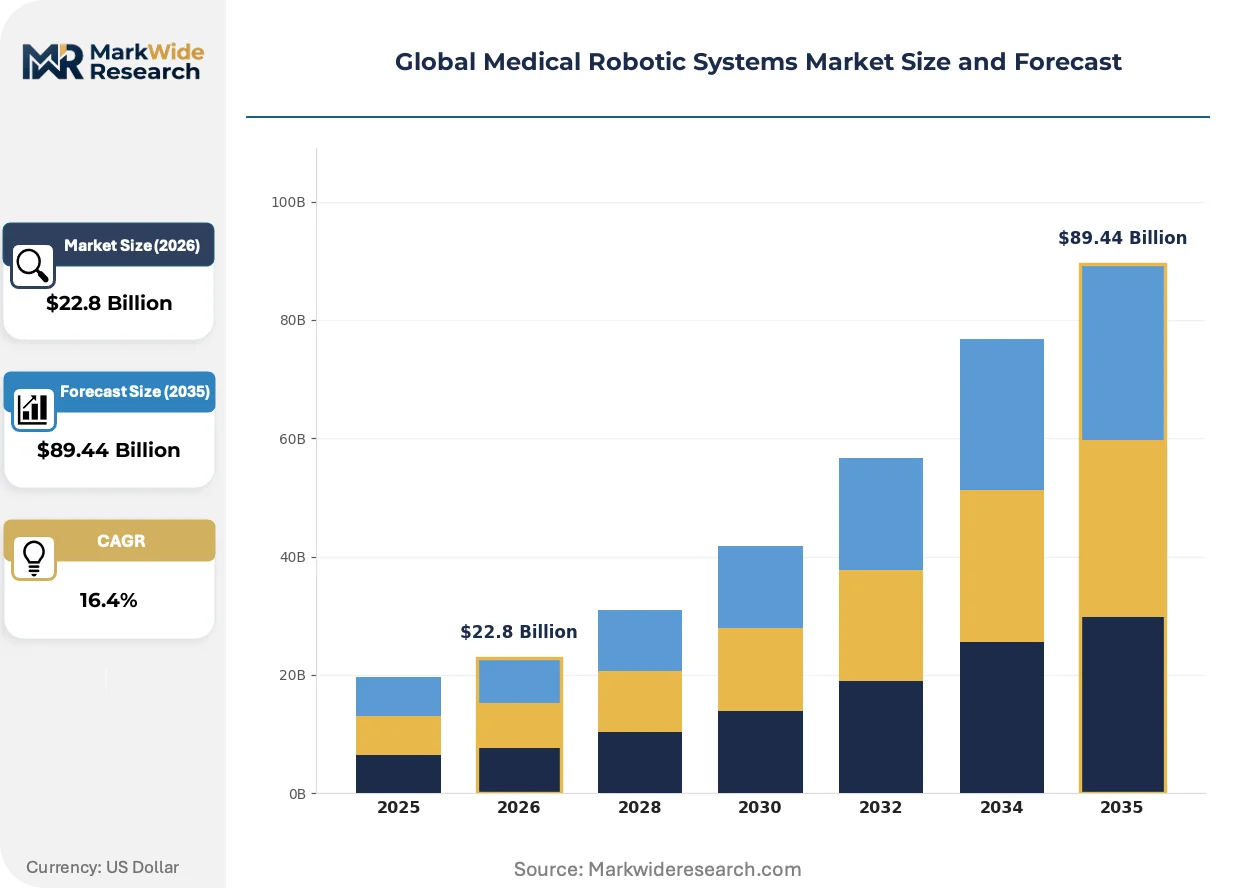
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $89.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Pharmacy Automation Robots, Diagnostic Robots, Disinfection Robots Application: Minimally Invasive Surgery, Orthopedic Surgery Assistance, Neurological Surgery, Remote Patient Monitoring, Laboratory Automation Technology: Lidar Navigation, Machine Vision, Force Feedback, Haptic Technology, Artificial Intelligence End User: Hospitals, Ambulatory Surgical Centers, Research Laboratories, Care Facilities, Academic Institutions |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, CYBERDYNE INC., Ekso Bionics, Bionik Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Robotic Systems Market Shifts & Advancements
Autonomous navigation capabilities are migrating from research prototypes into commercial surgical platforms, redefining the boundary between surgeon-directed and machine-executed motions. This shift is compressing training requirements while raising novel liability questions.
Force-sensing haptic feedback is integrating sub-millimeter tactile resolution into robotic end-effectors, enabling tissue manipulation that approximates manual palpation. Academic medical centers in the United States and Germany are adopting these platforms for complex oncologic resections. The technology is integrating real-time biomechanical modeling that adjusts grip parameters based on tissue density variations, reducing iatrogenic injury rates.
FDA's evolving guidance on autonomous surgical systems is requiring manufacturers to submit algorithmic transparency documentation alongside traditional safety data. This policy shift is extending premarket review timelines by twelve to eighteen months for platforms with adaptive learning features. Soft-tissue procedure categories face the most stringent evidentiary burdens, prompting developers to prioritize orthopedic and spinal applications where anatomical constraints are more predictable.
Health system procurement departments are consolidating vendor relationships through master service agreements that span multiple facilities and procedure types. Group purchasing organizations are displacing individual hospital negotiations, extracting volume discounts and standardized training commitments. This concentration is most visible in the United States, where integrated delivery networks now control over sixty percent of robotic surgery capital allocations.
Global Medical Robotic Systems Market Segmentation
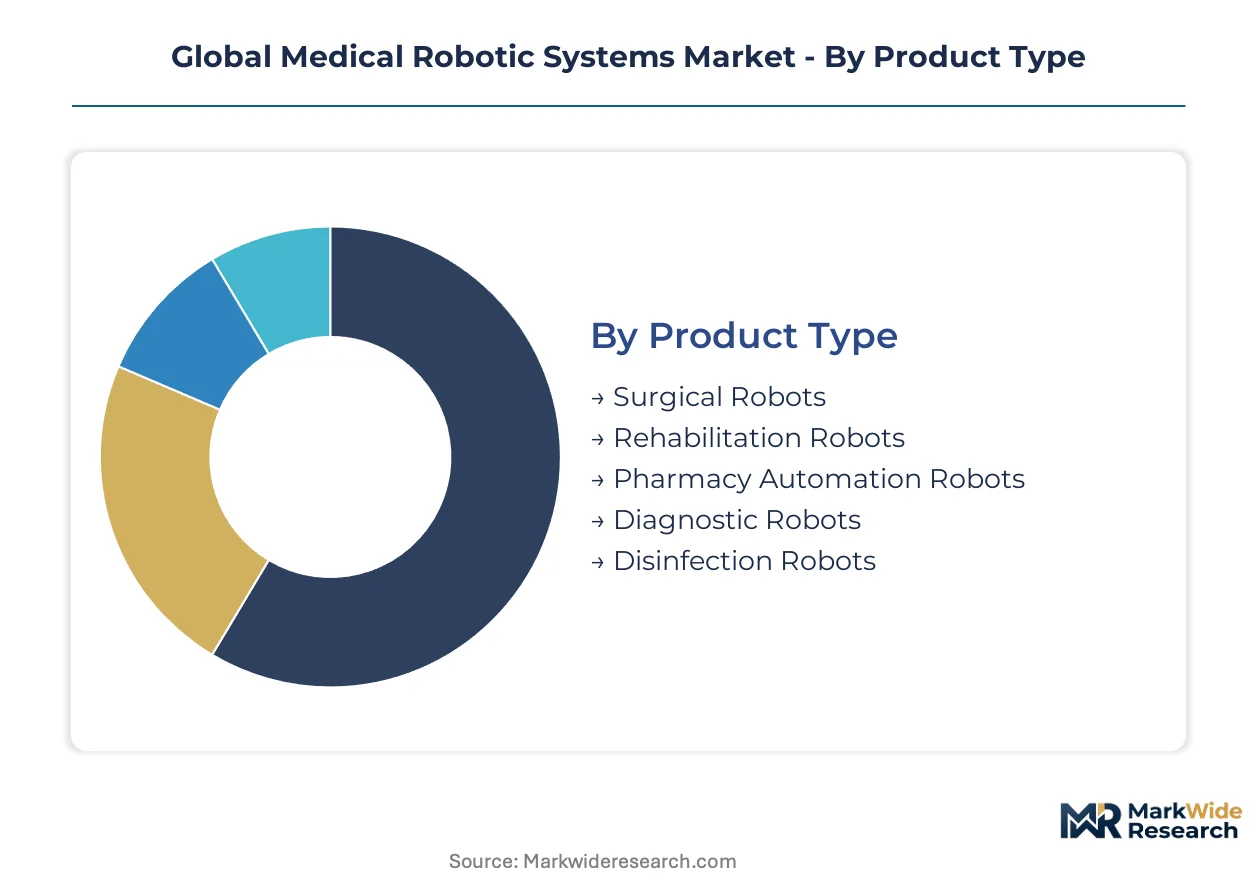
Medical robotic systems fragment across multiple technical and commercial dimensions that determine regulatory pathways, pricing architecture, and deployment velocity. Understanding these segment boundaries reveals where capital concentrates and which technology configurations command premium positioning.
Product Type:
FDA 510(k) and EU MDR Class IIa/IIb designations vary sharply across these categories, with surgical platforms facing the most stringent clinical evidence requirements while disinfection systems navigate simpler conformity routes.
- Surgical Robots:Electromechanical platforms with articulated arms and endoscopic visualization enable precision tissue manipulation through minimally invasive access ports. Tertiary hospitals in the United States and Germany concentrate procurement here, driven by reimbursement codes that reward reduced length-of-stay metrics. FDA premarket notification timelines for autonomous features now extend twelve to eighteen months.
- Rehabilitation Robots:Exoskeleton and end-effector systems deliver repetitive motion therapy for stroke and spinal cord injury recovery. Skilled nursing facilities and post-acute care centers in Japan represent the fastest-expanding demand node, supported by PMDA fast-track reviews for autonomy-enabled gait training.
- Pharmacy Automation Robots:Dispensing and compounding systems reduce medication error liability in high-volume hospital formularies.
- Diagnostic Robots:Biopsy and imaging-guided platforms automate tissue acquisition with sub-millimeter targeting accuracy.
- Disinfection Robots:UV-C and hydrogen peroxide vapor systems automate terminal cleaning protocols in isolation rooms and operating suites.
Surgical robots sit at the top of the volume ranking, with rehabilitation robots climbing the fastest.
Application:
Procedure reimbursement differentials across CMS and parallel European payor systems create tiered demand intensity, with orthopedic and cardiac interventions commanding stronger capital justification than laboratory workflows.
- Minimally Invasive Surgery:Laparoscopic and thoracoscopic procedures leverage robotic assistance for suturing, dissection, and retraction in confined anatomical spaces. United States integrated delivery networks channel sixty percent of capital allocation toward these platforms, extracting multi-year service bundling from vendors.
- Orthopedic Surgery Assistance:Kinematic navigation systems guide implant positioning and bone resection with mechanical alignment verification. German hospitals prioritize MDR-compliant platforms here given predictable anatomical constraints that accelerate regulatory clearance.
- Neurological Surgery:Stereotactic frames and trajectory planning software enable deep brain stimulation and tumor biopsy.
- Remote Patient Monitoring:Telepresence robots and vital sign automation extend specialist reach into rural and underserved geographies.
- Laboratory Automation:Specimen handling and high-throughput screening systems reduce manual pipetting burden in clinical diagnostics.
Minimally invasive surgery commands the largest installed base, though orthopedic assistance is gaining share fastest.
Technology:
Intellectual property concentration and component supply geography vary dramatically across these technology layers, with force-sensing modules relying on Japanese and German suppliers while AI training clusters concentrate in the United States.
- Artificial Intelligence:Machine learning algorithms enable real-time tissue classification, predictive kinematic control, and autonomous navigation within predefined anatomical constraints. FDA's evolving guidance now requires algorithmic transparency documentation alongside traditional safety submissions, extending review timelines for adaptive learning features.
- Force Feedback:Haptic interfaces transmit tissue resistance and texture sensation to surgeon consoles, enabling palpation-equivalent manipulation. Academic medical centers in Germany and the United States adopt these platforms for complex oncologic resections where tactile discrimination reduces iatrogenic injury.
- Lidar Navigation:Time-of-flight ranging enables spatial mapping for autonomous mobile platforms in disinfection and logistics applications.
- Machine Vision:Stereo camera arrays and depth sensors provide scene understanding for instrument tracking and tissue recognition.
- Haptic Technology:Vibrotactile and kinesthetic feedback systems supplement force sensing with texture and vibration cues.
Artificial intelligence anchors the steepest expansion trajectory, while force feedback maintains the deepest penetration in premium surgical consoles.
End User:
Procurement authority centralization versus facility-level autonomy determines vendor pricing power and contract structure complexity across these customer categories.
- Hospitals:Tertiary academic centers and community hospitals represent the dominant capital deployment channel, with integrated delivery networks consolidating purchasing across multiple facilities. Group purchasing organizations now control over sixty percent of robotic surgery allocations in the United States, extracting standardized training commitments and volume discounts.
- Ambulatory Surgical Centers:Freestanding outpatient facilities pursue compact, lower-cost platforms for high-volume procedures eligible for same-day discharge. CMS reimbursement parity with hospital outpatient departments supports capital recovery timelines here.
- Research Laboratories:Academic and commercial R&D facilities procure pre-commercial platforms for clinical validation studies.
- Care Facilities:Skilled nursing and long-term acute care settings deploy rehabilitation robotics for stroke recovery automation.
- Academic Institutions:Medical schools and teaching hospitals prioritize training-enabled platforms with simulation modules and procedure recording.
Hospitals dominate capital deployment, with ambulatory surgical centers expanding most quickly as site-of-care migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement intensity in the United States outpaces German investment rates by a factor of three, yet Japan's rehabilitation robotics deployment velocity now exceeds both markets on a per-capita basis.
United States
Integrated delivery networks in Texas and California consolidate sixty percent of national robotic surgery capital allocation, extracting multi-year service bundling from vendors. FDA premarket notification pathways for autonomous navigation features now extend twelve to eighteen months, filtering which platforms achieve commercial scale. The Boston metro area anchors mechatronics engineering talent pools that concentrate surgical kinematics expertise.
Germany
Tertiary hospitals in Bavaria and Baden-Württemberg prioritize MDR-compliant orthopedic platforms given predictable anatomical constraints that accelerate regulatory clearance. BfArM imposes additional localization testing that filters which systems achieve reimbursement parity with conventional surgery. The Stuttgart metro cluster concentrates force-sensing haptic feedback component suppliers serving European manufacturers.
Japan
Demographic contraction among trained surgeons drives hospital investment in robotic assistance systems that extend operative capacity in Tokyo and Osaka medical centers. PMDA fast-track reviews for autonomy-enabled features support this transition, particularly for gait training rehabilitation platforms. The Nagoya-Chubu corridor hosts precision actuator manufacturers supplying domestic and export markets.
India
Tier-2 city hospitals in Maharashtra and Karnataka present whitespace for compact, lower-cost robotic platforms as CDSCO regulatory harmonization with IMDRF standards reduces entry barriers. Central government production-linked incentive schemes for medical devices accelerate domestic manufacturing capacity. The Hyderabad-Telangana cluster attracts multinational R&D facilities targeting price-sensitive Asian markets.
United Kingdom
NHS England procurement frameworks concentrate purchasing authority through national commercial agreements that standardize training commitments across hospital trusts. MHRA alignment with EU MDR post-Brexit maintains CE marking recognition for continental suppliers. The Oxford-Cambridge-London arc concentrates academic medical centers adopting force-feedback platforms for complex oncologic resections.
Global Medical Robotic Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology layers, creating a tiered structure where capital intensity determines market access. Surgical robotics concentrates around platforms with decades of iterative refinement, while rehabilitation and pharmacy automation segments sustain more fragmented vendor bases. Three archetypes dominate: integrated health technology conglomerates with multi-industry portfolios, dedicated surgical robotics developers with narrow procedure focus, and rehabilitation specialists leveraging post-acute care automation tailwinds. Competitive moves center on multi-year service contract bundling and cloud-based surgical analytics integration that locks in hospital procurement relationships.
Within the integrated health technology tier, Johnson & Johnson and Medtronic occupy positions spanning surgical, orthopedic, and diagnostic robotics through diversified medical device portfolios. Intuitive Surgical exemplifies the dedicated surgical robotics archetype with concentrated expertise in soft-tissue minimally invasive platforms. Stryker Corporation anchors orthopedic robotics specialization through its focused SmartRobotics positioning in knee and hip arthroplasty navigation systems.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson |
| CYBERDYNE INC. |
| Ekso Bionics |
| Bionik Laboratories |
| Others |
Supply & Pricing Matrix
Captive production of force-sensing haptic modules by German and Japanese component specialists anchors both supply security and premium pricing power for surgical console manufacturers. This backward integration into precision actuator manufacturing insulates tier-one vendors from input cost volatility while enabling multi-year service bundling that locks hospital procurement relationships.
Pricing Analysis
Capacity additions in India's Telangana and Maharashtra manufacturing corridors are reshaping price floors for compact robotic platforms targeting tier-2 hospital buyers. Three-tier pricing structure across premium da Vinci-class systems, mid-range orthopedic navigation platforms, and economy rehabilitation exoskeletons reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from group purchasing organization consolidation across United States integrated delivery networks extracting standardized training commitments. Ambulatory surgical centers exhibit highest price sensitivity due to capital recovery timeline pressures, while tertiary academic centers prioritize performance tier over unit cost.
Supply Chain Analysis
Force-sensing haptic feedback modules rest on Japanese and German specialty component producers, with precision actuators sourcing from Nagoya-Chubu and Stuttgart metro clusters. Surgical robotic platforms draw from Taiwanese semiconductor foundries for machine vision processors, Swiss precision machining for kinematic chains, and United States AI training infrastructure for navigation algorithms. Single-source vulnerability concentrates in sub-millimeter tactile sensor arrays subject to export licensing delays. Distribution runs through hospital procurement departments consolidating vendor relationships via master service agreements spanning multiple facilities and procedure types.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA premarket notification timelines and EU MDR conformity assessments create sustained competitive moats for cleared platforms. CMS reimbursement coding decisions represent the pivotal regulatory milestone accelerating hospital capital deployment.
For Market Incumbents: Deepen clinical support capabilities through cloud-based surgical analytics integration that satisfies payor evidence requirements and locks in multi-year service contracts. Counter emerging entrant pressure from compact platform developers by accelerating capacity addition in India's production-linked incentive corridors. Prioritize certification investment in EU MDR Class IIb designations to defend positioning in German and Dutch reimbursement pools. For New Entrants and Emerging Players: Capture whitespace in India's tier-2 city hospitals where CDSCO regulatory harmonization with IMDRF standards reduces entry barriers for multinational manufacturers. Target skilled nursing facilities for rehabilitation robotics deployment where Medicare Advantage plan expansion creates reimbursement tailwinds. Pursue go-to-market angles emphasizing compact form factors and localized training partnerships that circumvent incumbent service bundling advantages. For Investors and Strategic Acquirers: Roll-up economics work for rehabilitation robotics specialists because post-acute care automation fragmentation sustains multiple mid-scale platforms without winner-take-all consolidation. Long-term viability centers on software-enabled recurring revenue models rather than capital equipment sales. Target acquisition archetypes feature AI-actuated preoperative planning developers with EU AI Act risk classification clarity. Watch PMDA fast-track review velocity for autonomy-enabled features as inflection indicator for Japanese market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Autonomous Navigation | Algorithmic transparency documentation requirements extend review timelines twelve to eighteen months for adaptive learning features. |
| CE Marking Pathway for MDR Class IIb | Streamlined conformity assessments accelerate product launches across German, French, and Dutch reimbursement pools. |
| Hospital System Partnership for GPO Access | Integrated delivery network consolidation extracts volume discounts and standardized training commitments across sixty percent of capital allocation. |
| Software Companion Development for Analytics | Real-time procedure data capture enables outcome tracking that satisfies CMS bundled payment contract requirements. |
| Reimbursement Strategy for CMS Coding | Cost parity determination with conventional surgery dictates whether community hospitals justify extended depreciation cycles. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each regional cluster combining interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation. Hospital procurement databases, CMS Medicare reimbursement data, FDA 510(k) filings, and EU MDR conformity assessment records provided foundational secondary sourcing. Bottom-up unit deployment modeling and top-down healthcare capital expenditure triangulation anchored volume and value estimates.
Granularity-level modeling proceeded at product type, application, technology, and end user dimensions across the projection horizon, with additional disaggregation by regional regulatory cluster and reimbursement framework. CAGRs derived from procedure volume elasticity to demographic aging patterns, capital replacement cycles, and payor policy evolution. Force-sensing component supply constraints and mechatronics engineering talent scarcity served as industry-specific forecast inputs tempering capacity expansion assumptions.
Regulatory clearance delays, reimbursement coding reversals, and component export licensing disruptions are the dominant revision risks to modeled deployment trajectories. Forecasts reflect documented assumptions regarding FDA premarket notification pathway efficiency and EU MDR assessment body capacity. A small set of named triggers including PMDA fast-track review velocity and CMS site-of-care migration policy warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Claytronics Market