
 Wearable Robotic Exoskeleton Market | 2026-2036
Wearable Robotic Exoskeleton Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Robotic Exoskeleton Market Analysis
The gap between premium active exoskeletons and commodity passive frames is expanding. Sarcos Corporation anchors the high-performance tier through its hydraulic full-body systems for industrial logistics. Ekso Bionics Holdings Inc. competes in medical rehabilitation with FDA-cleared gait-training platforms. Cyberdyne Inc. dominates the Japanese market through its hospital-focused HAL hybrid systems.
A wearable robotic exoskeleton is a motorized or passive mechanical frame worn on the human body to augment, assist, or restore movement through torque generation at joints, typically powered by electric motors, pneumatic actuators, or elastic elements with load ratings from 15 kg to 80 kg assistive force. These devices serve industrial workplaces, clinical rehabilitation centers, and military operations by reducing musculoskeletal strain or retraining neural pathways. The active product segment leads absolute revenue as battery-powered systems command premium pricing for mobility assistance in spinal cord injury populations. Soft exoskeletons represent the fastest-growing technology category, leveraging fabric-based actuators to serve elderly care applications where rigid frames limit acceptance. AI-driven control systems concentrate margin pools through real-time gait adaptation algorithms that differentiate premium offerings from basic pneumatic units.
The FDA classifies powered exoskeletons as Class II medical devices requiring 510(k) premarket notification, while OSHA workplace guidelines influence industrial adoption thresholds for lifting support applications. ISO 13485 quality management standards govern manufacturing processes for rehabilitation therapy devices sold into European markets under the MDR framework. Stakeholders must monitor reimbursement code expansions for exoskeletal training in outpatient settings, as payer decisions will determine whether clinical volumes scale beyond early-adopter hospital networks.
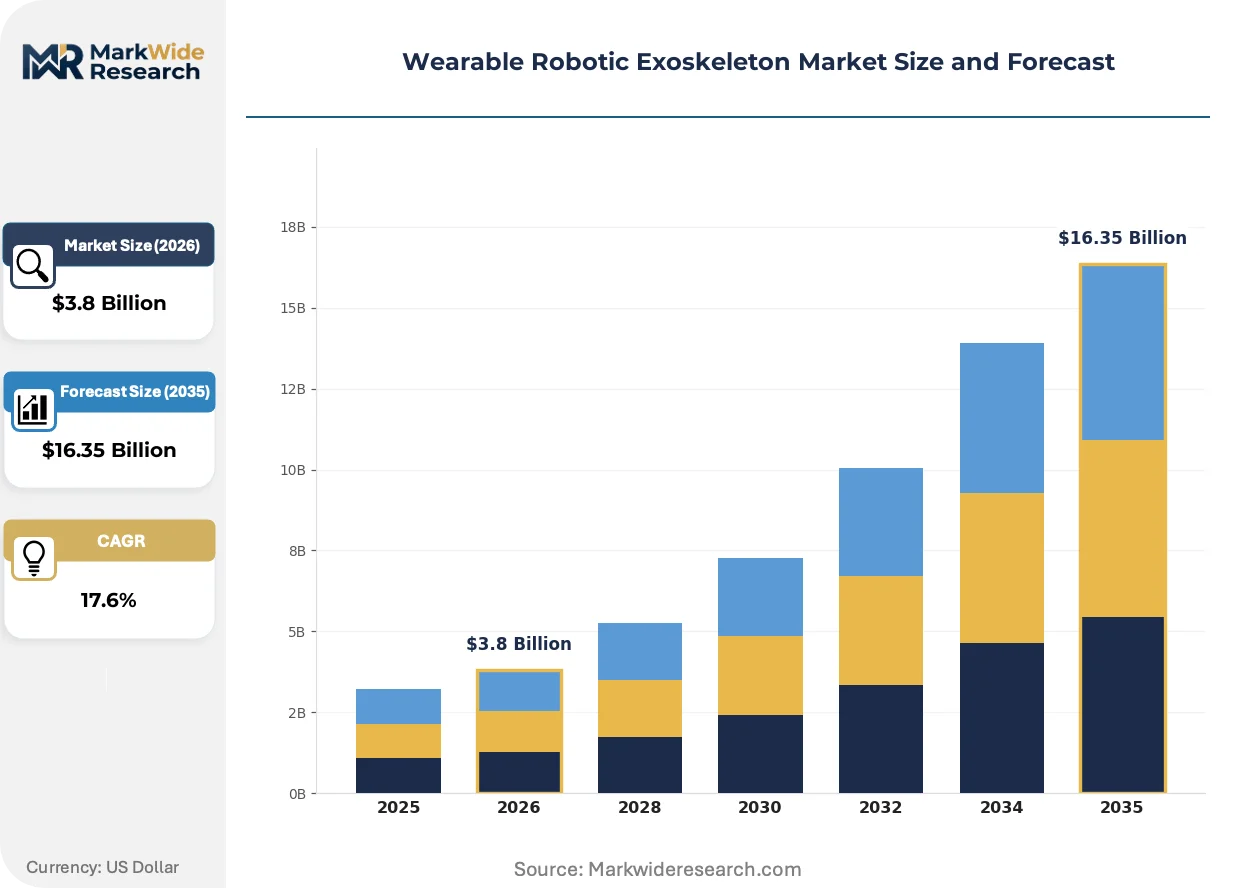
Market Dynamics
The FDA's Class II medical device classification for powered exoskeletons creates a bifurcated competitive landscape where 510(k) clearance separates reimbursable clinical systems from industrial lifting aids lacking therapeutic codes.
Growth Catalysts
- Japan's hospital rehabilitation mandate:METI reimbursement policies for HAL hybrid systems in spinal cord injury therapy expand clinical volumes beyond early-adopter networks.
- ISO 13485 quality frameworks:MDR compliance requirements in European markets accelerate manufacturer consolidation around certified production facilities.
- Automotive assembly strain reduction:BMW and Volkswagen deployment of passive lifting frames in German manufacturing corridors validates industrial ROI metrics for musculoskeletal injury prevention.
Market Restraints
- Lithium-ion battery cost volatility:Active exoskeleton power systems face input price pressure from cathode material supply concentration in Chinese processing facilities.
- Hydraulic actuator maintenance burden:Sarcos Corporation's full-body industrial systems require specialized technician networks unavailable outside major logistics hubs.
- Reimbursement code fragmentation:CMS outpatient therapy coverage gaps limit patient access to FDA-cleared gait training platforms outside inpatient rehabilitation settings.
Strategic Opportunities
- Elderly care soft exoskeleton penetration:Fabric-based actuator systems address acceptance barriers in Japanese home health services where rigid frames restrict daily mobility.
- AI-driven gait adaptation convergence:Real-time neural network control algorithms differentiate premium offerings from basic pneumatic units in clinical rehabilitation.
- OSHA workplace guideline expansion:Lifting support application thresholds create compliance-driven procurement mandates in US distribution and warehousing operations.
Industry Challenges
- Biomechanical engineer talent scarcity:Specialized expertise in human-robot interaction design concentrates in Boston and Pittsburgh academic clusters, constraining manufacturer R&D scaling.
- FDA 510(k) timeline compression:Clinical validation requirements for novel sensor fusion algorithms extend premarket notification review cycles beyond 18 months.
- Legacy EMR integration complexity:Gait training platforms face interoperability friction with Cerner and Epic hospital information systems during therapy documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Robotic Exoskeleton Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active, Passive, Hybrid, Soft Technology: AI-Driven, Pneumatic, Hydraulic, Electric End User: Medical Rehabilitation, Industrial Workers, Military Personnel, Elderly Care Application: Mobility Assistance, Exoskeletal Training, Lifting Support, Rehabilitation Therapy |
| Companies Covered | Sarcos Corporation, Honda Motor Co. Ltd, Cyberdyne Inc., DIH Medical, Ottobock, Ekso Bionics Holdings Inc., Myomo Inc., Comau, ReWalk Robotics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Robotic Exoskeleton Market Emerging Trajectories
Soft material actuation and AI-native control architectures are compressing the performance gap between rigid industrial frames and clinical mobility systems. Three developments dominate vendor roadmaps.
Dielectric elastomer actuators are electrifying the soft exoskeleton category through fabric-based torque generation that eliminates rigid joint linkages. Japanese home health providers pilot these systems for elderly fall prevention where traditional hydraulic frames restrict bathroom navigation. The technology is electrifying acceptance curves in aging-in-place markets previously closed to wearable robotics.
The EU AI Act's risk classification for autonomous movement assistance devices imposes conformity assessment burdens on real-time gait adaptation algorithms. Manufacturers must document training data provenance and decision transparency for systems deployed in European rehabilitation clinics. German hospital procurement committees now require AI Act compliance documentation alongside existing MDR technical files.
Hospital network consolidation is compressing vendor sales cycles toward enterprise framework agreements. Individual rehabilitation department purchases surrender to centralized supply chain decisions at multi-facility health systems. This pattern concentrates contract awards in US markets where HCA and Kaiser Permanente operate standardized device evaluation committees.
Wearable Robotic Exoskeleton Market Segmentation
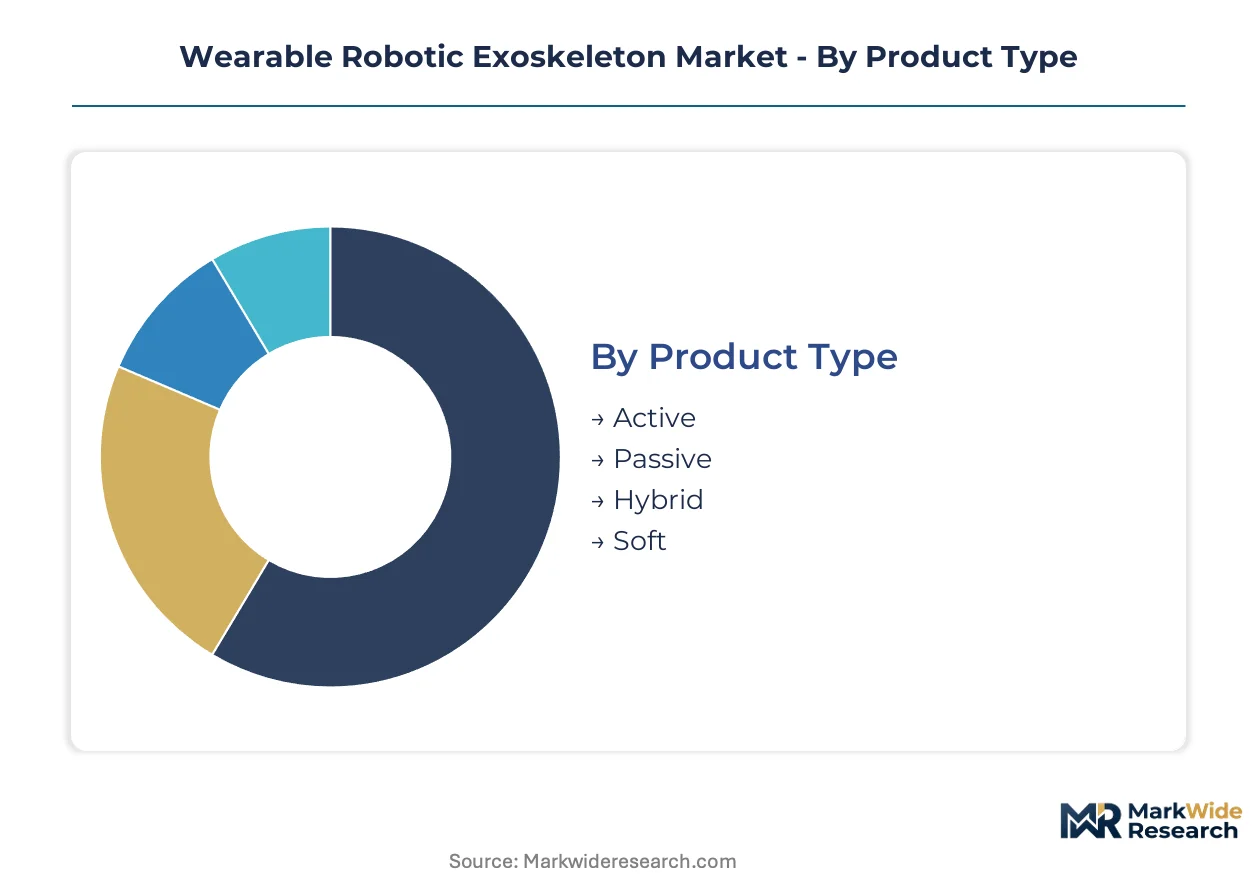
Segmentation in wearable robotic exoskeletons separates reimbursable clinical systems from industrial lifting aids through distinct certification pathways. Each category carries different FDA, MDR, and METI compliance burdens that shape pricing tiers and addressable markets.
Product Type:
FDA Class II 510(k) clearance requirements apply selectively across this category, with powered systems facing premarket notification while passive frames bypass therapeutic device pathways.
- Active:Battery-powered motorized frames with electric or hydraulic actuators deliver continuous torque assistance for spinal cord injury mobility. Demand concentrates in US inpatient rehabilitation hospitals where FDA-cleared devices qualify for CMS reimbursement codes, though outpatient coverage gaps constrain patient access.
- Soft:Fabric-based actuation systems using dielectric elastomers or cable-driven mechanisms eliminate rigid joint structures. Japanese home health providers pilot these for elderly fall prevention where traditional frames restrict bathroom navigation, electrifying acceptance curves in aging-in-place markets.
- Passive:Unpowered mechanical frames relying on springs, counterweights, or elastic elements to redistribute lifting loads. BMW and Volkswagen deploy these in German automotive assembly corridors for musculoskeletal injury prevention without battery maintenance burdens.
- Hybrid:Systems combining powered actuation with passive energy storage elements, typically switching modes based on task demands. METI reimbursement policies in Japan favor these configurations for hospital-based gait training programs.
Leading the category by volume: Active systems. Growing fastest: Soft exoskeletons.
Technology:
Cost tiers stratify sharply here, with AI-native architectures commanding premium pricing against commodity pneumatic units.
- AI-Driven:Real-time neural network control algorithms adapt gait patterns through sensor fusion, differentiating premium clinical offerings. The EU AI Act imposes conformity assessment burdens on these systems for European rehabilitation clinic deployment.
- Electric:Brushless DC motors with harmonic drive gearboxes dominate battery-powered mobility assistance, though lithium-ion cathode material supply concentration in Chinese processing facilities creates input price volatility.
- Hydraulic:High-pressure fluid actuators deliver force density for full-body industrial logistics systems. Sarcos Corporation anchors this tier, though specialized technician network scarcity outside major logistics hubs constrains maintenance scaling.
- Pneumatic:Compressed air or gas-powered muscle-like actuators offer lower cost per degree of freedom. These units sacrifice precision for affordability in entry-level lifting support applications.
Highest margin concentration: AI-Driven. Steepest expansion trajectory: Electric systems.
End User:
Customer type determines procurement channel—health system tender processes versus enterprise safety budgets versus defense acquisition programs.
- Medical Rehabilitation:Hospital-based therapy departments in Japan's aging facilities drive volume through METI-mandated HAL system adoption. FDA 510(k) clearance separates reimbursable platforms from non-clinical devices in US markets.
- Industrial Workers:German automotive assembly lines validate ROI metrics for strain reduction, with OSHA workplace guidelines beginning to shape US distribution and warehousing procurement thresholds.
- Military Personnel:Load carriage and endurance augmentation programs in defense agencies, subject to distinct acquisition timelines and ruggedization specifications separate from commercial medical or industrial standards.
- Elderly Care:Japanese home health services pilot soft exoskeleton acceptance where rigid frames limit daily mobility, addressing aging population caregiver shortage pressures.
Dominant revenue share: Medical Rehabilitation. Gaining share fastest: Elderly Care.
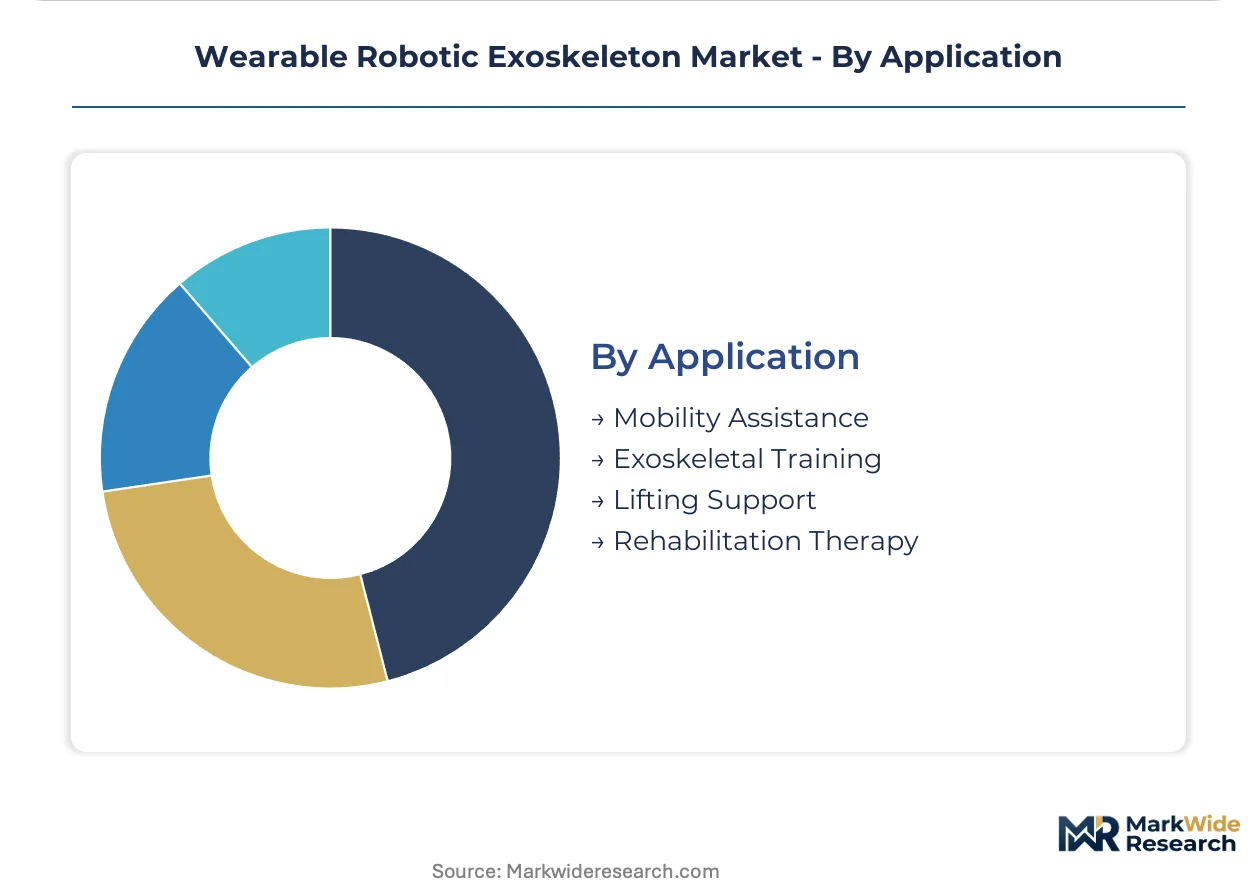
Application:
Maturity curves diverge—some applications carry decades of clinical validation while others emerge from recent OSHA guideline expansions.
- Rehabilitation Therapy:Gait training for spinal cord injury and stroke recovery carries the deepest clinical evidence base. Hospital network consolidation in US markets compresses vendor sales cycles toward enterprise framework agreements with HCA and Kaiser Permanente.
- Lifting Support:Industrial back and shoulder assistance for repetitive material handling tasks. German manufacturing corridors demonstrate validated injury prevention metrics, though hydraulic actuator maintenance burdens constrain deployment outside major logistics hubs.
- Mobility Assistance:Ambulation enablement for paralyzed or severely weakened users. CMS outpatient therapy coverage gaps limit patient access to FDA-cleared platforms outside inpatient rehabilitation settings.
- Exoskeletal Training:Neural pathway retraining protocols combining physical therapy with robotic assistance. Legacy EMR integration friction with Cerner and Epic systems complicates therapy documentation workflows.
Most mature segment: Rehabilitation Therapy. Climbing fastest: Lifting Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pittsburgh anchors the North American exoskeleton R&D corridor through Carnegie Mellon and University of Pittsburgh human-robot interaction labs. This concentration of specialized biomechanical engineering talent constrains manufacturer scaling outside established academic clusters.
United States
FDA 510(k) premarket notification pathways for powered lower-limb devices shape commercial timelines for gait-training platforms. CMS reimbursement code gaps limit patient access outside inpatient rehabilitation settings. The Boston-Worcester corridor concentrates medical device venture capital and early-stage exoskeleton startups.
Germany
BMW and Volkswagen deployment of passive lifting frames in automotive assembly corridors validates industrial ROI metrics for musculoskeletal injury prevention. The EU AI Act imposes conformity assessment burdens on real-time gait adaptation algorithms for rehabilitation clinic deployment. Bavarian manufacturing clusters around Munich and Stuttgart drive procurement of ISO 13485-certified production systems.
Japan
METI reimbursement policies for HAL hybrid systems in spinal cord injury therapy expand clinical volumes beyond early-adopter hospital networks. PMDA regulatory frameworks govern powered exoskeleton classification alongside FDA-aligned technical standards. Tokyo-Osaka hospital rehabilitation departments in aging facilities drive adoption through mandated therapy protocols.
China
NMPA medical device registration requirements for powered rehabilitation systems create parallel certification burdens distinct from FDA or MDR pathways. Lithium-ion cathode material processing concentration in domestic facilities generates input cost volatility for active exoskeleton manufacturers. Shenzhen and Shanghai hardware ecosystems supply electric actuator components to international vendors.
Wearable Robotic Exoskeleton Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent certification pathways. The vendor base stratifies into FDA-cleared medical device specialists, industrial logistics system fabricators, and soft exoskeleton material innovators. Three archetypes dominate: premium active system developers, commodity passive frame manufacturers, and AI-native control algorithm specialists. Consolidation pressures concentrate around M&A activity for 510(k) clearance portfolios and strategic partnerships for dielectric elastomer actuator supply.
Within the premium active system tier, Sarcos Corporation and Ekso Bionics Holdings Inc. exemplify divergent strategic positioning. Cyberdyne Inc. occupies a distinctive geography-first anchor in Japanese hospital networks through METI-aligned reimbursement structures. Among European fabricators, Ottobock represents rehabilitation-focused archetype consolidation, while ReWalk Robotics Inc. and Myomo Inc. sit within the FDA-cleared medical device specialist category. Honda Motor Co. Ltd and Comau exemplify industrial conglomerate diversification into wearable robotics from adjacent automation competencies.
| Leading Market Players |
|---|
| Sarcos Corporation |
| Honda Motor Co. Ltd |
| Cyberdyne Inc. |
| DIH Medical |
| Ottobock |
| Ekso Bionics Holdings Inc. |
| Myomo Inc. |
| Comau |
| ReWalk Robotics Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into lithium-ion cathode processing anchors pricing power for active exoskeleton manufacturers tethered to Chinese supply chains. FDA-cleared medical device producers offset material volatility through premium positioning tied to reimbursement eligibility, while industrial passive frame suppliers compete on volume scale without battery cost exposure.
Pricing Analysis
Outcome-based pricing tied to patient mobility restoration anchors premium tiers for FDA-cleared gait training platforms. Three-tier pricing structure across premium, standard, and economy levels separates AI-driven adaptive systems from basic pneumatic units and commodity passive frames. Cost compression in electric actuator tiers intensifies because cathode material supply concentration limits sourcing alternatives. Hospital procurement committees demonstrate lowest price sensitivity due to reimbursement code coverage, whereas industrial safety managers face capital budget constraints that favor passive frame economics.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States manage hub-and-spoke patterns for ISO 13485-certified production systems. Component sourcing draws from Chinese lithium processing facilities, Japanese precision gearbox manufacturers, and German hydraulic actuator specialists. Single-source vulnerability in rare earth magnet supply creates procurement risk for brushless motor assemblies. Distribution runs through hospital GPO contracts in medical segments and direct OEM relationships in automotive manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is compressing margins across the exoskeleton value chain as manufacturers pursue captive control over AI-native control architectures to escape commodity actuator pricing.
For Market Incumbents: Lock in reimbursement code expansions through CMS outpatient therapy lobbying before emerging soft exoskeleton entrants capture elderly care volume. Deepen backward integration into dielectric elastomer actuator supply to defend margin position against fabric-based system commoditization. FDA 510(k) clearance portfolios represent the priority defensive asset against unregulated industrial lifting aid competitors. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass consolidated hospital supply chain gatekeepers blocking traditional vendor access. Target Japanese home health services as the most penetrable geography given METI-mandated HAL adoption creating infrastructure familiarity. White-space exists in OSHA-compliant warehousing applications where passive frame economics dominate but AI-driven adaptive systems remain unproven. For Investors and Strategic Acquirers: Exit pathways concentrate in medical device conglomerates seeking FDA-cleared rehabilitation portfolios. Five-to-ten-year viability hinges on reimbursement code expansion velocity rather than technology differentiation alone. Acquisition target archetypes include AI-native control algorithm specialists lacking manufacturing scale. The signal to watch is CMS outpatient therapy coverage decisions determining addressable market expansion beyond inpatient rehabilitation settings.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Unlocks CMS reimbursement eligibility for gait training platforms in spinal cord injury populations. |
| AI-Native Control Algorithm Development | Differentiates premium offerings from basic pneumatic units through real-time gait adaptation. |
| Dielectric Elastomer Actuator Supply Partnership | Secures fabric-based torque generation for elderly care soft exoskeleton penetration. |
| Hospital GPO Contract Consolidation | Compresses sales cycles toward enterprise framework agreements with HCA and Kaiser Permanente. |
| OSHA Workplace Guideline Alignment | Creates compliance-driven procurement mandates in US distribution and warehousing operations. |
Methodological Framework
Document review covered FDA 510(k) filings, METI reimbursement policy documents, and ISO 13485 certification registries, complemented by interviews with hospital rehabilitation directors, biomedical engineers, industrial safety managers, and GPO contract specialists. Secondary validation drew from CMS Medicare data, hospital procurement databases, and automotive OEM capex disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing from regulatory filing analysis.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user category, and application maturity. CAGRs were derived from regression analysis of reimbursement expansion timelines and industrial safety regulation adoption patterns. Forecast inputs incorporated lithium-ion battery cost trajectories and AI Act compliance burden estimates for European rehabilitation clinic deployment.
Inputs from FDA premarket notification databases and METI policy releases were available through the study window; gaps in real-time hospital purchasing transaction data introduce uncertainty bands around volume estimates. Forecasts reflect documented assumptions regarding reimbursement code expansion velocity and OSHA guideline implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Food Robotics Market
Robotics and Automation
Global Automotive Gesture Recognition System Market