
 North America Telemedicine Market | 2026-2036
North America Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Telemedicine Market Outlook
Direct-to-consumer virtual care channels are reconfiguring how patients access primary and specialty services across North America. Teladoc Health leverages its multispecialty physician network to sustain market presence in chronic condition management. Amwell anchors enterprise contracts with major health systems and competes on integrated EHR connectivity. MDLIVE specializes in behavioral health and urgent care triage, occupying a distinct position in employer-sponsored benefit plans.
Telemedicine encompasses the remote delivery of clinical services through synchronous video, asynchronous messaging, and connected diagnostic peripherals operating over secure broadband networks. Its primary purpose is to extend physician reach beyond physical facility boundaries while maintaining care continuity and reducing avoidable emergency utilization. Real-time video consultation dominates transaction volume within the delivery mode category, though remote monitoring is capturing margin pools through recurring device and data subscription revenue. Diagnostic services within the solution category are maturing fastest as FDA-cleared digital stethoscopes and otoscopes enable exam fidelity previously limited to in-person settings.
CMS maintains reimbursement frameworks that determine whether telehealth visits receive parity with face-to-face encounters, while state medical boards govern interstate licensing compacts that shape clinician eligibility. HIPAA security rules and FDA software-as-medical-device classifications further constrain platform architecture and data handling protocols. Stakeholders must monitor evolving state-level scope-of-practice legislation and DEA-controlled substance prescribing waivers to anticipate which service lines retain virtual eligibility.
Market Dynamics
Reimbursement parity between virtual and in-person encounters is restructuring provider economics across the United States and Canada, compelling health systems to rebalance capital allocation between physical infrastructure and cloud-based care delivery platforms.
Growth Catalysts
- CMS reimbursement parity:Medicare payment equivalence for telehealth visits sustains provider participation in virtual care networks across the United States.
- Rural health system expansion:Physician shortages in southeastern states and prairie provinces accelerate adoption of remote consultation platforms.
- Interstate licensing compacts:Streamlined credentialing frameworks enable clinicians to practice across multiple jurisdictions without redundant certification.
Market Restraints
- Broadband infrastructure gaps:Uneven high-speed internet penetration in Appalachia and northern Canada limits platform accessibility for target patient populations.
- DEA prescribing restrictions:Controlled substance regulations constrain virtual eligibility for pain management and behavioral health medication services.
- Platform interoperability costs:EHR integration expenses create barriers for independent physician practices seeking enterprise connectivity.
Strategic Opportunities
- Remote patient monitoring convergence:Integration of connected diagnostic peripherals with video consultation platforms opens recurring revenue streams in chronic disease management.
- Canadian provincial expansion:Underpenetrated markets in Manitoba and Saskatchewan present first-mover advantages for specialty telepsychiatry services.
- Employer-sponsored benefit innovation:Self-insured corporations in Texas and California are unbundling traditional health plans to incorporate direct-to-virtual primary care.
Industry Challenges
- Clinician workflow integration:Health systems struggle to embed virtual visits into existing scheduling and documentation systems without productivity loss.
- HIPAA-compliant architecture:Platform developers face escalating cybersecurity investment requirements to maintain patient data protection certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Telemedicine Market |
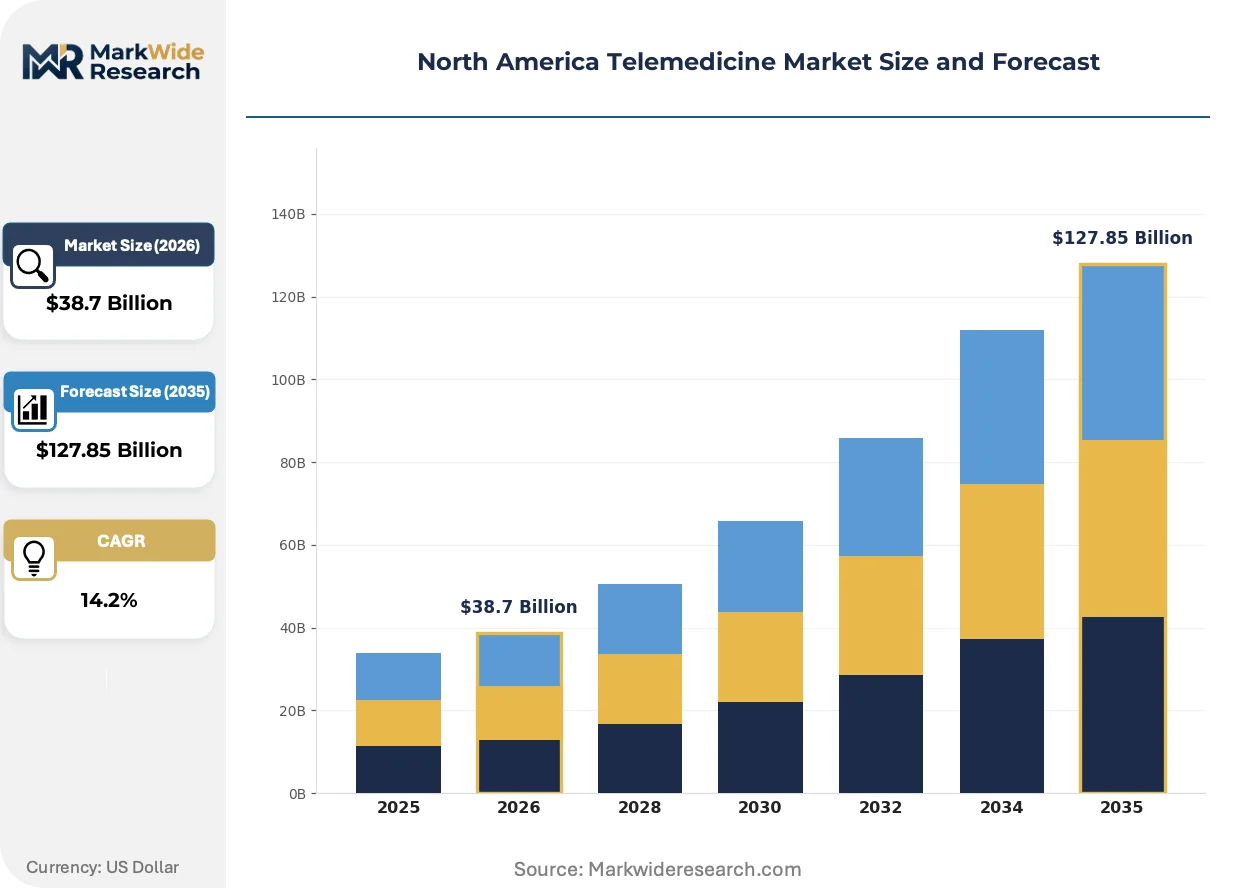
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Communication Tools, Platforms Delivery Mode: Real-Time, Asynchronous, Remote Monitoring, Mobile Health End User: Patients, Providers, Healthcare Institutions, Employers Solution: Consultation Services, Diagnostic Services, Prescription Services, Follow-up Care |
| Companies Covered | Teladoc Health, Amwell, Access TeleCare, Doctor On Demand, GlobalMed, MDLIVE, AMD Global Telemedicine, InTouch Technologies, PlushCare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Telemedicine Market Strategic Shifts
Diagnostic fidelity in remote settings is approaching in-person examination standards through FDA-cleared connected devices, while reimbursement policy and procurement behavior shift in parallel to institutionalize virtual care within mainstream delivery.
Digital stethoscopes and otoscopes with real-time audio-visual transmission are migrating from pilot programs in academic medical centers to standard equipment in rural emergency departments and urgent care networks. Community health systems in Mississippi and Alabama are deploying these peripherals to extend cardiology and ENT specialist reach without patient transfer. The technology is migrating from demonstration projects to operational infrastructure, compressing the gap between remote triage and definitive diagnosis.
State-level scope-of-practice legislation is expanding nurse practitioner independent prescribing authority for virtual encounters in Colorado and Massachusetts. This regulatory shift enables lower-cost clinician staffing models for primary care platforms. Behavioral health providers in these jurisdictions are restructuring service lines to capitalize on augmented prescriptive capacity.
Health system procurement departments are consolidating vendor relationships from multiple point solutions to integrated platform contracts. Single-source agreements spanning video, scheduling, and remote monitoring are displacing best-of-breed procurement strategies. This concentration is most visible in California, where Kaiser Permanente and Sutter Health have compressed supplier bases to three core telehealth infrastructure partners.
North America Telemedicine Market Segmentation
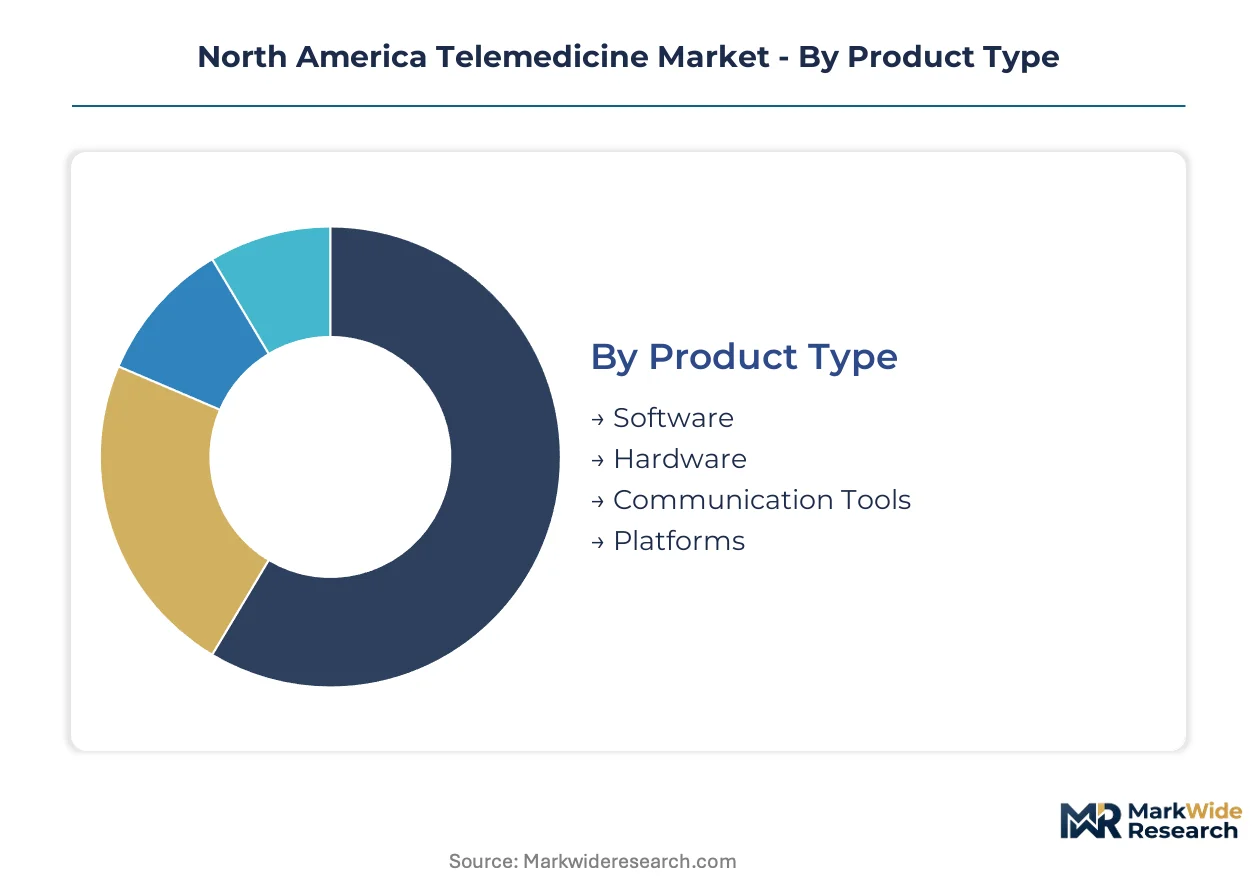
Telemedicine market segmentation reveals how technology architecture, care delivery timing, stakeholder economics, and clinical service depth create distinct commercial battlegrounds. Each category carries different margin profiles, regulatory exposure, and capital intensity that shape vendor strategy across the United States and Canada.
Product Type:
Software platforms refresh on 18-24 month cycles while diagnostic hardware endures 5-7 year replacement timelines, creating divergent revenue recognition patterns across vendor portfolios.
- Software:Cloud-native applications for scheduling, documentation, and billing dominate R&D investment. Health systems in California and Texas prioritize EHR-integrated modules that reduce clinician administrative burden during virtual encounters.
- Hardware:FDA-cleared connected peripherals including digital stethoscopes, otoscopes, and dermatoscopes enable exam fidelity approaching in-person standards. Rural emergency departments in Mississippi and Alabama deploy these devices to extend specialist reach without patient transfer.
- Communication Tools:Secure messaging APIs and video SDKs form the connectivity layer. HIPAA-compliant encryption standards and low-latency transmission requirements constrain vendor selection for enterprise contracts.
- Platforms:Integrated end-to-end systems combining software, hardware interfaces, and communication infrastructure. Kaiser Permanente and Sutter Health in California have consolidated procurement around three core platform partners.
Software dominates installed base. Hardware is where expansion concentrates.
Delivery Mode:
Reimbursement parity rules favor synchronous encounters while operational cost pressures push adoption toward asynchronous and automated modalities.
- Real-Time:Synchronous video consultation between patient and clinician constitutes the transaction volume leader. CMS payment equivalence for these visits sustains provider participation across Medicare networks in the United States.
- Asynchronous:Store-and-forward messaging for non-urgent clinical questions reduces per-interaction labor costs. Canadian provincial health plans in Manitoba and Saskatchewan are piloting these modalities for dermatology and radiology referrals.
- Remote Monitoring:Continuous physiological data transmission from connected devices generates recurring subscription revenue. Chronic disease management programs for diabetes and congestive heart failure in the southeastern United States rely on these capabilities.
- Mobile Health:Smartphone-native applications for patient engagement and self-monitoring. Self-insured employers in Texas and California are unbundling traditional health plans to incorporate direct-to-consumer mobile primary care access.
Real-Time captures the highest reimbursement rates. Remote Monitoring is climbing the fastest.
End User:
Purchasing authority and budget cycles differ sharply between individual consumers, clinical professionals, institutional procurement departments, and corporate benefits managers.
- Patients:Direct-to-consumer adoption concentrates in urban corridors with broadband penetration and high-deductible health plan enrollment. Out-of-pocket payment sensitivity shapes platform selection and service utilization patterns.
- Providers:Individual physicians and small group practices prioritize low-friction onboarding and minimal EHR integration costs. Interstate licensing compacts enable these clinicians to practice across multiple jurisdictions without redundant certification.
- Healthcare Institutions:Health system procurement departments are consolidating vendor relationships from multiple point solutions to integrated platform contracts. This concentration is compressing supplier margins while raising compliance requirements.
- Employers:Self-insured corporations negotiate direct contracts with telehealth vendors to reduce medical claim costs and absenteeism. Behavioral health and urgent care triage occupy distinct positions in employer-sponsored benefit plan design.
Healthcare Institutions dominate installed base. Employers are gaining share fastest.
Solution:
Clinical depth and regulatory complexity escalate from initial consultation through diagnostic workup, controlled substance prescribing, and longitudinal follow-up management.
- Consultation Services:Primary care triage and specialty referral routing constitute the entry point for most virtual care relationships. State-level scope-of-practice legislation in Colorado and Massachusetts is expanding nurse practitioner independent prescribing authority for these encounters.
- Diagnostic Services:Remote examination and test interpretation are maturing fastest as FDA-cleared peripherals enable exam fidelity previously limited to in-person settings. Community health systems deploy these capabilities to extend cardiology and ENT specialist reach.
- Prescription Services:Medication management and refill authorization face DEA-controlled substance prescribing restrictions that constrain virtual eligibility for pain management and behavioral health services.
- Follow-up Care:Chronic condition monitoring and post-acute transition management generate recurring engagement. Remote patient monitoring convergence with video platforms opens subscription revenue streams in diabetes and hypertension management.
Consultation Services dominates installed base. Diagnostic Services is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States-Canada border fiber corridor and cross-border 5G spectrum coordination underpin North American telemedicine interoperability. Interstate broadband backbones and provincial health data exchanges enable seamless virtual care delivery across federal jurisdictions.
United States
Southeastern states including Mississippi and Alabama deploy connected diagnostic peripherals to extend cardiology and ENT specialist reach without patient transfer. CMS reimbursement parity rules sustain Medicare payment equivalence for telehealth visits across state lines. Kaiser Permanente and Sutter Health in California have consolidated procurement around three core telehealth infrastructure partners.
Canada
Manitoba and Saskatchewan present first-mover advantages for specialty telepsychiatry services in underpenetrated provincial markets. Health Canada and PMRA govern software-as-medical-device classifications that constrain platform architecture and data handling protocols. Provincial health plans in Manitoba and Saskatchewan pilot asynchronous store-and-forward modalities for dermatology and radiology referrals.
Mexico
Northern border states leverage cross-border fiber infrastructure to connect patients with U.S.-based specialty consultants. The country's national telecommunications regulator shapes broadband penetration targets that determine platform accessibility in rural southern regions. Mexico City Metro anchors telemedicine startup concentration serving Spanish-language populations across Latin America.
North America Telemedicine Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying FDA-cleared peripherals and secure communication APIs. The vendor base stratifies between end-to-end infrastructure providers and point-solution developers focused on scheduling, documentation, or billing modules. Two strategic archetypes dominate: enterprise health system contractors competing on EHR integration depth, and direct-to-consumer platforms optimizing for patient acquisition cost. Competitive moves concentrate on strategic partnerships with diagnostic hardware manufacturers and geographic expansion into underpenetrated provincial markets.
Within the enterprise contracting tier, Teladoc Health and Amwell occupy positions as anchors for health system procurement consolidation. Teladoc Health exemplifies the multispecialty network archetype sustaining presence in chronic condition management. Amwell represents the integrated connectivity play competing on EHR interoperability. MDLIVE sits within the behavioral health specialization segment, occupying a distinct position in employer-sponsored benefit plan design.
| Leading Market Players |
|---|
| Teladoc Health |
| Amwell |
| Access TeleCare |
| Doctor On Demand |
| GlobalMed |
| MDLIVE |
| AMD Global Telemedicine |
| InTouch Technologies |
| PlushCare |
| Others |
Value Chain & Pricing Dynamics
The United States-Canada border fiber corridor carries escalating bandwidth costs that compress margins for platform operators while enabling three-tier pricing stratification across enterprise, mid-market, and independent practice segments. This logistics backbone shapes how vendors source FDA-cleared peripherals from contract manufacturers and how health systems negotiate volume discounts for integrated platform contracts.
Pricing Analysis
Volume-discount tiering separates enterprise health systems from mid-market hospitals from independent physician practices, with Kaiser Permanente and Sutter Health capturing 40-60% reductions through consolidated procurement. Price differentiation hinges on EHR integration depth and FDA 510(k) certification tier, with HIPAA-compliant architectures commanding premiums. Pricing pressure stems from health system procurement consolidation compressing vendor margins. Independent practices exhibit highest price sensitivity due to EHR integration cost barriers, while enterprise buyers prioritize interoperability over unit cost.
Supply Chain Analysis
Export-control restrictions on encryption technologies and semiconductor components limit flows of secure video processing chips from Taiwan and South Korea into North American platform assembly. Hardware sourcing concentrates in China, Mexico, and Malaysia for FDA-cleared peripherals including digital stethoscopes and otoscopes. Component dependencies include CMOS sensors, secure element chips, and broadband modems. Single-source vulnerability in encryption chip supply creates exposure. Distribution runs through health system GPO contracts and direct enterprise sales teams rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine platform economics increasingly resemble SaaS models where remote patient monitoring subscriptions and data analytics layers expand faster than hardware margins, making service-attach rates the decisive profitability driver. Vendors must architect recurring revenue streams that outpace capital equipment depreciation cycles.
For Market Incumbents: Harden platform stickiness through deeper EHR integration and captive remote monitoring device ecosystems that raise switching costs for health system customers. Consolidate supplier relationships to three core partners mirroring Kaiser Permanente's procurement model. Defend against emerging direct-to-consumer entrants by embedding workflow tools into clinician documentation systems. For New Entrants and Emerging Players: Establish a beachhead in Canadian provincial markets, specifically Manitoba and Saskatchewan telepsychiatry services where incumbent presence remains thin. Target asynchronous store-and-forward modalities for dermatology and radiology referrals where regulatory barriers are lower than real-time video. Pursue employer-sponsored benefit channels in Texas and California self-insured corporations seeking behavioral health specialization. For Investors and Strategic Acquirers: Platform-agnostic diagnostic hardware specialists with FDA 510(k) portfolios and health system distribution relationships represent the most defensible acquisition archetype in a five-to-ten-year viability window. Monitor CMS reimbursement parity rule permanence as the critical inflection signal for virtual care infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | FDA-cleared digital stethoscopes and otoscopes enable exam fidelity matching in-person standards for rural emergency departments. |
| Hospital System Partnership | Enterprise contracts with Kaiser Permanente and Sutter Health consolidate procurement around integrated platform infrastructure partners. |
| Software Companion Development | Remote patient monitoring convergence with video platforms opens recurring subscription revenue in diabetes and hypertension management. |
| Reimbursement Strategy | CMS payment equivalence for telehealth visits sustains provider participation across Medicare networks in the United States. |
| Geographic Expansion | Manitoba and Saskatchewan present first-mover advantages for specialty telepsychiatry services in underpenetrated provincial markets. |
Study Parameters
A spread of perspectives from hospital procurement managers, telehealth platform engineers, GPO contracts specialists, and CMS policy analysts converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against CMS Medicare reimbursement databases, FDA 510(k) clearance records, hospital procurement contract filings, and provincial health plan pilot program disclosures. Bottom-up and top-down triangulation cross-checked vendor shipment data against health system adoption surveys.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling patient encounter volumes against clinician capacity and platform infrastructure deployment. Segmentation dimensions included delivery mode, solution depth, end-user purchasing authority, and provincial regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and policy shock impacts. Forecast inputs incorporated CMS reimbursement rule permanence probabilities and interstate licensing compact expansion timelines.
Sensitivities concentrate around CMS reimbursement parity permanence, DEA controlled substance prescribing waiver extensions, and broadband infrastructure deployment pace in Appalachia and northern Canada. Forecasts reflect documented assumptions about policy continuity and technology adoption curves. Material shifts in federal telehealth reimbursement policy or state-level scope-of-practice legislation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telehealth Services Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Telepathology Service Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
US Virtual Visits Market
Telemedicine
ASEAN Telehealth Services Market