
 Telecom Transformers Market | 2026-2036
Telecom Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Transformers Market Analytics
Specialized magnetics engineering talent is bifurcating between legacy power distribution and telecom-specific design, constraining R&D velocity for next-generation units. Schneider Electric leverages its integrated energy management portfolio to anchor European supply relationships for data center operators. Siemens sustains technology leadership through deep investment in dry-type insulation systems for indoor telecom installations. ABB competes aggressively on modular platform architectures that slash commissioning timelines for 5G base station deployments.
Telecom transformers are electromagnetic devices engineered to step voltage levels for reliable power delivery to communication infrastructure, typically operating at frequencies from 50 Hz to 400 Hz with insulation classes rated up to 220°C for dry-type designs. Their primary commercial purpose centers on protecting sensitive network equipment from voltage transients while maintaining power quality across distributed antenna systems and central office facilities. Three-phase transformers dominate volume procurement for macro cell towers and central offices where load density justifies polyphase distribution, while smart transformers represent the fastest-expanding technology segment as remote monitoring capabilities become standard in utility-telecom hybrid networks. Dry-type installations command premium positioning in urban 5G small cell deployments where fire safety codes restrict liquid-immersed alternatives in underground vaults and building basements.
The EU Ecodesign Directive and REACH chemical compliance frameworks mandate reduced losses and restricted insulating fluid compositions, forcing redesign cycles across European supply chains. The US Department of Energy efficiency standards and FCC equipment authorization requirements shape product roadmaps for units serving domestic wireless infrastructure. India's BIS certification and CEA technical standards create formal entry barriers that favor established manufacturers with local testing capabilities. Stakeholders must monitor evolving grid interconnection standards as telecom operators increasingly source power directly from renewable microgrids rather than traditional utility feeds.
Market Dynamics
5G network densification is compressing transformer procurement cycles as telecom operators race to power millions of small cell installations, forcing manufacturers to abandon legacy lead times and adopt modular platform architectures.
Growth Catalysts
- BharatNet Rural Broadband:India's national digital inclusion initiative is driving large-scale procurement of distribution-class transformers for telecom infrastructure in underserved districts.
- EU Ecodesign Efficiency Mandates:Loss reduction requirements under this directive are accelerating replacement of aging units with smart transformer technologies across European utility-telecom hybrid networks.
- Dry-Type Insulation Systems:Urban fire safety codes restricting liquid-immersed equipment in underground vaults are elevating demand for cast-resin designs in 5G small cell deployments.
Market Restraints
- Copper and Grain-Oriented Steel Volatility:Raw material price swings compress transformer margins and complicate long-term contract pricing for manufacturers serving capital-constrained telecom operators.
- Specialized Magnetics Talent Scarcity:The bifurcation of engineering expertise between legacy power distribution and telecom-specific design constrains R&D velocity for next-generation units.
- REACH Chemical Compliance:Restricted insulating fluid compositions under this framework force costly redesign cycles across European supply chains.
Strategic Opportunities
- Renewable Microgrid Integration:Telecom operators sourcing power directly from solar and wind installations require transformers engineered for bidirectional power flow and grid-forming inverters.
- Remote Monitoring Capability Standardization:Smart transformers with embedded sensors and edge analytics represent white space as utilities and telecoms converge on hybrid network architectures.
- India BIS Certification Barriers:Formal entry requirements favor established manufacturers with local testing capabilities, creating defensive moats for compliant suppliers.
Industry Challenges
- Grid Interconnection Standard Evolution:Divergent technical requirements across utility territories complicate product certification and delay commissioning timelines for multi-site 5G rollouts.
- Legacy Central Office Retrofit Complexity:Aging facilities with space-constrained vaults demand custom transformer geometries that strain manufacturing flexibility and extend engineering lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Transformers Market |
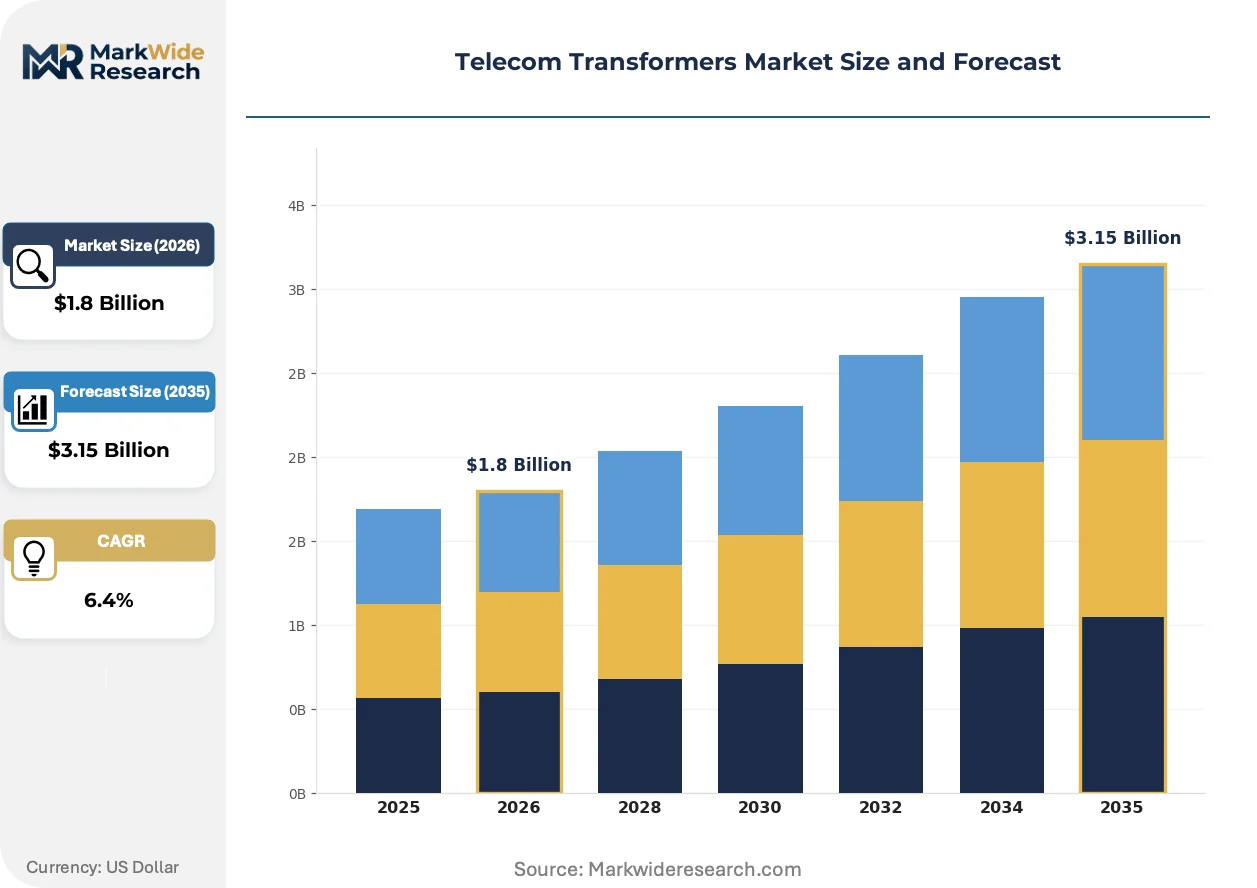
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Transformers, Three-Phase Transformers, Distribution Transformers, Isolation Transformers Technology: Conventional Transformers, Smart Transformers, Liquid-Immersed Transformers, Dry-Type Transformers End User: Telecom Operators, IT Service Providers, Data Center Operators, Network Equipment Manufacturers Installation: Indoor Installation, Outdoor Installation, Compact Installation, Modular Installation |
| Companies Covered | Schneider Electric, Siemens, ABB, General Electric, Eaton, Mitsubishi Electric, Toshiba, Hitachi, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Transformers Market Evolving Landscape
Transformer engineering is pivoting from commodity hardware toward intelligent power nodes as telecom infrastructure converges with utility distribution systems and digital monitoring becomes non-negotiable.
Amorphous metal core technology is bifurcating efficiency performance in distribution transformers. Telecom operators with sustainability mandates specify these cores for no-load loss reduction in always-on base station power supplies. The technology is bifurcating procurement specifications between premium efficiency tiers and standard offerings.
REACH chemical restrictions on mineral oil insulating fluids are forcing accelerated adoption of ester-based and dry-type alternatives across European supply chains. Manufacturers serving indoor telecom installations face compressed redesign timelines to maintain CE marking compliance. Data center operators and urban 5G deployers are absorbing cost premiums for fire-safe cast-resin units.
Telecom procurement departments are consolidating supplier relationships around integrated energy management portfolios rather than discrete transformer transactions. Equipment vendors bundling transformers with power distribution units and remote monitoring software are displacing standalone component suppliers. This concentration is most visible in Germany and the Netherlands where data center operators pursue single-source accountability for critical infrastructure uptime.
Telecom Transformers Market Segmentation
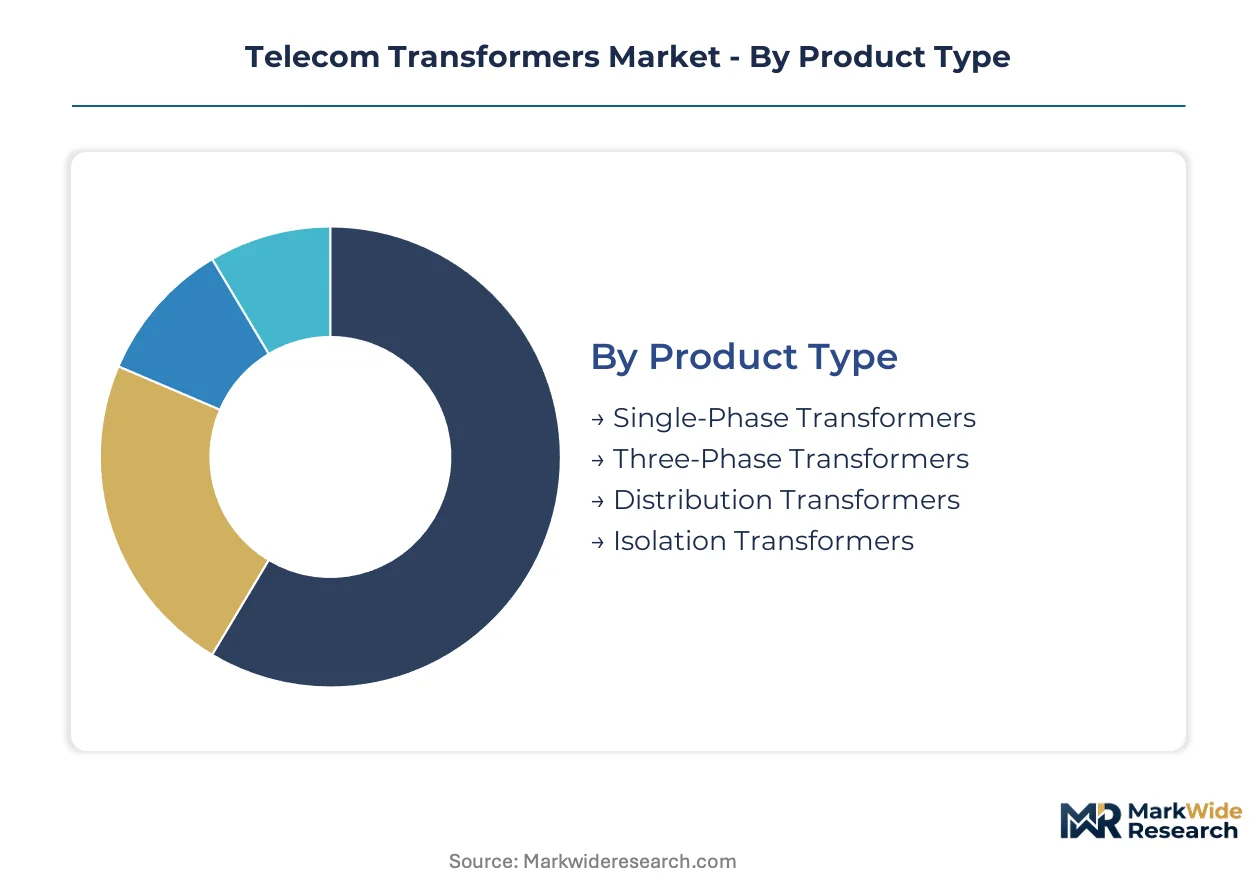
Telecom transformer procurement patterns diverge sharply across product architectures and deployment contexts. Each segment carries distinct technical specifications, regulatory footprints, and margin structures that reshape supplier positioning.
Product Type:
Domestic demand concentrates on utility-grade units for national broadband programs, while export flows favor compact designs for dense urban 5G deployments.
- Three-Phase Transformers:Polyphase electromagnetic units handle higher load densities across macro cell towers and central office facilities. India's BharatNet rural broadband initiative is driving large-scale procurement of these distribution-class units for telecom infrastructure in underserved districts.
- Distribution Transformers:Step-down units engineered for medium-voltage-to-low-voltage conversion at network edge points. European utility-telecom hybrid networks under EU Ecodesign efficiency mandates are accelerating replacement of aging units with smart transformer technologies.
- Single-Phase Transformers:Compact units serving low-power remote radio heads and small cell installations where load profiles justify simpler winding configurations.
- Isolation Transformers:Specialized magnetics providing galvanic separation for sensitive network equipment protection against voltage transients and ground loop interference.
Three-phase units hold the largest share; momentum sits with distribution transformers as grid-telecom convergence accelerates.
Technology:
Cost tiers separate legacy commodity hardware from premium intelligent systems with embedded monitoring capabilities.
- Smart Transformers:Intelligent power nodes integrating sensors, edge analytics, and remote monitoring for predictive maintenance. Telecom operators sourcing power directly from renewable microgrids require these units engineered for bidirectional power flow and grid-forming inverters.
- Dry-Type Transformers:Cast-resin or vacuum-pressure-impregnated insulation systems eliminating liquid fire hazards. Urban fire safety codes in Germany and the Netherlands restricting liquid-immersed equipment in underground vaults are elevating demand for these designs in 5G small cell deployments.
- Conventional Transformers:Standard electromagnetic designs without digital monitoring, dominating price-sensitive procurement in emerging markets.
- Liquid-Immersed Transformers:Mineral oil or ester-filled units offering superior thermal performance for high-load outdoor installations, facing REACH chemical compliance redesign pressures.
Conventional technology still dominates unit volumes; dry-type systems are expanding most quickly as indoor deployment accelerates.
End User:
Customer type determines specification stringency, with data center operators demanding integrated energy management portfolios.
- Data Center Operators:Hyperscale and colocation facilities requiring high-reliability power conditioning with redundant transformer configurations. These buyers are consolidating supplier relationships around integrated energy management portfolios rather than discrete transformer transactions.
- Telecom Operators:Wireless carriers and wireline incumbents powering base stations, central offices, and distributed antenna systems. 5G network densification is compressing transformer procurement cycles as these operators race to power millions of small cell installations.
- IT Service Providers:Managed infrastructure operators with standardized specifications across multi-tenant facilities.
- Network Equipment Manufacturers:Original equipment manufacturers integrating transformers into packaged power systems for resale to carriers.
Telecom operators command the largest procurement volumes; data center operators are gaining share fastest as cloud infrastructure investment outpaces traditional network buildouts.
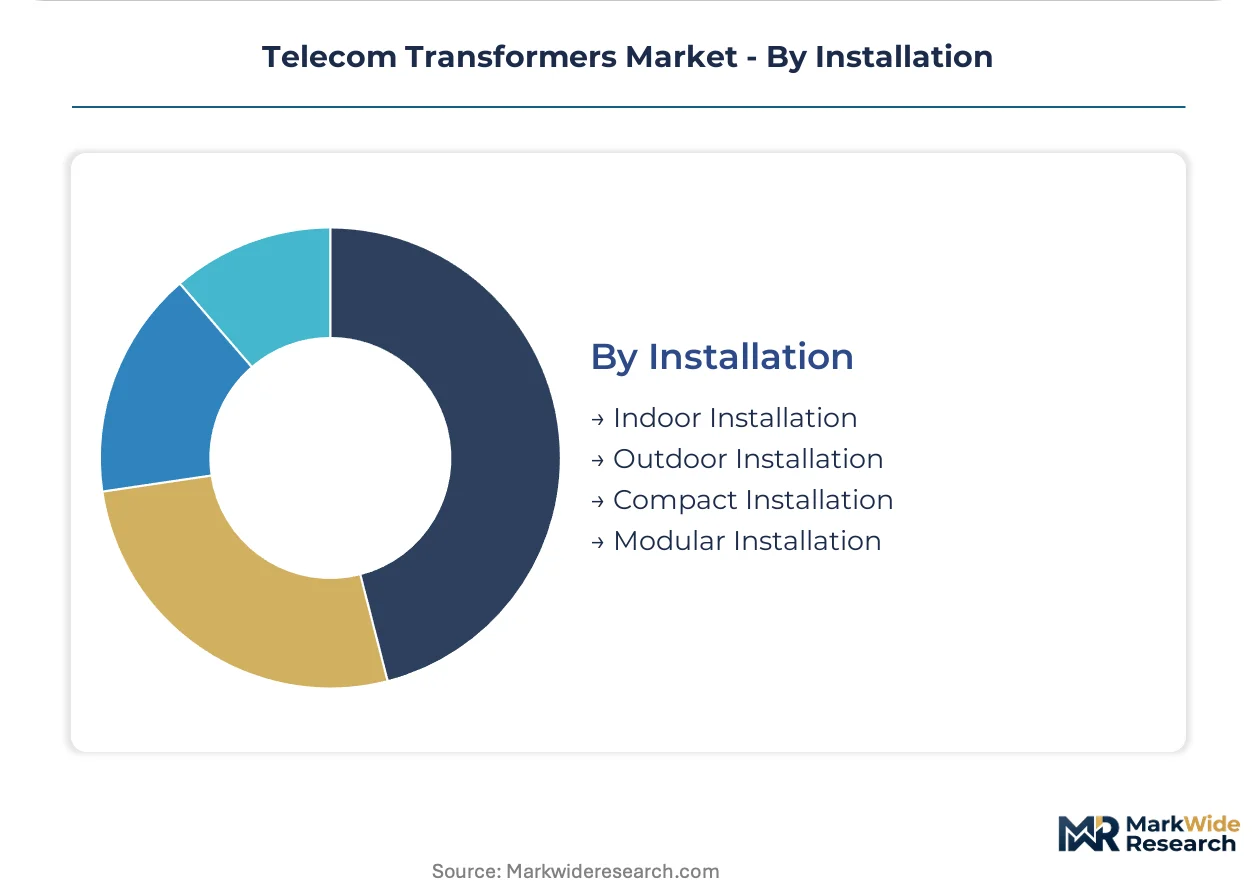
Installation:
Volume concentration tracks urbanization patterns, with compact and modular formats displacing conventional footprints in space-constrained environments.
- Indoor Installation:Building-integrated deployments in basements, vaults, and equipment rooms requiring fire-safe insulation. REACH chemical restrictions on mineral oil are forcing accelerated adoption of ester-based and dry-type alternatives for these European installations.
- Modular Installation:Pre-fabricated skid-mounted or containerized systems enabling rapid commissioning. Manufacturers serving multi-site 5G rollouts face divergent grid interconnection standards across utility territories that complicate product certification for these standardized formats.
- Outdoor Installation:Pole-mounted or pad-mounted units exposed to environmental stresses, dominating rural and suburban macro cell deployments.
- Compact Installation:Reduced-footprint designs for space-constrained legacy central office retrofits where aging facilities demand custom transformer geometries.
Outdoor installation retains the largest share; modular formats are climbing the fastest as deployment velocity becomes critical competitive terrain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the Netherlands exceeds that in India by substantial margins, reflecting divergent regulatory stringency and buyer sophistication across these telecom transformer markets.
United States
FCC equipment authorization requirements and DOE efficiency standards compress product development timelines for manufacturers serving domestic wireless infrastructure. Data center operators in Northern Virginia and Dallas-Fort Worth consolidate procurement around integrated energy management portfolios. Grid interconnection standards vary across utility territories, complicating multi-site 5G rollout certification.
Germany
Urban fire safety codes in Berlin and Frankfurt restrict liquid-immersed equipment in underground vaults, elevating demand for cast-resin dry-type designs. EU Ecodesign Directive loss reduction mandates accelerate smart transformer replacement cycles. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate engineering talent for next-generation magnetics development.
India
BharatNet rural broadband procurement drives large-scale distribution-class transformer demand across underserved districts. BIS certification and CEA technical standards create formal entry barriers favoring established manufacturers with local testing capabilities. Manufacturing activity concentrates in Maharashtra and Gujarat, where domestic capacity expansion addresses import substitution priorities.
China
MIIT equipment standards and GB certification frameworks shape product specifications for domestic 5G infrastructure deployment. Yangtze River Delta and Pearl River Delta industrial bases supply compact transformer designs for dense urban small cell installations. State Grid integration requirements influence bidirectional power flow engineering for renewable microgrid applications.
Japan
METI efficiency regulations and JIS standards govern transformer performance specifications for telecom and data center applications. Tokyo and Osaka metropolitan areas demand space-optimized designs for legacy central office retrofits. Kansai region manufacturers specialize in high-reliability insulation systems for indoor installations.
Telecom Transformers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated energy management portfolios commanding premium positioning against commodity component suppliers. The vendor base stratifies across three tiers: multinational conglomerates with full infrastructure portfolios, specialized magnetics manufacturers with deep insulation expertise, and regional fabricators competing on price and local certification access. Dominant competitive moves include portfolio bundling of transformers with power distribution and monitoring systems, plus geographic expansion through local certification partnerships.
Within the multinational conglomerate tier, Schneider Electric, Siemens, and ABB occupy positions defined by integrated energy management capabilities rather than discrete component supply. Schneider Electric anchors European supply relationships through its full infrastructure portfolio. Siemens exemplifies technology leadership via dry-type insulation specialization. ABB represents modular platform architectures that address compressed 5G deployment timelines.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| General Electric |
| Eaton |
| Mitsubishi Electric |
| Toshiba |
| Hitachi |
| Nexans |
| Others |
Value Network & Pricing Analysis
Fourteen-week engineering lead times for configured-to-order distribution transformers concentrate pricing power with manufacturers holding modular platform capabilities, while standard unit inventories of sixty days anchor commodity-tier competition around copper and grain-oriented steel cost pass-through mechanisms.
Pricing Analysis
The customization-premium spread separates configured-to-order transformer specifications from standard catalog offerings by a substantial margin, with bespoke winding configurations and compact geometries for legacy central office retrofits commanding substantial premiums. Three-tier pricing structure across premium smart transformer, standard dry-type, and economy conventional levels reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because raw material volatility compresses margins on long-term contracts with capital-constrained telecom operators. Data center operators demonstrate the lowest price sensitivity as they consolidate procurement around integrated energy management portfolios, while rural broadband procurement under India's BharatNet program exhibits acute price sensitivity.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement for copper and grain-oriented electrical steel, with manufacturers maintaining ninety-day inventory buffers against commodity volatility rather than just-in-time exposure. Manufacturing concentration centers on China, India, and Germany for core lamination and winding operations. Supply chains draw from Chilean copper concentrate, Ukrainian grain-oriented steel, and Japanese amorphous metal ribbon feedstocks. Single-source vulnerability in grain-oriented steel from integrated steel mills creates structural risk for European manufacturers facing REACH compliance redesign cycles. Distribution runs through direct OEM relationships for large telecom operators and electrical distributors serving fragmented small cell deployment contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecom transformer procurement is shifting toward platform-economics logic as energy management software converges with hardware specifications, with interoperability between utility SCADA systems and telecom network operations centers becoming the decisive ecosystem battleground.
For Market Incumbents: Compound technology leadership in dry-type insulation systems through backward integration into cast-resin formulation capabilities, defending against modular platform competitors by embedding predictive maintenance algorithms that lock in multi-year service contracts. Capacity addition in Maharashtra and Gujarat addresses India's BIS certification barriers while insulating against import substitution pressures.
For New Entrants and Emerging Players: BIS certification fast-track partnerships with established testing laboratories in India unlock the most penetrable geography, where BharatNet rural broadband procurement concentrates volume in distribution-class units with standardized specifications. White-space targets include compact installation formats for legacy central office retrofits and smart transformer remote monitoring bundles for renewable microgrid integration.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core power distribution assets, particularly European manufacturers with stranded mineral oil transformer product lines facing REACH compliance obsolescence. Long-term viability hinges on software-defined service revenue attachment rates. The signal to watch is utility-telecom hybrid network procurement consolidation around single-source accountability models.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Transformer Platform Integration | Embedded sensors and edge analytics enable predictive maintenance revenue streams across EU utility-telecom hybrid networks. |
| Backward Integration into Core Materials | Captive supply of amorphous metal ribbon insulates margin compression from grain-oriented steel volatility. |
| Modular Installation Format Expansion | Pre-fabricated skid-mounted systems compress commissioning timelines for multi-site 5G densification programs. |
| Renewable Microgrid Certification Investment | Bidirectional power flow engineering unlocks telecom operator procurement outside traditional utility interconnection. |
| India BIS Testing Partnership | Local certification capabilities create defensive moats against import competition in BharatNet rural broadband procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with telecom network planning executives, transformer procurement managers at data center operators, power distribution engineers at utility-telecom hybrid networks, and magnetics R&D directors at component manufacturers. Secondary validation drew from BIS certification registries, CEA technical standard filings, EU Ecodesign Directive compliance databases, and FCC equipment authorization records. Bottom-up unit shipment estimates triangulated against top-down infrastructure capex allocations across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product architecture, insulation technology, end-user type, and installation format dimensions. CAGRs were derived from infrastructure deployment timelines for 5G densification and rural broadband programs, with cross-referencing against raw material cost trajectories and regulatory compliance cycle impacts. Industry-specific forecast inputs included utility interconnection standard evolution and telecom operator energy procurement centralization trends.
The analysis sits within stated boundaries; outcomes outside sustained 5G capital expenditure commitment and stable copper price bands would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology substitution rates. Revision becomes warranted when utility-telecom organizational convergence crosses operational integration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Infant Fever Stickers Market
Others
Lined Tank Market
Others
Tobacco Packaging Market
Others
North America Video Conferencing Hardware Market
Others
Defense Optronics Market
Others
Africa Cotton Market
Others
Fluid Dispensing Systems Market
Others
Diamond Mining Market
Others
Football Sportswear Market
Others
5G Smartphone Market
Others
Eye Balm Market
Others
Hybrid Switchgear Market
Others
Nuclear Power Cables Market
Others
Latin America IT Device Market
Others
Coalescing Filter Market
Others
Computer on Module Market