
 5G Smartphone Market | 2026-2036
5G Smartphone Market Size, Share, and Industry Trends Forecast 2026-2036
5G Smartphone Market Intelligence
3GPP Release 17 certification is unwinding the competitive field for premium 5G handset manufacturers, forcing smaller brands toward sub-6 GHz-only configurations. Samsung Electronics Co. Ltd. leverages in-house modem and display integration to sustain margin control across the high-end tier. Apple Inc. anchors North American premium demand through carrier-locked distribution and proprietary silicon roadmaps. Xiaomi Corporation competes aggressively on price-performance ratios in mid-range dual-band segments across emerging markets.
A 5G smartphone integrates a cellular radio capable of operating in sub-6 GHz and/or mmWave frequency bands, paired with antenna arrays, baseband processors, and power management systems designed for gigabit-throughput connectivity and sub-10 millisecond latency. Its primary commercial purpose is to deliver enhanced mobile broadband, ultra-reliable low-latency communication, and massive machine-type connectivity for consumers and enterprise endpoints. The high-end product type captures the majority of industry profit pools, while foldable variants represent the fastest-growing hardware form factor despite manufacturing yield challenges. Sub-6 GHz technology dominates unit volumes due to broader geographic coverage and lower infrastructure deployment costs, whereas mmWave configurations concentrate in dense urban corridors where spectrum availability supports peak throughput claims.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct radio equipment authorization frameworks that dictate band support, power emission limits, and SAR testing protocols, directly shaping which silicon and antenna configurations gain market access. REACH and RoHS compliance in the European Union further constrain material selection for printed circuit boards and battery chemistries, raising compliance costs for non-EU manufacturers. Stakeholders must monitor spectrum reallocation decisions and evolving cybersecurity certification mandates as the primary variables that will determine which regional variants justify dedicated production lines.
Market Dynamics
Enterprise fleet procurement and mid-band spectrum reallocation are compressing handset refresh cycles while fragmenting silicon sourcing strategies across competing frequency certifications.
Growth Catalysts
- Logistics fleet digitization:Last-mile delivery operators in the United States are mandating 5G-enabled telematics for real-time route optimization and predictive maintenance scheduling.
- MIIT infrastructure mandates:China's accelerated base station deployment creates captive demand for domestically certified sub-6 GHz chipsets and antenna modules.
- Release 17 certification:The 3GPP framework is expanding addressable use cases for fixed wireless access and industrial IoT, pulling premium handset feature sets downward into mid-tier price bands.
Market Restraints
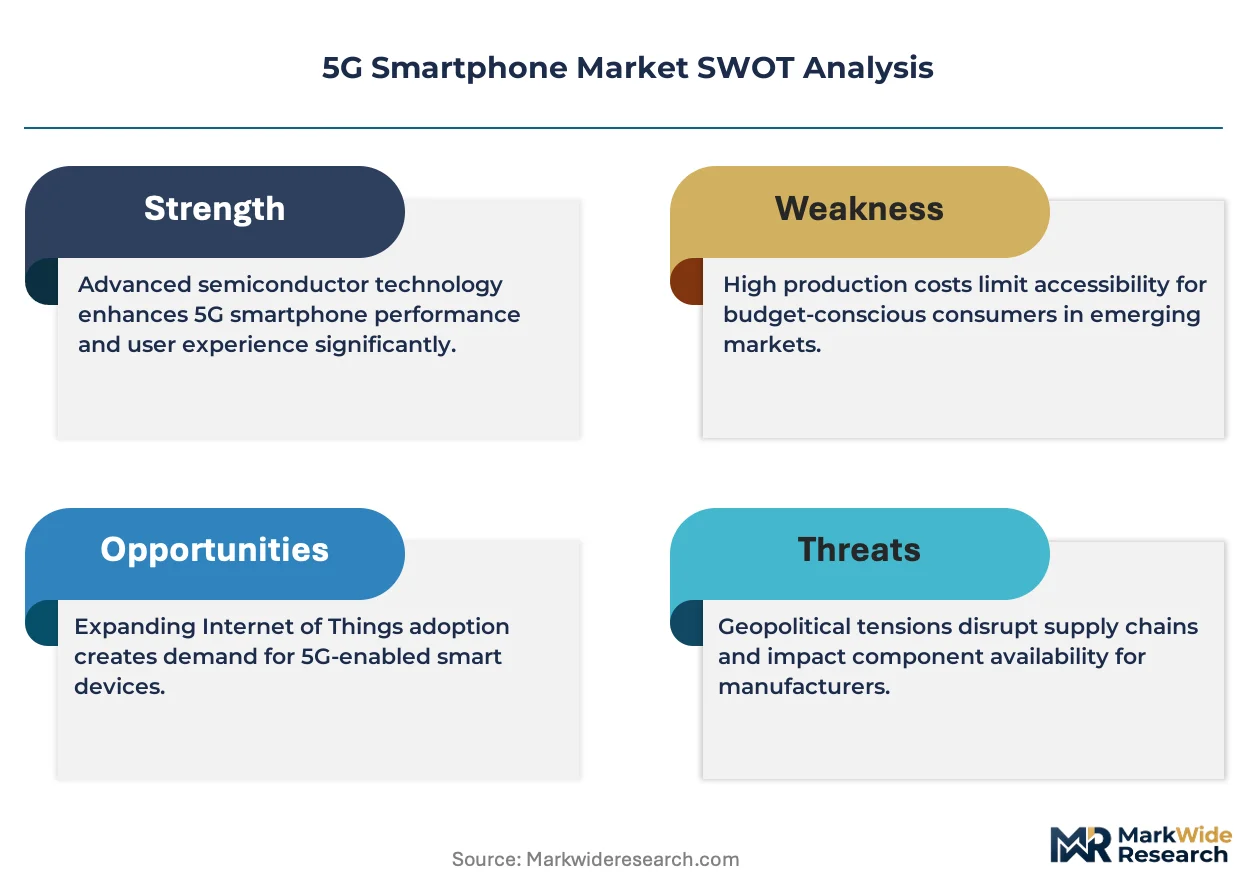
- mmWave module cost structure:Beamforming antenna arrays and phased-array modules carry 3-4x the bill-of-materials burden versus sub-6 GHz equivalents, constraining adoption outside dense urban corridors.
- Foundry concentration risk:Leading-edge 4nm and 3nm modem fabrication depends on Taiwan-based capacity, exposing supply continuity to geopolitical friction and export control variability.
- REACH substance restrictions:European Union constraints on lead-free solder alternatives and flame-retardant compounds are extending qualification timelines for non-EU assembly operations.
Strategic Opportunities
- India PLI scheme leverage:Production-linked incentives for local assembly and component sourcing are attracting module-level investment to serve price-sensitive South Asian demand pools.
- Fixed wireless access convergence:CPE and smartphone modem platform sharing is enabling silicon vendors to amortize R&D across dual-use chipsets, compressing unit economics for both categories.
- Dual carbon alignment:China's SAMR energy efficiency labeling and carbon accounting requirements are favoring suppliers with verified low-carbon assembly and rare-earth traceability.
Industry Challenges
- RF engineering talent scarcity:mmWave antenna design and electromagnetic simulation expertise concentrates within a narrow cohort of semiconductor specialists, inflating compensation and extending hiring cycles.
- Carrier certification timelines:Each major United States operator maintains distinct interoperability testing protocols, forcing parallel validation tracks that delay commercial launch windows by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Smartphone Market |
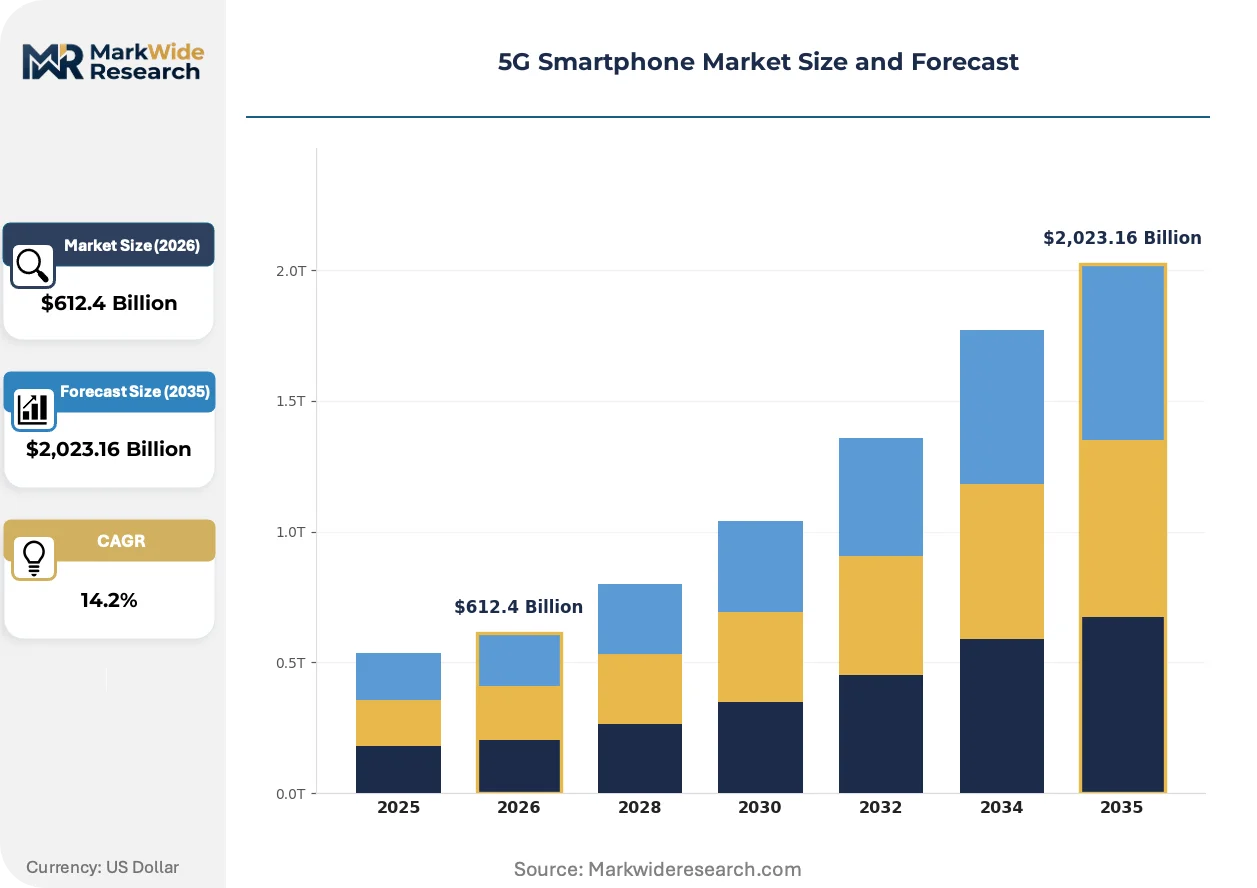
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $2,023.16 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-End, Mid-Range, Budget, Foldable Technology: Sub-6 GHz, mmWave, Dual-Band, Multi-Mode Operating System: Android, iOS, HarmonyOS, Linux Distribution Channel: Online Retail, Offline Retail, Telecom Operators, Wholesalers |
| Companies Covered | Samsung Electronics Co. Ltd., Apple Inc., Huawei Technologies Co. Ltd., Xiaomi Corporation, OPPO, vivo, Motorola Inc., LG Electronics Inc., Lenovo Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Smartphone Market Strategic Shifts & Innovations
Silicon integration roadmaps and spectrum policy divergence are compressing competitive differentiation into modem-antenna co-design capabilities and regional certification velocity.
Integrated modem-RF systems are supplanting discrete baseband and transceiver configurations in premium tier designs. Flagship handset manufacturers are adopting these consolidated packages to reclaim board space for larger battery cells and thermal management. This architectural shift is supplanting legacy multi-chip suppliers with vertically integrated platform vendors capable of delivering calibrated antenna-matching algorithms.
ETSI's evolving cybersecurity certification framework for radio equipment is mandating formalized vulnerability disclosure and software bill-of-materials documentation. European Union member states are beginning to enforce these requirements as market access preconditions, compelling firmware architecture redesigns. Mid-range handset vendors targeting Germany, France, and Italy are responding by segregating radio stack security domains from application processor environments.
Carrier-direct enterprise procurement is displacing traditional distributor-led volume purchasing for fleet deployments. Logistics operators in the United States are negotiating multi-year device-as-a-service agreements that bundle hardware, connectivity, and lifecycle management. This contractual pivot is most visible among national trucking and field service conglomerates seeking to offload obsolescence risk and standardize support workflows across dispersed workforces.
5G Smartphone Market Segmentation
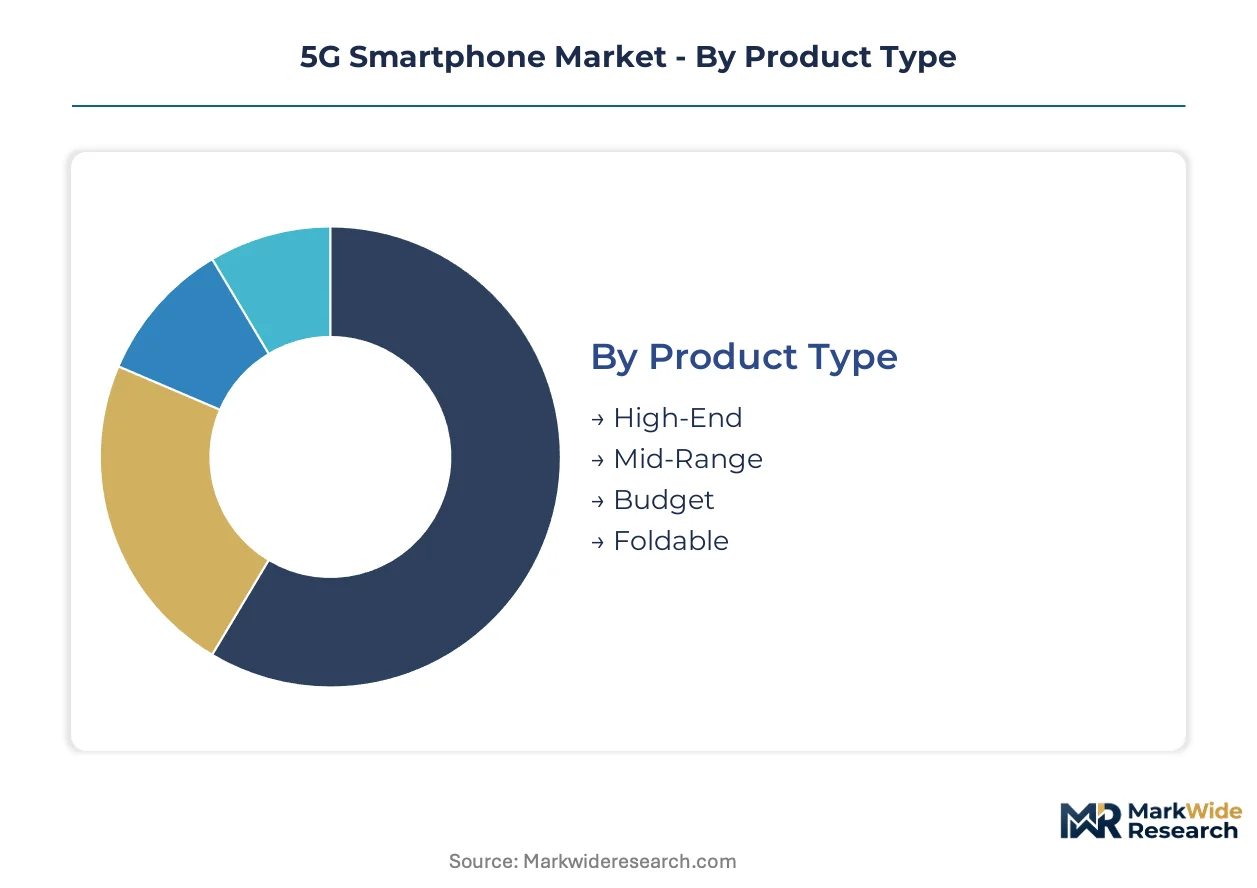
5G smartphone segmentation reveals how silicon sourcing, certification requirements, and procurement channels fragment manufacturing strategies. Manufacturers must align modem configurations with specific frequency deployments and carrier testing protocols to secure market access.
Product Type:
Substitution pressure from refurbished devices and extended-lifecycle fleet management is compressing margins in standardized form factors while elevating differentiation value in novel architectures.
- High-End:Flagship devices integrate 4nm or 3nm modem-RF systems with calibrated antenna-matching algorithms for sub-6 GHz and mmWave operation. Procurement concentrates among North American and Chinese consumers seeking carrier-locked premium distribution with proprietary silicon roadmaps.
- Mid-Range:Dual-band sub-6 GHz configurations dominate this tier, pairing cost-optimized baseband processors with simplified antenna arrays. Demand clusters in India and Southeast Asia where the PLI scheme incentivizes local assembly and price-performance positioning.
- Budget:Sub-6 GHz-only chipsets with discrete modem-transceiver configurations serve emerging market entry segments.
- Foldable:Flexible OLED integration with reinforced hinge mechanisms and thermal management systems addresses ultra-premium niches despite manufacturing yield constraints.
High-End retains volume leadership; Foldable holds the steepest expansion curve.
Technology:
Cost tier stratification follows bill-of-materials escalation from single-band sub-6 GHz through multi-mode mmWave configurations.
- Sub-6 GHz:Dominant unit volume technology leveraging 600 MHz to 6 GHz spectrum bands with mature RF front-end integration and lower infrastructure deployment costs. China's MIIT infrastructure mandates and domestic chipset production create captive supply ecosystems serving captive demand.
- mmWave:Beamforming antenna arrays and phased-array modules enable gigabit-throughput in dense urban corridors where spectrum availability supports peak performance claims. Deployment concentrates in United States metropolitan areas with FCC mid-band auction allocations driving carrier rollout priorities.
- Dual-Band:Combined sub-6 GHz and mmWave capability serves premium tier requirements with flexible geographic coverage.
- Multi-Mode:3GPP Release 17 certified platforms supporting fixed wireless access and industrial IoT use cases with backward compatibility.
Sub-6 GHz commands absolute shipment scale; mmWave delivers the most rapid deployment acceleration in corridor-specific markets.
Operating System:
Application ecosystem lock-in and security certification velocity determine regional competitive positioning across platform alternatives.
- Android:Open-source architecture with customizable OEM skins and Google Mobile Services integration dominates non-Apple volume. The platform's flexibility enables rapid carrier certification adaptation across divergent regional band requirements.
- iOS:Proprietary vertical integration of silicon, firmware, and distribution anchors North American premium demand through carrier-locked channels and controlled lifecycle management.
- HarmonyOS:China's domestic alternative with distributed device architecture and MIIT compliance prioritization serves government and enterprise procurement mandates.
- Linux:Specialized industrial and enterprise fleet deployments with segregated security domains for radio stack isolation.
Android sustains broadest geographic penetration; HarmonyOS is climbing the fastest in captive procurement environments.
Distribution Channel:
Customer type migration from consumer retail toward enterprise fleet procurement is restructuring volume concentration and contractual terms.
- Telecom Operators:Carrier-direct enterprise procurement now dominates United States logistics fleet digitization, with multi-year device-as-a-service agreements bundling hardware, connectivity, and lifecycle management. National trucking and field service conglomerates offload obsolescence risk through standardized support workflows.
- Online Retail:E-commerce platforms with flash-sale dynamics and price-transparent comparison tools concentrate mid-range volume in India and Southeast Asia where the PLI scheme supports local assembly cost structures.
- Offline Retail:Physical storefront presence with hands-on demonstration and immediate fulfillment serves premium tier consumers in urban China and European metropolitan markets.
- Wholesalers:Gray-market and regional distributor networks facilitate budget segment penetration in markets with limited carrier infrastructure.
Telecom Operators capture the dominant enterprise value pool; Online Retail is expanding most quickly in price-sensitive emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise fleet procurement concentrates in the United States logistics sector, while consumer replacement cycles accelerate in China and India. Carrier-locked distribution channels dominate North American premium tiers. Government-backed infrastructure mandates reshape procurement patterns across Asia-Pacific manufacturing clusters.
United States
National trucking conglomerates and last-mile delivery operators mandate 5G-enabled telematics for predictive maintenance scheduling. The FCC's mid-band spectrum auctions have reshaped carrier rollout priorities and handset compatibility requirements. Silicon Valley and Austin semiconductor design clusters concentrate modem-RF integration engineering talent.
China
Domestic chipset production and government-backed infrastructure deployment create a self-reinforcing supply ecosystem for captive demand. MIIT accelerated base station deployment mandates favor domestically certified sub-6 GHz chipsets. Shenzhen and Dongguan manufacturing corridors concentrate flexible OLED integration and hinge mechanism assembly for foldable variants.
India
Price-sensitive consumer segments drive dual-band sub-6 GHz volume in mid-range tiers. The PLI scheme for production-linked incentives attracts module-level investment for local assembly cost structures. Karnataka and Tamil Nadu electronics manufacturing clusters host expanding smartphone assembly operations serving South Asian demand pools.
South Korea
Advanced display integration and in-house modem development anchor premium tier positioning. The MFDS and national spectrum regulator enforce distinct radio equipment authorization frameworks for SAR testing protocols. Seoul Capital Area design centers concentrate mmWave antenna design and electromagnetic simulation expertise.
Germany
Industrial IoT and fixed wireless access applications pull premium handset feature sets into enterprise procurement channels. ETSI's evolving cybersecurity certification framework mandates formalized vulnerability disclosure for radio equipment market access. Munich and Stuttgart automotive clusters drive telematics integration demand for connected fleet management.
5G Smartphone Market Key Industry Players
Player mix skews toward vertically integrated platform vendors with captive modem-RF capabilities and carrier-locked distribution partnerships. Tiered competitive structure separates premium silicon architects from mid-range price-performance specialists and regional assembly contractors. Strategic archetypes include integrated platform vendors, component modularization specialists, and government-backed domestic champions. Dominant competitive moves center on modem-antenna co-design consolidation and multi-year device-as-a-service contractual pivots.
Within the integrated platform tier, Samsung Electronics Co. Ltd. and Apple Inc. occupy positions defined by in-house silicon roadmaps and premium distribution channel control. Xiaomi Corporation exemplifies the price-performance archetype competing aggressively in mid-range dual-band segments. Among China-based fabricators, Huawei Technologies Co. Ltd. represents the government-backed domestic champion model serving captive procurement mandates.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| Apple Inc. |
| Huawei Technologies Co. Ltd. |
| Xiaomi Corporation |
| OPPO |
| vivo |
| Motorola Inc. |
| LG Electronics Inc. |
| Lenovo Group Limited |
| Others |
Cost & Logistics Intelligence
Ninety-day chipset inventory cycles at Taiwan-based foundries concentrate margin leverage among vertically integrated platform vendors while compressing pricing power for assembly-dependent brands. This lead-time bandwidth amplifies cost-plus contract renegotiation frequency across modem-RF procurement tiers, with indexation clauses tied to wafer capacity utilization rates and rare-earth magnet pricing.
Pricing Analysis
Cost-plus contracts with semiconductor foundries carry quarterly price indexation tied to wafer loading rates and noble metal spot markets. Three-tier pricing structure across premium, standard, and economy levels separates calibrated mmWave-modem flagships from sub-6 GHz mid-range devices and discrete-modem budget units. Pricing pressure stems from refurbished device substitution in enterprise fleet procurement, with logistics operators demanding device-as-a-service bundles that offload obsolescence risk. Mid-range dual-band segments exhibit highest price sensitivity, while carrier-locked premium tiers retain pricing power through proprietary silicon roadmaps.
Supply Chain Analysis
Taiwan and South Korea anchor leading-edge 4nm and 3nm modem wafer fabrication, while China concentrates sub-6 GHz baseband processor assembly and flexible OLED module production. The supply chain draws from gallium arsenide substrate suppliers, rare-earth magnet providers for antenna actuators, and high-frequency laminate vendors for mmWave circuit boards. Single-source vulnerability at Taiwan-based foundry nodes exposes continuity to export control variability and geopolitical friction. Distribution runs through carrier-direct enterprise procurement channels in the United States and PLI-supported local assembly networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise fleet digitization and Release 17 certification expansion signal early-cycle penetration growth, with fixed wireless access convergence pulling premium modem capabilities into mid-tier price bands. Logistics operators mandating 5G-enabled telematics create durable demand foundations across North American and Asia-Pacific procurement channels.
For Market Incumbents: Fortify modem-RF integration capabilities through in-house antenna-matching algorithm development and calibrated thermal management IP. Carrier certification velocity serves as the primary defensive moat against emerging platform vendors, while backward integration into display driver IC production protects margin structures from foundry concentration risk. Prioritize multi-year device-as-a-service contract structures with national trucking conglomerates to lock out substitute procurement channels.
For New Entrants and Emerging Players: Enterprise security domain segregation presents a service-layer gap where incumbents under-serve mid-range fleet deployments requiring ETSI cybersecurity compliance. Target India's PLI-supported manufacturing clusters with locally assembled sub-6 GHz modules priced for price-sensitive South Asian consumer segments. Pursue carrier-direct certification partnerships rather than distributor-led volume channels to compress commercial launch timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with captive modem engineering teams but sub-scale smartphone distribution. Long-term viability centers on platform vendors with verified low-carbon assembly credentials and dual-band certification velocity across FCC and MIIT frameworks. Watch for inflection signals in fixed wireless access CPE procurement volumes, which indicate smartphone modem platform sharing economics reaching scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Modem-RF System Integration | Consolidated packages from Qualcomm and MediaTek reclaim board space for Samsung and Apple flagship designs. |
| Carrier-Direct Enterprise Procurement | Multi-year device-as-a-service agreements with Verizon and AT&T reshape logistics fleet purchasing workflows. |
| India PLI Scheme Localization | Module-level investment in Karnataka and Tamil Nadu clusters compresses assembly costs for Xiaomi and OPPO mid-range portfolios. |
| ETSI Cybersecurity Certification | Formalized vulnerability disclosure mandates force firmware architecture redesigns for European market access. |
| Fixed Wireless Access Convergence | CPE and smartphone modem platform sharing amortizes R&D across dual-use chipsets for silicon vendors. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with RF engineering directors, carrier procurement leads, semiconductor foundry planning officers, and logistics fleet technology managers; and secondary validation through 3GPP release documentation, FCC spectrum auction records, MIIT base station deployment filings, and SEC semiconductor supplier disclosures. Bottom-up triangulation across component bill-of-materials estimates and top-down reconciliation against carrier subscriber equipment forecasts anchored volume and value projections.
Across the analysis window, the forecasting framework modeled smartphone shipments by product tier, technology band configuration, operating system platform, and distribution channel structure. CAGRs were derived from regression analysis of historical replacement cycle compression and enterprise fleet penetration curves, with cross-validation against foundry capacity expansion plans and spectrum allocation timelines. Industry-specific inputs included 3GPP Release 17 certification schedules and PLI scheme incentive disbursement trajectories.
Material uncertainties — geopolitical friction affecting Taiwan-based foundry access, unanticipated REACH substance restriction amendments, and carrier interoperability testing protocol changes — sit outside the modeled envelope. Forecasts reflect assumptions about sustained enterprise fleet digitization momentum and mid-band spectrum deployment continuity. Recalibration cycles align with material shifts in 3GPP standardization timelines and major carrier procurement award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bitcoin Mining Servers Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Drum Motor Market
Others
Smart Home Controller Market
Others
Cathode Battery Material Market
Others
Industrial Tablet PC Market
Others
Stand-Up Pouch Valves Market
Others
ASEAN Smart Homes Market
Others
South Korea Smart Home Market
Others
Paper Shredder Market
Others
Profilometer Market
Others
Running Apparel Market
Others
High Frequency Vibrator Market
Others
Belt Loader Market
Others
Bamboo Straws Market
Others
Global Electroshock Weapons Market