
 Africa Cotton Market | 2026-2036
Africa Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Cotton Market Outlook
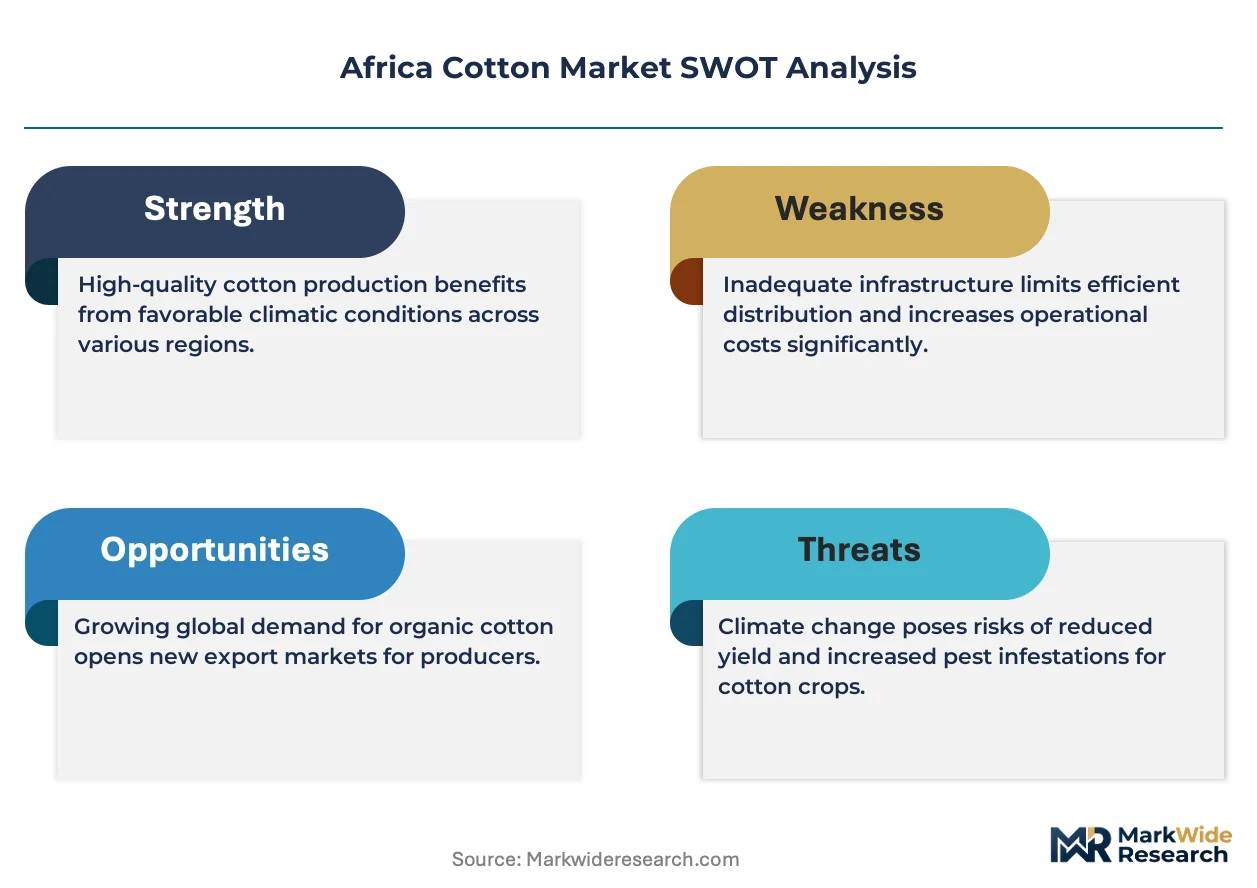
Asset-light ginning concessions and warehouse-receipt financing is rewriting competitive entry in Africa's cotton value chain. SOCOMA leverages backward integration into seed cotton collection to sustain origination volumes in Madagascar. Olam Agri anchors its Sahel presence through controlled logistics networks spanning Burkina Faso and Mali. CMDT dominates Mali's southern cotton basin, where state-backed input credit schemes still govern farmer planting decisions.
Cotton comprises seed-hair fibers of the genus Gossypium, with staple lengths ranging from short-staple upland varieties near 27 millimeters to extra-long-staple Egyptian types exceeding 35 millimeters, and serves as the principal natural cellulosic feedstock for spun yarn and nonwoven manufacturing. Upland Cotton occupies the volume core across Francophone West Africa, where ginning capacity and seed-cotton procurement density determine processor economics. Organic Cotton commands premium offtake from European apparel manufacturers, though certified hectarage remains constrained by three-year conversion rules and input cost barriers. The Clothing application segment channels the majority of lint through spinning mills in Egypt and Tunisia, with bedding and upholstery absorbing higher-grade long-staple supplies.
Burkina Faso's national cotton regulator oversees varietal approval and input subsidy frameworks that directly shape farmer seed choices and fiber quality profiles. Egypt's plant quarantine standards and lint classification protocols govern access to premium export channels, particularly for combed yarn spinners in South Asia. Stakeholders must monitor how climate-risk financing instruments and carbon-accounting rules for natural fiber production reshape capital allocation across ginning and textile manufacturing assets.
Market Dynamics
Asset-light ginning concessions and warehouse-receipt financing are compressing capital barriers for new entrants across Francophone West Africa, fragmenting origination control away from state-backed monopolies toward logistics-integrated traders.
Growth Catalysts
- Input Credit Schemes:Mali's CMDT state-backed input programs govern farmer planting decisions, locking in seed-cotton procurement volumes for ginners. These frameworks stabilize origination despite price volatility.
- Organic Certification Premiums:European apparel manufacturers command certified organic offtake, creating price differentiation for growers meeting three-year conversion rules. Conversion hectarage expands where extension services support compliance.
- Logistics Network Density:Controlled transport corridors spanning Burkina Faso and Mali reduce seed-cotton collection costs. Olam Agri anchors Sahel presence through this infrastructure concentration.
Market Restraints
- Seed-Cotton Price Volatility:Farmer payment delays and input cost inflation compress planting incentives. Burkina Faso's national cotton regulator struggles to balance floor prices with ginning margins.
- Ginning Capacity Concentration:Processing assets cluster in Mali's Sikasso region and coastal Egypt, leaving hinterland origins dependent on costly long-haul transport. This geographic lock-in raises delivered lint costs.
- Synthetic Fiber Substitution:Polyester staple pricing pressure from Asian petrochemical complexes erodes cotton's share in mass-market yarn blends. Spinners in Tunisia and Egypt increasingly blend down natural fiber ratios.
Strategic Opportunities
- Climate-Risk Financing Instruments:Parametric drought insurance and carbon-accounting rules for natural fiber production reshape capital allocation. Development finance institutions pilot instruments in Madagascar and Mozambique.
- Long-Staple Premium Channels:Egyptian extra-long-staple varieties exceeding 35 millimeters command specialized offtake from South Asian combed yarn spinners. Quality differentiation escapes commodity lint pricing.
- Warehouse-Receipt Collateralization:Formalized inventory finance allows farmers and cooperatives to time sales against seasonal price curves. SOCOMA leverages backward integration into collection to support this channel innovation.
Industry Challenges
- Organic Conversion Timelines:Three-year certification rules and input cost barriers constrain certified hectarage expansion. Extension service capacity limits farmer uptake of compliant agronomy.
- Ginning Technology Gaps:Roller ginning versus saw ginning equipment choices affect fiber quality profiles and seed-cotton throughput. Capital intensity for modernization outstrips concession-holder balance sheets.
- Phytosanitary Compliance Complexity:Egypt's plant quarantine standards and lint classification protocols create export friction. Rejection risk at port of entry disrupts premium channel access for non-compliant shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Cotton Market |
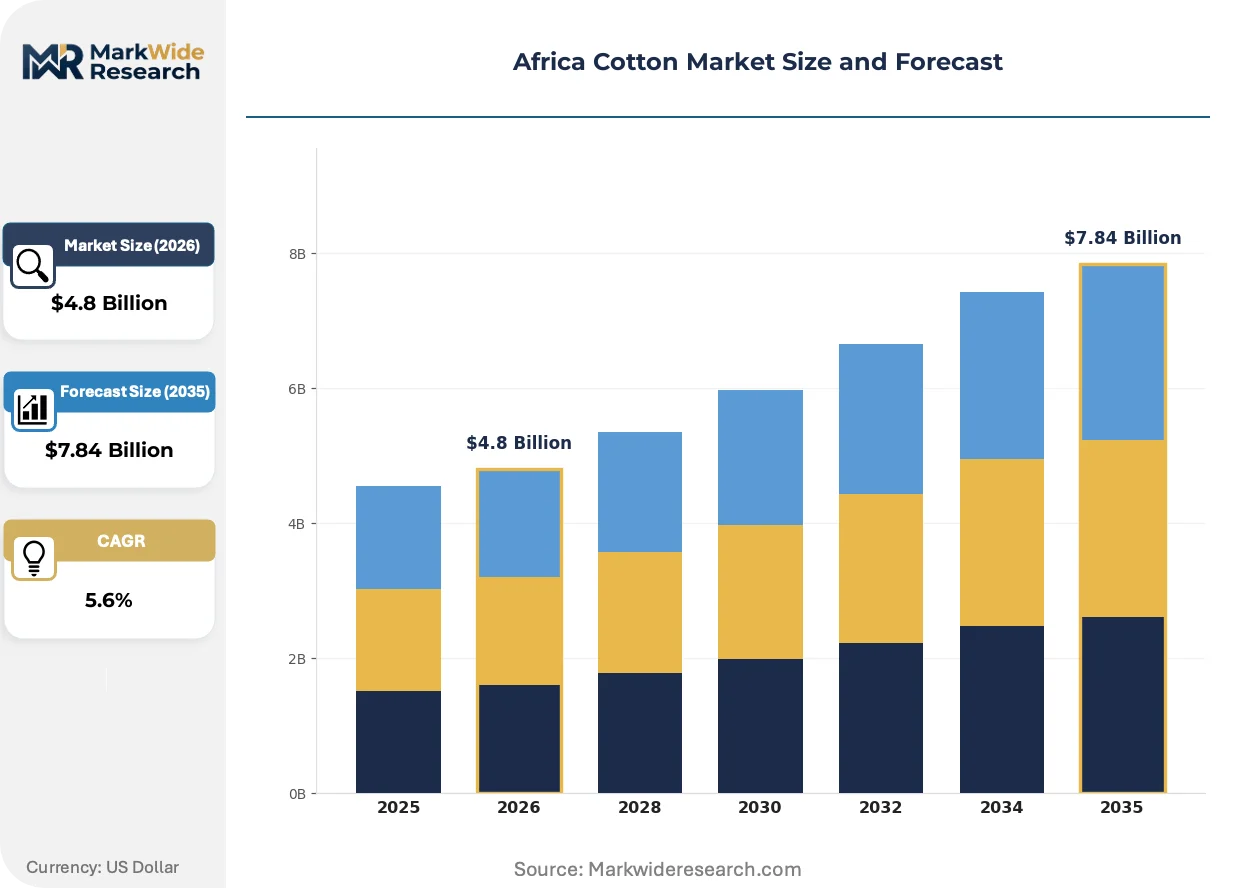
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upland Cotton, Pima Cotton, Organic Cotton, Fiber Blends End User: Textile Industry, Apparel Manufacturers, Home Furnishings, Non-woven Products Distribution Channel: Wholesale, Retail, Direct Sales, Online Marketplaces Application: Clothing, Bedding, Upholstery, Industrial Textiles |
| Companies Covered | SOCOMA, Olam Agri, CMDT, Egyptian Cotton Egypt, Nouvelle Société du Coton de Ketta, SOFITEX, FASO COTON, Akosombo Textiles Ltd, SODECOTON, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Cotton Market Strategic Shifts
Digital traceability platforms and climate-adaptive varietal development are reconfiguring how lint quality is verified and how farmer planting decisions respond to environmental risk.
Gene-edited drought tolerance traits in Gossypium hirsutum varieties are hybridizing conventional breeding pipelines with CRISPR acceleration. Burkina Faso's national cotton regulator evaluates these materials for varietal approval, though biosafety frameworks lag technical capability. Seed companies anticipate commercial release timelines contingent on regulatory clarity, compressing the gap between research station performance and field-scale deployment.
EU Deforestation Regulation due diligence requirements are mandating geolocation verification for cotton entering European apparel supply chains. Ginners and traders must deploy farm-polygon mapping and mass-balance documentation systems. Mali's CMDT and private operators in Côte d'Ivoire are piloting satellite-based farm boundary registration to preempt compliance disruption.
Direct contracting between spinners and organized farmer cooperatives is displacing spot-market lint procurement through traditional auction channels. Egyptian and Tunisian textile mills negotiate multi-season volume commitments with designated origin clusters. This procurement model shift concentrates quality accountability upstream, rewarding ginners with certified traceability systems and penalizing informal intermediaries.
Africa Cotton Market Segmentation
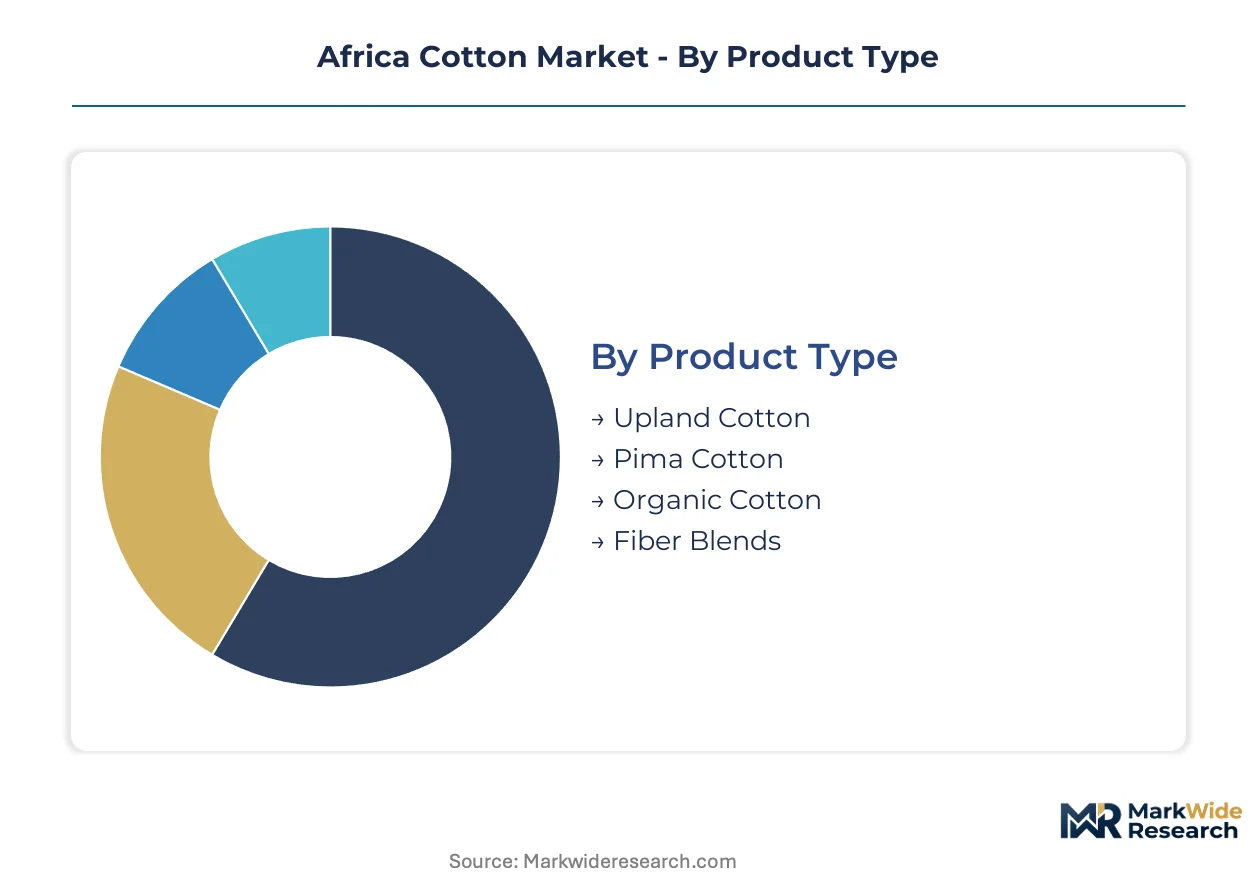
Segmentation in Africa's cotton sector reveals how fiber specifications, procurement channels, and end-use requirements fragment commercial opportunity. Ginners and traders must align origination strategies with distinct quality premiums and logistics constraints across each dimension.
Product Type:
Use-case spectrum spans commodity volume plays through specialized premium positioning, with fiber length and certification status determining margin architecture.
- Upland Cotton:Short-staple varieties near 27 millimeters dominate ginning throughput across Francophone West Africa. Mali's CMDT-governed Sikasso region channels the bulk of regional lint supply into mass-market yarn spinners in Tunisia and Egypt.
- Organic Cotton:Certified organic offtake commands price differentiation from European apparel manufacturers. Conversion hectarage expands slowly due to three-year certification rules and input cost barriers that constrain farmer uptake.
- Pima Cotton:Extra-long-staple Egyptian types exceeding 35 millimeters serve specialized combed yarn spinners in South Asia.
- Fiber Blends:Cotton-polyester mixtures respond to Asian petrochemical pricing pressure in mass-market segments.
The dominant share belongs to Upland Cotton, while Organic Cotton is gaining share fastest on certified premium channels.
End User:
Customer concentration patterns reflect downstream integration depth, from state-linked textile mills to fragmented home furnishing converters.
- Textile Industry:Integrated spinning mills in Egypt and Tunisia absorb the majority of lint volume. These processors negotiate multi-season volume commitments with designated origin clusters, displacing spot-market procurement.
- Apparel Manufacturers:European brands drive organic certification demand through supply chain due diligence requirements. EU Deforestation Regulation mandates geolocation verification, forcing upstream traceability investments.
- Home Furnishings:Bedding and upholstery applications absorb higher-grade long-staple supplies from Egyptian origins.
- Non-woven Products:Medical and hygiene applications source specific fiber cleanliness grades through direct contracting.
Textile Industry concentration anchors volume, though Apparel Manufacturers are expanding procurement most quickly on sustainability mandates.
Distribution Channel:
Channel economics hinge on working capital intensity and inventory risk allocation between producers and intermediaries.
- Wholesale:Traditional auction channels through national cotton companies still govern Mali and Burkina Faso origination. These structures lock in farmer planting decisions through state-backed input credit schemes.
- Direct Sales:Spinners in Egypt and Tunisia negotiate multi-season commitments with organized cooperatives. This procurement shift concentrates quality accountability upstream and penalizes informal intermediaries.
- Retail:Small-scale traders serve local spinning operations with limited volume aggregation.
- Online Marketplaces:Digital platforms remain nascent for physical cotton transactions but support price discovery and farm-polygon mapping for compliance documentation.
Wholesale channels retain the largest flow, yet Direct Sales are climbing the fastest as mills bypass traditional auction structures.
Application:
Application segmentation tracks how fiber length and processing quality map to finished product performance requirements.
- Clothing:Garment manufacturing channels the majority of lint through spinning mills in Egypt and Tunisia. Mass-market apparel blends face polyester substitution pressure from Asian petrochemical complexes.
- Bedding:Higher thread-count applications demand longer staple lengths and superior fiber uniformity. Egyptian extra-long-staple varieties command specialized offtake for premium sheet and duvet markets.
- Upholstery:Furniture fabric applications require specific durability and dye uptake characteristics.
- Industrial Textiles:Technical applications in automotive and filtration use specialized fiber strength grades.
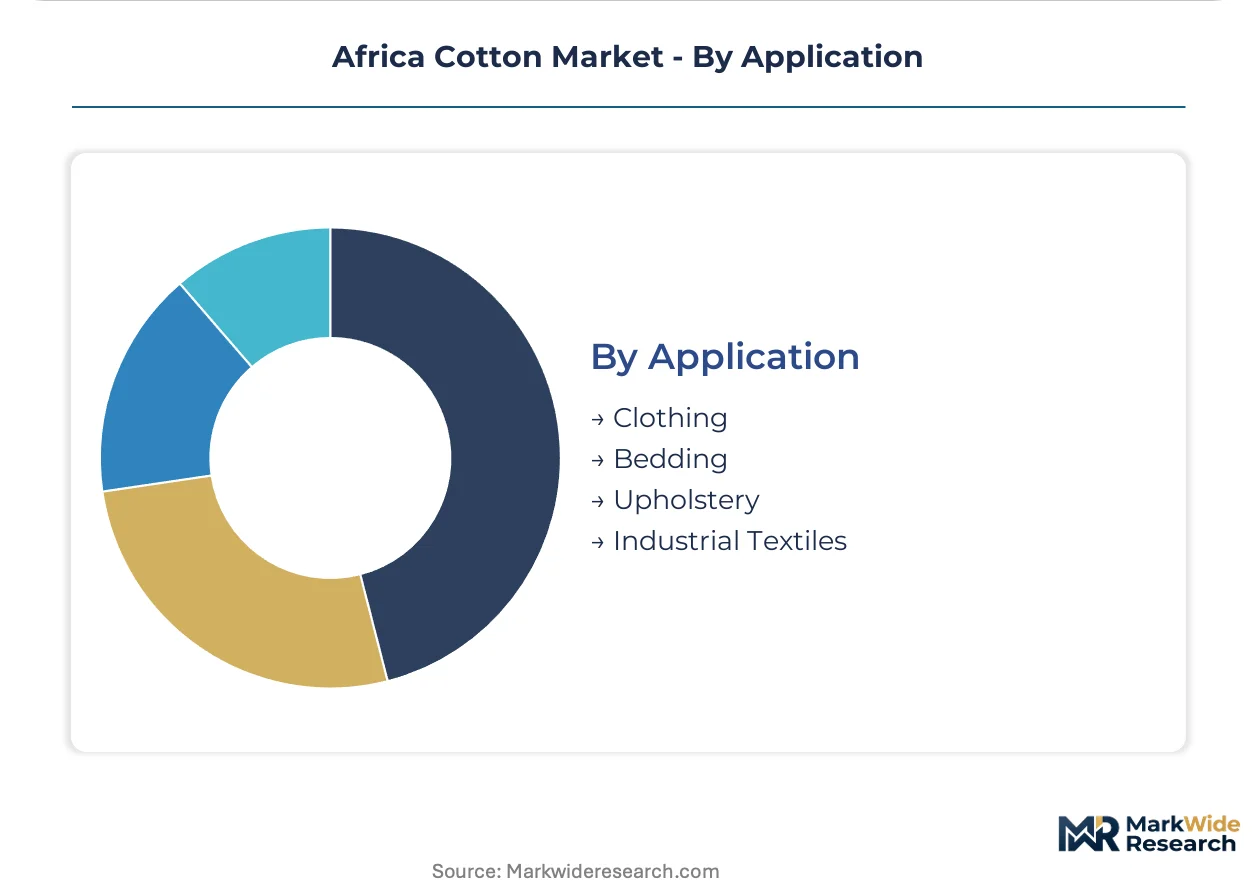
Clothing applications dominate lint absorption, while Bedding shows the steepest expansion trajectory on premium long-staple differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Input subsidy frameworks and state-backed credit programs govern planting decisions across Francophone West Africa. These institutional arrangements concentrate ginning capacity in specific basins while shaping fiber quality profiles through varietal approval regimes.
Mali
CMDT's input credit schemes lock in seed-cotton procurement volumes for southern basin ginners. The Sikasso region channels bulk lint supply into mass-market yarn spinners through controlled logistics networks. State-backed planting programs stabilize origination despite seasonal price volatility.
Burkina Faso
FASO COTON and SOFITEX operate within a national regulator framework that oversees varietal approval and floor price setting. The national cotton company restructuring underpins institutional reform efforts. Ginning concessions fragment origination control away from historical monopolies.
Egypt
Extra-long-staple varieties exceeding 35 millimeters command specialized offtake from South Asian combed yarn spinners. Plant quarantine standards and lint classification protocols create export friction for non-compliant shipments. Nile Delta clusters anchor premium channel access.
Madagascar
SOCOMA leverages backward integration into seed cotton collection to sustain origination volumes. Development finance institutions pilot parametric drought insurance instruments here. Extension services support organic conversion compliance where three-year certification rules apply.
Cameroon
SODECOTON governs northern planting basins through integrated input supply and ginning operations. Warehouse-receipt financing pilots allow cooperatives to time sales against seasonal price curves. Yaoundé-based coordination links collection networks to coastal export channels.
Africa Cotton Market Competitive Environment
Channel-controlling players compete with product-specialist players across Africa's cotton value chain. State-linked processors retain origination dominance in Mali and Burkina Faso through credit-integrated procurement, while logistics-integrated traders capture margin through transport corridor density. Three archetypes define competitive positioning: national cotton companies with input-credit monopolies, ginning concessionaires with asset-light balance sheets, and origin-integrated traders with controlled logistics networks. Competitive moves center on backward integration into collection and warehouse-receipt collateralization systems.
Among Francophone West African operators, SOFITEX and FASO COTON exemplify national cotton company archetypes with state-linked procurement mandates. SOCOMA occupies a position representing origin-integrated collection models in Indian Ocean markets. Olam Agri anchors the logistics-integrated trader archetype through Sahel corridor control. Egyptian Cotton Egypt sits within the premium-tier specialist category serving long-staple differentiation channels.
| Leading Market Players |
|---|
| SOCOMA |
| Olam Agri |
| CMDT |
| Egyptian Cotton Egypt |
| Nouvelle Société du Coton de Ketta |
| SOFITEX |
| FASO COTON |
| Akosombo Textiles Ltd |
| SODECOTON |
| Others |
Value Chain & Pricing Dynamics
Mali's CMDT-governed Sikasso region anchors seed-cotton procurement density, concentrating origination leverage with state-backed ginners who capture margin pools through input-credit-locked farmer commitments. This upstream control cascades downstream, where Egyptian extra-long-staple varieties command specialized premiums from South Asian combed yarn spinners.
Pricing Analysis
Certification level creates the primary spread between commodity upland lint and organic-certified offtake to European apparel manufacturers. Three-tier pricing structure across premium long-staple, standard upland, and economy-grade lint governs contract negotiations. Pricing pressure stems from polyester staple pricing pressure from Asian petrochemical complexes eroding cotton's share in mass-market yarn blends. Small-scale home furnishing converters exhibit highest price sensitivity; premium bedding manufacturers demonstrate lowest.
Supply Chain Analysis
Contract ginning capacity concentrates with SOFITEX and FASO COTON in Burkina Faso, CMDT in Mali, and Egyptian Cotton Egypt in the Nile Delta. Seed-cotton collection, ginning throughput, and lint classification equipment anchor production economics. Supply chain risk centers on single-source vulnerability where hinterland origins depend on costly long-haul transport to coastal export channels. Distribution runs through state-linked auction structures in Francophone West Africa and direct mill contracting in Egypt and Tunisia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where state-backed input credit schemes create regulatory entrenchment that locks in farmer planting decisions and origination volumes. Switching costs for farmers exiting established credit-ginning relationships reinforce incumbent positioning.
For Market Incumbents: Harden origination control through backward integration into warehouse-receipt collateralization systems that allow cooperatives to time sales against seasonal price curves. Expand climate-risk financing instrument pilots in Madagascar and Mozambique to preempt development finance institution encroachment. Synthetic fiber substitution in Tunisian and Egyptian mass-market spinning mills threatens volume offtake; counter with certified organic premium channel expansion.
For New Entrants and Emerging Players: Establish a beachhead in warehouse-receipt financing for seed-cotton collection, where asset-light balance sheets can bypass CMDT's capital-intensive infrastructure. Target organic certification compliance services in Burkina Faso and Mali, where three-year conversion rules and extension service gaps constrain farmer uptake. Go-to-market through logistics-integrated trader partnerships leveraging controlled transport corridor density.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with ginning concessionaires holding asset-light balance sheets across Francophone West Africa. Long-term viability hinges on traceability infrastructure investments required by EU Deforestation Regulation geolocation mandates. Watch for inflection where direct spinner-cooperative contracting displaces traditional auction channels, penalizing informal intermediaries and rewarding certified traceability systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection | SOCOMA's seed-cotton collection model secures origination volumes against concession fragmentation. |
| Climate-Risk Financing Pilot | Parametric drought insurance instruments in Madagascar reshape capital allocation for natural fiber production. |
| Digital Traceability Platform Deployment | Farm-polygon mapping systems preempt EU Deforestation Regulation compliance disruption for ginners. |
| Organic Certification Expansion | Three-year conversion compliance unlocks premium offtake from European apparel manufacturers. |
| Direct Mill Contracting | Egyptian and Tunisian textile multi-season commitments concentrate quality accountability upstream. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the value chain, including ginning operations managers, state cotton company procurement directors, textile mill spinning supervisors, and European apparel sustainability officers. Secondary validation drew from CMDT annual reports, Burkina Faso national cotton regulator filings, Egyptian plant quarantine standards documentation, and EU Deforestation Regulation technical guidance. Bottom-up seed-cotton volume estimates triangulated with top-down lint consumption models across the analysis window.
Calibration against historical price volatility and input subsidy program changes anchored projection reliability. Segmentation dimensions modeled included fiber type tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume trajectories and lint price band assumptions. Forecast inputs incorporated climate-adaptive varietal adoption curves and carbon-accounting rule implementation timelines.
Stress conditions across seed-cotton price floors, input cost inflation, and synthetic fiber substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding state credit program continuity and biosafety framework clarity for gene-edited varieties. Quarterly review of varietal approval decisions, warehouse-receipt financing penetration, and EU compliance system deployment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hearables Market
Others
Human Enhancement Technology Market
Others
ISO Cylinder Market
Others
Surgical Simulation Market
Others
Inorganic Tin Chemicals Market
Others
North America Automotive LED Lighting Market
Others
Global Animal Feed Protein Ingredients Market
Others
Stand-Up Pouch Valves Market
Others
Hot Air System Market
Others
Brazil Lime Market
Others
AC Switchgear Market
Others
Cloud Advertising Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Aircraft Switches Market
Others
Managed Testing Services Market
Others
Global Computer Graphics Market