
 Computer on Module Market | 2026-2036
Computer on Module Market Size, Share, and Industry Trends Forecast 2026-2036
Computer on Module Market Intelligence
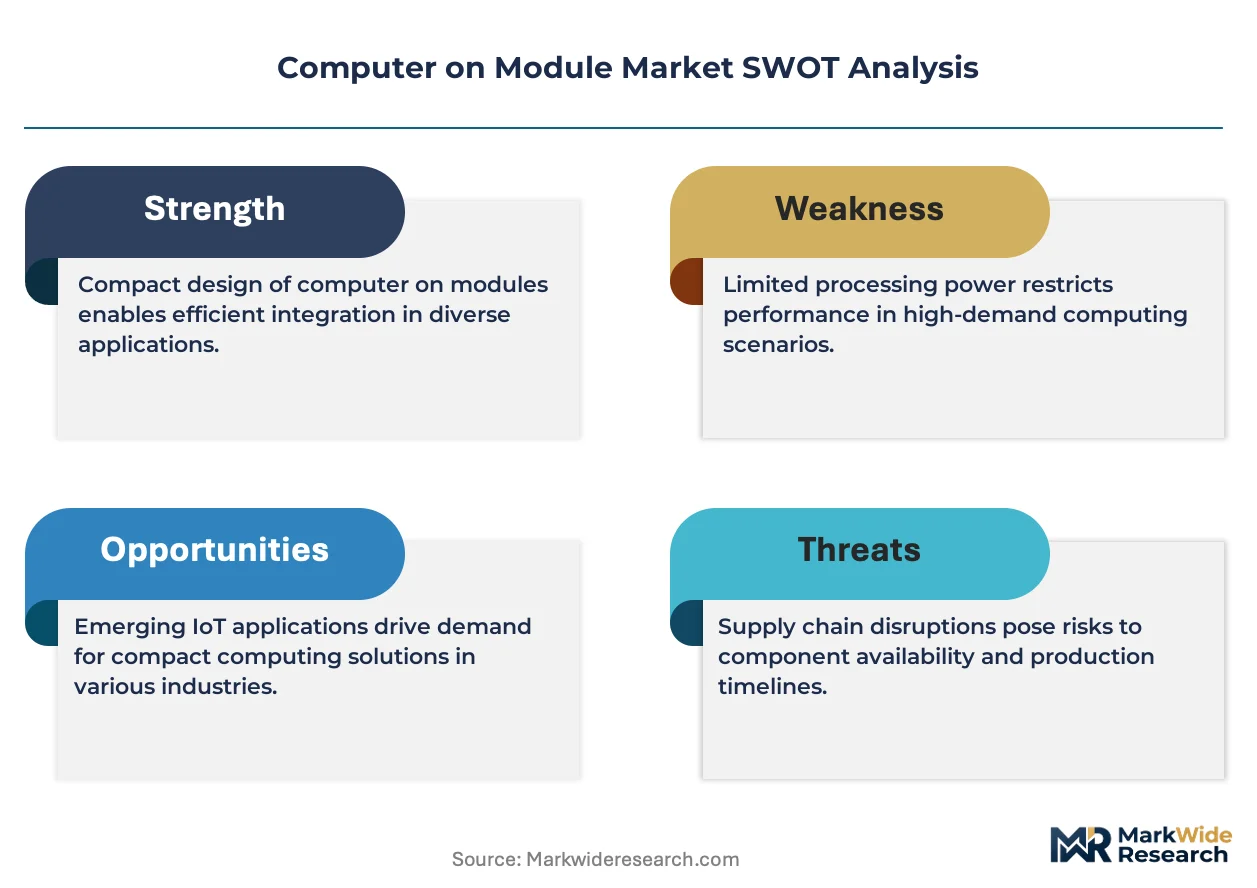
REACH is rebalancing material sourcing constraints for European COM manufacturers, raising the cost-of-entry calculus for new entrants lacking RoHS-compliant supply chains. Advantech Co., Ltd. leverages captive foundry partnerships to sustain margin control across industrial temperature-grade modules. Kontron AG anchors its position through backward integration into carrier-board design, while congatec AG competes via specialization in SMARC form factors for medical imaging subsystems.
A computer on module integrates a complete computing subsystem—CPU, memory, power management, and I/O controllers—onto a standardized board designed to mate with a carrier board via high-density connectors, typically operating across -40°C to 85°C industrial temperature ranges. Its primary purpose is to decouple processor complexity from application-specific circuitry, letting OEMs swap compute engines without redesigning entire devices. The x86 segment dominates revenue owing to legacy compatibility in factory automation and medical diagnostics, while ARM modules represent the fastest-expanding margin pool as robotics OEMs prioritize watt-per-inference metrics. COM Express form factors occupy the mature core of the market, though SMARC is gaining share in space-constrained drone and portable medical applications.
The EU AI Act and CE marking requirements are reshaping edge-AI module certification, forcing vendors to document algorithmic transparency and hardware security before market access. The FCC in the United States enforces electromagnetic compatibility standards that govern Wi-Fi and Bluetooth subsystems embedded in COM designs. Japan's METI promotes industrial IoT interoperability through JIS standards that influence module pinout and thermal specifications. Stakeholders must monitor whether emerging cybersecurity mandates for critical infrastructure will fragment compliance regimes across export destinations.
Market Dynamics
Factory digitization is compressing replacement cycles for industrial controllers, forcing COM vendors to align module refresh rates with software-defined automation timelines rather than traditional hardware depreciation schedules.
Growth Catalysts
- EU AI Act edge-AI mandates:The regulation's risk-classification framework for embedded inference hardware is accelerating procurement of pre-certified modules among German automotive integrators and Italian packaging-machine OEMs.
- ARM architecture watt-per-inference optimization:Robotics manufacturers specify ARM-based COMs for mobile cobot applications where thermal budgets and battery endurance constrain x86 deployments.
- SMARC form factor penetration:Drone and portable medical device engineers adopt the compact standard for space-constrained designs previously served by custom single-board computers.
Market Restraints
- Industrial-grade component sourcing:Extended lead times for -40°C to 85°C rated memory and power management ICs from Taiwanese foundries constrain module output scheduling.
- REACH and RoHS compliance layering:European manufacturers absorb elevated material qualification costs as ECHA adds restricted substances, raising the cost-of-entry for new COM entrants lacking compliant supply chains.
- Carrier-board redesign friction:OEMs hesitate to migrate between module standards because existing carrier investments lock them into legacy pinout configurations.
Strategic Opportunities
- Medical imaging subsystem specialization:SMARC modules with integrated MIPI-CSI interfaces capture design wins in ultrasound and endoscopy equipment where camera-parallel processing is critical.
- Japan METI industrial IoT interoperability:JIS-compliant thermal and pinout specifications open procurement channels among Japanese machine-tool builders standardizing on modular compute.
- Edge-AI security module bundling:Vendors can attach hardware security element services to COM shipments, addressing EU AI Act documentation requirements for algorithmic transparency.
Industry Challenges
- Embedded Linux kernel maintenance:OEMs struggle to secure long-term support contracts for Yocto and real-time patch streams across decade-long industrial equipment lifecycles.
- CE marking timeline compression:EU AI Act pre-market conformity assessments extend certification cycles by four to six months, delaying revenue recognition for new module introductions.
- Multi-generational socket compatibility:Engineers face integration complexity when mating new processor modules to carrier boards designed for superseded pinout revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer on Module Market |
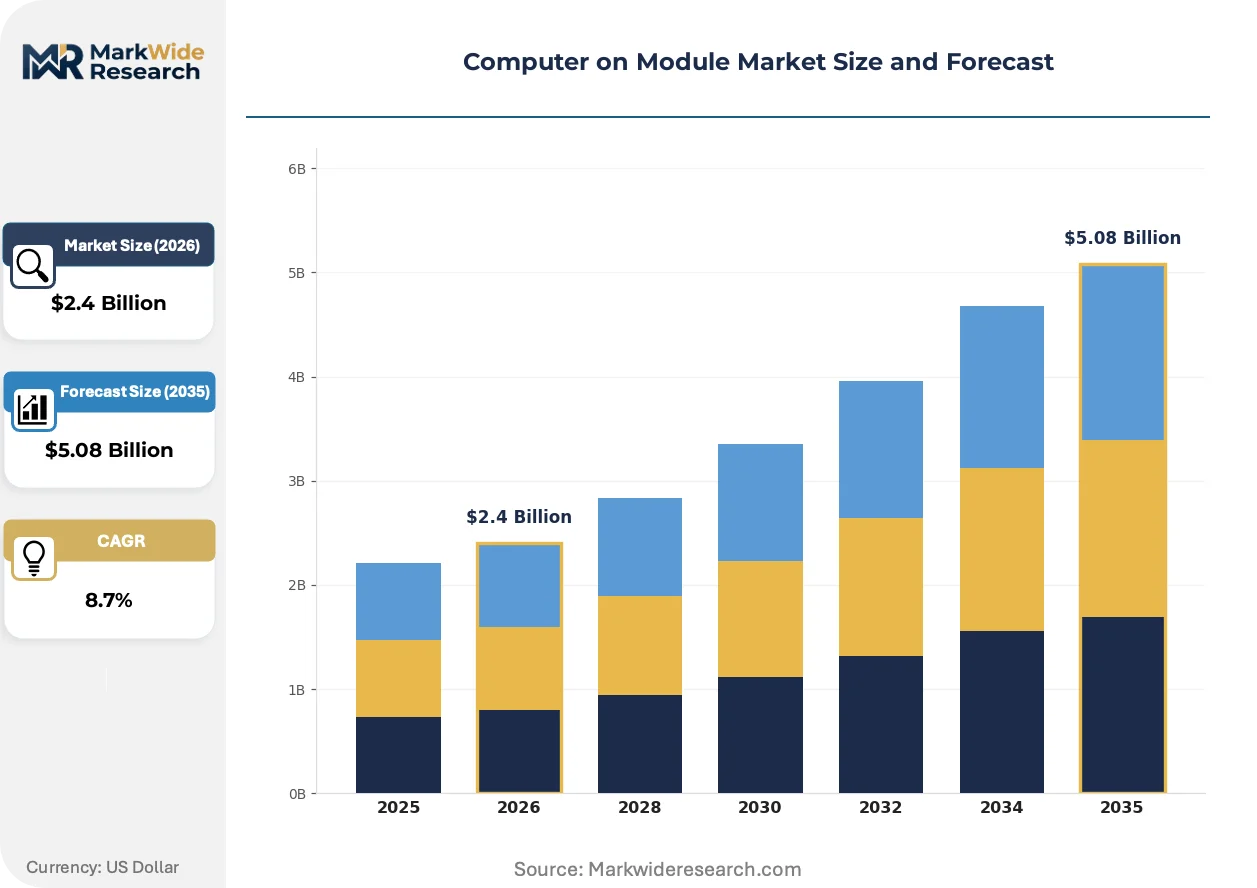
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ARM, x86, Raspberry Pi, Jetson Nano End User: Industrial Automation, Robotics, Medical Devices, Consumer Electronics Form Factor: COM Express, Qseven, SMARC, μQseven Connectivity: Ethernet, Wi-Fi, Bluetooth, USB |
| Companies Covered | Advantech Co., Ltd., Kontron AG, congatec AG, ADLINK Technology Inc., AAEON Co., Ltd., Toradex, Eurotech S.p.A., Axiomtek Co., Ltd., SECO S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer on Module Market Strategic Shifts & Innovations
Module architectures are converging around software-defined peripherals, enabling OEMs to reconfigure I/O personalities through firmware rather than hardware respins. This shift is compressing carrier-board redesign cycles and altering how vendors compete on customization.
Heterogeneous processor integration is unifying CPU, GPU, and NPU dies within single-package COMs. Automotive ADAS subsystem suppliers in Germany and machine-vision integrators in Japan are specifying these fused architectures to consolidate inference and control workloads. The technology is unifying previously separate vision-processing and motion-control modules into single-board designs, reducing BOM line counts and inter-board cabling.
REACH substance restrictions are tightening material sourcing constraints for European COM manufacturers. ECHA's expanding candidate list forces reformulation of solder alloys and PCB laminates, raising qualification costs for industrial temperature-grade modules. German and Swiss medical-device OEMs now specify RoHS-compliant supply chain documentation as a mandatory procurement filter, displacing vendors with opaque material provenance.
Long-term kernel support contracts are displacing traditional hardware-warranty purchasing. German automotive tier-ones and Japanese factory-automation OEMs now negotiate ten-year Linux maintenance agreements as standard procurement terms. This behavioral shift is most visible in safety-critical applications where regulatory file-sets require traceable software update histories across full equipment lifecycles.
Computer on Module Market Segmentation
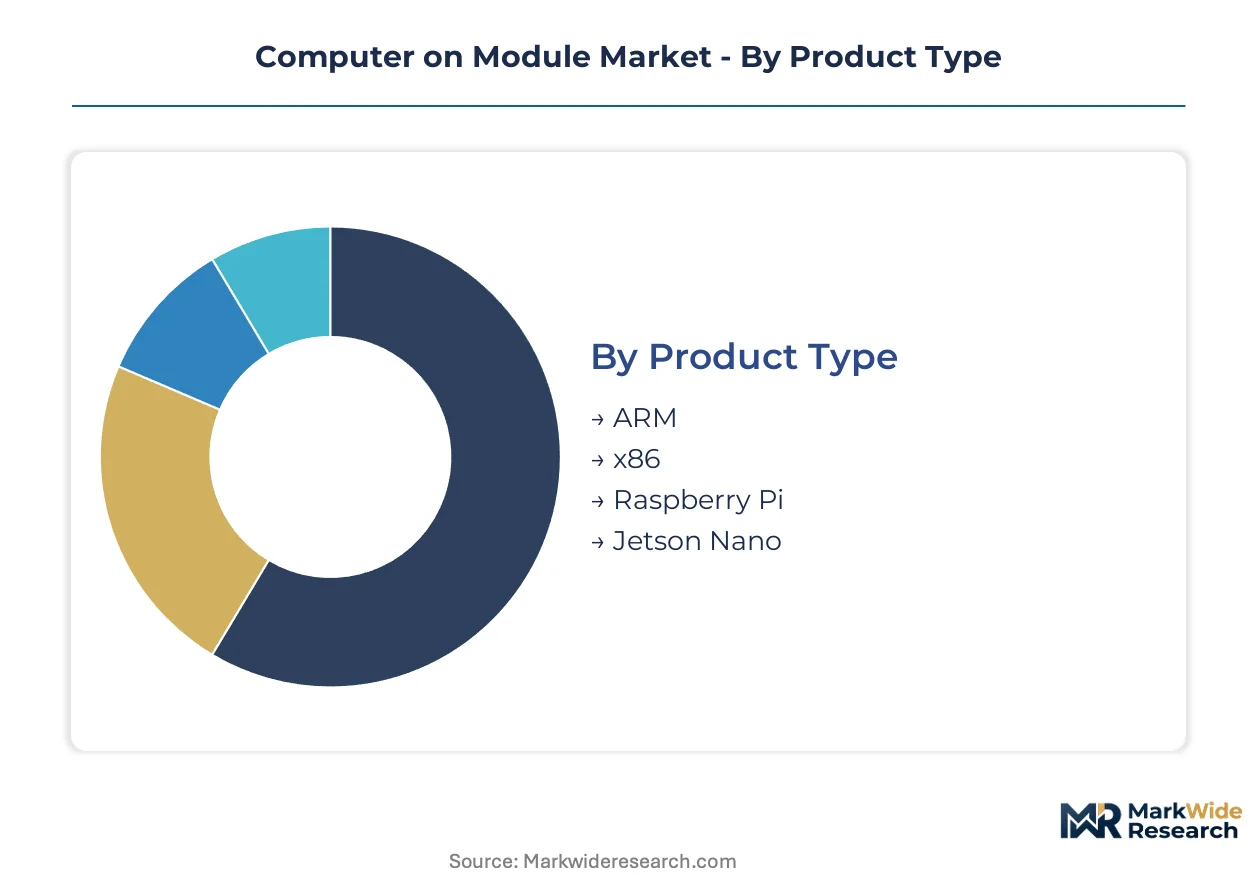
Computer on module segmentation reveals how architectural choices lock OEMs into specific thermal budgets, software ecosystems, and carrier-board redesign cycles. Procurement patterns diverge sharply between factory automation integrators prioritizing legacy x86 compatibility and robotics engineers optimizing for inference-per-watt.
Product Type:
Architectural selection determines software stack compatibility, thermal design power envelopes, and long-term silicon roadmaps available to OEMs.
- x86:Intel and AMD processor-based modules deliver full Windows and legacy industrial software compatibility. German automotive tier-ones and Japanese machine-tool builders specify these for controller retrofits where decade-old HMI software must run unchanged.
- ARM:Qualcomm, NXP, and Rockchip SoC-based modules optimize performance-per-watt for battery-constrained deployments. Italian packaging-machine OEMs and drone manufacturers in Shenzhen are standardizing on ARM for mobile cobot and UAV applications where thermal budgets exclude x86.
- Raspberry Pi:Broadcom SoC-based modules offer cost-optimized compute for educational and prototyping use cases. Makers and low-volume industrial integrators specify these for non-critical monitoring subsystems.
- Jetson Nano:NVIDIA GPU-integrated modules accelerate edge inference workloads. Machine-vision integrators in Japan and medical imaging OEMs in Germany deploy these for real-time defect detection and endoscopic video processing.
x86 leads volumes today; ARM is gaining share fastest.
End User:
Application-specific certification requirements and environmental stress profiles reshape module specification priorities across customer verticals.
- Industrial Automation:PLC replacement and soft-motion controllers demand -40°C to 85°C temperature grades and deterministic I/O. German automotive plants and Japanese semiconductor fabs specify COM Express modules with real-time Ethernet for synchronized multi-axis control.
- Robotics:Mobile cobots and AMRs prioritize watt-per-inference metrics and compact SMARC footprints. Battery endurance constraints in warehouse automation are displacing x86 with ARM-based alternatives.
- Medical Devices:Ultrasound, endoscopy, and patient monitoring equipment require MIPI-CSI camera interfaces and IEC 60601 isolation. Swiss and German OEMs mandate RoHS-compliant supply chain documentation as a procurement filter.
- Consumer Electronics:Digital signage and kiosk builders seek cost-optimized modules with HDMI-native output. These deployments tolerate commercial temperature grades absent in factory-floor applications.
Industrial Automation anchors revenue concentration; Medical Devices shows the steepest expansion trajectory.
Form Factor:
Physical dimensions and connector pinout standards determine carrier-board redesign costs and module interchangeability across processor generations.
- COM Express:The 95mm × 125mm and compact 95mm × 95mm variants dominate factory automation with legacy PCI Express and SATA connectivity. German machine-tool integrators specify Type 6 and Type 10 pinouts for ruggedized controllers.
- SMARC:The 82mm × 50mm short and 82mm × 80mm full-size modules capture space-constrained medical and drone applications. MIPI-DSI display and MIPI-CSI camera interfaces differentiate this standard for imaging-heavy designs.
- Qseven:The 70mm × 70mm legacy standard persists in transportation and outdoor digital signage where carrier-board investments resist migration. Limited pin count constrains high-speed expansion relative to COM Express.
- μQseven:The 40mm × 70mm ultra-compact variant serves wearable industrial devices and portable medical instruments. Connector density challenges limit this form factor to low-I/O applications.
COM Express retains the largest installed base; SMARC climbs the fastest.
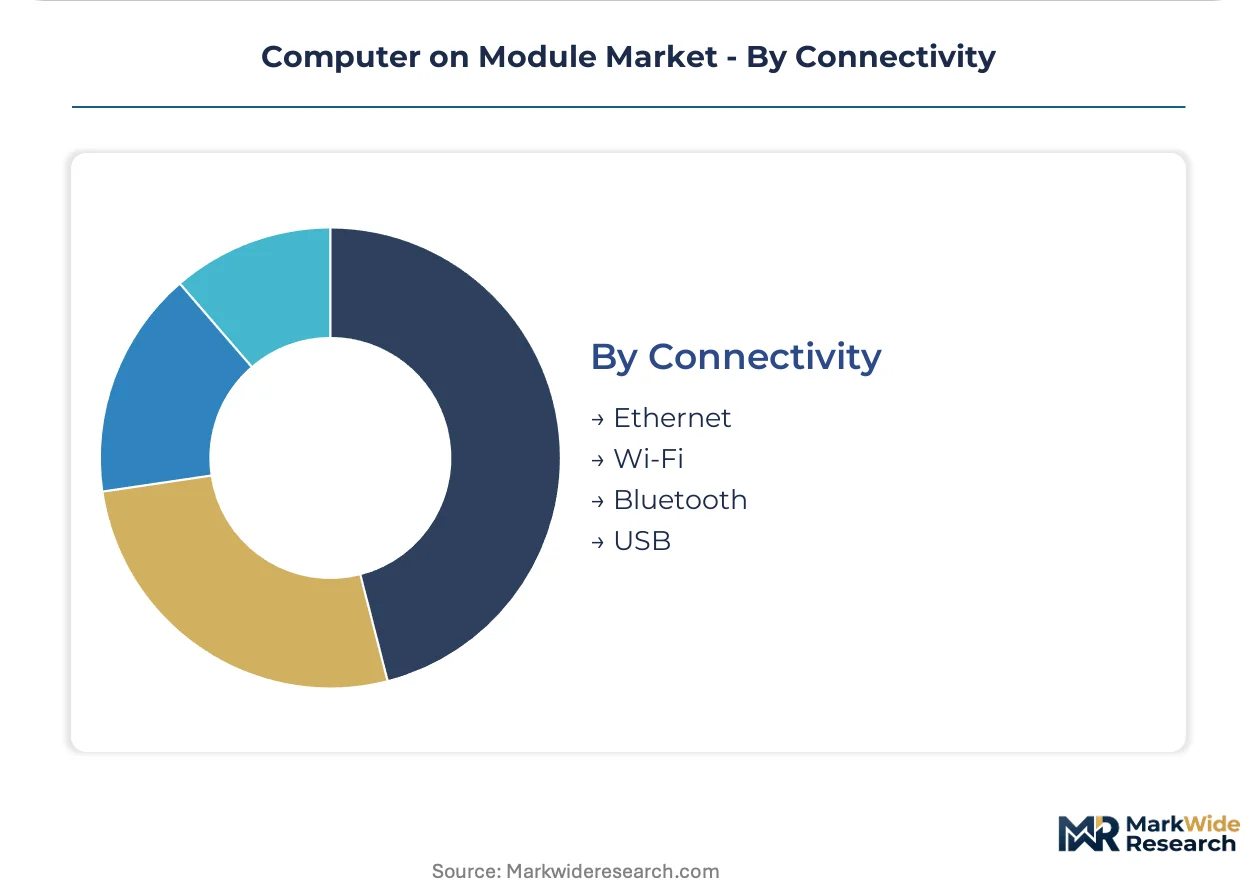
Connectivity:
Peripheral interface selection determines real-time determinism, wireless certification burdens, and cabling complexity in distributed installations.
- Ethernet:Gigabit and multi-gigabit industrial Ethernet with TSN support dominates factory automation. German automotive integrators require PROFINET and EtherCAT conformance for synchronized motion control.
- Wi-Fi:Wi-Fi 6 and 6E modules enable untethered mobile robot communication. FCC electromagnetic compatibility certification in the United States and CE marking in Europe extend module qualification timelines.
- Bluetooth:Low-energy variants support wireless sensor pairing and maintenance tablet connections. Medical device OEMs in Switzerland specify Bluetooth 5.3 for patient monitor peripheral integration.
- USB:USB 3.2 and USB4 interfaces handle camera, storage, and human-interface device attachment. Consumer-facing kiosks and medical carts leverage USB-C for reversible connector convenience.
Ethernet commands the highest specification priority; Wi-Fi is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computer on Module manufacturing traces its industrial roots to German machine-tool engineering and Japanese factory automation, with both countries establishing the foundational standards for modular embedded computing in the 1990s.
Germany
Automotive tier-ones in Stuttgart and Munich specify COM Express Type 6 modules for ADAS validation rigs and battery management controllers. The EU AI Act risk-classification framework forces edge-AI module vendors to document algorithmic transparency before CE marking approval. Bavarian machine-tool integrators anchor procurement volume for ruggedized -40°C to 85°C temperature-grade modules.
Japan
Tokyo and Osaka-based robotics OEMs prioritize ARM-based SMARC modules for mobile cobot deployments where thermal budgets constrain x86 alternatives. METI promotes industrial IoT interoperability through JIS standards that dictate thermal and pinout specifications for modular compute. Nagoya's automotive supply chain concentrates demand for heterogeneous CPU-GPU-NPU fused architectures in vision-processing subsystems.
United States
Silicon Valley machine-vision startups and Austin industrial automation firms drive procurement of NVIDIA Jetson-integrated modules for real-time defect detection. The FCC enforces electromagnetic compatibility standards governing Wi-Fi and Bluetooth subsystems embedded in COM designs. Boston's medical device cluster specifies RoHS-compliant supply chain documentation as mandatory for ultrasound and endoscopy equipment.
China
Shenzhen drone manufacturers and Shanghai medical imaging OEMs adopt compact SMARC form factors for space-constrained designs previously served by custom single-board computers. MIIT oversees GB standards compliance for embedded computing modules deployed in critical infrastructure. Pearl River Delta electronics assemblers concentrate module integration capacity for export-bound industrial controllers.
Switzerland
Zurich and Basel medical device manufacturers mandate IEC 60601 isolation and MIPI-CSI camera interfaces for patient monitoring and diagnostic equipment. Swissmedic oversees hardware certification timelines that extend module qualification cycles for safety-critical applications. The country's precision engineering cluster concentrates procurement of SMARC modules with integrated parallel processing for endoscopic video subsystems.
Computer on Module Market Key Industry Players
The competitive structure tilts toward diversified industrial computing conglomerates with captive foundry partnerships and backward integration into carrier-board design. Tiered specialization separates vendors by thermal qualification depth, form factor breadth, and long-term kernel support contract availability. Two dominant competitive moves define positioning: strategic partnerships with Taiwanese semiconductor foundries for industrial-grade component sourcing, and specialization in medical imaging or robotics subsystems to escape commodity pricing in factory automation.
Among diversified industrial computing conglomerates, Advantech Co., Ltd. and Kontron AG exemplify scale-driven archetypes with captive supply chain control, while congatec AG occupies a position within the form-factor-specialist tier focused on medical imaging subsystems. These three anchors represent divergent strategic postures—foundry partnership leverage, backward integration into carrier-board design, and SMARC specialization respectively—without any single approach commanding decisive advantage across all verticals.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Kontron AG |
| congatec AG |
| ADLINK Technology Inc. |
| AAEON Co., Ltd. |
| Toradex |
| Eurotech S.p.A. |
| Axiomtek Co., Ltd. |
| SECO S.p.A. |
| Others |
Cost & Logistics Intelligence
Industrial temperature-grade certification bifurcation separates premium COM vendors from commodity assemblers, with the divergence manifesting in both pricing power and supply chain depth. German automotive tier-ones pay substantial premiums for -40°C to 85°C qualified modules with decade-long kernel support contracts, while consumer-facing kiosk builders source commercial-grade alternatives through Shenzhen distributors at compressed margins.
Pricing Analysis
Hardware-software bundling versus unbundled module-only procurement splits buyer segments sharply. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and long-term support availability. Price differentiation hinges on REACH-compliant material documentation and ten-year Linux maintenance agreements. Cost compression in the economy tier intensifies because Shenzhen-based assemblers flood digital signage applications with minimally validated alternatives. Medical device OEMs in Switzerland exhibit lowest price sensitivity; consumer electronics integrators in China show highest.
Supply Chain Analysis
Dual-sourcing mandates from German automotive tier-ones force COM vendors to qualify second-source foundries for industrial-grade memory and power management ICs. Manufacturing concentrates in Taiwan, China, and Germany. Component sourcing draws from Taiwanese foundries for -40°C to 85°C rated silicon, Japanese suppliers for high-reliability capacitors, and German PCB fabricators for automotive-grade laminates. Single-source vulnerability persists for specialized industrial temperature-grade memory. Distribution runs through authorized distributors in Stuttgart and Tokyo, direct OEM contracts for volume automotive programs, and Shenzhen trading companies for cost-optimized consumer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward pre-certified edge-AI modules with EU AI Act documentation. German automotive and Swiss medical device OEMs now mandate algorithmic transparency and hardware security as standard procurement filters.
For Market Incumbents: Deepen captive foundry partnerships to secure allocation priority for industrial temperature-grade components when Taiwanese capacity tightens. Expand backward integration into carrier-board design services to lock in socket compatibility across processor generations. ARM-based module specialists threaten x86 incumbents in mobile cobot applications where watt-per-inference metrics dominate specification. For New Entrants and Emerging Players: Japanese machine-tool distributors offer the most accessible channel for JIS-compliant module qualification without competing directly against Advantech and Kontron in German automotive. Target medical imaging subsystems in Switzerland where SMARC form factors with MIPI-CSI interfaces face limited qualified competition. Pursue METI interoperability certification to unlock procurement among Osaka-based robotics OEMs standardizing on modular compute architectures. For Investors and Strategic Acquirers: Consolidation pressure builds where long-term kernel support contracts exceed in-house engineering capacity at sub-scale vendors. Five-to-ten year viability favors specialists with captive foundry relationships and medical imaging certification depth. Acquisition target archetype: SMARC-focused vendors with IEC 60601 isolation expertise and existing Swiss OEM relationships. Watch for EU AI Act pre-market conformity assessment backlogs extending beyond six months as inflection signal for vendor distress.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Kernel Support Contracting | Ten-year Linux maintenance agreements satisfy German automotive tier-one procurement requirements for traceable software histories. |
| EU AI Act Pre-certification | Algorithmic transparency documentation accelerates CE marking timelines for edge-AI modules in Stuttgart ADAS validation programs. |
| SMARC Form Factor Specialization | Compact modules with MIPI-CSI interfaces capture design wins in Swiss endoscopic video processing equipment. |
| Foundry Partnership Diversification | Dual-source qualification for industrial-grade memory ICs mitigates allocation risk from Taiwanese supply concentration. |
| Carrier-board Design Integration | In-house carrier design services lock OEMs into socket-compatible module refresh cycles across processor generations. |
Research Approach
Bottom-up industrial automation and medical device demand modeling reconciled against top-down semiconductor supply tracking forms the analytical core. Primary interviews with embedded systems procurement managers, carrier-board design engineers, COM vendor product marketing directors, and Taiwanese foundry account executives combined with secondary validation from SEC 10-K filings, ECHA REACH substance restriction updates, and METI JIS standard publications. Triangulation across these sources ensures shipment estimates align with silicon allocation data.
Historical trendline analysis of module shipment patterns by form factor and architecture informed projection frameworks across the analysis window. Segmentation dimensions modeled include processor architecture, end-use vertical, form factor standard, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for EU AI Act implementation timelines and REACH substance restriction phase-ins. Forecast inputs incorporate foundry capacity expansion announcements and German automotive production schedules.
Revisions become necessary when Taiwanese foundry allocation priorities shift toward AI accelerators, when ECHA expands restricted substance lists forcing solder alloy reformulation, or when cybersecurity mandates for critical infrastructure fragment compliance regimes across export destinations. Deviation in industrial temperature-grade component lead times would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Australia Content Services Platform Market
Others
Printing Machines Market
Others
Japan Coal Market
Others
Mobile Edge Computing Market
Others
Magnetic Stripe Readers Market
Others
Global OTA Testing Market
Others
Pin Mills Market
Others
Liquid-Cooled Heat Sink Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Fire Sprinkler Market
Others
Smart Home Water Softener Market
Others
Corn Fiber Market
Others
Foldable Smartphone Market
Others
Brazil Lime Market
Others
Solid White Films Market
Others
Solar Panel Testers Market