
 Battery Pack High-Voltage Wiring System Components Market | 2026-2036
Battery Pack High-Voltage Wiring System Components Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Pack High-Voltage Wiring System Components Market Insights
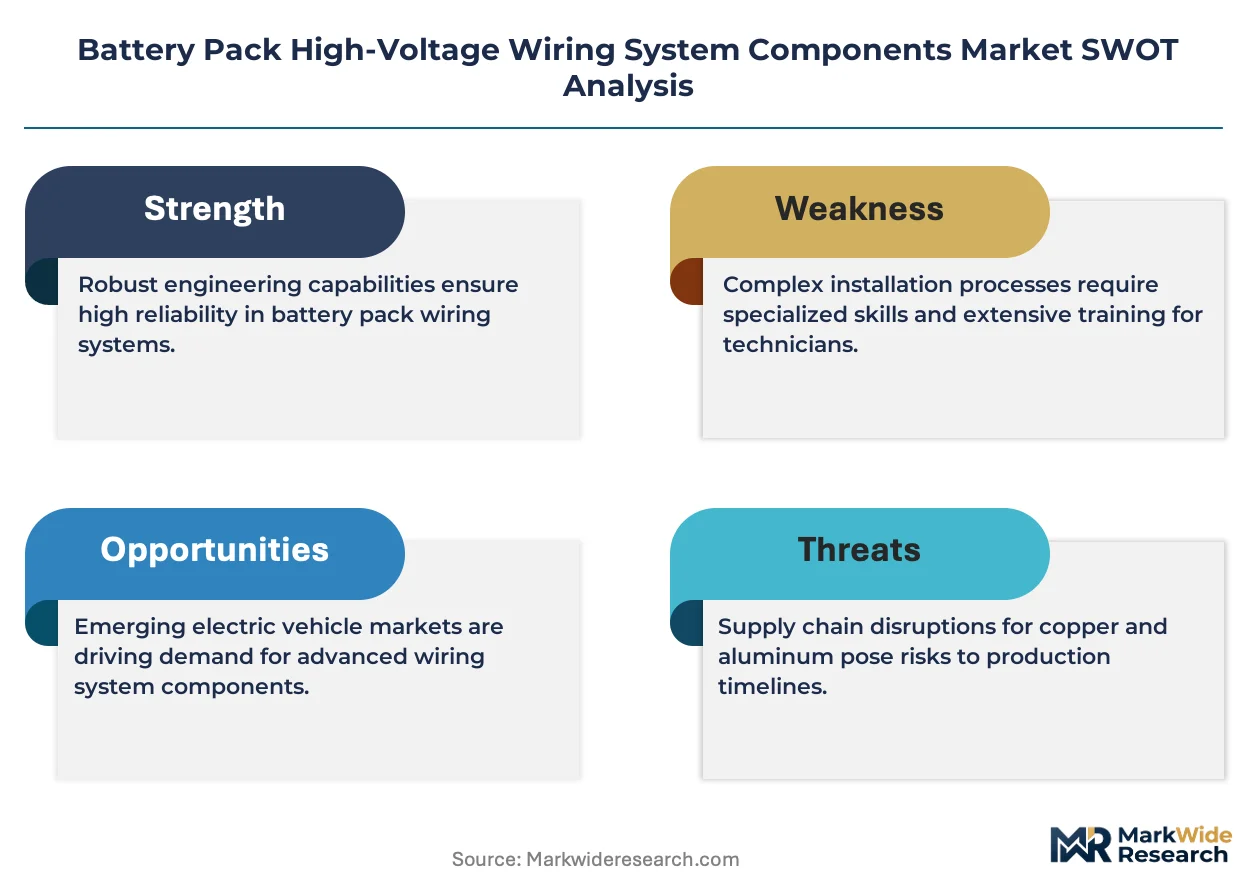
Multi-source procurement from dedicated wiring specialists is repositioning how OEMs secure high-voltage interconnect capacity. TE Connectivity leverages its sensor-connector integration to anchor premium electric vehicle platforms. Yazaki Corporation sustains cost-competitive wire harness production across multiple geographies. Sumitomo Electric Industries specializes in aluminum conductor technology for weight-sensitive battery architectures.
Battery pack high-voltage wiring system components comprise conductors, connectors, and protective assemblies engineered to transmit power above 60V DC between battery modules, inverters, and motors, typically employing shielded copper or aluminum conductors with silicone or cross-linked polyethylene insulation rated for 150°C continuous operation. Their primary purpose is to ensure safe, efficient energy transfer while managing electromagnetic interference and thermal loads in electrified propulsion systems. Connectors and wire harnesses command the largest share of current procurement spend as vehicle electrification scales, while busbars gain share in high-energy-density pack designs where space constraints favor rigid conductor geometries. Lightweight materials technology is attracting the fastest development investment as manufacturers target mass reduction for extended range.
China's GB standards and NMPA vehicle safety protocols mandate specific insulation grades and flame-resistance thresholds for high-voltage automotive wiring. Europe's REACH and RoHS frameworks restrict hazardous substances in cable sheathing and connector plating, directly influencing material selection across the supply base. The EU Green Deal's embodied carbon requirements are beginning to shape supplier qualification criteria for battery system components. Stakeholders must monitor how evolving thermal runaway propagation standards redefine protective sleeve specifications and test protocols.
Market Dynamics
The transition to 800V electrical architectures is compressing design cycles and forcing wholesale requalification of insulation materials, connector sealing, and electromagnetic shielding across battery pack wiring systems.
Growth Catalysts
- 800V Platform Migration:Electric vehicle OEMs are accelerating high-voltage architecture deployment to enable faster charging and reduce copper mass, directly expanding demand for upgraded interconnect components.
- Europe's F-Gas Regulation:Restrictions on fluorinated greenhouse gases in cable insulation and cooling systems are accelerating adoption of silicone and cross-linked polyethylene alternatives with equivalent thermal performance.
- China's GB/T Charging Protocol:Mandatory high-power charging standards are standardizing connector geometries and current ratings, creating procurement volume concentration around certified component suppliers.
Market Restraints
- Copper Price Volatility:Raw material cost swings for high-conductivity copper rod directly compress margin visibility for harness manufacturers locked into annual automotive supply agreements.
- German Supply Concentration:Tier-1 wiring harness production clusters heavily around Stuttgart and Munich, creating geographic vulnerability to single-point logistics disruptions or labor actions.
- Aluminum Conductor Limitations:Cold-creep behavior and oxidation sensitivity in aluminum terminations restrict deployment in high-vibration battery pack zones despite weight advantages.
Strategic Opportunities
- India's PLI Scheme for Auto Components:Production-linked incentives for advanced automotive electronics and electrification components are attracting harness investment into Tamil Nadu and Gujarat manufacturing corridors.
- Thermal Runaway Containment Systems:Integrating fire-resistant mica sleeves and ceramic-coated busbars into battery pack wiring creates new product categories with premium pricing potential.
- Sensor-Connector Convergence:Embedding temperature and current sensors directly into high-voltage connectors is integrating diagnostic capability and reducing separate component counts.
Industry Challenges
- High-Voltage Safety Certification Bottlenecks:Extended validation timelines for IEC 60664-1 clearance and creepage requirements delay new product introductions by 12-18 months.
- Electromagnetic Compatibility Engineering Shortage:Scarce expertise in shielding design for 800V switching frequencies limits supplier capacity to support simultaneous customer programs.
- Legacy Vehicle Platform Support:Maintaining 400V component production while scaling 800V capacity strains capital allocation and manufacturing line flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Pack High-Voltage Wiring System Components Market |
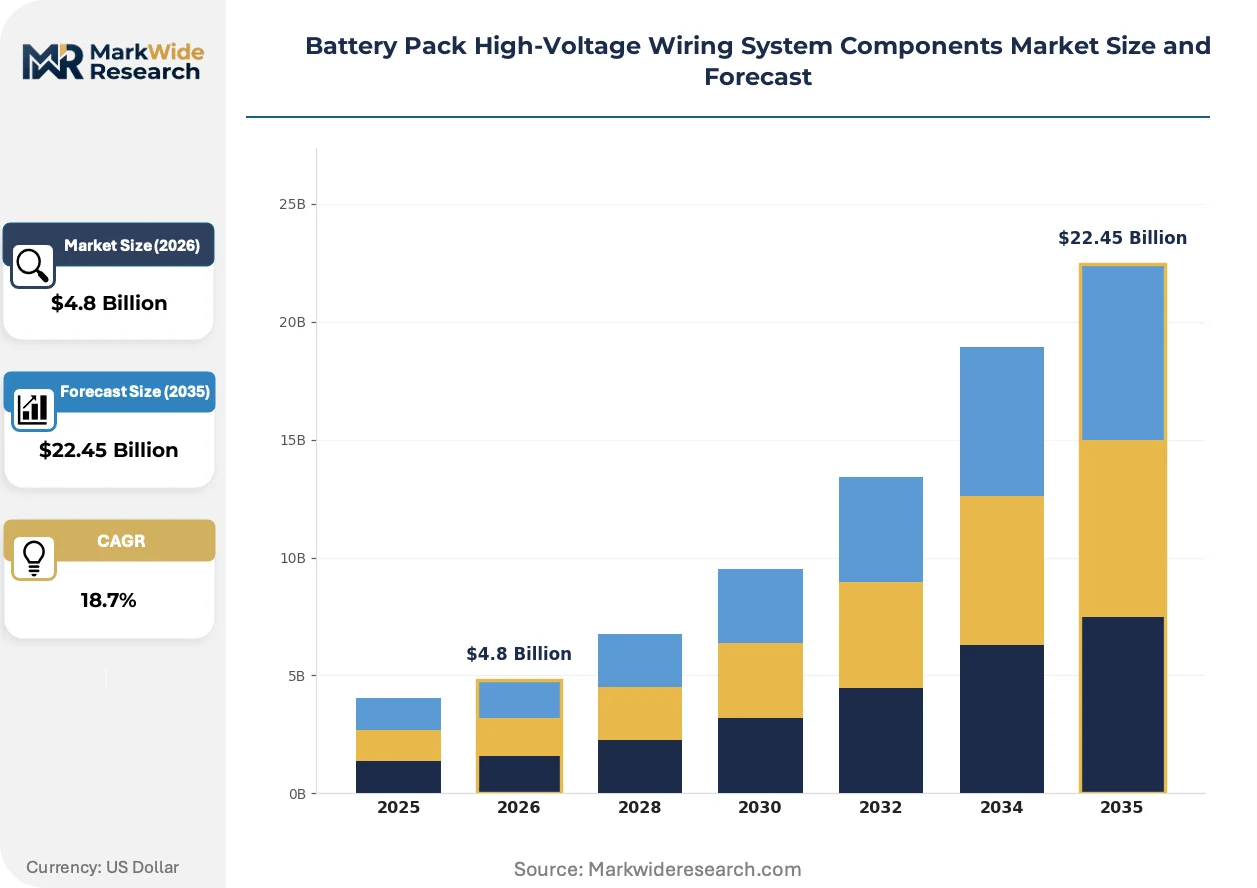
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Cables, Busbars, Wire Harnesses, Protective Sleeves Application: Electric Vehicles, Renewable Energy Storage, Industrial Automation, Aerospace Equipment, Rail Transit End User: OEMs, Tier-1 Suppliers, Aftermarket Specialists, Vehicle Assemblers, Equipment Manufacturers Technology: Low Resistance, Lightweight Materials, High Thermal Stability, Enhanced Durability, Modular Design |
| Companies Covered | TE Connectivity, Aptiv, Yazaki Corporation, Sumitomo Electric Industries, Amphenol, Leoni, Lear Corporation, Furukawa Electric, LS Cable & System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Pack High-Voltage Wiring System Components Market Trends and Innovations
Material science breakthroughs and regulatory tightening on fire safety are actively reshaping how battery pack wiring systems are engineered, sourced, and validated for next-generation electric vehicles.
Aluminum conductor technology is integrating composite core designs with copper-clad terminations to solve cold-flow and galvanic corrosion challenges. Weight-sensitive battery pack architects at premium electric vehicle platforms are adopting these hybrid conductors for module-to-module busbars. The technology is integrating mass reduction targets with maintained electrical reliability, compressing the historical performance-versus-weight tradeoff in high-voltage distribution.
Europe's REACH and RoHS frameworks are restricting halogenated flame retardants and heavy metal plating in cable sheathing and connector finishes. Suppliers are reformulating insulation compounds with phosphorus-nitrogen intumescent systems and switching to tin-bismuth alloy coatings. High-voltage harness manufacturers serving German automotive OEMs face the most immediate material qualification pressure, with 2025 compliance deadlines forcing accelerated vendor audits.
Direct sourcing from dedicated wiring specialists is displacing bundled procurement through traditional Tier-1 system integrators. Battery pack manufacturers and electric vehicle OEMs are establishing technical relationships with connector and conductor specialists to secure capacity and co-develop 800V-compatible designs. This pattern is most visible in China's Yangtze River Delta, where NEV startups are bypassing established harness distributors to contract directly with component technology providers.
Battery Pack High-Voltage Wiring System Components Market Segmentation
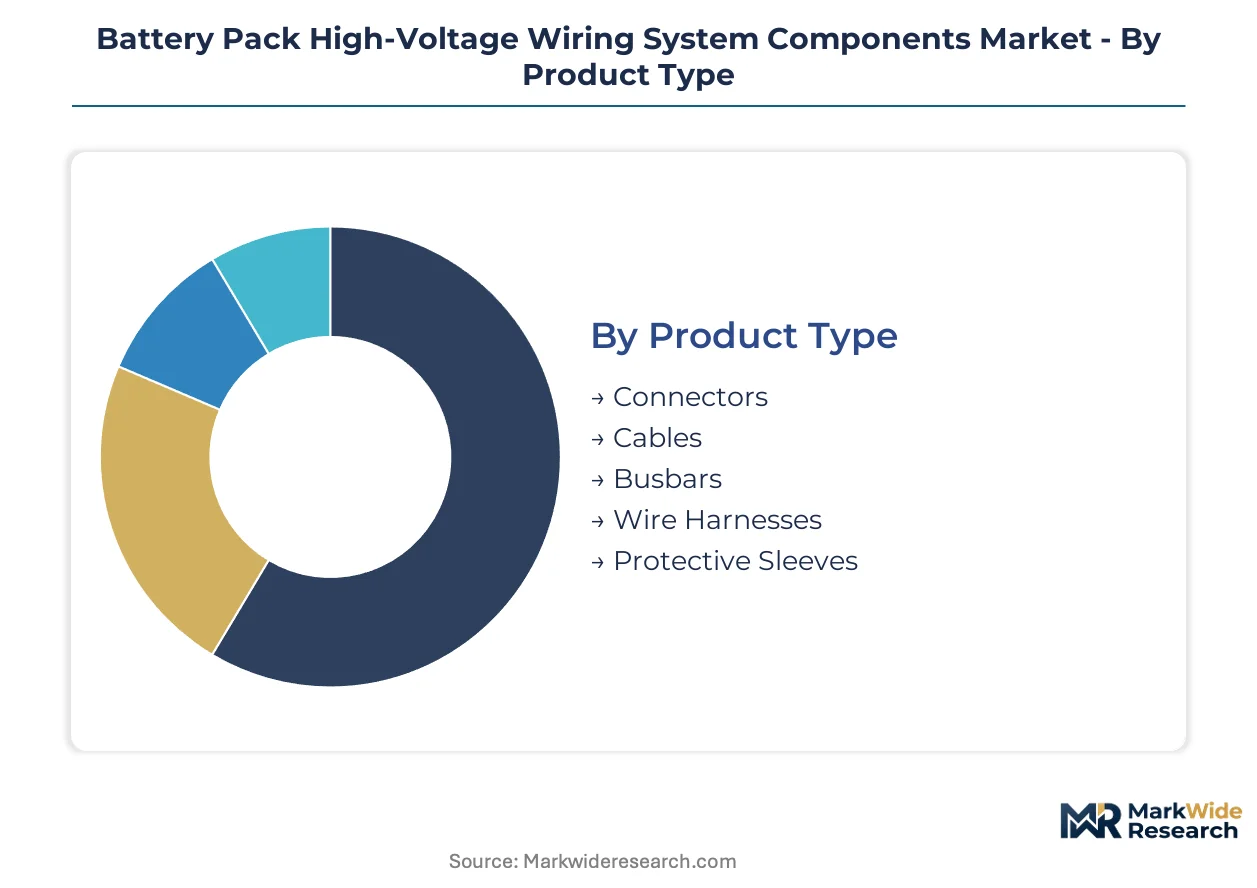
High-voltage wiring procurement patterns diverge sharply across product architectures and end-use applications. OEM sourcing strategies prioritize different performance thresholds depending on whether components serve passenger vehicles, grid storage, or industrial equipment.
Product Type:
Connectors and wire harnesses demand the heaviest upfront tooling investment due to precision molding and automated assembly requirements. Busbars and protective sleeves require less capital intensity but impose stricter material qualification cycles.
- Connectors:Multi-pin sealed assemblies with silicone gaskets and electromagnetic shielding rated for 800V operation. German automotive OEMs concentrate procurement around Stuttgart-based Tier-1 suppliers to satisfy ECHA REACH compliance timelines.
- Cables:Shielded copper or aluminum conductors with cross-linked polyethylene or silicone insulation rated for 150°C continuous duty. China's NEV manufacturers in the Yangtze River Delta drive volume demand as GB/T charging protocols standardize current ratings.
- Busbars:Rigid conductor systems for module-to-module power distribution.
- Wire Harnesses:Integrated cable-connector assemblies with routing and retention features.
- Protective Sleeves:Fire-resistant mica or ceramic coatings for thermal runaway containment.
Wire harnesses absorb the bulk of installed capacity; protective sleeves are expanding most quickly as thermal runaway standards tighten.
Application:
Cost tiers separate passenger electric vehicles from industrial and aerospace deployments. Premium pricing in aerospace and rail transit subsidizes development costs that later cascade into mass-market automotive applications.
- Electric Vehicles:Battery pack, inverter, and motor interconnect systems for passenger and commercial vehicles. European OEMs accelerate 800V migration under F-Gas Regulation pressure, compressing design cycles for insulation materials.
- Renewable Energy Storage:Grid-scale battery interconnect for solar and wind integration. Utility procurement in Germany favors busbar-heavy designs where space constraints matter less than cost per megawatt-hour.
- Industrial Automation:Factory equipment and robotics power distribution.
- Aerospace Equipment:Weight-optimized interconnect for electric aircraft propulsion.
- Rail Transit:Traction power systems for electrified passenger and freight networks.
Electric vehicles command the dominant procurement volume; aerospace equipment follows the steepest expansion trajectory as electrified flight demonstrators mature.
End User:
Customer type determines contract structure and technical collaboration depth. Direct OEM relationships favor co-development models, while aftermarket channels prioritize inventory availability over customization.
- OEMs:Vehicle and equipment manufacturers specifying proprietary connector geometries and validation protocols. Chinese NEV startups increasingly bypass traditional distributors to contract directly with wiring specialists.
- Tier-1 Suppliers:System integrators bundling harnesses with battery management electronics.
- Aftermarket Specialists:Replacement component distributors serving repair networks.
- Vehicle Assemblers:Contract manufacturers requiring rapid line-feed logistics.
- Equipment Manufacturers:Industrial and energy storage system builders.
OEMs dominate forward capacity commitments; Tier-1 suppliers retain the largest installed production footprint.
Technology:
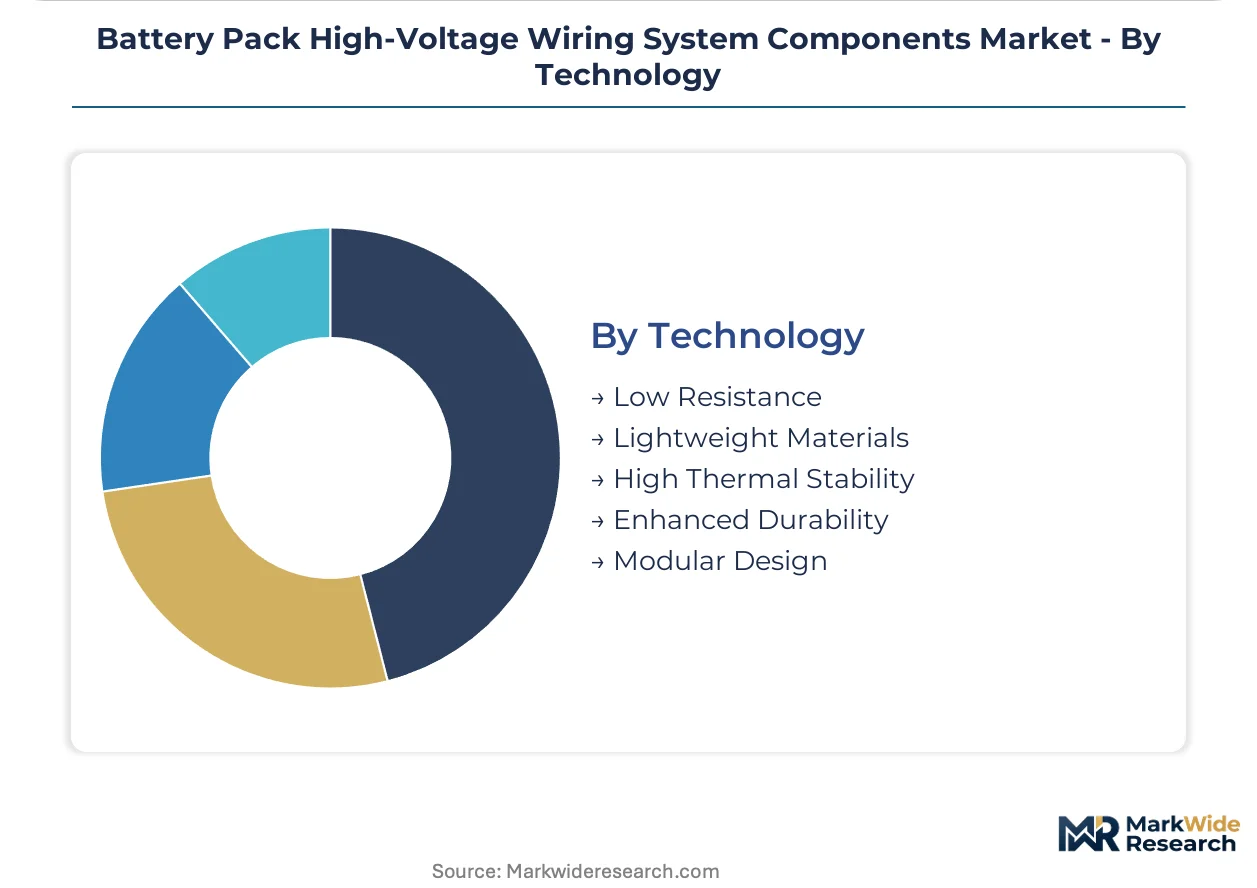
Volume concentration sits with proven low-resistance and durability platforms, while lightweight and thermal stability innovations attract development investment for next-generation architectures.
- Low Resistance:Optimized conductor geometries and contact plating to minimize I²R losses. European suppliers reformulate under EU Green Deal embodied carbon criteria while maintaining IEC 60664-1 clearance compliance.
- Lightweight Materials:Aluminum conductors and composite cores replacing copper mass. Premium EV platforms adopt hybrid copper-clad aluminum terminations to solve cold-creep and oxidation limitations.
- High Thermal Stability:Insulation systems rated for sustained elevated temperatures.
- Enhanced Durability:Vibration and contamination resistance for harsh environments.
- Modular Design:Field-serviceable connector systems with standardized interfaces.
Low resistance technology anchors current production scale; lightweight materials gain share fastest as mass reduction targets intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volume concentrates where electric vehicle manufacturing clusters intersect with high-voltage platform mandates. National regulators are accelerating design cycle compression through charging protocol standardization and material safety specifications.
China
NEV manufacturers in the Yangtze River Delta drive connector and cable demand as GB/T charging protocols standardize current ratings. MIIT and NMPA vehicle safety protocols mandate specific insulation grades and flame-resistance thresholds for high-voltage automotive wiring. Shenzhen and Shanghai host direct sourcing relationships between battery pack manufacturers and wiring specialists, bypassing traditional Tier-1 distributors.
Germany
Automotive OEMs accelerate 800V migration under ECHA REACH and F-Gas Regulation pressure, compressing qualification timelines for insulation materials. Stuttgart and Munich anchor Tier-1 wiring harness production clusters serving premium electric vehicle platforms. KBA vehicle type approval requirements enforce electromagnetic compatibility standards that shape connector shielding specifications across the supply base.
United States
Domestic battery gigafactories in the Midwest and Southeast expand procurement of module-to-module interconnect systems. NHTSA safety standards and state-level zero-emission vehicle mandates influence high-voltage component validation protocols. Michigan and Tennessee manufacturing corridors attract harness investment to support localized electric vehicle assembly capacity.
Japan
Automotive electronics specialists supply weight-optimized conductor technology for next-generation battery architectures. METI industrial policy and JIS standards govern high-voltage cable performance specifications for domestic and export markets. Nagoya and Tokyo metropolitan areas concentrate connector development expertise for 800V-compatible designs.
India
Production-linked incentives for advanced automotive electronics attract harness investment into Tamil Nadu and Gujarat manufacturing corridors. BIS standards and the PLI scheme for auto components accelerate supplier qualification for high-voltage interconnect capacity. Chennai and Ahmedabad emerge as focal points for export-oriented wiring component fabrication.
Battery Pack High-Voltage Wiring System Components Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers race to qualify 800V-compatible designs before platform launches. The vendor base separates into three tiers: integrated connector-conductor specialists, cost-optimized harness manufacturers, and materials technology innovators. Strategic archetypes include sensor-integrated platform anchors, multi-geography volume producers, and aluminum conductor weight-reduction specialists. M&A activity and direct OEM technical partnerships represent the dominant competitive vectors reshaping supply relationships.
Within the integrated platform tier, TE Connectivity and Yazaki Corporation exemplify divergent geographic and technical positioning strategies. TE Connectivity occupies a position as a sensor-connector integration specialist anchoring premium electric vehicle programs. Yazaki Corporation sits within the cost-competitive volume tier, sustaining multi-continent production footprints. Sumitomo Electric Industries represents the materials innovation archetype, specializing in aluminum conductor technology for mass-sensitive battery pack architectures.
| Leading Market Players |
|---|
| TE Connectivity |
| Aptiv |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Amphenol |
| Leoni |
| Lear Corporation |
| Furukawa Electric |
| LS Cable & System |
| Others |
Pricing and Supply Chain Analysis
Electromagnetic compatibility engineering talent clusters in Germany's Stuttgart-Munich corridor compress labor-cost differentials between premium sensor-integrated harnesses and standard commodity assemblies. Tier-1 suppliers leverage this concentration to command pricing premiums for 800V-qualified designs while offshoring volume production to lower-cost manufacturing zones.
Pricing Analysis
Warranty and validation service bundling separates premium-tier suppliers from unbundled commodity producers. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 60664-1 certification grade and volume commitment scale. Cost compression in standard-grade harnesses intensifies because Chinese NEV manufacturers negotiate direct contracts with wiring specialists. Fleet procurement teams at commercial vehicle OEMs exhibit highest price sensitivity, while aerospace equipment buyers prioritize weight-optimized performance over unit cost.
Supply Chain Analysis
IEC 60664-1 clearance and creepage qualification gates filter supplier access to 800V platform contracts. Manufacturing concentrates in Germany, China, and Japan, with raw material feeds drawing from Chilean copper rod and Chinese silicone polymer production. Single-source vulnerability sits with high-purity copper rod suppliers locked into annual automotive supply agreements. Distribution runs through Tier-1 system integrators toward OEM assembly plants, though direct sourcing from wiring specialists is displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over aluminum conductor metallurgy and 800V connector sealing technology determines margin capture. Players pursue backward integration into high-purity copper rod and silicone polymer compounding to defend pricing power.
For Market Incumbents: Hedge against aluminum conductor substitution by securing long-term offtake agreements with Chilean copper smelters and accelerating composite-core conductor R&D. TE Connectivity and Yazaki Corporation anchor positions through sensor-connector integration patents, but emerging Chinese wiring specialists threaten volume share in GB/T-certified applications. Incumbents should deepen backward integration into electromagnetic shielding material production.
For New Entrants and Emerging Players: Thermal runaway containment sleeve technology offers a technology-first wedge into premium electric vehicle supply chains. India's Tamil Nadu manufacturing corridor presents the most penetrable geography given PLI scheme subsidies and underdeveloped local harness capacity. New entrants should pursue direct technical partnerships with NEV battery pack manufacturers rather than Tier-1 distributor channels.
For Investors and Strategic Acquirers: Re-rating potential sits with aluminum conductor specialists given EU Green Deal embodied carbon requirements and mass reduction mandates. Long-term viability favors suppliers with dual 400V/800V platform flexibility and qualified capacity across three continental manufacturing zones. The signal to watch is KBA type approval timeline compression for new insulation material formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| 800V Platform Qualification | IEC 60664-1 certification unlocks premium electric vehicle procurement contracts at German OEMs. |
| Aluminum Conductor Scale-Up | Hybrid copper-clad termination technology addresses cold-creep limitations in high-vibration battery zones. |
| Direct OEM Technical Partnership | Bypassing Tier-1 distributors secures capacity allocation and co-development influence with NEV manufacturers. |
| Thermal Runaway Sleeve Integration | Fire-resistant mica and ceramic coatings create new product categories with premium pricing potential. |
| India PLI Manufacturing Footprint | Tamil Nadu and Gujarat corridors offer cost-competitive export capacity for GB/T-compliant harnesses. |
Research Methodology
Multi-period observation of 800V platform deployment timelines, GB/T charging protocol adoption rates, and F-Gas Regulation compliance deadlines anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, electromagnetic compatibility engineering leads, and aftermarket distribution specialists. Secondary validation drew from MIIT vehicle safety filings, ECHA REACH substance restrictions, KBA type approval databases, and customs trade data for copper rod and silicone polymer imports. Bottom-up segment sizing triangulated against top-down electric vehicle production forecasts.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework throughout the forecast period. CAGRs derived from fitted growth curves applied to battery pack wiring content per vehicle, scaled by regional electric vehicle production clusters. Industry-specific inputs included 800V architecture migration curves, aluminum conductor adoption rates in mass-sensitive designs, and thermal runaway containment standard evolution.
Several conditions sit outside the modeled scope, including sudden copper price volatility spikes, labor action disruptions in Germany's harness production corridor, and unanticipated regulatory acceleration in halogenated flame retardant restrictions. Forecasts reflect assumptions about OEM platform launch timing and supplier qualification cycle duration. A model refresh is warranted upon material change in IEC thermal runaway propagation test protocols or ECHA REACH substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
North America Micro Inverter Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Global Rectifier Market
Power Systems
Low Voltage Drives Market
Power Systems
PV Inverter Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Integrated UPS Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
EV Power Module Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
DC Stabilized Power Supply Market