
 Dynamite Market | 2026-2036
Dynamite Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamite Market Analysis
Australia's Western Australia mining belt is fragmenting as new capacity enters the packaged explosives space. Orica Limited leverages its integrated blasting services model to sustain contract renewal rates across Pilbara iron ore operations. Dyno Nobel competes through ammonium nitrate supply chain control, while Solar Industries India Ltd anchors its position in African copperbelt contracts through localized manufacturing partnerships.
Dynamite comprises nitroglycerin-sensitized blasting agents typically formulated with ammonium nitrate, carbonaceous fuels, and stabilizing gels, designed to generate controlled gas pressure for rock fragmentation in confined drill holes. The product type dimension shows industrial-grade formulations dominating volume, with emulsion-based forms capturing margin pools due to water resistance and detonation velocity control. Mining applications absorb the majority of throughput, though quarrying segments exhibit faster structural growth as aggregate demand intensifies near urban construction zones.
OSHA workplace exposure limits and EPA air quality standards constrain formulation chemistry and handling protocols across the United States, while China's SAMR enforces GB standards on explosive manufacturing licensing and transport classification. The EU's REACH framework governs nitroglycerin precursor chemical registration and downstream safety documentation. Stakeholders must monitor evolving fragmentation between legacy nitroglycerin-based products and bulk emulsion alternatives when allocating R&D budgets and regional distribution assets.
Market Dynamics
The transition from nitroglycerin-sensitized cartridges to bulk emulsion delivery systems is fragmenting supplier relationships across hard-rock mining corridors, forcing reformulation investments and rewriting contract structures for blasting services.
Growth Catalysts
- Mechanized blasting intensity:South African platinum and gold extraction corridors are expanding drill-and-blast automation, driving packaged emulsion consumption per meter of advance.
- REACH framework compliance:EU chemical registration mandates for nitroglycerin precursors are accelerating documentation investments that favor established suppliers with regulatory infrastructure.
- Urban aggregate demand:Quarrying operations near construction zones in Australia and India are absorbing water-resistant emulsion formulations for wet-bench blasting.
Market Restraints
- Ammonium nitrate supply concentration:Fertilizer-to-explosive feedstock competition concentrates pricing power with integrated chemical producers in China and Russia.
- OSHA exposure limits:Workplace nitroglycerin vapor thresholds constrain formulation potency and handling labor productivity across US surface operations.
- Emulsion substitution:Bulk pumped systems displace packaged cartridges in large-scale open-pit copper, compressing dynamite's addressable tonnage in tier-one deposits.
Strategic Opportunities
- Indonesian nickel laterite expansion:Sulawesi and Halmahera mining concessions are greenfield sites without legacy explosive infrastructure, open to emulsion-delivery system partnerships.
- China GB standard tightening:SAMR licensing requirements for industrial explosive manufacturing are raising barriers for uncertified competitors, consolidating share for compliant domestic producers.
- Drone-enabled blast monitoring:Convergence of detonation velocity sensors with unmanned aerial survey platforms enables outcome-based fragmentation optimization contracts.
Industry Challenges
- Blast engineering talent scarcity:Specialized expertise in electronic detonator timing and vibration control is concentrating with aging practitioners in South Africa and Australia.
- Dual-certification timelines:Cross-border product registration under both China's GB standards and Australia's Dangerous Goods codes extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamite Market |
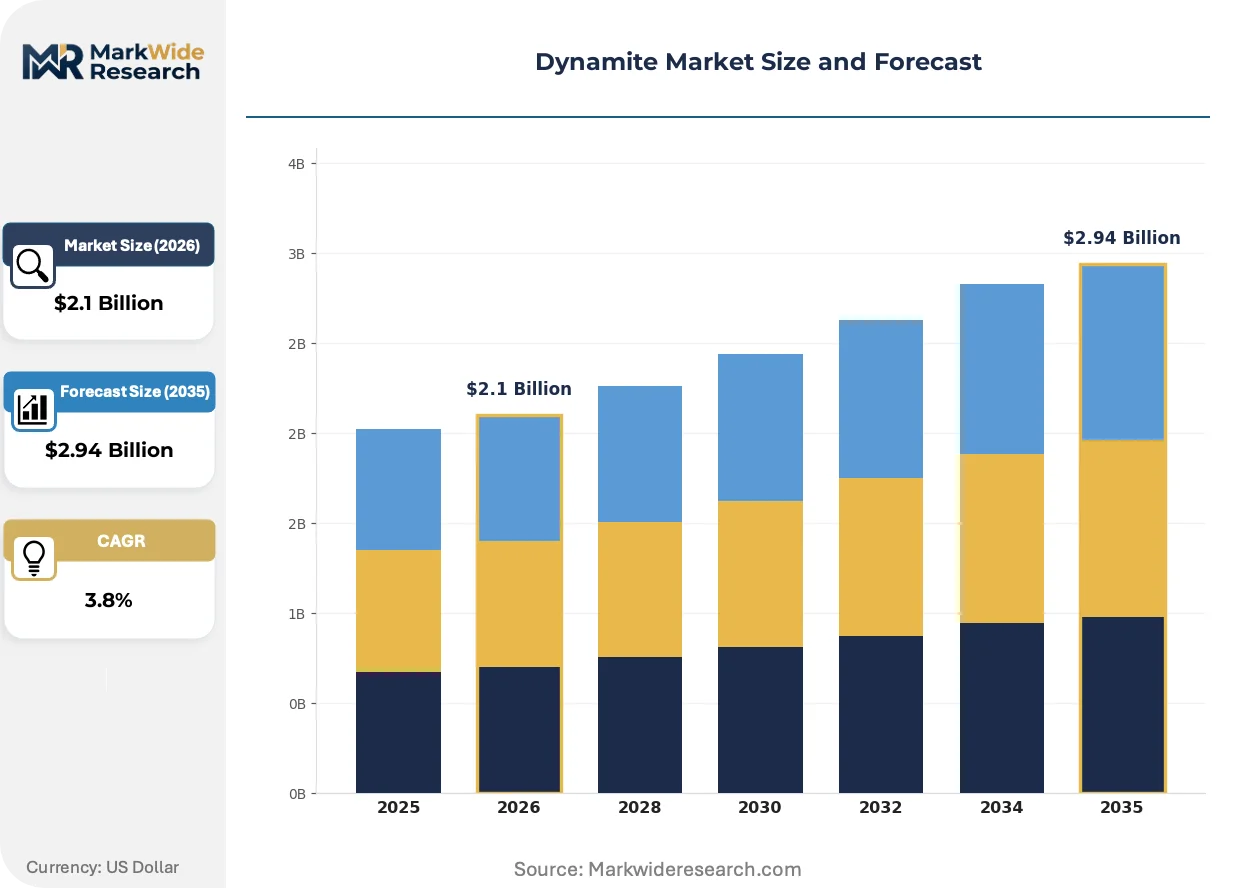
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial, Commercial, Military, Pyrotechnics Form: Gel, Powder, Emulsion, Solid Application: Mining, Construction, Demolition, Quarrying Regulatory Compliance: OSHA, EPA, NFPA, Local Regulations |
| Companies Covered | ENAEX S.A., AECI Limited, Orica Limited, Solar Industries India Ltd, Sasol Limited, Dyno Nobel, Austin Powder Company, TITANOBEL, MAXAM Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamite Market Emerging Trajectories
Blasting operations are digitizing fragmentation prediction and reshaping how explosive energy couples to rock mass, compressing the feedback loop between drill pattern design and muckpile outcomes.
Electronic detonation systems with programmable delay timing are virtualizing the role of traditional pyrotechnic fuse caps in controlled blasting sequences. Underground operators in Canada's Sudbury Basin and Sweden's Kiruna district are adopting these systems at replacement rates exceeding 40% annually for new headings. The technology is virtualizing inventory management for distributors who previously stocked dozens of pyrotechnic delay intervals, collapsing SKUs to software-defined timing profiles.
China's GB 28263-2012 safety standards for industrial explosive manufacturing are tightening licensing audits and transport classification protocols. The regulation requires real-time production monitoring and traceable batch records, elevating capital requirements for facility upgrades. Domestic producers in Shanxi and Sichuan provinces are consolidating smaller licensed operations to spread compliance costs across volume, while foreign suppliers face extended certification timelines for imported formulations.
Integrated blasting service contracts are displacing product-only procurement in tier-one mining jurisdictions. Anglo American and Rio Tinto operations in Chile and Western Australia now specify fragmentation size distribution guarantees rather than explosive tonnage, transferring rock-breakage risk to Orica and Dyno Nobel service crews. The model concentrates margin with vertically integrated suppliers who control drill rig fleets, survey drones, and post-blast analytics platforms.
Dynamite Market Segmentation
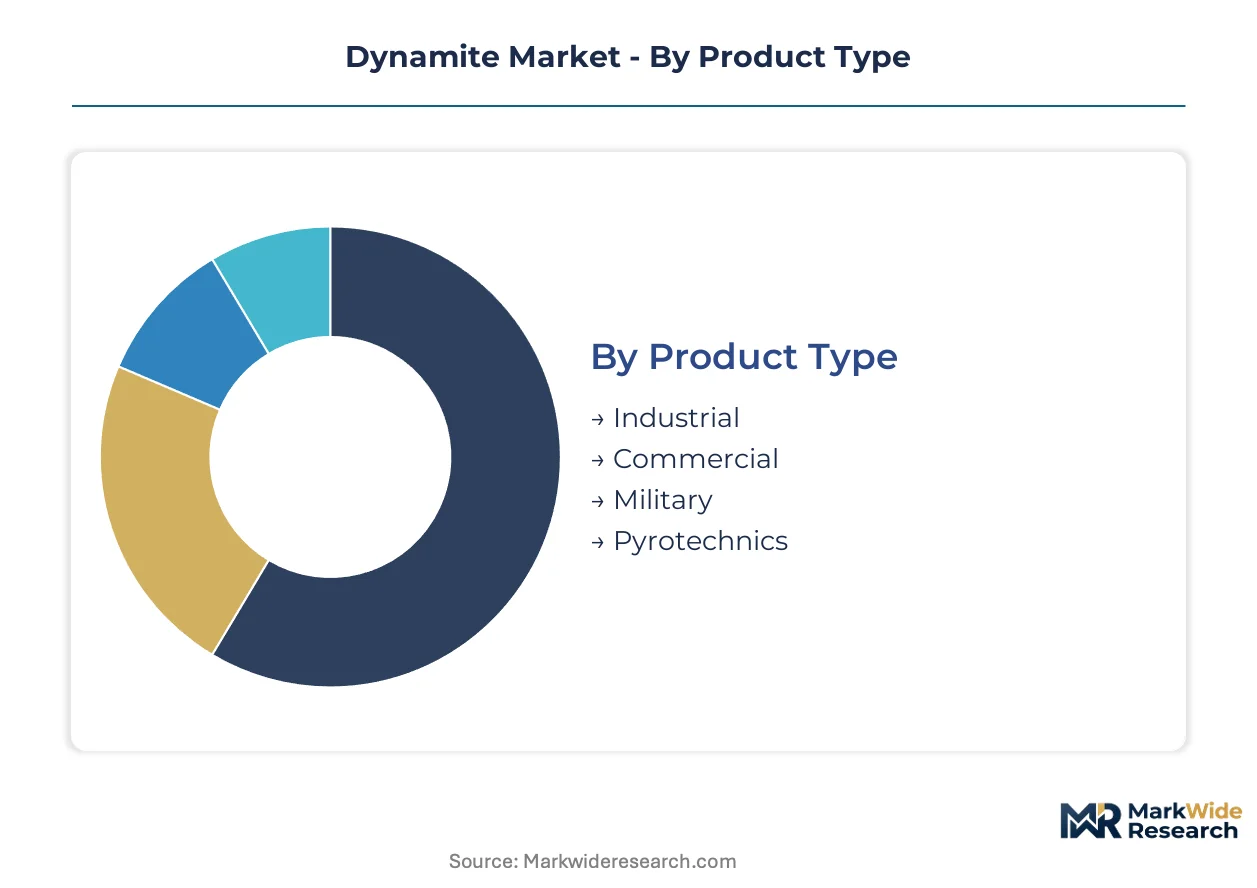
Dynamite market segmentation reveals how formulation chemistry, physical state, end-use environment, and safety protocols fragment demand across incompatible use cases. Each dimension carries distinct margin profiles and regulatory burdens that reshape supplier positioning.
Product Type:
Industrial operators demand nitroglycerin-sensitized formulations for controlled gas pressure generation in hard-rock fragmentation, while commercial buyers prioritize handling safety over detonation velocity.
- Industrial:Ammonium nitrate-carbonaceous fuel blends with nitroglycerin sensitization dominate underground mining in Australia's Western Australia belt and South Africa's platinum corridors. Drill-and-blast automation in mechanized headings drives cartridge consumption per meter of advance.
- Commercial:Reduced-sensitivity formulations with stabilized gel matrices serve construction demolition and specialized quarrying where transport restrictions limit high-nitroglycerin products. Urban aggregate operations near Australian and Indian construction zones absorb water-resistant variants for wet-bench blasting.
- Military:Specialized compositions meet defense procurement specifications for demolition charges and breaching applications, with demand concentrated through national arsenals and defense contractors.
- Pyrotechnics:Low-velocity formulations support controlled entertainment and signaling applications with distinct licensing requirements separate from industrial explosive frameworks.
The dominant share belongs to Industrial, while Commercial is closing the gap fastest.
Form:
Physical state determines water resistance, loading efficiency, and compatibility with mechanized delivery systems across wet and dry blasting environments.
- Emulsion:Water-in-oil microsphere suspensions with controllable detonation velocity capture margin pools in wet underground conditions. Sulawesi and Halmahera nickel laterite operations specify emulsion-delivery systems for greenfield sites lacking legacy cartridge infrastructure.
- Gel:Nitroglycerin-sensitized colloidal suspensions with stabilizing agents maintain plasticity across temperature ranges, serving traditional cartridge loading in South African gold extraction where mechanized pumping remains uneconomical.
- Powder:Porous ammonium nitrate-fuel oil blends offer cost advantages in dry surface mining with simplified handling protocols.
- Solid:Cast or pressed formulations serve specialized military and demolition applications requiring precise shape charge geometry.
Emulsion commands the premium tier, though Gel retains volume leadership in legacy mining jurisdictions.
Application:
End-use intensity varies from continuous production blasting to intermittent demolition cycles, fragmenting procurement patterns and service contract structures.
- Mining:Underground and surface extraction operations consume packaged explosives through integrated blasting service contracts. Rio Tinto and Anglo American operations in Chile and Western Australia now specify fragmentation size distribution guarantees rather than explosive tonnage, transferring rock-breakage risk to service crews.
- Quarrying:Urban aggregate operations near construction zones in Australia and India exhibit steepest expansion trajectory as infrastructure demand intensifies wet-bench blasting with water-resistant formulations.
- Construction:Controlled demolition and foundation excavation require precision timing and vibration control, concentrating demand with electronic detonation systems.
- Demolition:Structural takedown and rock excavation for civil works operate on project-based procurement with irregular volume patterns.
Mining absorbs the majority of throughput, yet Quarrying gains share fastest.
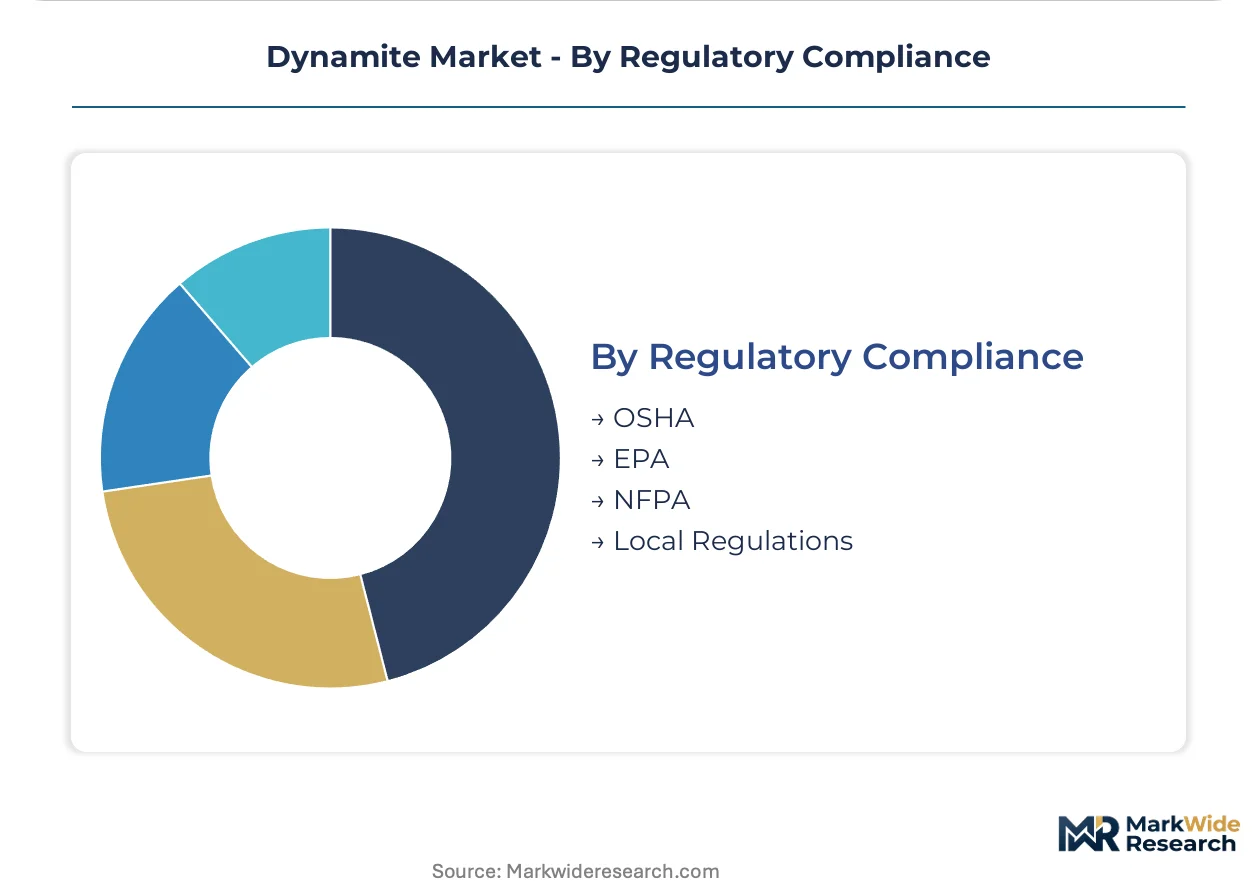
Regulatory Compliance:
Safety frameworks constrain formulation chemistry, handling protocols, and cross-border product registration timelines.
- OSHA:Workplace nitroglycerin vapor exposure limits constrain formulation potency and handling labor productivity across US surface operations, forcing reformulation investments for compliance.
- EPA:Air quality standards govern emission profiles from blasting operations and manufacturing facilities, affecting plant siting and abatement equipment requirements.
- NFPA:Fire code classifications for storage, transport, and handling create facility design constraints that differentiate distributor infrastructure investments.
- Local Regulations:China's SAMR enforces GB standards on manufacturing licensing and transport classification, while Australia's Dangerous Goods codes impose dual-certification timelines extending commercialization cycles.
OSHA and EPA dominate compliance expenditure in North America, though Local Regulations command attention in fastest-growing Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia consumes dynamite through mechanized underground headings where drill-and-blast automation dominates, while South African operations retain cartridge-loading traditions in labor-intensive reef extraction. This consumption-mix differential fragments supplier strategies across hard-rock mining corridors.
Australia
Western Australia's Pilbara iron ore belt and Kalgoorlie gold camps drive packaged emulsion demand through integrated blasting service contracts. The country's Dangerous Goods codes impose dual-certification timelines with China's GB standards, extending product registration cycles. Perth-based procurement offices for Rio Tinto and BHP specify fragmentation guarantees rather than explosive tonnage, transferring rock-breakage risk to contractor crews.
China
Shanxi and Sichuan provinces consolidate industrial explosive manufacturing under SAMR's tightening GB 28263-2012 licensing audits and real-time production monitoring mandates. The country's dual carbon goals pressure energy-intensive nitroglycerin synthesis operations, raising facility upgrade capital requirements. Domestic producers spread compliance costs across volume by absorbing smaller licensed operations, while foreign suppliers face extended certification timelines for imported formulations.
South Africa
Platinum and gold extraction corridors in the Bushveld Complex and Witwatersrand Basin sustain mechanized blasting intensity, driving cartridge consumption per meter of advance. The country's national explosives regulator enforces strict transport classification and storage protocols for nitroglycerin-sensitized products. Johannesburg-centered blasting contractors face talent scarcity in electronic detonator timing expertise as aging practitioners concentrate specialized knowledge.
United States
Surface copper and coal operations in Arizona and Wyoming absorb bulk emulsion deliveries, compressing dynamite's addressable tonnage in tier-one deposits. OSHA workplace nitroglycerin vapor exposure limits constrain formulation potency and handling labor productivity, forcing reformulation investments. EPA air quality standards govern emission profiles from manufacturing facilities, affecting plant siting decisions in the Mountain West.
Indonesia
Sulawesi and Halmahera nickel laterite mining concessions represent greenfield sites without legacy explosive infrastructure, open to emulsion-delivery system partnerships. The country's national mining ministry coordinates with industrial explosive licensing authorities on import permit classifications for bulk systems. Makassar and Bitung serve as logistics hubs for contract blasting services deploying Chinese and Australian equipment packages.
Dynamite Market Vendor Landscape
Capability concentration sits with integrated blasting service providers who control drill rig fleets and post-blast analytics; scale advantage sits with ammonium nitrate supply chain controllers who anchor feedstock pricing. The market structures around three tiers: vertically integrated multinationals, regional specialists with localized manufacturing partnerships, and national champions serving protected domestic markets. Competitive moves center on integrated service contract capture and regulatory certification infrastructure buildout.
Among Australia-based integrated service providers, Orica Limited exemplifies the capability-concentrated archetype through its fragmentation-guarantee contracting model. Dyno Nobel occupies a position representing supply-chain-scale advantage with North American ammonium nitrate infrastructure. Solar Industries India Ltd anchors the regional specialist tier through African copperbelt manufacturing partnerships. These three patterns illustrate how competitive positioning fragments across service integration, feedstock control, and geographic specialization vectors.
| Leading Market Players |
|---|
| ENAEX S.A. |
| AECI Limited |
| Orica Limited |
| Solar Industries India Ltd |
| Sasol Limited |
| Dyno Nobel |
| Austin Powder Company |
| TITANOBEL |
| MAXAM Corp |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Chinese ammonium nitrate synthesis facilities is driving feedstock pricing volatility that reshapes both supplier contract postures and buyer procurement calendars across the explosives value chain.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between tier-one miners and integrated blasting service providers, with spot purchasing confined to project-based quarrying operations. Price differentiation rests on emulsion formulation grade and GB standard certification tier, with water-resistant variants commanding premiums in wet-bench applications. Cost compression in standard-grade cartridges is intensifying because fertilizer-to-explosive feedstock competition concentrates ammonium nitrate pricing power with integrated chemical producers. Construction demolition buyers exhibit highest price sensitivity due to irregular project cycles, while mechanized underground operators prioritize fragmentation consistency over unit cost.
Supply Chain Analysis
Extended payment terms from Indonesian nickel laterite operators are forcing supply-chain finance facilities upon distributors serving greenfield Sulawesi and Halmahera concessions. Manufacturing concentration centers on China, Australia, and South Africa for packaged emulsion production, with nitroglycerin sensitization chemistry drawing from specialized Shanxi and Sichuan facilities. Feedstock supply hinges on ammonium nitrate, carbonaceous fuels, and stabilizing gel matrices sourced through fertilizer industry channels. Single-source vulnerability runs through Chinese SAMR-licensed production nodes subject to dual carbon goal pressures. Distribution runs through Makassar and Bitung logistics hubs for Indonesian contracts, Perth for Pilbara operations, and Johannesburg for Bushveld Complex corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the displacement of pyrotechnic fuse caps by electronic detonation systems, creating specialist niches for programmable timing technology and blast analytics platforms.
For Market Incumbents: Harden regulatory certification infrastructure against China's tightening GB 28263-2012 licensing audits and Australia's Dangerous Goods dual-certification timelines. Deepen backward integration into ammonium nitrate supply channels to defend margin position against feedstock pricing volatility from fertilizer industry competition. Prioritize captive production of water-resistant emulsion formulations to capture premium pools in wet underground headings. For New Entrants and Emerging Players: Establish a beachhead in Indonesian nickel laterite greenfield sites lacking legacy cartridge infrastructure, where emulsion-delivery system partnerships face minimal incumbent entrenchment. Target quarrying operations near Australian and Indian urban construction zones exhibiting fastest structural growth in aggregate demand. Lead with drone-enabled blast monitoring and outcome-based fragmentation optimization contracts to differentiate from product-only suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Chinese manufacturing compliance upgrades under SAMR real-time production monitoring mandates. Long-term viability over the next decade favors vertically integrated service providers controlling drill rig fleets and post-blast analytics platforms over pure-play product manufacturers. Watch electronic detonator replacement rates in Canada's Sudbury Basin and Sweden's Kiruna district as inflection indicators for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Certification Investment | SAMR licensing barriers consolidate market share for compliant domestic producers in Shanxi and Sichuan provinces. |
| Emulsion-Delivery System Partnership | Greenfield Indonesian nickel laterite concessions lack legacy infrastructure, opening contract capture opportunities. |
| Electronic Detonator Platform Deployment | Programmable timing systems virtualize inventory management and collapse SKU complexity for distributors. |
| Integrated Blasting Service Contract | Fragmentation guarantees transfer rock-breakage risk from Rio Tinto and Anglo American to contractor crews. |
| Drone-Enabled Blast Monitoring | Convergence of detonation velocity sensors with unmanned aerial platforms enables outcome-based optimization. |
Methodological Framework
A standing panel of blasting services procurement managers, plant engineers at ammonium nitrate facilities, SAMR licensing auditors, and underground mine operations directors provided ongoing calibration across the study period. Primary interviews with electronic detonator timing specialists and quarrying contractors combined with secondary validation through customs and trade data, SEC filings from integrated chemical producers, and SAMR regulatory disclosure databases. Bottom-up volume modeling across formulation chemistry tiers triangulated against top-down value estimates from contract value disclosures.
Scenario-bracketing around ammonium nitrate feedstock pricing volatility and GB standard compliance timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, physical form state, end-use application intensity, and regional regulatory cluster. CAGRs derived from mechanized blasting intensity trajectories in South African platinum corridors and drill-and-blast automation adoption rates in Australian Western Australia belt operations. Industry-specific forecast inputs incorporated electronic detonator replacement velocities and urban aggregate demand proximity indices.
Sensitivities concentrate around Chinese dual carbon goal implementation pace, Indonesian nickel laterite concession award timelines, and South African blast engineering talent scarcity progression. Forecasts reflect documented assumptions regarding feedstock competition dynamics and regulatory audit stringency. Macroeconomic commodity price deviation, unanticipated SAMR licensing suspension events, or breakthrough bulk emulsion pumping technology would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market