
 Taurine Market | 2026-2036
Taurine Market Size, Share, and Industry Trends Forecast 2026-2036
Taurine Market Analysis
Functional beverage formulations is expanding as the fastest-rising demand channel for taurine, displacing conventional pharmaceutical offtake. Qianjiang Yongan Pharmaceutical anchors China's fermentation capacity and supplies bulk powder to global formulators. Ajinomoto differentiates through synthetic production expertise and Japanese quality certifications. Kyowa Hakko Bio dominates pharmaceutical-grade supply chains with cGMP-compliant manufacturing.
Taurine, or 2-aminoethanesulfonic acid, is a sulfur-containing amino acid synthesized naturally in the body or produced industrially via ethylene oxide-ammonia chemistry or microbial fermentation; it functions primarily as an osmoregulator, bile acid conjugant, and cellular antioxidant across mammalian physiology. The powder segment leads volume shipments due to cost-efficient bulk handling in industrial formulation, while liquid taurine concentrates capture premium positioning in ready-to-drink energy products. Nutritional supplements and animal feed applications together occupy the largest share of margin pools, with pharmaceutical-grade specifications commanding the highest unit economics.
FDA food additive regulations and EFSA novel food assessments govern taurine inclusion levels in consumer products across the United States and Europe, directly constraining formulation ceilings and label claims. China's NMPA and SAMR enforce GB standards on amino acid purity and production facility licensing, shaping export eligibility for domestic manufacturers. Stakeholders must monitor evolving pharmacovigilance requirements for high-dose taurine and fermentation sustainability disclosures as procurement criteria tighten.
Market Dynamics
Fermentation-based manufacturing is displacing synthetic chemistry as the dominant production pathway, with China's NMPA purity mandates accelerating this capital-intensive transition across Asian supply bases.
Growth Catalysts
- ESG-driven feedstock sourcing:Fermentation processes utilizing renewable carbohydrate feedstocks attract sustainability-linked procurement contracts from European beverage formulators.
- Sports nutrition category expansion:Pre-workout and hydration product launches by functional drink brands create sustained bulk powder demand exceeding pharmaceutical offtake volumes.
- China's NMPA pharmaceutical-grade alignment:Stricter GB standards on amino acid additives force domestic capacity upgrades that simultaneously unlock premium export certifications.
Market Restraints
- Ethylene oxide feedstock volatility:Synthetic taurine producers face margin compression from petrochemical input cost swings and energy price spikes.
- Single-region supply concentration:Hubei province fermentation clusters account for disproportionate global output, creating geopolitical and logistics risk exposure.
- EFSA novel food assessment timelines:Extended safety evaluation periods for new taurine delivery formats delay European market entry by 18-36 months.
Strategic Opportunities
- Cell-culture media applications:Biopharmaceutical-grade taurine demand for cultivated meat and precision fermentation inputs remains underdeveloped relative to nutritional uses.
- Indian FSSAI regulatory harmonization:Pending alignment with CODEX standards would reduce import barriers for pharmaceutical-grade specifications.
- Direct-to-brand e-procurement platforms:Bulk ingredient marketplaces disintermediate traditional distributor networks for mid-size functional beverage startups.
Industry Challenges
- cGMP certification backlog:Fermentation facility audits face examiner shortages, delaying pharmaceutical-grade qualification timelines.
- Cross-contamination protocols:Multi-product amino acid plants require segregated production lines that strain capital deployment efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taurine Market |
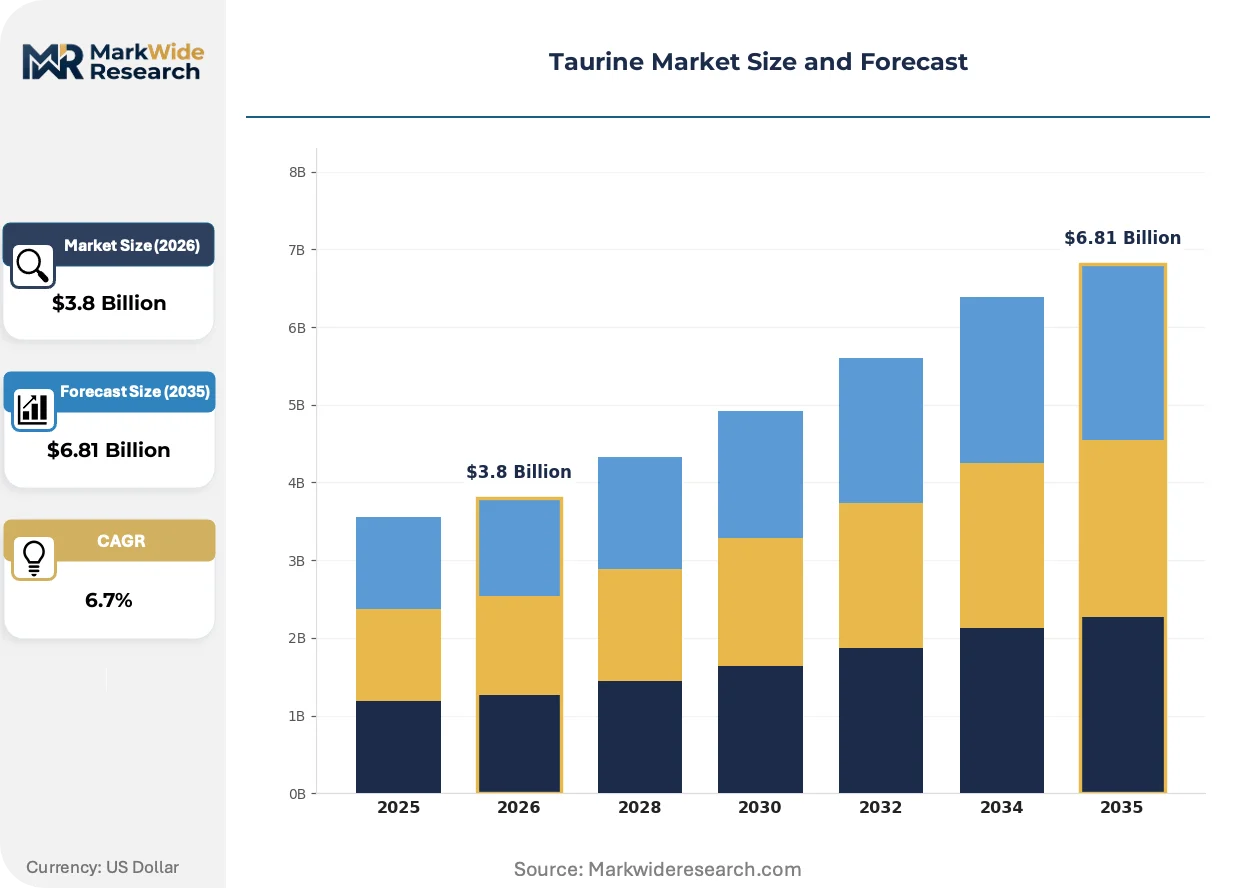
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Softgel Application: Nutritional Supplements, Animal Feed, Food & Beverages, Pharmaceuticals End User: Healthcare Providers, Fitness Enthusiasts, Manufacturers, Retailers Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Qianjiang Yongan Pharmaceutical, Ajinomoto, Kyowa Hakko Bio, Merck KGaA, Taisho Pharmaceutical Holdings, The Honjo Chemical Corporation, AlzChem Group AG, Mitsui Chemicals, Jiangsu Yuanyang Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taurine Market Emerging Trajectories
Continuous fermentation systems and single-use bioreactor technologies are compressing batch cycle times while regulatory data transparency requirements reshape competitive disclosure practices across supply chains.
Continuous fermentation technology is consolidating manufacturing economics for high-volume taurine output. The approach eliminates downtime between batches and reduces labor intensity. Sports nutrition contract manufacturers in China are adopting these systems fastest, compressing unit costs for powder-grade material and squeezing synthetic chemistry competitors on price.
EFSA's updated novel food guidance on sulfur-containing amino acids is tightening toxicological data requirements for new delivery formats. The regulation demands extended sub-chronic studies that extend development timelines. Functional beverage brands targeting European markets are reformulating around existing approved specifications rather than pursuing innovative encapsulation technologies.
Brand-direct bulk purchasing is fragmenting traditional distributor relationships in North American and European supply chains. Mid-size functional drink startups now source fermentation-grade powder through B2B platforms, bypassing regional chemical distributors. This pattern concentrates procurement leverage with large-volume buyers while compressing margins for intermediaries.
Taurine Market Segmentation
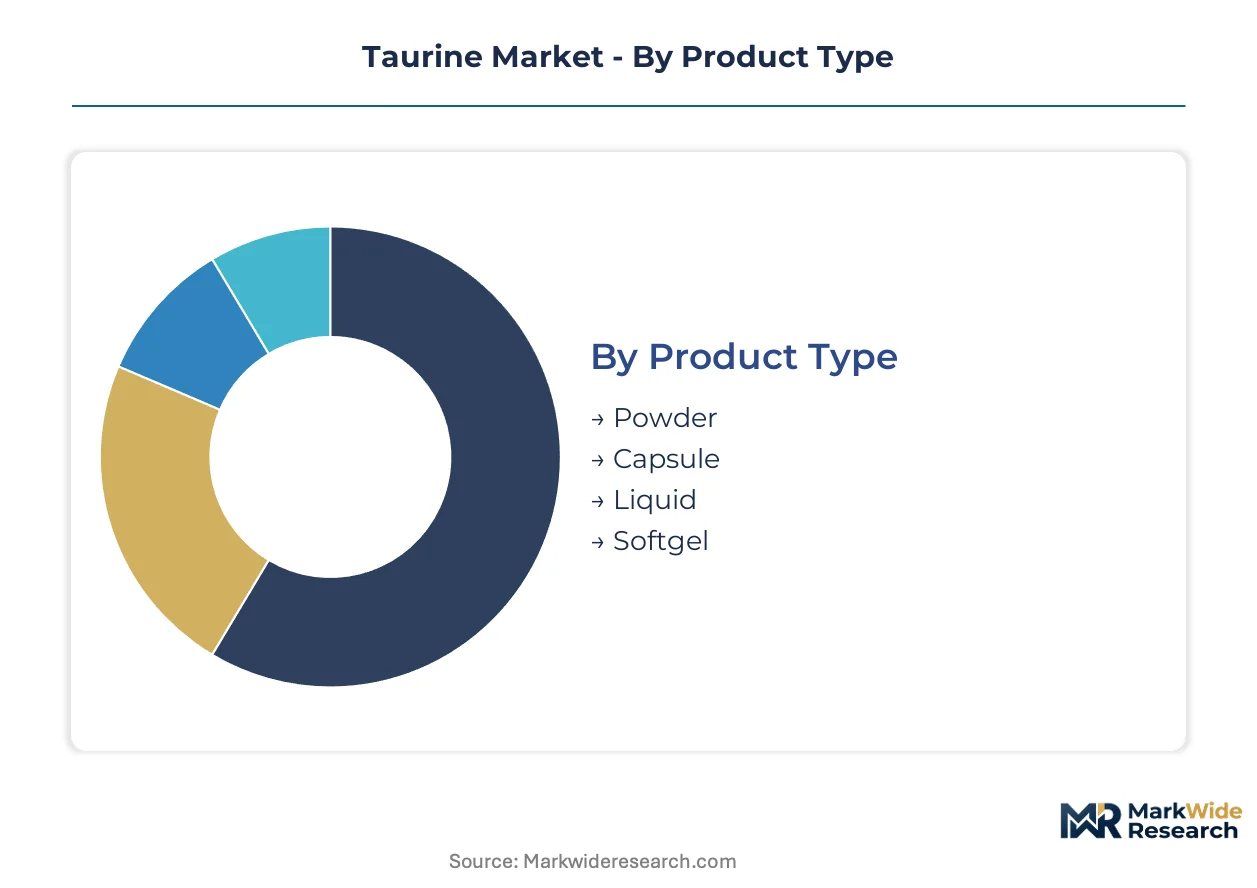
Taurine procurement patterns diverge sharply across physical formats and customer workflows, with fermentation-scale economies favoring bulk powder while finished brands chase differentiated delivery systems. Each segment tier carries distinct certification burdens and margin structures that reshape supplier priorities.
Product Type:
Supply concentration in Hubei province fermentation clusters tilts manufacturing economics toward powder-grade output, yet brand differentiation drives investment into alternative formats.
- Powder:Crystalline bulk material dominates industrial formulation for energy drinks and pre-workout blends due to cost-efficient handling and scalable blending operations. Sports nutrition contract manufacturers in China absorb the majority of global powder shipments as functional beverage launches accelerate.
- Liquid:Ready-to-drink concentrates command premium positioning in convenience-oriented energy products, with European beverage formulators specifying pharmaceutical-grade solubility standards for direct incorporation. EFSA novel food timelines constrain European launch velocity for innovative liquid formats.
- Capsule:Encapsulated taurine serves precision-dosing supplement regimens, particularly in North American direct-to-consumer wellness brands.
- Softgel:Lipid-suspended delivery targets fat-soluble co-formulation with vitamins and omega compounds in premium supplement lines.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Cost tier stratification separates commodity feed-grade material from pharmaceutical-certified supply, with margin pools concentrating in human nutrition applications.
- Nutritional Supplements:Dietary capsules, tablets, and functional powders constitute the highest-margin application tier, with cGMP certification requirements filtering supplier eligibility. North American and European brands drive specification escalation toward fermentation-derived, allergen-free material.
- Food & Beverages:Energy drink formulations represent the volume anchor for bulk taurine procurement, with Red Bull and Monster-scale buyers commanding preferential supply terms. China's SAMR enforces GB standard purity floors that reshape export eligibility for domestic fermentation plants.
- Pharmaceuticals:Prescription-grade taurine for cardiovascular and metabolic indications requires PMDA, FDA, or EMA-registered manufacturing sites with validated impurity profiles.
- Animal Feed:Livestock and aquaculture nutrition utilizes technical-grade material with relaxed specification tolerances and compressed pricing.
Nutritional supplements capture the steepest margin expansion; food and beverages command the largest absolute volume.
End User:
Customer type fragmentation splits procurement between institutional specification-setters and brand-driven volume buyers with divergent technical requirements.
- Manufacturers:Contract formulators and beverage co-packers constitute the primary demand channel, translating bulk powder into finished goods for brand owners. These intermediaries concentrate purchasing leverage and drive fermentation-grade volume commitments.
- Fitness Enthusiasts:Direct consumption of pre-workout and hydration products creates pull-through demand that shapes brand formulation decisions, particularly in subscription-model supplement commerce.
- Healthcare Providers:Clinical settings utilize pharmaceutical-grade taurine for parenteral nutrition and metabolic disorder management under prescription protocols.
- Retailers:Private-label development by pharmacy and grocery chains generates specification demand for semi-finished bulk material with packaging flexibility.
Manufacturers absorb the bulk of installed capacity; fitness enthusiasts are expanding most quickly.
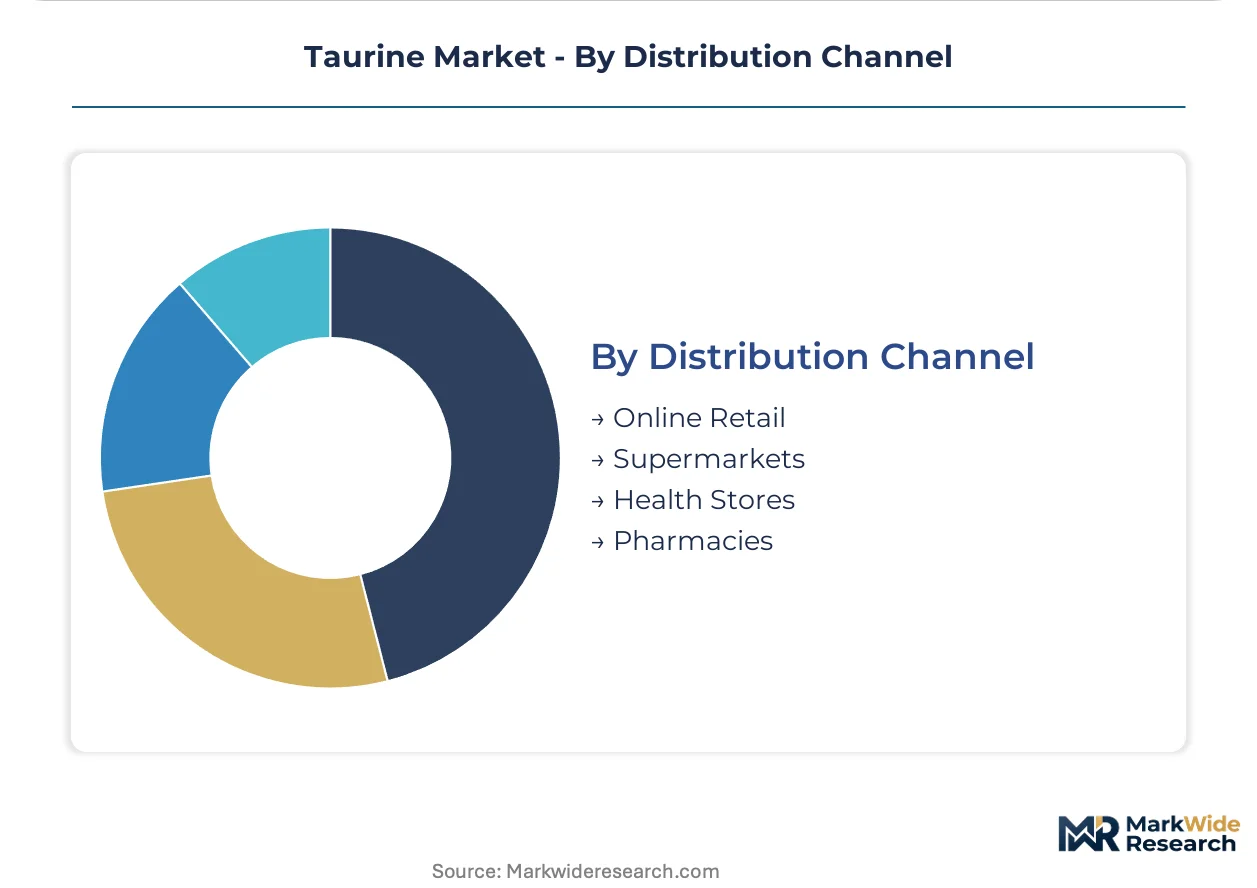
Distribution Channel:
Channel maturity varies across geography, with digital procurement disrupting traditional chemical distributor networks in developed markets.
- Online Retail:B2B platforms and brand-direct marketplaces fragment conventional distributor relationships, enabling mid-size functional beverage startups to source fermentation-grade powder without regional intermediary markup. Amazon Business and Alibaba.com concentrate transaction liquidity.
- Supermarkets:Mass-market retail placement for finished energy drinks and supplements drives indirect taurine demand through brand procurement offices rather than direct ingredient purchasing.
- Health Stores:Specialty supplement retailers curate premium-positioned taurine SKUs with third-party certification claims targeting discerning wellness consumers.
- Pharmacies:Regulated retail channels for pharmaceutical-grade taurine require documentation trails that favor established supplier relationships over platform-based sourcing.
Online retail is gaining share fastest; supermarkets anchor the largest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global taurine supply through Hubei province fermentation clusters, while the United States, Germany, and Japan absorb disproportionate shares of pharmaceutical-grade and functional beverage offtake. This production-consumption divide shapes trade flows, regulatory arbitrage, and certification requirements across major markets.
United States
Energy drink brands and sports nutrition formulators drive sustained bulk powder demand, with contract manufacturers in the Southeast and California absorbing significant import volumes. FDA food additive regulations govern taurine inclusion levels in dietary supplements and beverages, constraining label claims and formulation ceilings. Texas and New Jersey host major beverage co-packing facilities that translate imported fermentation-grade material into finished goods.
China
Domestic fermentation capacity in Hubei province supplies global formulators, with Qianjiang Yongan Pharmaceutical anchoring industrial-scale output. NMPA tightened GB standards on amino acid purity, forcing facility upgrades that simultaneously unlock pharmaceutical-grade export certifications. The Yangtze River Delta concentrates downstream blending operations for both domestic consumption and re-export to Southeast Asian markets.
Germany
EFSA novel food assessments govern taurine delivery format approvals, with extended toxicological timelines delaying innovative encapsulation launches. The country's central position in European beverage distribution channels concentrates procurement offices for pan-EU functional drink brands. Bavaria and North Rhine-Westphalia house major flavor houses and contract manufacturers that specify fermentation-derived, allergen-free material.
Japan
PMDA-registered manufacturing requirements filter supplier eligibility for pharmaceutical-grade taurine used in cardiovascular and metabolic indications. Domestic synthetic production expertise, exemplified by Ajinomoto and Kyowa Hakko Bio, maintains premium positioning through Japanese quality certifications. The Kansai region retains concentrated amino acid manufacturing infrastructure serving both domestic and export pharmaceutical markets.
India
Nutritional supplement brands and generic pharmaceutical formulators generate growing bulk import demand as domestic fermentation capacity remains underdeveloped. FSSAI regulatory harmonization with CODEX standards remains pending, creating import friction for pharmaceutical-grade specifications. Maharashtra and Gujarat host the majority of contract manufacturing organizations that blend imported taurine into finished dosage forms.
Taurine Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade supply chains with cGMP certifications, while mid-tier fermentation specialists compete on volume and cost efficiency for beverage-grade material. The vendor base stratifies across three archetypes: synthetic chemistry incumbents with petrochemical integration, microbial fermentation scale players with carbohydrate feedstock flexibility, and pharmaceutical-grade specialists with regulatory dossier depth. Dominant competitive moves include fermentation capacity expansion in China and strategic partnerships between ingredient suppliers and functional beverage brands.
Within the fermentation-scale tier, Qianjiang Yongan Pharmaceutical and Jiangsu Yuanyang Chemical represent Chinese capacity leadership, while Ajinomoto and Kyowa Hakko Bio occupy positions defined by synthetic and pharmaceutical-grade expertise respectively. Merck KGaA and Taisho Pharmaceutical Holdings exemplify diversified chemical and pharmaceutical conglomerates with amino acid portfolio breadth. AlzChem Group AG anchors European synthetic production capabilities. These named entities illustrate archetype positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Qianjiang Yongan Pharmaceutical |
| Ajinomoto |
| Kyowa Hakko Bio |
| Merck KGaA |
| Taisho Pharmaceutical Holdings |
| The Honjo Chemical Corporation |
| AlzChem Group AG |
| Mitsui Chemicals |
| Jiangsu Yuanyang Chemical |
| Others |
Supply Flow & Price Mechanics
Fermentation technician concentrations in Hubei province compress labor-cost differentials between pharmaceutical-grade and beverage-grade taurine, widening pricing-tier spreads as certification overhead accumulates faster than wage premiums.
Pricing Analysis
Margin tightening in beverage-grade powder reflects continuous fermentation scale economies achieved by Chinese contract manufacturers. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade specifications separates buyers by impurity tolerance and documentation burden. Pricing pressure intensifies in synthetic chemistry-derived material as ethylene oxide feedstock volatility erodes cost competitiveness. Sports nutrition formulators exhibit highest price sensitivity, while cardiovascular pharmaceutical developers absorb premium positioning without volume elasticity.
Supply Chain Analysis
Dual-sourcing mandates from European beverage formulators require simultaneous qualification of Hubei fermentation clusters and Japanese synthetic producers, extending vendor onboarding timelines. Supply concentrates in China, Japan, and Germany, with Hubei province anchoring fermentation output and Ajinomoto maintaining synthetic expertise. Raw material flows draw from corn-derived carbohydrate feedstocks, petrochemical ethylene oxide, and sulfur reagents. Single-region concentration in Hubei creates geopolitical risk exposure. Distribution runs through B2B procurement platforms and traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The taurine market functions as a vertical-integration race where backward control over fermentation carbohydrate feedstocks determines margin capture against synthetic chemistry competitors.
For Market Incumbents: Deepen cGMP certification depth at Hubei facilities to defend pharmaceutical-grade positioning against Kyowa Hakko Bio's regulatory dossier advantages. Expand captive corn-processing capacity to offset carbohydrate feedstock price volatility squeezing fermentation economics. For New Entrants and Emerging Players: Begin with cell-culture media specifications for cultivated meat applications, the most penetrable tier given underdeveloped supplier coverage relative to nutritional uses. Pursue direct-to-brand e-procurement platform relationships with mid-size functional beverage startups bypassing established distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade fermentation specialists given NMPA purity mandate enforcement accelerating export certification unlocks. Long-term viability favors assets with dual food-pharma qualification rather than single-tier positioning. Watch for FSSAI-CODEX harmonization completion as India import barrier inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Capacity Expansion | Compresses unit costs for powder-grade material below synthetic chemistry breakeven thresholds. |
| Pharmaceutical-Grade cGMP Certification Investment | Unlocks cardiovascular and metabolic indication supply contracts requiring PMDA or FDA registration. |
| Carbohydrate Feedstock Backward Integration | Captures margin from corn-derived renewable inputs attracting ESG-linked procurement contracts. |
| Direct-to-Brand E-Procurement Platform Partnership | Disintermediates regional chemical distributors serving mid-size functional beverage formulators. |
| Cell-Culture Media Application Development | Addresses cultivated meat and precision fermentation input demand currently underdeveloped relative to nutrition. |
Methodological Framework
Multi-period observation of fermentation capacity utilization, NMPA facility licensing timelines, and EFSA novel food assessment queues anchored the trend analysis, supplemented by interviews with amino acid plant managers, sports nutrition procurement leads, pharmaceutical regulatory affairs directors, and beverage co-packing operators. Secondary validation drew from NMPA GB standard filings, EFSA scientific opinions, customs trade data, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down category spending estimates.
Input-output matrices mapped fermentation yield rates, carbohydrate feedstock conversion efficiencies, and certification cost burdens across pharmaceutical-grade, food-grade, and feed-grade tiers over the projection horizon. Segmentation dimensions included physical format, application end-use, customer type, and regional regulatory cluster. CAGRs emerged from slope analysis of segment-level trajectory convergence. Industry-specific forecast inputs incorporated NMPA enforcement intensity scenarios and sports nutrition category launch pipelines.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications carry tighter precision than feed-grade commodity flows due to documented certification audit trails. Forecasts reflect assumptions on regulatory harmonization timelines and fermentation technology diffusion rates. Deviation in China's NMPA enforcement intensity or ethylene oxide feedstock availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Perms and Relaxants Market