
 Specialty Biocides Market | 2026-2036
Specialty Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Biocides Market Outlook
Peracetic acid formulations are displacing traditional chlorine-based chemistries in cold-temperature sanitization, which is recalibrating cost structures across food processing and healthcare end uses. Lonza Group Ltd. leverages its integrated active-ingredient manufacturing to sustain price competitiveness in quaternary ammonium compounds. DuPont de Nemours Inc. anchors its position through differentiated polymer-stabilized biocide delivery systems that extend performance duration in recirculating cooling towers.
Specialty biocides are antimicrobial agents engineered with defined active concentrations, typically ranging from 0.1 ppm to 500 ppm depending on target organism and application matrix, designed to inhibit microbial proliferation in industrial and consumer systems. Their primary commercial purpose centers on preserving material integrity, ensuring process hygiene, and meeting operational safety thresholds in water-intensive industries. Bactericides command the largest share of product-type revenue owing to their ubiquity in cooling water and oilfield applications, while algaecides represent the fastest-expanding category as photovoltaic panel cleaning protocols proliferate. Within application segments, water treatment generates the deepest margin pools due to long-term service contracts and technical support bundling, whereas coatings applications remain more fragmented with shorter replacement cycles.
The EPA Office of Pesticide Programs and the EU Biocidal Products Regulation jointly determine market access through dual-track registration requirements that prolong commercialization timelines but elevate barriers to commoditized supply. China's Ministry of Ecology and Environment enforces discharge standard GB 31570-2015, which limits residual biocide concentrations in industrial effluent and redirects formulation choices toward biodegradable actives. ISO 9001 quality management and OECD test guideline compliance have become baseline qualifiers for supplier qualification in multinational procurement frameworks. Stakeholders must monitor the trajectory of green chemistry certification programs and their incorporation into public-sector tender specifications to anticipate premium positioning opportunities.
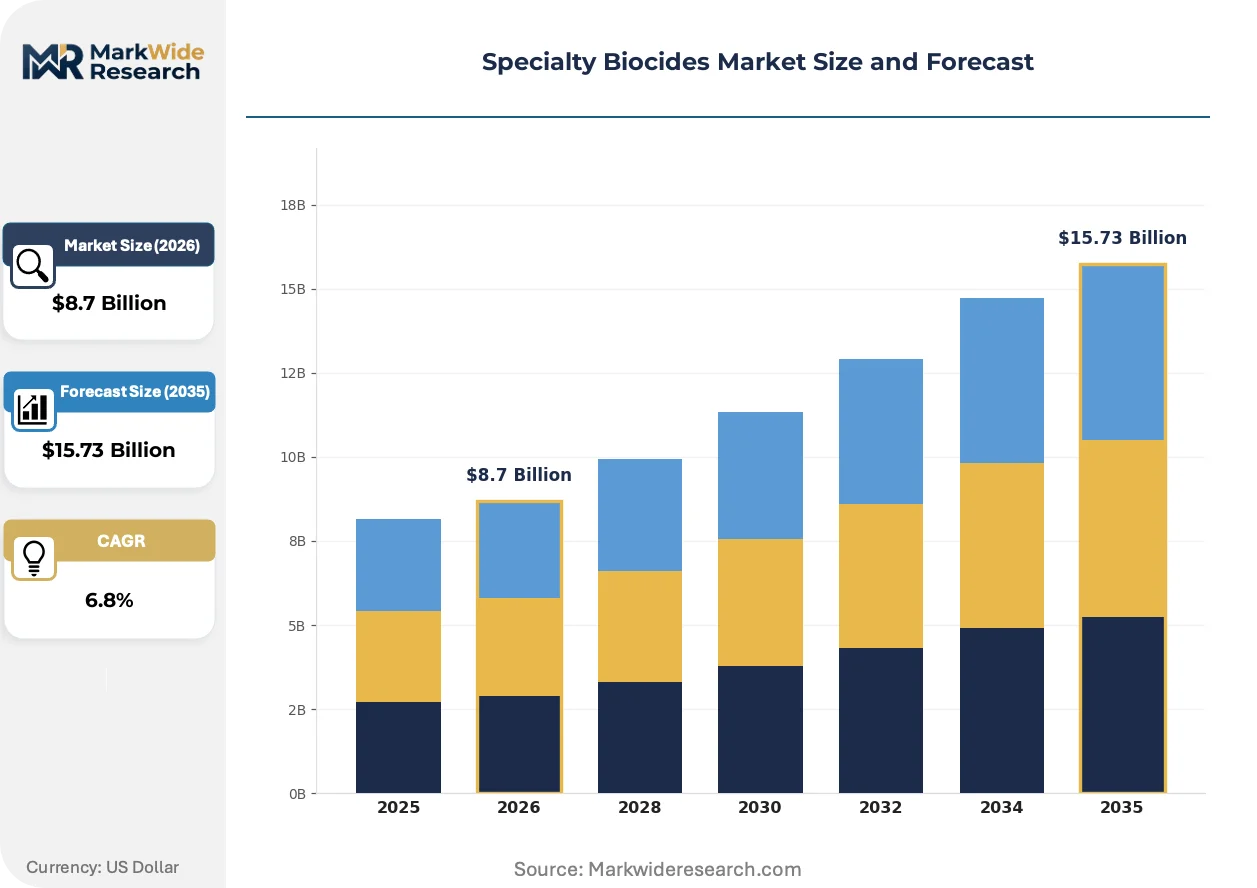
Market Dynamics
Halogen-free biocidal systems are recalibrating procurement criteria across water treatment utilities, compressing demand for legacy chlorine chemistries while elevating peracetic acid and quaternary ammonium compound specifications in contract tenders.
Growth Catalysts
- EU BPR efficacy mandates:Tighter documentation requirements for active substance suppliers are filtering out commoditized producers and concentrating procurement among technically qualified formulators.
- Industrial water reuse protocols:Stringent discharge limits in Germany, China, and the United States are mandating biocide residuals below detectable thresholds, accelerating biodegradable active adoption.
- Photovoltaic panel cleaning expansion:Solar farm operators in arid climates are specifying algaecide chemistries for module maintenance, creating a new demand vector outside traditional cooling water applications.
Market Restraints
- EPA registration timelines:Dual-track approval requirements with EU BPR extend commercialization cycles to 36-48 months, elevating working capital burdens for active ingredient developers.
- Acetic acid feedstock volatility:Peracetic acid manufacturers face margin compression from petrochemical derivative price swings, complicating long-term contract pricing.
- Halogenated legacy infrastructure:Existing dosing equipment in municipal water systems creates technical lock-in that slows conversion to non-chlorine chemistries despite regulatory pressure.
Strategic Opportunities
- Polymer-stabilized delivery systems:Encapsulation technologies that extend biocide release in recirculating cooling towers command 15-20% price premiums over conventional formulations.
- India industrial effluent enforcement:State Pollution Control Boards are tightening COD and microbial discharge limits, redirecting textile and pharmaceutical processors toward certified biodegradable actives.
- ISO 9001 bundling with technical service:Multinational procurement frameworks increasingly require quality certification plus on-site application support, favoring integrated suppliers over commodity traders.
Industry Challenges
- Microbiological assay standardization:Variability in OECD test guideline interpretation across notified bodies creates registration submission rejections and timeline extensions.
- Cross-contamination protocols in multi-use facilities:Food processing plants running both organic and conventional lines require segregated biocide inventories, complicating supply chain logistics and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Biocides Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algaecides, Fungicides, Bactericides, Insecticides Application: Agriculture, Water Treatment, Wood Preservation, Coatings End User: Food Processing, Healthcare, Household, Industrial Form: Liquid, Powder, Granular, Emulsifiable |
| Companies Covered | Buckman Laboratories International Inc., DuPont de Nemours Inc., Albemarle Corp., Lonza Group Ltd., Lanxess AG, Baker Hughes Co., Clariant International Ltd., Nouryon, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Biocides Market Strategic Shifts
Formulation chemistry and delivery mechanisms are undergoing rapid recalibration as end-users prioritize performance duration, temperature stability, and regulatory pre-certification in procurement specifications.
Electrochemical peracetic acid generation is electrifying on-site production economics for cold-chain sanitization. Meat processing facilities and hospital sterilization departments are adopting skid-mounted generators to eliminate bulk chemical transport and storage liabilities. This distributed manufacturing model is compressing traditional chemical distributor margins while capturing 30-40% operating cost reductions for high-volume users.
REACH authorization requirements for certain isothiazolinone actives are forcing reformulation investments across coatings and adhesives segments. ECHA's sunset date enforcement is eliminating legacy preservative options from EU supply chains, redirecting R&D expenditure toward MIT-CMIT alternatives and formaldehyde-releaser replacements. Decorative paint manufacturers in Italy and Spain are accelerating validation of phenoxyethanol-boosted systems to maintain shelf-life claims.
Technical service unbundling is fragmenting traditional supplier-customer relationships in water treatment. Facility operators are separating chemical procurement from application monitoring, awarding dosing system contracts to automation specialists while sourcing actives through tender-based spot purchasing. This bifurcation is most advanced in Texas and Alberta oilfield operations, where produced water handling complexity favors specialized service providers over integrated chemical houses.
Specialty Biocides Market Segmentation
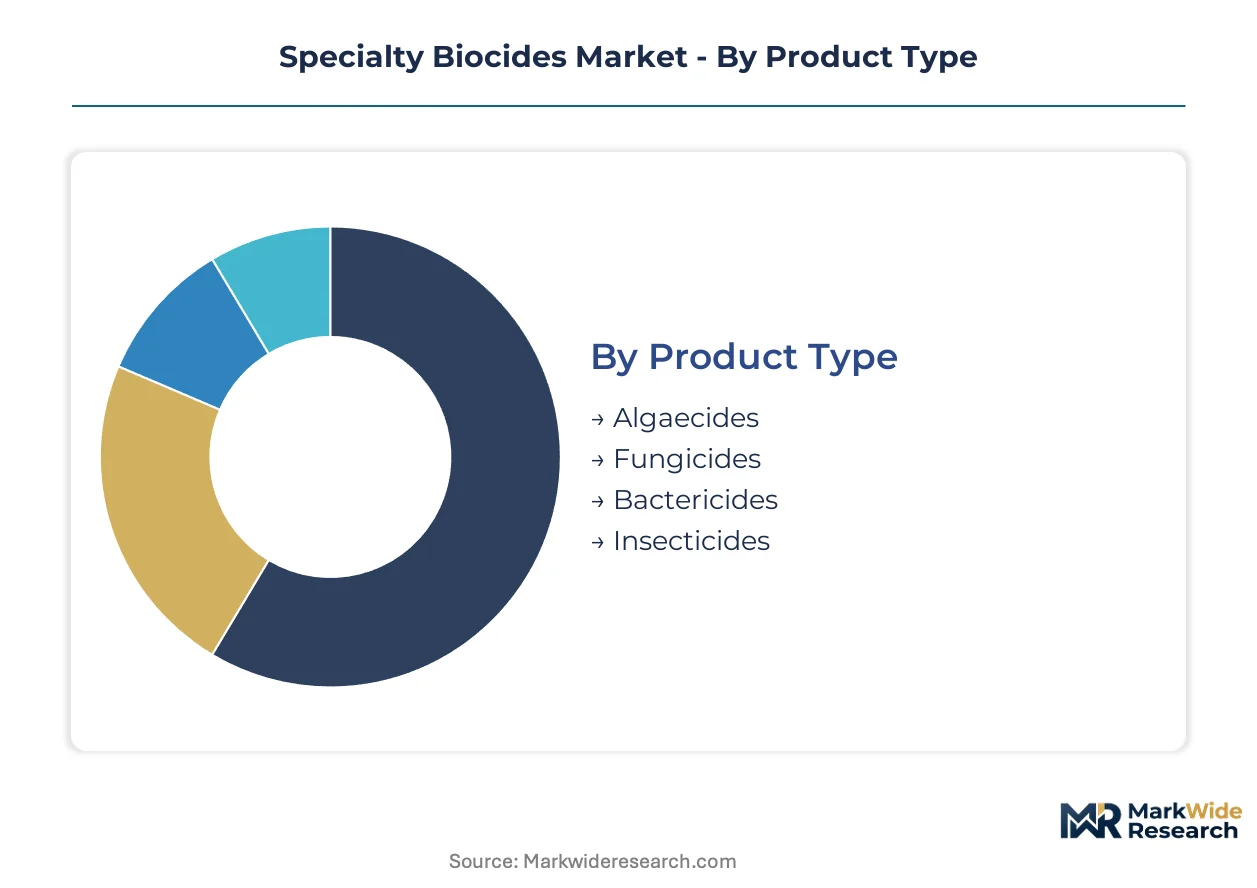
Segmentation in specialty biocides determines capital allocation priorities, as formulation complexity and registration burdens vary sharply across active chemistries and delivery formats. Procurement specifications increasingly bundle technical service requirements with product certification, reshaping competitive positioning by segment.
Product Type:
Capital intensity concentrates in bactericide manufacturing, where integrated active-ingredient production requires substantial fixed-asset investment to achieve cost competitiveness.
- Bactericides:These antimicrobial formulations target bacterial proliferation in aqueous systems, typically employing quaternary ammonium compounds or isothiazolinone actives. Demand concentrates in cooling water applications across Germany, China, and the United States, where industrial water reuse mandates drive specification of biodegradable actives over legacy halogenated chemistries.
- Algaecides:Formulations engineered to inhibit photosynthetic microbial growth on surfaces, with copper-based and quaternary ammonium systems dominating commercial supply. Photovoltaic panel cleaning protocols in arid climates are creating new demand vectors outside traditional cooling water applications, expanding the addressable market for module maintenance specifications.
- Fungicides:Active systems targeting mold and yeast contamination in coatings and wood preservation matrices.
- Insecticides:Niche biocidal applications in agricultural and household pest control segments.
Bactericides absorb the bulk of installed capacity; algaecides are expanding most quickly.
Application:
Margin profiles diverge sharply across applications, with long-term service contracts in water treatment generating substantially deeper margin pools than fragmented coatings procurement.
- Water Treatment:Industrial and municipal systems requiring continuous microbial control in recirculating loops and discharge streams. EPA and EU BPR registration pathways elevate barriers to entry, concentrating procurement among technically qualified formulators capable of efficacy documentation and on-site application support.
- Coatings:Preservative applications in decorative and industrial paints, adhesives, and sealants. REACH authorization timelines for isothiazolinone actives are forcing reformulation investments across Italian and Spanish decorative paint manufacturers, redirecting R&D expenditure toward MIT-CMIT alternatives.
- Agriculture:Crop protection and post-harvest preservation applications with distinct seasonal demand patterns.
- Wood Preservation:Pressure-treatment and surface applications protecting lumber and engineered wood products.
Water treatment commands the deepest margin pools; coatings applications are gaining share fastest as regulatory reformulation cycles accelerate.
End User:
Customer sophistication determines technical service bundling requirements, with food processing and healthcare operators imposing the most stringent segregated inventory protocols.
- Industrial:Oilfield operations, pulp and paper mills, and manufacturing facilities with complex water handling requirements. Texas and Alberta produced water operations are advancing technical service unbundling, separating chemical procurement from dosing system contracts.
- Food Processing:Meat, dairy, and beverage facilities requiring cold-temperature sanitization compliance. Electrochemical peracetic acid generation is electrifying on-site production economics, with skid-mounted generators eliminating bulk chemical transport liabilities.
- Healthcare:Hospital sterilization departments and medical device manufacturing with zero-tolerance microbial standards.
- Household:Consumer disinfectant and preservation applications with price-sensitive mass-market dynamics.
Industrial end users absorb the bulk of volume; food processing is climbing the fastest as cold-chain sanitization protocols expand.
Form:
Delivery format selection dictates supply chain configuration, with liquid systems requiring specialized handling infrastructure and powder formats enabling broader distribution reach.
- Liquid:Ready-to-dose formulations dominating industrial water treatment and food processing applications. Polymer-stabilized liquid delivery systems command price premiums in recirculating cooling towers by extending biocide release duration.
- Powder:Dry concentrates requiring on-site reconstitution, prevalent in agricultural and remote industrial settings.
- Granular:Controlled-release formats for soil and water treatment applications.
- Emulsifiable:Concentrates designed for dispersion in hydrophobic matrices such as coatings and wood preservatives.
Liquid formulations absorb the bulk of production capacity; emulsifiable systems are gaining traction fastest in coatings reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States where industrial water reuse mandates are most stringent. Water treatment utilities across these markets are expanding procurement of halogen-free biocidal systems. The EU BPR and EPA registration pathways are tightening efficacy documentation requirements for active substance suppliers.
United States
Texas and Alberta oilfield operations are advancing technical service unbundling, separating chemical procurement from dosing system contracts. EPA Office of Pesticide Programs registration timelines extend commercialization cycles to 36-48 months, elevating working capital burdens for active ingredient developers. Meat processing facilities in the Midwest are adopting electrochemical peracetic acid generators for cold-chain sanitization.
Germany
Industrial water reuse protocols mandate biocide residuals below detectable thresholds, accelerating biodegradable active adoption. EU Biocidal Products Regulation efficacy documentation requirements are filtering out commoditized producers and concentrating procurement among technically qualified formulators. The Rhine-Ruhr industrial corridor hosts cooling water treatment facilities specifying polymer-stabilized delivery systems.
China
Ministry of Ecology and Environment enforces discharge standard GB 31570-2015, limiting residual biocide concentrations in industrial effluent. Yangtze River Delta manufacturing clusters are redirecting formulation choices toward biodegradable actives to meet effluent compliance. Photovoltaic panel cleaning protocols in arid western provinces are creating new algaecide demand vectors.
India
State Pollution Control Boards are tightening COD and microbial discharge limits, redirecting textile and pharmaceutical processors toward certified biodegradable actives. Central Pollution Control Board enforcement is expanding from metropolitan centers to secondary industrial cities. Gujarat and Maharashtra chemical manufacturing zones are upgrading wastewater treatment infrastructure to meet biocide residual standards.
United Kingdom
Water treatment utilities are recalibrating procurement criteria to favor halogen-free biocidal systems over legacy chlorine chemistries. Health and Safety Executive alignment with EU BPR post-Brexit maintains stringent efficacy documentation requirements for active substance suppliers. London and Southeast England municipal water systems are piloting peracetic acid formulations in cold-temperature applications.
Specialty Biocides Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated active-ingredient producers commanding premium positioning in bactericide categories while formulation houses capture value in application-specific delivery systems. Market structure tilts toward consolidation among registrants capable of navigating dual-track EPA and EU BPR approval pathways, while spot-market suppliers compete on price in unregulated segments. Three archetypes dominate: captive chemical manufacturers with backward integration into active ingredients, independent formulators bundling technical service with certification, and regional distributors leveraging logistics scale. Competitive moves center on polymer-stabilized delivery system development and geographic expansion into India and Southeast Asia.
Among Swiss-domiciled integrated producers, Lonza Group Ltd. and Clariant International Ltd. occupy positions emphasizing active-ingredient manufacturing scale. German chemical conglomerates Lanxess AG and BASF SE exemplify diversified portfolio players with biocide segments nested within broader material science operations. DuPont de Nemours Inc. anchors the U.S.-based tier, representing specialty chemical houses with differentiated delivery system capabilities. These named entities collectively illustrate how registration capacity and technical service bundling separate premium suppliers from commodity competitors.
| Leading Market Players |
|---|
| Buckman Laboratories International Inc. |
| DuPont de Nemours Inc. |
| Albemarle Corp. |
| Lonza Group Ltd. |
| Lanxess AG |
| Baker Hughes Co. |
| Clariant International Ltd. |
| Nouryon |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Electrochemical peracetic acid generation is compressing traditional chemical distributor margins while redistributing value toward on-site production equipment suppliers, simultaneously fragmenting procurement authority across food processing and healthcare end users. This distributed manufacturing transition concentrates pricing power with skid-mounted system OEMs while eroding bulk chemical contract premiums.
Pricing Analysis
Volume concentrates in commodity quaternary ammonium compounds while margins pool in polymer-stabilized delivery systems and electrochemical generation equipment. Price differentiation rests on EPA-EU BPR dual registration status and technical service bundling rather than raw active concentration. Cost compression in standard bactericide formulations is intensifying as Chinese manufacturers expand export capacity. Municipal water utilities exhibit the sharpest price sensitivity due to public procurement frameworks, whereas hospital sterilization departments prioritize performance certification over unit economics.
Supply Chain Analysis
Specialized chemical engineering talent shortages in Germany and the United States are constraining expansion of integrated active-ingredient manufacturing. Supply concentrates in China for isothiazolinone precursors, Switzerland for quaternary ammonium compound synthesis, and the United States for peracetic acid formulation. Feedstock exposure to acetic acid and petrochemical derivatives creates margin volatility that complicates long-term contracting. Distribution runs through certified chemical distributors with EPA-registered warehousing capabilities, though direct procurement from formulators is advancing in Texas and Alberta oilfield markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty biocides sector is consolidating around registrants capable of navigating dual-track EPA and EU BPR approval pathways, with efficacy documentation burdens filtering out commoditized suppliers lacking technical service infrastructure.
For Market Incumbents: Extend polymer-stabilized delivery system portfolios to capture 15-20% price premiums in recirculating cooling tower applications. Deepen backward integration into active-ingredient manufacturing to defend margin position against Chinese import competition. Prioritize ISO 9001 certification bundling with on-site application support to maintain procurement preference in multinational frameworks. For New Entrants and Emerging Players: Direct-to-facility digital procurement platforms offer the lowest-friction entry vector for spot-market biocide supply in unregulated segments. Target photovoltaic panel cleaning algaecide specifications in arid western China and India as the most penetrable white-space application. Lead with biodegradable active positioning to align with tightening effluent discharge mandates across textile and pharmaceutical processing clusters. For Investors and Strategic Acquirers: Re-rating potential sits with integrated formulators possessing dual EPA-EU BPR registration portfolios given sustained regulatory elevation of market access barriers. Five-to-ten year viability favors suppliers combining captive active-ingredient production with technical service infrastructure over pure distribution plays. Monitor India State Pollution Control Board enforcement expansion as the signal indicating acceleration of certified biodegradable active demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual EPA-EU BPR Registration Investment | Establishes defensible market access moats that commodity suppliers cannot replicate. |
| Electrochemical Generation Equipment Partnership | Captures value migration from bulk chemical supply toward distributed manufacturing infrastructure. |
| Polymer-Stabilized Delivery System Development | Commands price premiums in cooling water applications through extended release performance. |
| India Technical Service Infrastructure Buildout | Positions for State Pollution Control Board enforcement tightening across textile and pharmaceutical clusters. |
| Biodegradable Active Portfolio Expansion | Aligns with GB 31570-2015 and EU discharge limit trajectories redirecting formulation choices. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with water treatment procurement managers, food processing plant engineers, EPA registration consultants, and specialty chemical distribution executives. SEC 10-K disclosures, EU BPR substance dossiers, and Chinese customs export statistics provided volume and value triangulation against bottom-up plant capacity assessments.
Granularity extended to active chemistry, application matrix, and end-use industry dimensions across the projection horizon, with separate modeling for liquid, powder, and emulsifiable delivery formats. CAGRs derived from regression analysis of historical procurement patterns against regulatory enforcement timelines and industrial water reuse mandate adoption curves. Feedstock cost indices and registration approval duration distributions informed margin and competitive structure projections.
The model holds under sustained EPA and EU BPR efficacy documentation requirements; deviation in regulatory harmonization timelines or feedstock price volatility spikes would shift competitive positioning toward integrated manufacturers. Material deviation in enforcement intensity across India State Pollution Control Boards or Chinese Ministry of Ecology and Environment discharge standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Natural Phytosphingosine Market