
 Sandwich Preparation Refrigerators Market | 2026-2036
Sandwich Preparation Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Preparation Refrigerators Market Analytics
Foodservice equipment distribution is reshaping as dealer networks consolidate and e-procurement platforms capture mid-market volume. True Manufacturing leverages its domestic manufacturing footprint to sustain short-lead-time commitments to national chain accounts. Hoshizaki anchors the premium tier through specialized forced-air engineering for high-temperature kitchens. Turbo Air competes aggressively on price-positioned units while extending its warranty terms to offset brand recognition gaps against legacy players.
Sandwich preparation refrigerators are insulated commercial cabinets designed to maintain food-safe temperatures between 33°F and 41°F while providing integrated cutting surfaces and ingredient pan storage for high-volume cold food assembly. Units typically employ polyurethane foam insulation ranging from two to three inches in thickness, with stainless steel interiors specified for NSF sanitation compliance. Bottom-mount configurations lead the product type mix due to compressor accessibility and reduced kitchen floor-space requirements, while forced-air cooling technology captures growing preference among operators managing high ambient-temperature environments. The undercounter size segment dominates unit volume in urban restaurants where kitchen footprints compress, though full-size units concentrate margin pools through higher average selling prices and extended feature sets.
The US Department of Energy enforces minimum efficiency standards under 10 CFR Part 431, directly influencing compressor selection and insulation specifications for domestic manufacturers. NSF International certification governs food-zone materials and cleanability, creating a non-negotiable threshold for market access across commercial channels. The EPA's SNAP program phases hydrofluorocarbon refrigerants, compelling OEMs to qualify alternative cooling circuits. Stakeholders must monitor refrigerant transition timelines and efficiency rulemakings to align R&D pipelines with compliance deadlines while capturing early-mover positioning on natural-refrigerant platforms.
Market Dynamics
The US Department of Energy's 10 CFR Part 431 efficiency standards are compressing product development cycles and forcing compressor redesigns across domestic manufacturing footprints, while quick-service restaurant expansion sustains replacement demand.
Growth Catalysts
- Forced-air cooling architecture:High-temperature kitchen operators in the quick-service segment specify forced-air systems to maintain 33°F-41°F holding temperatures under thermal stress loads.
- Deli-format chain expansion:Independent sandwich shops and regional deli chains in the United States sustain equipment purchase volumes through new-location buildouts and cold-prep station retrofits.
- NSF International certification:Food-zone material standards create mandatory compliance thresholds that lock out uncertified imports and reinforce specification loyalty to qualified OEMs.
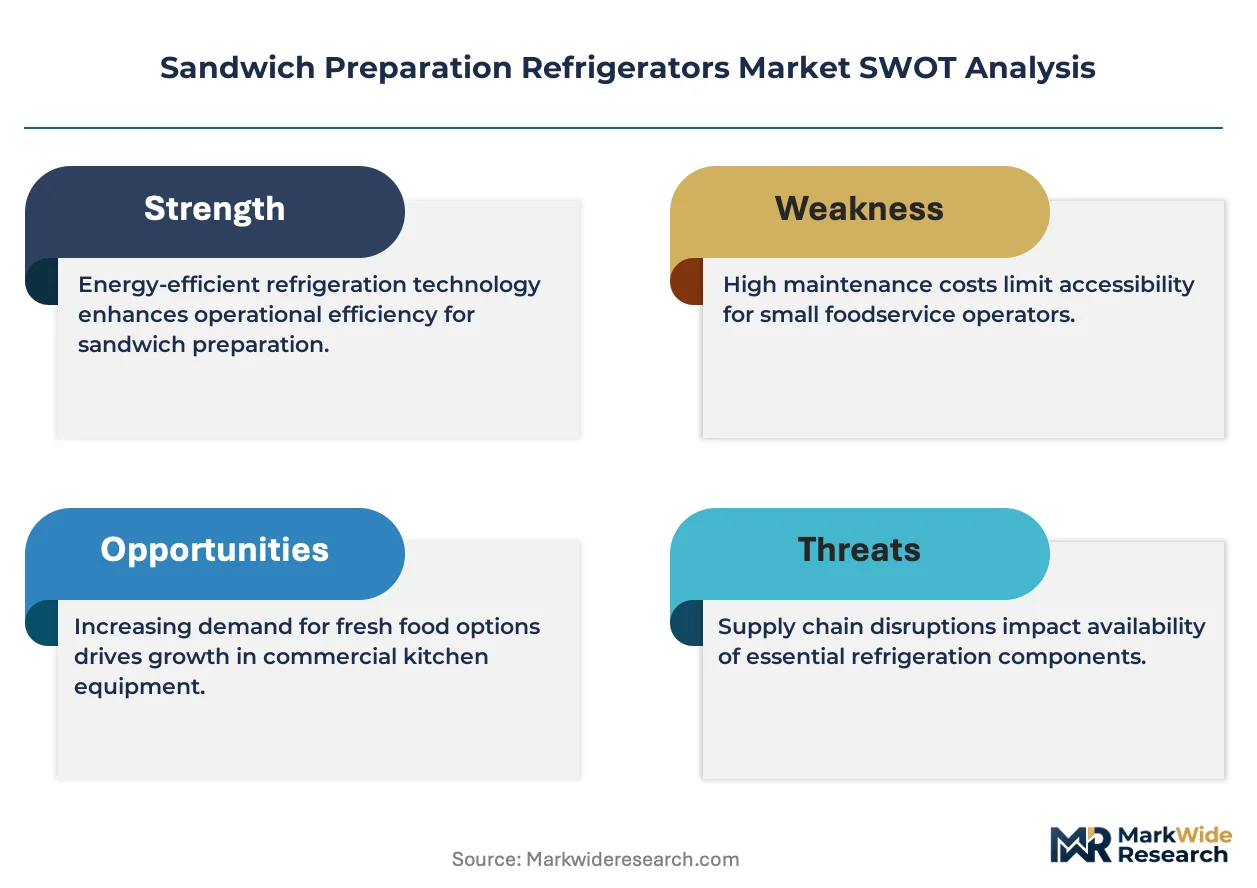
Market Restraints
- Refrigerant transition costs:The EPA's SNAP program phaseout of hydrofluorocarbon refrigerants forces OEMs to qualify alternative cooling circuits, compressing R&D budgets and extending qualification timelines.
- Steel and copper volatility:Stainless steel exterior panels and copper refrigeration tubing expose manufacturers to commodity price swings that erode margin stability on fixed-price chain contracts.
- Polyurethane foam supply:Two-to-three-inch insulation specifications depend on petrochemical feedstock availability, with domestic foam suppliers concentrating in the Gulf Coast region.
Strategic Opportunities
- E-procurement platform capture:Mid-market restaurant operators are consolidating purchasing through digital channels, creating direct-to-operator routes that bypass traditional dealer networks.
- Natural-refrigerant platforms:Early qualification of hydrocarbon or CO2 cooling circuits positions OEMs ahead of EPA SNAP compliance deadlines and future-proofs product portfolios.
- Urban kitchen compression:Undercounter configurations dominate unit volume in dense metropolitan foodservice markets where floor space commands premium lease rates.
Industry Challenges
- Refrigeration technician scarcity:Forced-air and natural-refrigerant system maintenance requires specialized field service capabilities that outstrip current training pipeline output.
- NSF certification timeline:Food-zone material validation and cleanability testing extends product launch schedules, delaying revenue recognition on redesigned units.
- Dealer consolidation friction:Independent equipment distributors merging into larger networks disrupts established territory relationships and complicates warranty service handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Preparation Refrigerators Market |
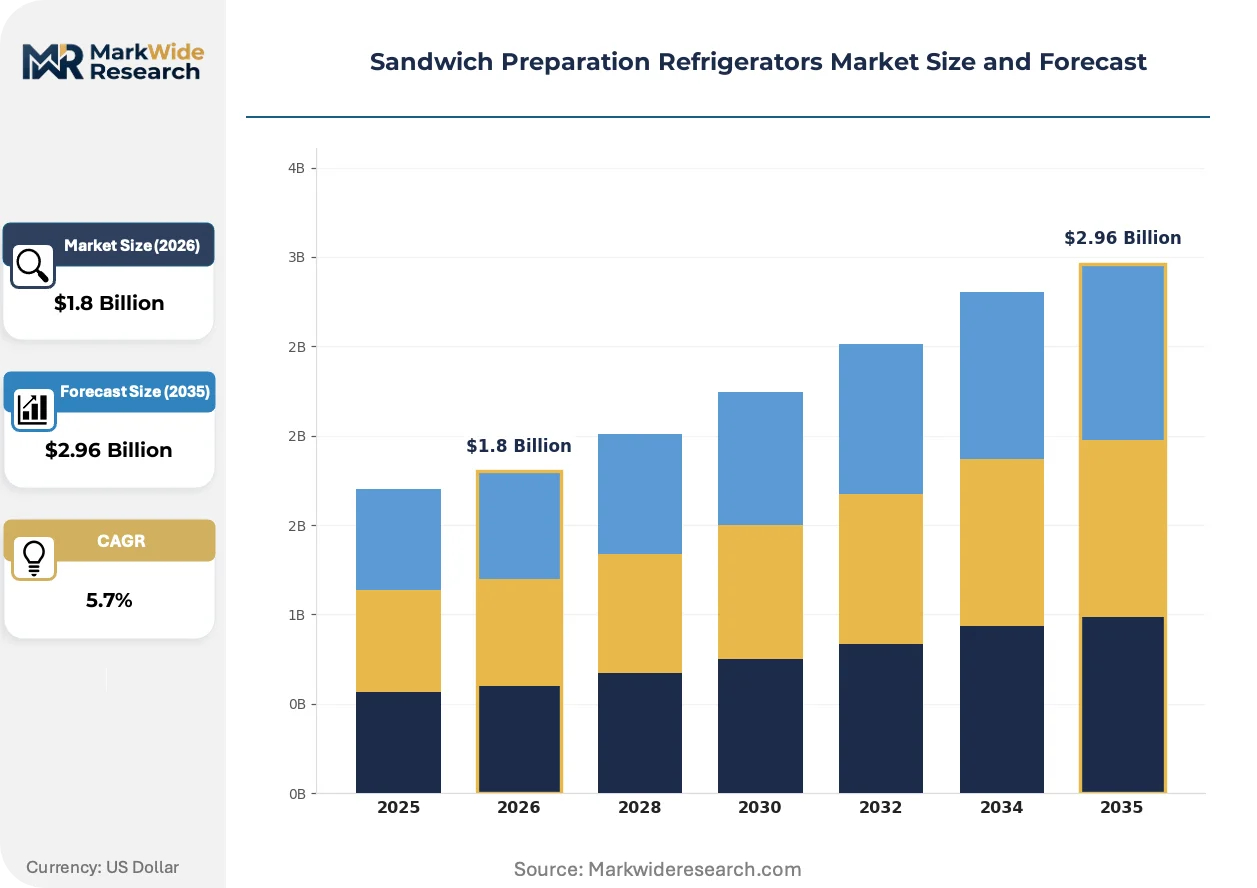
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottom-Mount, Top-Mount, Salad Bar, Open-Front End User: Restaurants, Cafés, Delis, Food Trucks Size: Countertop, Undercounter, Full-Size, Half-Size Cooling Technology: Static, Forced Air, Eco-Friendly, Dual Zone |
| Companies Covered | True Manufacturing, Hoshizaki, Turbo Air, Foster Refrigerator, Beverage-Air, SA Dukers, Avantco, TechniCool, Electrolux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Preparation Refrigerators Market Evolving Landscape
Refrigeration engineering is pivoting toward thermal management virtualization and compliance-driven material substitution, while procurement channels fragment between consolidated dealers and direct digital platforms.
Digital twin simulation is virtualizing compressor selection and airflow modeling for sandwich prep units before physical prototyping. OEM engineering teams deploy thermal modeling software to optimize forced-air distribution patterns across high-temperature kitchen scenarios. This virtualization compresses development cycles and reduces physical test-chamber hours for new cabinet configurations.
The EPA's SNAP program is accelerating hydrofluorocarbon phaseout timelines, compelling manufacturers to redesign cooling circuits around hydrocarbon or CO2 alternatives. Domestic OEMs face compressed qualification windows to maintain 10 CFR Part 431 efficiency compliance while transitioning refrigerant platforms. Full-size unit categories absorb disproportionate engineering attention due to higher average selling prices and extended feature sets.
Chain operators now unbundle equipment procurement from installation and after-sales service, treating sandwich prep refrigerators as capital goods rather than bundled solutions. National quick-service accounts negotiate direct pricing with manufacturers while sourcing installation through regional contractors. This disintermediation concentrates in the United States, where large deli-format chains possess sufficient purchasing volume to justify direct OEM relationships.
Sandwich Preparation Refrigerators Market Segmentation
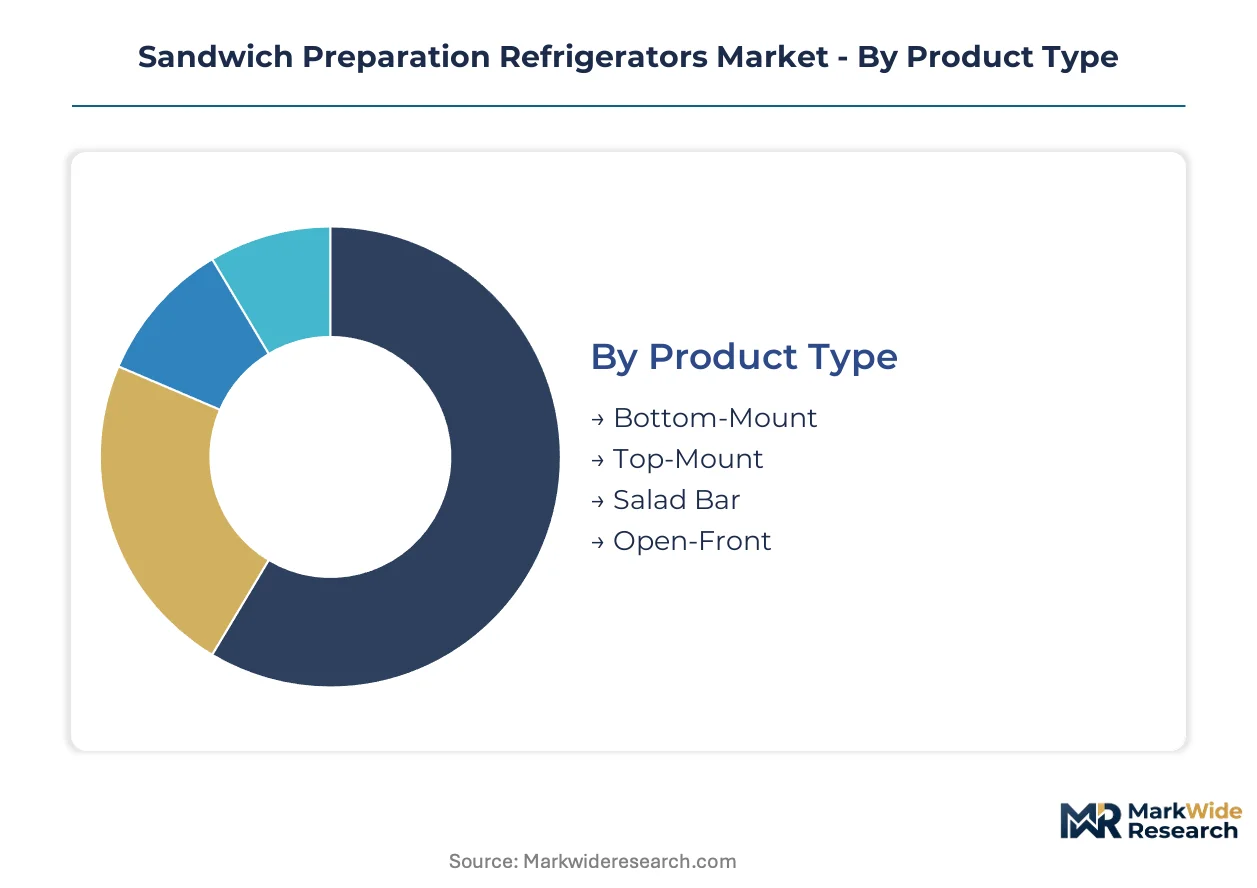
Sandwich preparation refrigerator purchasing decisions hinge on kitchen layout constraints, menu complexity, and thermal load profiles. Operators match cabinet configurations to available floor space, ambient temperature conditions, and volume throughput requirements. The four segmentation dimensions capture equipment specification trade-offs across installation geometry, end-use operational intensity, dimensional footprint, and refrigeration engineering approach.
Product Type:
Mounting configuration determines compressor accessibility, floor-space efficiency, and service lifecycle costs for operators managing high-volume cold-prep stations.
- Bottom-Mount:Compressor placement below the refrigerated cabinet elevates the work surface to ergonomic heights while reducing kitchen floor-space requirements. Quick-service restaurants in dense urban markets specify bottom-mount units to maximize linear prep footage within compressed kitchen footprints.
- Top-Mount:Gravity-assisted refrigeration circuits position compressors above the food zone, capturing rising warm air and reducing defrost frequency. Deli-format chains with lower ceiling clearances rotate toward top-mount configurations to preserve vertical storage capacity.
- Salad Bar:Open-refrigerated wells with integrated sneeze guards and pan rails support self-service cold food assembly. Cafeteria and buffet operators deploy salad bar units for front-of-house ingredient presentation.
- Open-Front:Curved glass or air-curtain designs enable customer-facing product visibility without door barriers. Grab-and-go retail formats specify open-front units for impulse-purchase sandwich displays.
Bottom-mount holds installed capacity. Salad bar is rotating up the share rankings.
End User:
Operational intensity and menu breadth shape specification requirements across foodservice establishment types, from high-throughput chain kitchens to mobile limited-menu operations.
- Restaurants:Full-service and quick-service operators drive specification volume through cold-prep station buildouts and replacement cycles. National sandwich chains negotiate direct OEM relationships for standardized unit deployments across franchise networks.
- Cafés:Limited-menu coffee and light-meal operators prioritize compact undercounter configurations with reduced pan capacity. Urban café density in metropolitan commercial districts sustains countertop and half-size unit demand.
- Delis:High-volume meat and cheese slicing operations require extended cutting surfaces and deep pan rails for ingredient variety. Independent delicatessens and regional chains specify full-size units with forced-air cooling to maintain food-safe temperatures during peak lunch rushes.
- Food Trucks:Mobile operators confront extreme ambient temperature swings and power supply constraints. Compact undercounter units with robust compressor duty cycles dominate food truck specifications.
Restaurants anchor procurement volume. Food trucks are expanding most quickly as mobile foodservice licensing proliferates.
Size:
Dimensional footprint directly correlates with lease cost structures and kitchen workflow optimization priorities across metropolitan and suburban foodservice markets.
- Countertop:Surface-mounted units with reduced pan capacity serve front-of-house assembly stations and auxiliary prep areas. Coffee shops and small cafés specify countertop models for beverage companion food preparation.
- Undercounter:Low-profile cabinets fit beneath standard work surfaces, preserving floor space in high-rent urban kitchens. The undercounter segment concentrates unit volume in dense metropolitan markets where square footage commands premium lease rates.
- Full-Size:Extended-width cabinets with 8-16 pan capacity support high-volume sandwich assembly lines. Central commissaries and high-throughput delis specify full-size units for batch-prep operations.
- Half-Size:Intermediate footprint balancing pan capacity against spatial constraints. Secondary prep stations and catering operations deploy half-size units for auxiliary cold-holding requirements.
Undercounter dominates unit shipments. Full-size commands margin concentration through higher average selling prices.
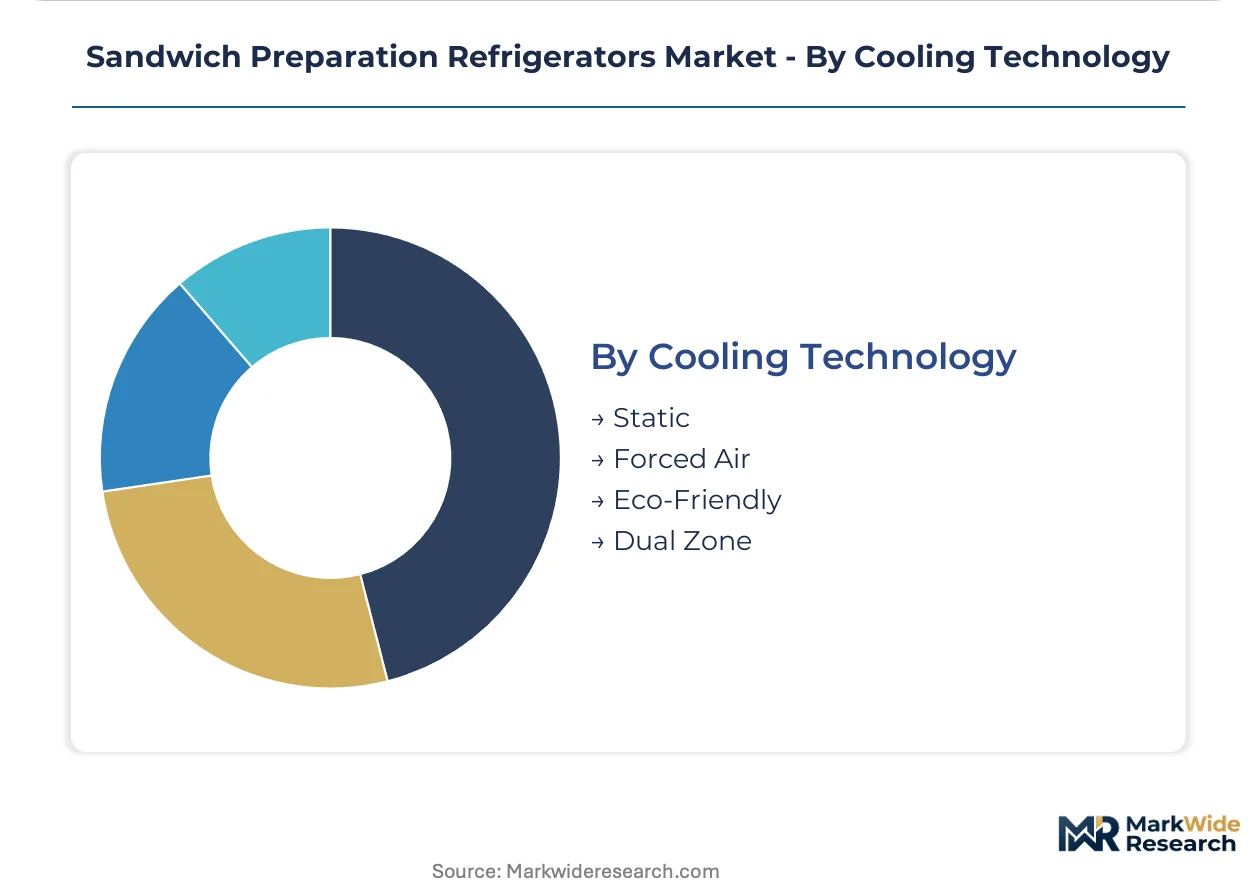
Cooling Technology:
Refrigeration engineering selection responds to ambient kitchen temperature profiles, energy efficiency mandates, and refrigerant transition compliance requirements.
- Static:Natural convection cooling with minimal moving parts reduces acquisition cost and maintenance complexity. Low-volume operators in moderate-temperature environments specify static cooling for capital expenditure minimization.
- Forced Air:Fan-driven circulation maintains uniform temperature distribution across high-load kitchen scenarios. Quick-service operators in high-temperature grill-line proximity specify forced-air systems to sustain 33°F-41°F holding ranges under thermal stress.
- Eco-Friendly:Hydrocarbon or CO2 refrigerant circuits align with EPA SNAP program phaseout timelines. OEMs qualifying eco-friendly platforms capture early-mover positioning ahead of compliance deadlines.
- Dual Zone:Independent temperature controls for separate food zones enable simultaneous meat and vegetable storage at distinct holding temperatures. High-menu-complexity delis specify dual-zone units for cross-contamination risk reduction.
Static cooling retains legacy installed base. Forced air is climbing the fastest as kitchen thermal loads intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy efficiency mandates and quick-service restaurant expansion are redistributing sandwich preparation refrigerator demand across key foodservice markets. The US Department of Energy's 10 CFR Part 431 standards and equivalent efficiency frameworks in other jurisdictions are compressing product qualification timelines while operators accelerate cold-prep station deployments.
United States
Deli-format chain expansion and independent sandwich shop replacement cycles sustain equipment procurement volume. The US Department of Energy enforces 10 CFR Part 431 efficiency standards that directly influence domestic manufacturer compressor selection and insulation specifications. Metropolitan clusters in the Northeast Corridor and California sustain undercounter unit demand where urban kitchen footprints compress.
Germany
Commercial kitchen efficiency retrofits and foodservice establishment energy audits drive specification upgrades. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, compelling OEMs to qualify hydrocarbon or CO2 cooling circuits for German market access. Industrial concentration in Bavaria and North Rhine-Westphalia anchors distribution logistics for central European foodservice equipment flows.
Japan
Compact urban restaurant formats and convenience store foodservice expansion concentrate demand for space-efficient configurations. METI energy conservation standards for commercial refrigeration equipment mandate minimum performance coefficients that shape product development priorities. The Kanto region around Tokyo sustains premium-tier specification volume through high-density foodservice clustering.
Australia
Food truck licensing proliferation and mobile foodservice regulation liberalization accelerate compact unit adoption. The country's national energy regulator maintains commercial refrigeration efficiency requirements that align with international standards while permitting regional adaptation. Sydney and Melbourne metropolitan foodservice corridors concentrate undercounter and countertop configuration demand.
United Kingdom
Independent café and deli sector recovery post-regulatory adjustment sustains mid-market equipment purchases. The UK's commercial refrigeration efficiency framework and building energy regulations constrain product specifications for domestic market entry. London and Southeast England foodservice density drives replacement cycle velocity for legacy static-cooling units.
Sandwich Preparation Refrigerators Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: domestic manufacturers with short-lead-time capabilities, premium-tier forced-air engineering specialists, and price-positioned volume competitors extending warranty terms to offset brand gaps. Tiered competitive positioning separates premium specification loyalty from mid-market procurement consolidation. Dominant competitive moves include dealer network consolidation to capture distribution efficiency and e-procurement platform partnerships to bypass traditional sales channels.
Within the established manufacturer tier, True Manufacturing, Hoshizaki, and Turbo Air occupy distinct positioning vectors. True Manufacturing exemplifies the domestic fabrication archetype with manufacturing footprint advantages for national chain account responsiveness. Hoshizaki anchors the premium engineering segment through specialized forced-air system credentials. Turbo Air represents the aggressive price-positioning archetype while extending warranty coverage to compete against legacy brand recognition. These three manufacturers collectively illustrate the competitive tension between lead-time performance, technical specification leadership, and cost-driven market penetration strategies.
| Leading Market Players |
|---|
| True Manufacturing |
| Hoshizaki |
| Turbo Air |
| Foster Refrigerator |
| Beverage-Air |
| SA Dukers |
| Avantco |
| TechniCool |
| Electrolux |
| Others |
Value Network & Pricing Analysis
Gulf Coast petrochemical clusters anchor polyurethane foam supply for sandwich preparation refrigerator insulation, concentrating feedstock pricing power among domestic foam suppliers and transmitting cost volatility downstream to OEMs managing fixed-price national chain contracts.
Pricing Analysis
Certification level (NSF/UL/DOE-grade) creates the primary spread across sandwich preparation refrigerator tiers, with forced-air cooling systems commanding premiums over static-cooling units due to elevated engineering complexity and thermal stress performance. Three-tier pricing structure across premium, standard, and economy levels stratifies by compressor specification, insulation thickness, and warranty duration. Pricing pressure stems from steel and copper commodity volatility eroding margin stability on long-term chain contracts. Mid-market independent sandwich shops exhibit highest price sensitivity, while national quick-service accounts trade volume for direct-OEM pricing leverage.
Supply Chain Analysis
Export-control regimes on compressor technology and refrigeration electronics limit component flows from certain jurisdictions, compelling domestic OEMs to qualify alternative sourcing channels for control systems and fan motors. Manufacturing concentrates in the United States, China, and Mexico, with stainless steel exterior panels drawing from North American steel mills and copper tubing resting on Chilean and Peruvian mining output. Single-source vulnerability concentrates in Gulf Coast foam suppliers exposed to hurricane disruption. Distribution runs through consolidating dealer networks and emerging e-procurement platforms serving mid-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as quick-service restaurant expansion and refrigerant transition timelines create specification niches for differentiated cooling architectures and compliance-ready product portfolios.
For Market Incumbents: Build certification moats through accelerated NSF validation pipelines and natural-refrigerant qualification ahead of EPA SNAP enforcement windows. Defensive moves center on captive polyurethane foam supply agreements to buffer Gulf Coast concentration risk, and forced-air engineering talent retention as technician scarcity intensifies. Threats include price-positioned competitors extending warranty terms to offset brand gaps. For New Entrants and Emerging Players: Establish a beachhead in urban undercounter configurations where kitchen compression drives specification volume and lease-cost sensitivity overrides brand loyalty. White-space targets include food truck mobile operators confronting extreme ambient temperature swings, and eco-friendly cooling platforms for operators seeking early SNAP compliance. Go-to-market angle: direct e-procurement platform partnerships bypassing consolidated dealer networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with national chain direct relationships and aftermarket service attach rates. Long-term viability favors manufacturers with hydrocarbon or CO2 cooling circuit qualification progress and domestic fabrication footprints enabling short-lead-time commitments. Acquisition target archetype: forced-air engineering specialists with METI or EU F-Gas regulatory positioning. Signal to watch: refrigerant transition timeline acceleration compressing qualification windows for laggard OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Natural-Refrigerant Platform Qualification | Positions OEMs ahead of EPA SNAP phaseout deadlines and future-proofs portfolios against compliance risk. |
| Dealer Network Consolidation | Captures distribution efficiency and territory control as independent distributors merge into larger networks. |
| E-Procurement Platform Partnership | Creates direct-to-operator routes bypassing traditional sales channels for mid-market volume capture. |
| Forced-Air Engineering Investment | Addresses high-temperature kitchen operator demand for thermal stress resilience in quick-service environments. |
| Domestic Manufacturing Footprint Expansion | Sustains short-lead-time commitments to national chain accounts requiring rapid deployment capabilities. |
Research Methodology
The analysis maps sandwich preparation refrigerator sub-sectors by product type, cooling technology, end-user vertical, and size configuration, each validated through equipment procurement directors, foodservice facility planners, and refrigeration service technicians. Primary interviews with OEM product managers and dealer network principals combined with secondary validation from DOE efficiency standard filings, NSF certification databases, and EPA SNAP program rulemakings. Bottom-up unit shipment modeling and top-down value triangulation anchored market size estimation.
Assumptions held fixed include DOE 10 CFR Part 431 efficiency standards and EPA SNAP refrigerant phaseout timelines, while variables spanned commodity price trajectories for steel and copper, and quick-service restaurant expansion velocity across metropolitan clusters. The forecast framework modeled four segmentation dimensions—product type, end user, size, and cooling technology—across the analysis window. CAGRs derived from trend extrapolation of replacement cycle velocity and new-location buildout rates, with thermal load intensity and kitchen footprint compression as industry-specific demand drivers.
Stress conditions across steel price volatility, foam supply disruption, and refrigerant transition acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory compliance timelines and chain expansion trajectories. Material shifts in EPA SNAP enforcement velocity or DOE efficiency standard revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Global Non Thermal Processing Market